
 Paper Cone Cup Market | 2026-2036
Paper Cone Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Cone Cup Market Analytics
Water-based barrier coating technology is fragmenting the traditional polyethylene-lined cup supply chain into compostable and recyclable sub-systems. Huhtamaki Oyj leverages its European R&D footprint to scale bio-barrier production. Stora Enso anchors Nordic fiber sourcing with integrated pulp-to-cup manufacturing. Dart Container Corporation competes through high-volume automated forming lines serving North American quick-service chains.
A paper cone cup is a tapered, single-wall fiber vessel formed from rolled paperboard, typically holding 4–12 ounces of liquid, with a sealed bottom and open top designed for direct consumption without a separate lid. Hot beverage cups command the largest volume share due to coffee and tea service frequency, while biodegradable paper grades are outpacing coated alternatives as municipal composting expands. Wholesale distributors occupy the dominant channel position, though direct sales to fast food chains are extending as buyers consolidate procurement under national contracts.
The FDA governs food-contact substance compliance for US-manufactured cone cups, while the EU Green Deal and REACH restrict perfluorinated chemicals in barrier coatings. Stakeholders must monitor evolving state-level extended producer responsibility laws and decide between compostable certification investments or recyclable stream optimization before regulatory deadlines harden.
Market Dynamics
The EU Single-Use Plastics Directive is forcing a material transition across foodservice packaging, splitting the supply chain between compostable fiber and recyclable polyethylene-lined systems. Quick-service restaurants now face procurement deadlines that favor bio-barrier coatings over conventional plastic linings.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-out of plastic foodservice items creates immediate substitution demand for fiber-based cone cups across German, French, and Italian foodservice chains.
- Municipal composting infrastructure:German cities with industrial composting facilities absorb biodegradable paper grades at scale, validating premium pricing for certified compostable products.
- Quick-service restaurant consolidation:National procurement contracts at major chains standardize sustainable packaging specifications, accelerating volume shifts toward fiber alternatives.
Market Restraints
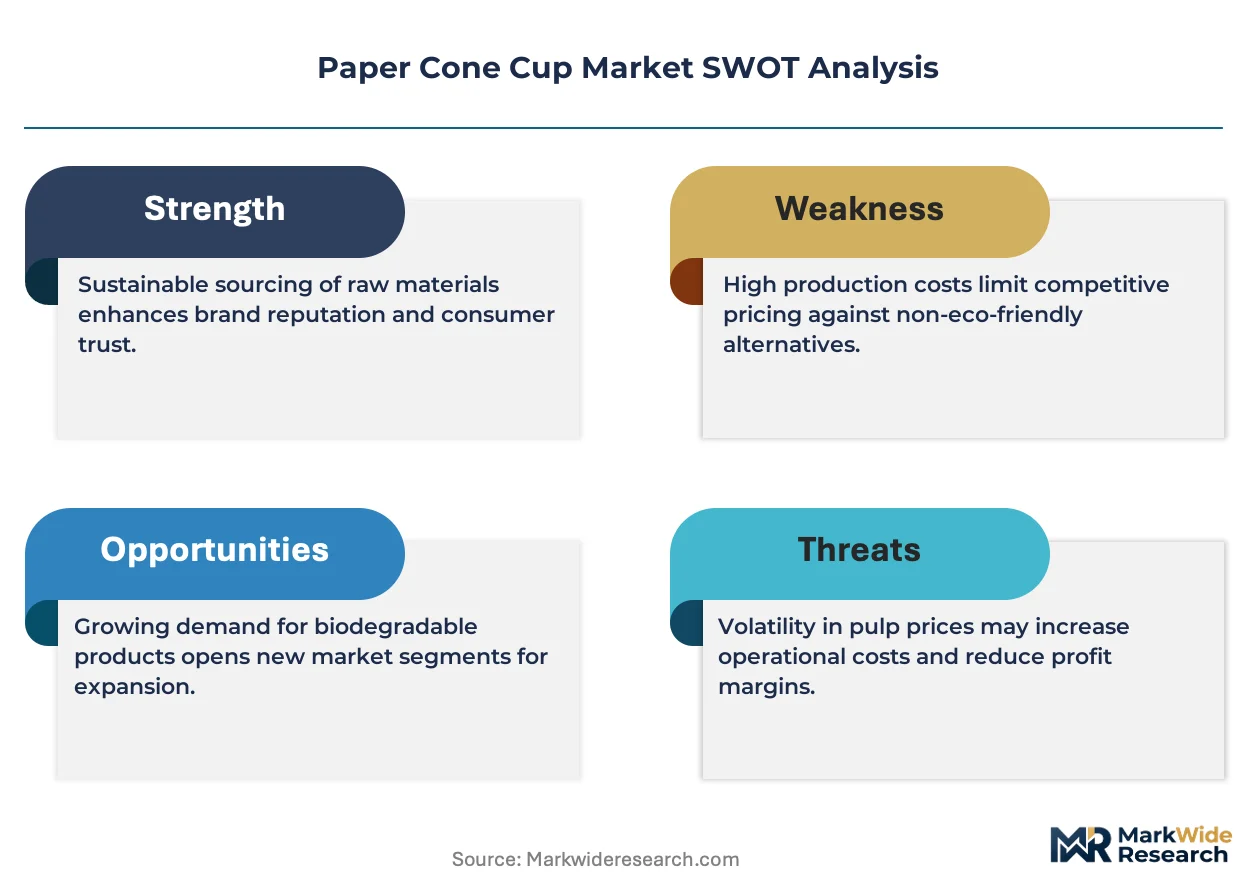
- Pulp price volatility:Nordic softwood pulp costs swing with energy and logistics inputs, compressing margins for integrated and non-integrated cup manufacturers alike.
- Barrier coating performance gap:Water-based bio-barriers currently exhibit shorter shelf stability and lower heat tolerance than polyethylene, limiting hot-fill applications.
- Recyclability confusion:Inconsistent municipal sorting infrastructure creates contamination risk, deterring some buyers from fiber cups despite compostable certification.
Strategic Opportunities
- Extended producer responsibility expansion:France and Italy are implementing EPR frameworks that internalize end-of-life costs, rewarding domestic producers with compliant compostable supply chains.
- Cold beverage cone formats:Untapped demand exists for smaller-volume tapered cups in juice and soft-serve applications, where barrier requirements are less stringent.
- Direct-to-chain distribution:Bypassing wholesale distributors through dedicated logistics contracts captures margin and locks in specification control with multinational buyers.
Industry Challenges
- Compostable certification timeline:TUV Austria and BPI approval processes extend 12-18 months, delaying product launches and locking out smaller manufacturers lacking dedicated compliance staff.
- Coating equipment retrofit costs:Converting polyethylene extrusion lines to water-based barrier application requires capital outlays that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Cone Cup Market |
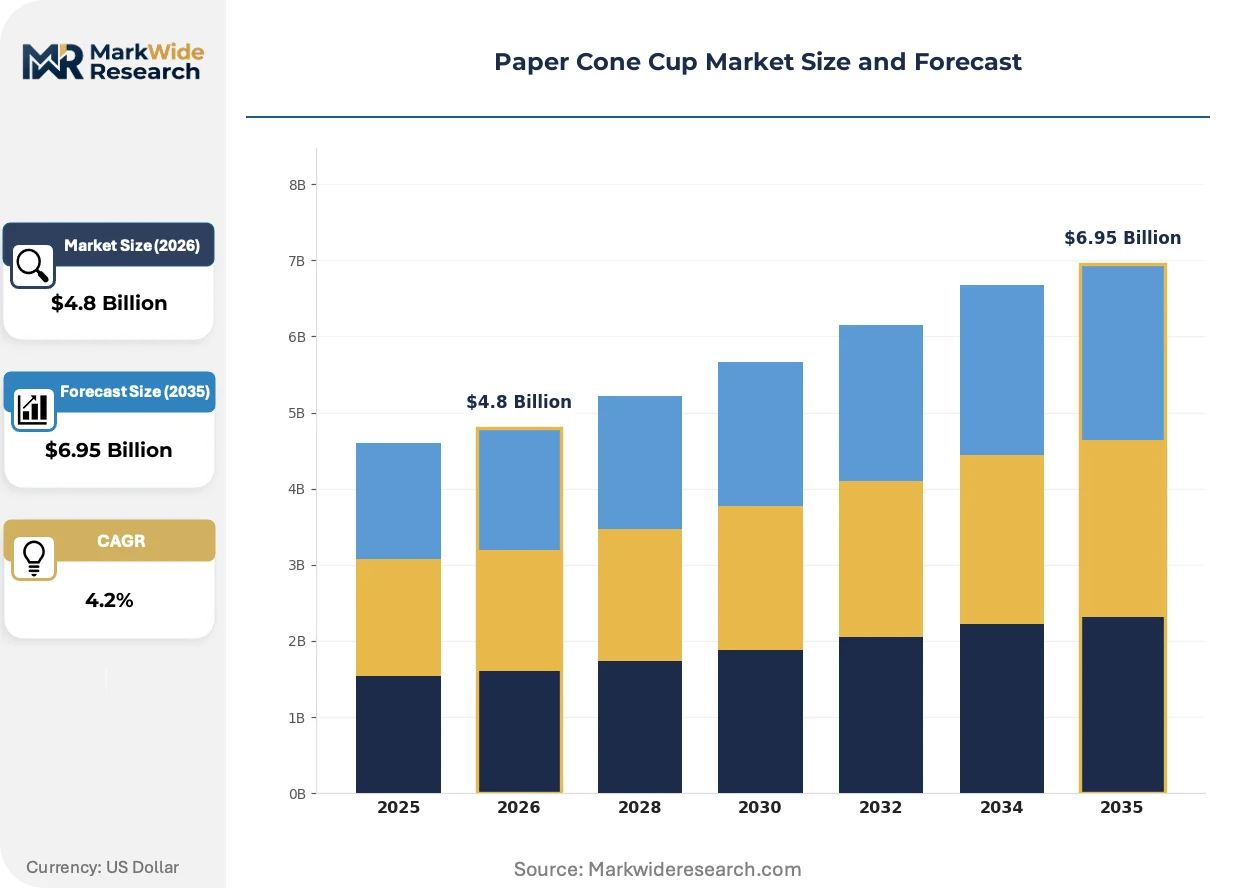
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Beverage Cups, Cold Beverage Cups, Combo Packs, Custom Design Cups Material: 100% Recycled Material, Biodegradable Paper, Coated Paper, Non-Coated Paper End User: Restaurants, Cafés, Fast Food Chains, Events Distribution Channel: Online Retail, Wholesale Distributors, Supermarkets, Direct Sales |
| Companies Covered | International Paper Company, Pactiv Evergreen Inc., Dart Container Corporation, Seda International Packaging Group, Stora Enso, Huhtamaki Oyj, Graphic Packaging International, Tekni-Plex, Inc., Georgia-Pacific Consumer Products LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Cone Cup Market Evolving Landscape
Barrier coating chemistry is hybridizing functional properties from multiple material classes, enabling paper cups to match plastic performance without sacrificing compostability. This technical convergence is reshaping R&D investment patterns and supplier qualification criteria.
Water-based bio-barrier formulations is hybridizing hydrophobic and grease-resistant properties previously achievable only with fluorinated or plastic coatings. Quick-service chains in Germany and the Netherlands are piloting these cups for hot coffee service. The technology is compressing the performance gap between compostable fiber and conventional polyethylene-lined products.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorochemical barriers from EU food-contact applications. Manufacturers must reformulate or exit the European market entirely. Hot beverage cups with legacy PFAS coatings face the steepest compliance burden, accelerating investment in silicone and polysaccharide alternatives.
Buyer consolidation under national procurement contracts is displacing fragmented regional purchasing across quick-service and convenience store channels. Wholesale distributors lose volume share as chains negotiate direct supply agreements with integrated fiber converters. This pattern is most visible in the United States, where three major burger chains now control specification standards for their entire franchise networks.
Paper Cone Cup Market Segmentation
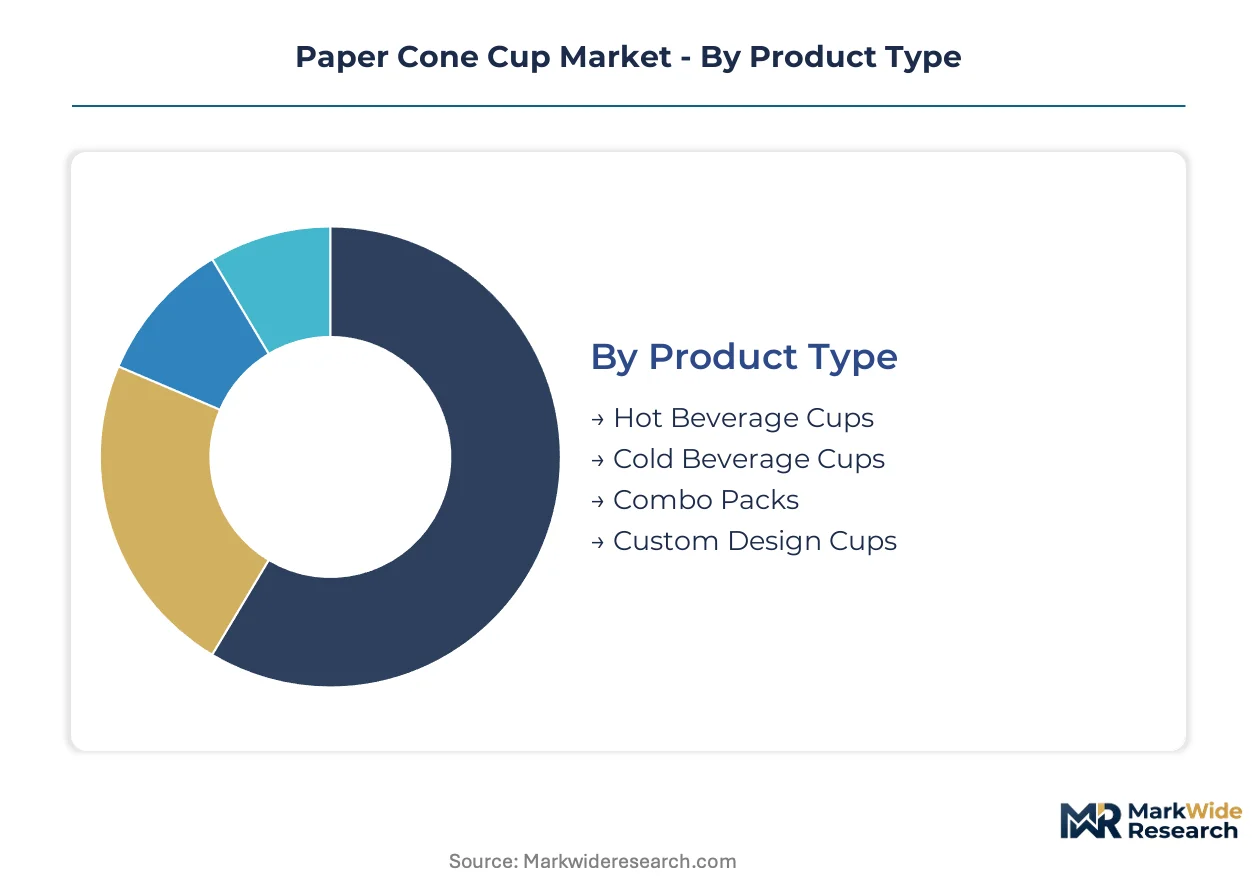
Paper cone cup segmentation reveals distinct performance requirements across temperature applications and disposal pathways. Material specifications and distribution economics create divergent margin profiles that shape supplier specialization strategies.
Product Type:
After-sales service intensity varies sharply by temperature rating and customization complexity, with hot-fill applications demanding technical support for barrier performance validation.
- Hot Beverage Cups:Single-wall fiber vessels with heat-resistant barrier coatings withstand temperatures exceeding 85°C for coffee and tea service. Quick-service chains in Germany and the Netherlands specify these for automated dispensing equipment, where dimensional consistency prevents jamming. By volume, Hot Beverage Cups leads. By growth pace, Custom Design Cups is ahead.
- Cold Beverage Cups:Lighter-weight constructions with moisture-resistant but lower heat-tolerance barriers serve juice, soft drink, and soft-serve applications. German municipal composting infrastructure absorbs these grades readily, validating simplified barrier formulations that reduce unit costs.
- Combo Packs:Assorted size configurations bundled for event catering and foodservice distributors seeking procurement efficiency.
- Custom Design Cups:Branded print specifications with proprietary taper angles and bottom-seal geometries for chain-exclusive supply agreements.
Temperature performance separates procurement specifications more decisively than volume scale across European foodservice channels.
Material:
Cost tier stratification follows certification grade and fiber sourcing intensity, with premium biodegradable grades commanding specification premiums in composting-enabled geographies.
- Biodegradable Paper:Certified compostable grades incorporating polysaccharide or silicone barriers replace legacy fluorinated coatings under REACH restrictions. German industrial composting facilities process these at scale, creating validated end-of-life economics that support price premiums.
- Coated Paper:Polyethylene-lined constructions retain dominant share in North American quick-service chains lacking municipal composting access, though EU regulatory deadlines are compressing this segment's European presence.
- 100% Recycled Material:Post-consumer fiber content meets corporate sustainability procurement thresholds without compostable certification complexity.
- Non-Coated Paper:Uncoated constructions for immediate consumption applications with minimal liquid exposure, primarily events and sampling programs.
Biodegradable Paper captures specification momentum where composting infrastructure exists; Coated Paper retains volume leadership in markets with recycling-stream optimization.
End User:
Customer type determines order frequency, customization depth, and compliance documentation requirements, with national chains consolidating procurement under dedicated supply agreements.
- Fast Food Chains:High-volume standardized specifications with national procurement contracts displacing fragmented regional purchasing. Three major US burger chains now control packaging standards across entire franchise networks, creating specification lock-in effects.
- Restaurants:Independent operators with mixed hot and cold beverage requirements, typically sourcing through wholesale distributors with limited technical specification involvement.
- Cafés:Premium positioning drives branded custom print requirements and compostable certification preferences aligned with consumer sustainability expectations.
- Events:Seasonal demand concentration with simplified product requirements and price-sensitive procurement through rental equipment suppliers.
Fast Food Chains generate the largest absolute volume; Cafés are expanding most quickly on per-unit value metrics.
Distribution Channel:
Supply concentration patterns favor direct relationships with volume buyers, while fragmentation persists in smaller-account servicing through intermediated channels.
- Wholesale Distributors:Dominant channel position serving fragmented independent restaurants and cafés with consolidated logistics and credit terms, though losing share to direct contracts at major chains.
- Direct Sales:Bypassing distributors through dedicated logistics contracts captures margin and locks specification control with multinational buyers, visible in US quick-service consolidation patterns.
- Online Retail:Small-order fulfillment for events, independent cafés, and test procurement with limited technical consultation.
- Supermarkets:Consumer-packaged formats for home and small-office consumption, marginal to foodservice volume.
Direct Sales channels are gaining share fastest as buyer consolidation accelerates; Wholesale Distributors retain the broadest account base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant procurement consolidation concentrates demand in Germany, the United States, and select European markets with mature composting infrastructure. National contracts at major chains now dictate specification standards across franchise networks, compressing regional supplier fragmentation. Regulatory deadlines under the EU Single-Use Plastics Directive and emerging state-level extended producer responsibility laws are accelerating geographic shifts in material sourcing.
Germany
Industrial composting facilities in Hamburg, Berlin, and Munich absorb certified biodegradable paper grades at scale, validating premium pricing for TUV Austria-certified products. The EU Green Deal and national packaging ordinances mandate plastic reduction timelines that favor fiber-based cone cups in automated coffee dispensing equipment. Baden-Württemberg hosts integrated pulp-to-cup manufacturing clusters serving quick-service chains across the DACH region.
United States
Three major burger chains now control packaging specifications across entire franchise networks, creating procurement consolidation in Texas, California, and the Southeast. FDA food-contact substance compliance requirements govern barrier coating formulations, while California and New York advance extended producer responsibility frameworks. The Pacific Northwest and Northeast corridor exhibit strongest compostable adoption where municipal infrastructure supports end-of-life processing.
France
National EPR implementation internalizes end-of-life costs for foodservice packaging, rewarding domestic producers with compliant compostable supply chains. The Île-de-France region concentrates quick-service restaurant headquarters procurement decisions that cascade to provincial franchise operations. REACH restrictions on perfluorinated chemicals eliminate legacy barrier coatings, accelerating silicone and polysaccharide alternative adoption in Lyon and Marseille foodservice clusters.
Netherlands
Amsterdam and Rotterdam quick-service chains pilot water-based bio-barrier cups for hot coffee service, validating performance in high-throughput automated dispensing environments. National waste management policies favor compostable fiber over recyclable polyethylene-lined alternatives where industrial composting access is universal. The Randstad region hosts distribution hubs serving Belgian and German cross-border procurement contracts.
United Kingdom
London and Southeast England concentrate café and fast-casual demand for branded custom print specifications with compostable certification preferences. Post-Brexit regulatory divergence creates compliance complexity as UK REACH develops separate chemical restriction timelines from EU frameworks. The Midlands and North England host wholesale distribution centers serving fragmented independent restaurant channels with consolidated logistics.
Paper Cone Cup Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market exhibits moderate consolidation at the integrated converter level while fragmenting among regional distributors and equipment-dependent formers. Three archetypes dominate: pulp-integrated multinationals with captive fiber supply, specialized barrier coating technology developers, and high-volume automated forming operators serving national chain contracts. Competitive moves concentrate on coating equipment retrofit partnerships and direct-to-chain logistics contract capture.
Among Nordic pulp-integrated multinationals, Stora Enso anchors fiber sourcing security through captive softwood supply, while Huhtamaki Oyj exemplifies bio-barrier R&D scale across European technical centers. At the North American volume end, Dart Container Corporation occupies a position tied to automated forming line throughput serving quick-service procurement consolidation. These three represent distinct competitive vectors: upstream resource control, coating chemistry development, and manufacturing scale efficiency.
| Leading Market Players |
|---|
| International Paper Company |
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Seda International Packaging Group |
| Stora Enso |
| Huhtamaki Oyj |
| Graphic Packaging International |
| Tekni-Plex, Inc. |
| Georgia-Pacific Consumer Products LP |
| Others |
Value Network & Pricing Analysis
Pulp price volatility in Nordic softwood markets determines both tier spreads between biodegradable and coated grades and the geographic shape of converter networks. Energy and logistics input swings compress margins uniformly, forcing integrated manufacturers to absorb cost spikes while non-integrated players retreat to contract-indexed sourcing.
Pricing Analysis
Cost-plus contracts with Nordic pulp indexation dominate procurement between converters and foodservice chains. Three-tier pricing structure across certified compostable, standard recyclable, and uncoated economy levels reflects TUV Austria certification premiums and volume scale. Pricing pressure stems from barrier coating equipment retrofit capital requirements that strain mid-tier producers. Fast Food Chains exhibit lowest price sensitivity through national contract consolidation, while independent Restaurants and Events segments drive hard bargaining on per-unit costs.
Supply Chain Analysis
Nordic softwood pulp from Sweden and Finland anchors upstream fiber supply, with German and French converters completing forming and coating stages. Water-based bio-barrier formulations and polyethylene resin constitute critical input dependencies alongside specialized coating application equipment. Single-source vulnerability concentrates in certified compostable barrier chemistry suppliers facing REACH reformulation deadlines. Distribution runs through wholesale distributors serving fragmented accounts, though Direct Sales channels gain share as multinational chains consolidate procurement under dedicated logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as national procurement contracts standardize specifications across franchise networks, creating interoperability lock-in effects that favor early movers with certified compostable supply chains.
For Market Incumbents: Pre-empt coating chemistry consolidation by securing exclusive bio-barrier formulation partnerships before REACH deadlines eliminate PFAS alternatives. Defend specification control at consolidated quick-service chains through integrated pulp-to-cup manufacturing investments in Germany and the Netherlands. Capacity expansion in Baden-Württemberg pulp clusters anchors cost position against Nordic fiber volatility. For New Entrants and Emerging Players: Build out cold beverage cone formats for juice and soft-serve applications where barrier requirements remain less stringent than hot-fill specifications. Target Events and independent Café segments with simplified certification pathways and rapid custom print turnaround. Partner with municipal composting operators in German industrial clusters to validate end-of-life economics supporting premium positioning. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors coating-technology specialists with approved silicone and polysaccharide alternatives. Long-term viability over the next decade hinges on compostable certification asset ownership rather than legacy polyethylene infrastructure. Watch for TUV Austria approval timelines as the inflection signal indicating which technology platforms achieve scalable market access.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Equipment Retrofit Partnership | Converts legacy polyethylene extrusion lines to water-based bio-barrier application serving EU regulatory deadlines. |
| Direct-to-Chain Logistics Contract | Bypasses wholesale distributors to capture margin and lock specification control with multinational quick-service buyers. |
| Compostable Certification Investment | Secures TUV Austria or BPI approval enabling premium positioning in German and Dutch municipal composting markets. |
| Backward Integration into Pulp Supply | Anchors fiber cost stability through captive Nordic softwood sourcing reducing exposure to energy and logistics volatility. |
| Cold Beverage Format Development | Addresses untapped juice and soft-serve segments with simplified barrier requirements and faster regulatory pathways. |
Research Methodology
The analysis maps hot beverage cups, cold beverage cups, biodegradable paper grades, and coated paper alternatives, each validated through procurement directors at quick-service chains, barrier coating R&D leads, wholesale distribution account managers, and municipal composting facility operators. Primary interviews combined with secondary validation from EU regulatory filings, FDA food-contact substance databases, Nordic pulp trade statistics, and national packaging ordinance texts. Bottom-up volume triangulation across converter capacity and top-down demand estimation from foodservice channel procurement data established analytical convergence.
Assumptions held fixed include EU Single-Use Plastics Directive enforcement timelines and German municipal composting facility capacity expansion trajectories, while Nordic pulp price volatility and REACH chemical restriction scope were varied across sensitivity scenarios. Segmentation dimensions modeled encompass temperature application, material certification grade, end-user channel consolidation status, and distribution pathway structure. CAGRs were derived from installed base replacement rates and new specification adoption curves across quick-service procurement cycles, with barrier coating performance evolution and buyer consolidation velocity as industry-specific forecast inputs.
Stress conditions across pulp cost spikes, bio-barrier shelf stability limitations, and composting infrastructure buildout delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and coating technology maturation trajectories. Cross-checking against EU EPR implementation progress and national composting facility commissioning announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paperboard Tray Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Display Paper Box Market