
 Mailer Box Market | 2026-2036
Mailer Box Market Size, Share, and Industry Trends Forecast 2026-2036
Mailer Box Market Foresight
FSC certification cycles for corrugated supply chains is collapsing from eighteen-month intervals to six-month audits, squeezing smaller converters out of retail-grade contracts. International Paper leverages its captive pulp capacity to sustain mill-direct pricing on kraft linerboard. Smurfit Westrock anchors European e-commerce supply through integrated corrugated and display packaging operations. Packaging Corporation of America dominates North American boxboard with recycled-content specialization across its containerboard network.
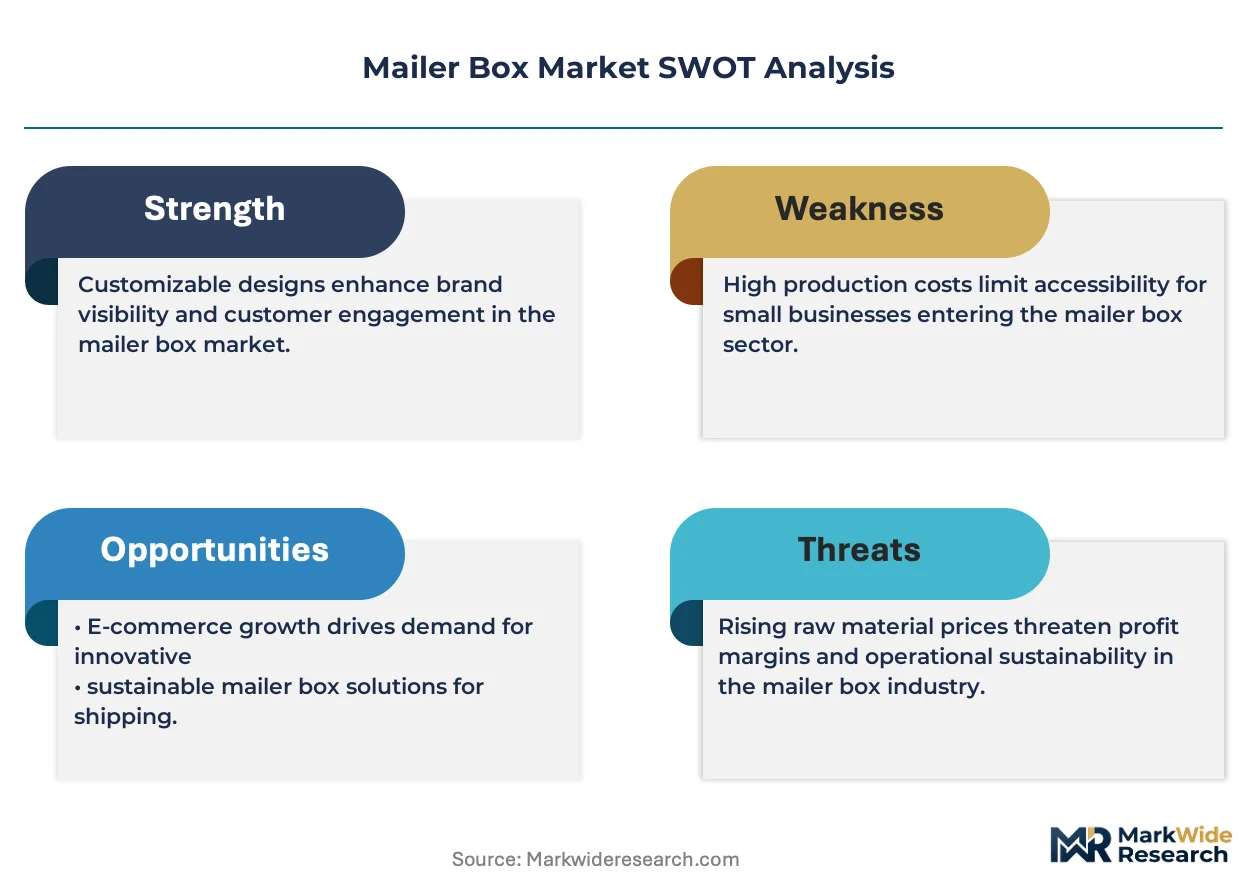
A mailer box is a self-sealing corrugated fiberboard container, typically constructed from 32 ECT to 44 ECT C-flute or B-flute board with tear-strip or adhesive closure, engineered for single-item or multi-item shipment without additional outer packaging. Cardboard mailers lead volume but carry thin margins; eco-friendly packaging types command price premiums as brands pursue plastic-free fulfillment pledges. Subscription services represent the fastest-growing end user segment, with custom size specifications driving shorter run lengths and digital print conversion.
The EPA guides recycled fiber standards under Comprehensive Procurement Guidelines, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility fees scaled to recyclability performance. FDA compliance for food-contact mailer surfaces shapes material selection in meal-kit and specialty food channels. Stakeholders must monitor how state-level recycled content laws in California and Washington diverge from federal baselines, creating compliance fragmentation that favors multi-plant operators with regional specification flexibility.
Market Dynamics
E-commerce fulfillment networks are collapsing order batch sizes and accelerating print-to-ship velocity, forcing mailer box converters to retool for sub-500-unit digital runs with same-day turnaround commitments.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility fees scaled to recyclability performance are pushing brands toward corrugated mailers over plastic alternatives, tightening specifications across German and French fulfillment networks.
- Subscription commerce:Meal-kit and specialty food channels are specifying custom-dimension mailers with food-contact-compliant barriers, driving specification diversity and repeat-order contract structures.
- Digital inkjet conversion:Single-pass corrugated printing is collapsing setup times and enabling economical variable-data branding at run lengths below 250 units.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import quota policies, compressing margins for non-integrated converters lacking captive pulp or long-term recovered fiber contracts.
- Mill concentration in Nordic kraft linerboard:Three suppliers control majority European virgin kraft capacity, creating bottleneck risk for retail-grade mailer specifications requiring high tear strength.
- Plastic mailer substitution in apparel:Polyethylene bubble mailers retain cost advantage below 8-ounce shipments, limiting corrugated penetration in fast-fashion returns-heavy channels.
Strategic Opportunities
- India e-commerce fulfillment buildout:Flipkart and Amazon India are localizing packaging specifications, creating demand for BIS-certified corrugated mailers with monsoon-resistant barriers.
- Walmart Marketplace seller packaging mandates:Third-party vendor requirements for frustration-free certification are opening specification influence to secondary packaging suppliers.
- Water-based barrier coatings:Fluorochemical-free oil and grease resistance is converging with fiber-based cushioning, enabling single-material mailers that bypass composite recycling complexity.
Industry Challenges
- FSC chain-of-custody audit compression:Certification cycles collapsing from eighteen to six months are straining quality management staffing at mid-tier converters.
- Legacy ERP integration with print workflow automation:Job ticketing systems from pre-digital eras require middleware development to connect with web-to-pack customer portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mailer Box Market |
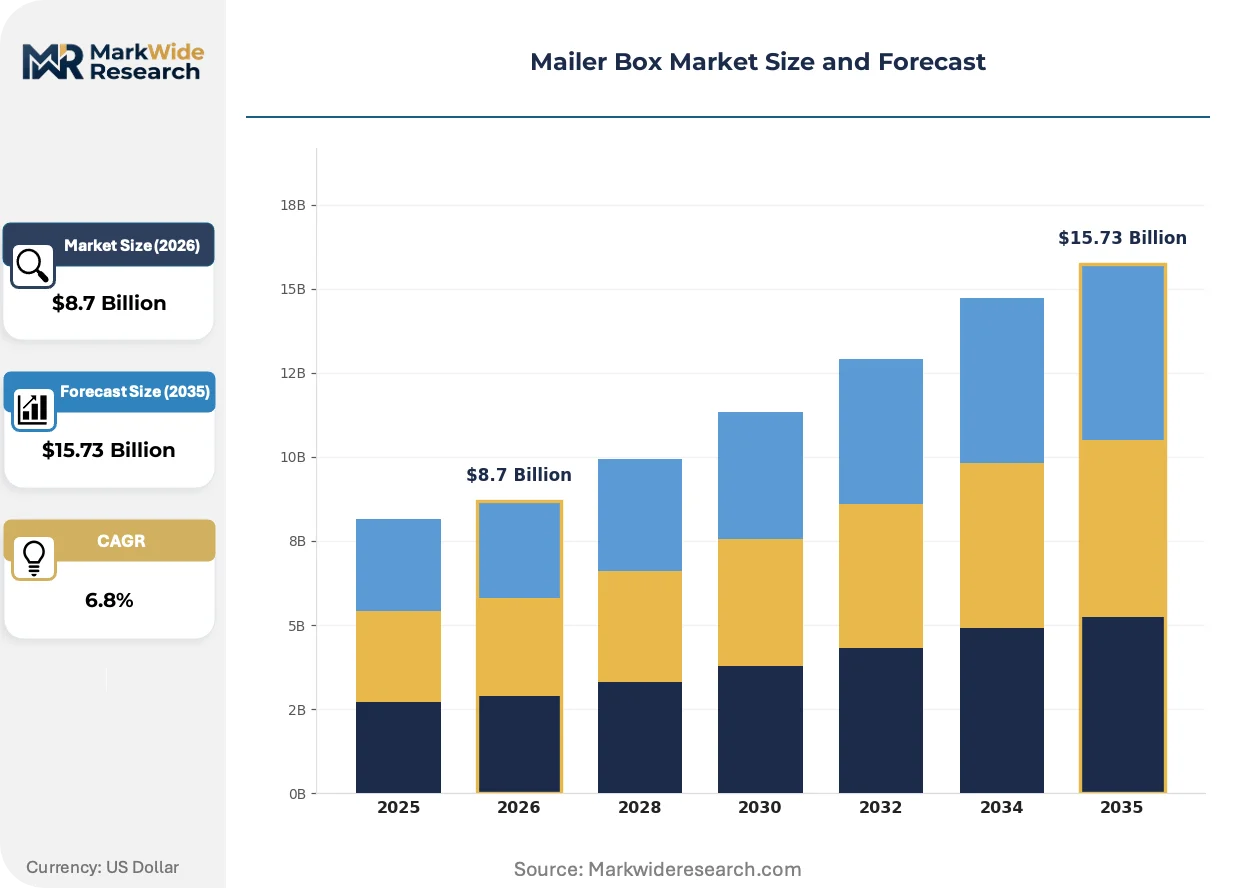
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard, Rigid, Flexible, Poly Mailers End User: E-Commerce, Retail, Food & Beverage, Subscription Services Size: Small, Medium, Large, Custom Packaging Type: Single-wall, Double-wall, Eco-friendly, Printed |
| Companies Covered | International Paper, Smurfit Westrock, Packaging Corporation of America, Sonoco, Packwire, UPrinting, Paper Mart, Green Bay Packaging, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mailer Box Market Shifts & Advancements
Digital production technologies and regulatory chemistry restrictions are simultaneously compressing run economics and rewriting material specifications across mailer box supply chains.
Single-pass inkjet systems are fragmenting the conventional flexo-dominated production landscape. Direct-to-corrugated inkjet eliminates plate costs and enables economical lot sizes below 100 units. Beauty and wellness subscription brands are adopting these capabilities for seasonal variant packaging at weekly refresh cycles.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from food-contact mailer specifications. The European Chemicals Agency enforcement timeline is forcing reformulation of barrier coatings ahead of full prohibition. Meal-kit operators are accelerating qualification of cellulose-based alternatives to maintain EU market access.
Direct-to-brand procurement is displacing distributor-mediated sourcing for mid-market e-commerce sellers. Shopify and WooCommerce merchants are specifying custom mailers through manufacturer-hosted configurators, bypassing traditional packaging distributor relationships. This pattern concentrates in North American direct-to-consumer verticals with high unboxing-video visibility requirements.
Mailer Box Market Segmentation
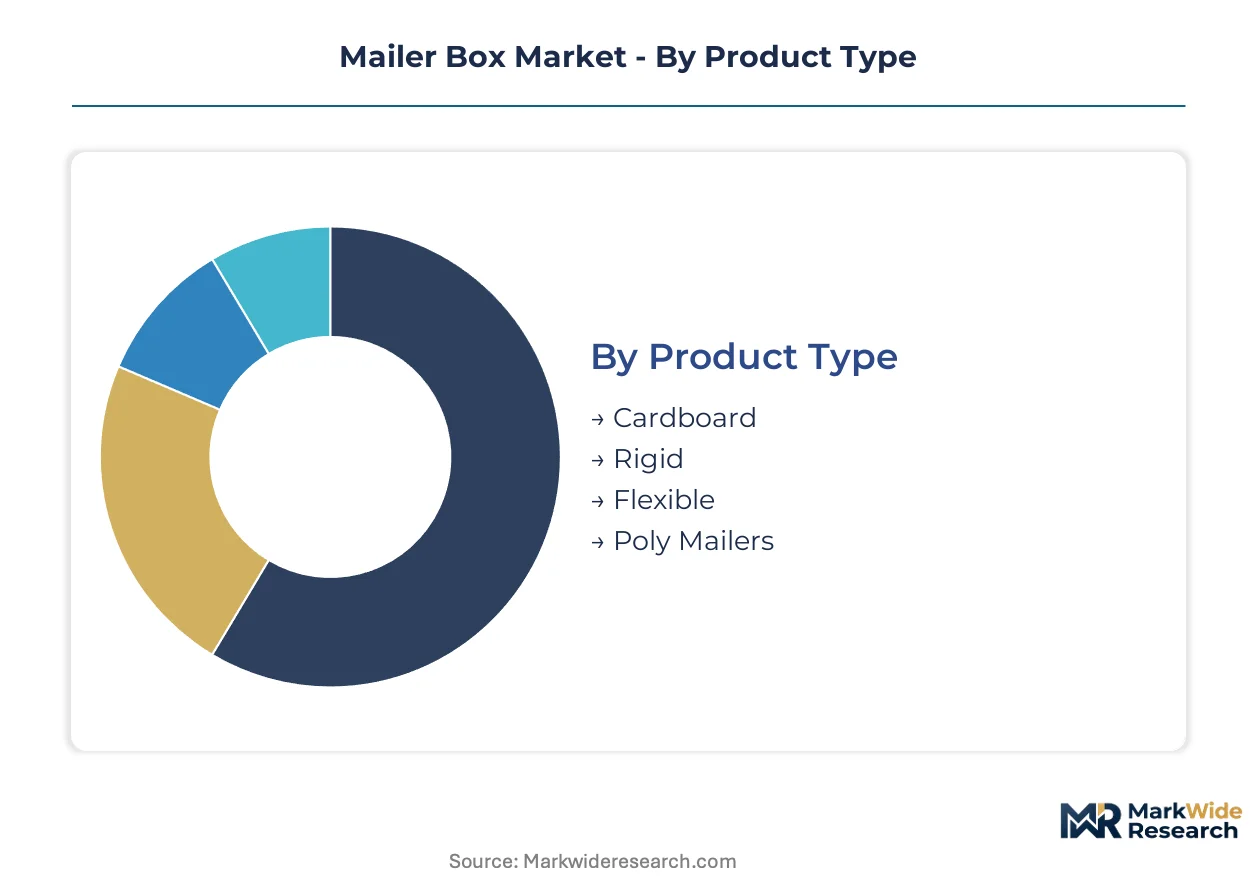
Mailer box specifications fragment across four intersecting dimensions that determine converter capability requirements and margin profiles. Product construction and end-use compliance create the primary segmentation fault lines, with size and packaging type specifications cascading from these core choices.
Product Type:
REACH restrictions on per- and polyfluoroalkyl substances and FDA food-contact compliance create divergent material qualification pathways across product categories.
- Cardboard:Constructed from 32 ECT to 44 ECT C-flute or B-flute corrugated fiberboard with tear-strip or adhesive closure. E-commerce fulfillment networks in Germany and France are specifying this construction for Amazon and Zalando operations under tightening EU Packaging and Packaging Waste Regulation recycled content mandates.
- Flexible:Lightweight fiber-based or polymer-hybrid constructions with conforming properties for irregular contents. Subscription services represent the steepest expansion trajectory for this segment, with custom size specifications driving shorter run lengths and digital print conversion.
- Rigid:Structural board constructions with reinforced corners and stacking strength for premium unboxing experiences. Luxury cosmetics and electronics brands specify these for high-visibility direct-to-consumer channels.
- Poly Mailers:Polyethylene bubble constructions retaining cost advantage below 8-ounce shipments in fast-fashion returns-heavy channels.
Established volume favors cardboard; emerging adoption favors flexible.
End User:
Customer procurement patterns range from centralized specification mandates to fragmented web-to-pack self-service configurations.
- E-Commerce:Fulfillment networks are collapsing order batch sizes and accelerating print-to-ship velocity, forcing converters to retool for sub-500-unit digital runs with same-day turnaround commitments. Amazon and Flipkart localization requirements span multiple continents.
- Subscription Services:Meal-kit and specialty food channels specify custom-dimension mailers with food-contact-compliant barriers, driving specification diversity and repeat-order contract structures. Beauty and wellness brands refresh packaging at weekly cycles using single-pass inkjet.
- Retail:Branded mailer specifications replace tertiary packaging in omnichannel fulfillment, with Walmart Marketplace seller mandates opening specification influence to secondary packaging suppliers.
- Food & Beverage:FDA compliance for food-contact surfaces and ECHA enforcement timelines on fluorochemical barriers shape material selection in this channel.
Volume concentrates in e-commerce; margin expansion concentrates in subscription services.
Size:
Dimensional specifications determine board grade selection and printing press compatibility across converter asset bases.
- Small:Single-item shipment formats dominating apparel and accessories fulfillment. Zalando and fast-fashion networks drive standardization here.
- Custom:Non-standard dimensions specified by subscription operators to minimize void fill and dimensional weight charges. Digital production technologies enable economical lot sizes below 100 units.
- Medium:Multi-item consolidation formats for general merchandise e-commerce.
- Large:Bulk shipment constructions requiring double-wall reinforcement for stacking integrity.
Standard sizes dominate unit volume; custom specifications dominate value growth.
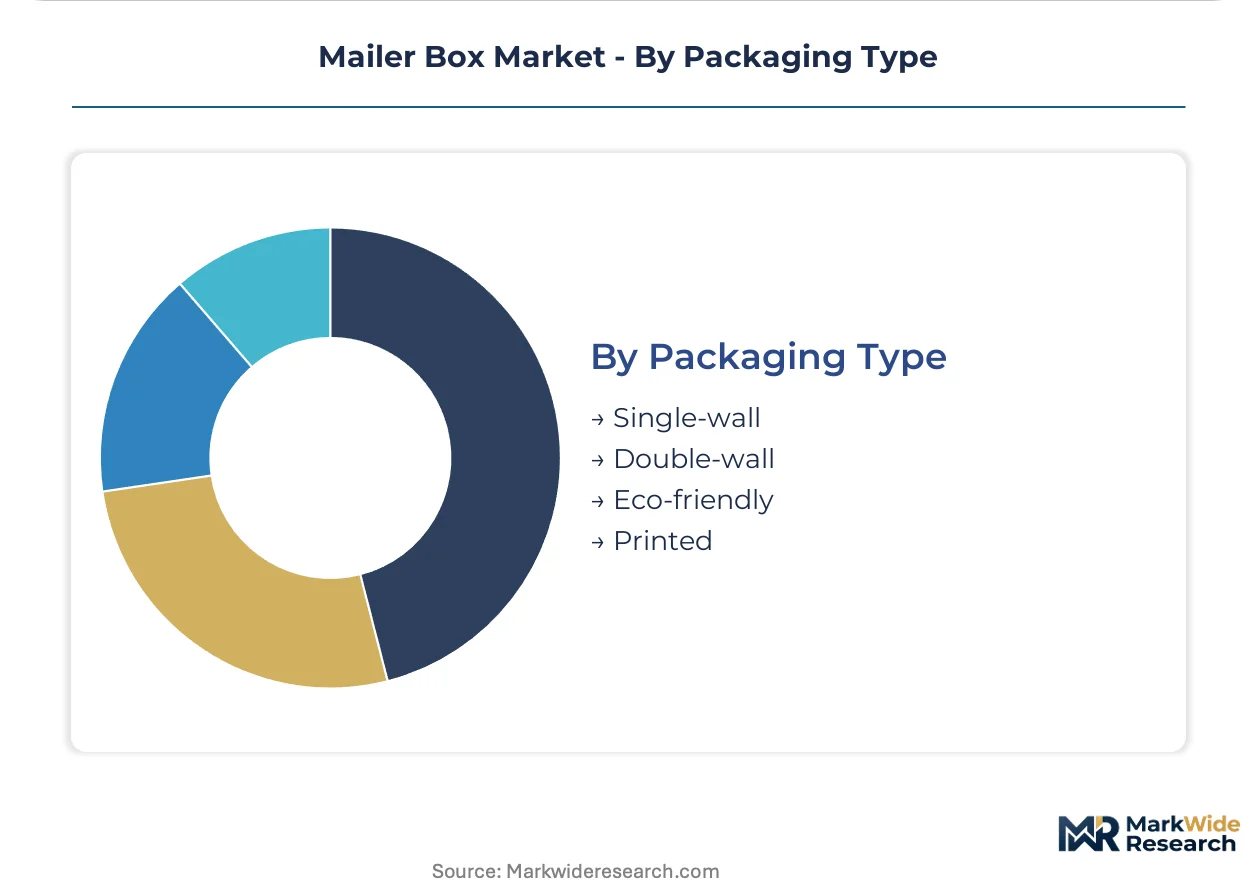
Packaging Type:
Structural and surface specifications segment by performance tier and sustainability positioning.
- Eco-friendly:Water-based barrier coatings and cellulose-based alternatives to fluorochemical treatments. REACH restrictions are eliminating legacy grease-resistant specifications, forcing reformulation ahead of full prohibition.
- Printed:Direct-to-corrugated inkjet and single-pass systems enabling variable-data branding. Direct-to-brand procurement through manufacturer-hosted configurators is displacing distributor relationships.
- Single-wall:Cost-optimized constructions for lightweight shipments under 15 pounds.
- Double-wall:Reinforced structures for heavy or fragile contents requiring edge crush resistance above 44 ECT.
Commodity specifications favor single-wall; sustainability pledges favor eco-friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is tightening recycled content mandates across member states. E-commerce fulfillment networks in Germany and France are driving specification standards for branded mailer boxes. Amazon and Zalando fulfillment networks anchor demand concentration in Western Europe.
United States
Amazon and Walmart Marketplace seller mandates are opening specification influence to secondary packaging suppliers. The EPA guides recycled fiber standards under Comprehensive Procurement Guidelines. California and Washington state-level recycled content laws diverge from federal baselines, creating compliance fragmentation that favors multi-plant operators with regional specification flexibility.
Germany
Amazon and Zalando fulfillment networks drive specification standards for corrugated mailers under tightening EU Packaging and Packaging Waste Regulation recycled content mandates. ECHA enforcement timelines on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from food-contact specifications. The Rhine-Ruhr industrial corridor concentrates converter capacity serving pan-European e-commerce distribution.
India
Flipkart and Amazon India are localizing packaging specifications, creating demand for BIS-certified corrugated mailers with monsoon-resistant barriers. The PLI scheme for manufacturing is attracting packaging investment alongside electronics and consumer goods production. Maharashtra and Karnataka host emerging converter clusters serving Bangalore and Mumbai fulfillment hubs.
China
Domestic e-commerce platforms are specifying custom mailer dimensions to minimize void fill and dimensional weight charges. MIIT standards and SAMR regulations shape material qualification for food-contact and export-grade packaging. The Yangtze River Delta and Pearl River Delta concentrate integrated pulp-to-box manufacturing serving both domestic and export fulfillment networks.
United Kingdom
Subscription commerce and direct-to-consumer verticals are driving demand for digital-print mailers with weekly refresh cycles. UK-specific packaging regulations operate alongside retained EU REACH commitments post-Brexit. The Midlands and Greater London host converter networks serving omnichannel retail fulfillment with same-day turnaround capabilities.
Mailer Box Market Competitive Landscape
Player mix skews toward integrated paper-to-box conglomerates with captive pulp capacity and regional specialists with digital production agility. The market exhibits tiered concentration: three multinational suppliers control virgin kraft linerboard supply, while hundreds of mid-tier converters compete on short-run customization and web-to-pack service models. Strategic archetypes include integrated pulp-to-box operators, digital-first custom converters, and distributor-mediated regional suppliers. Competitive moves center on backward integration into recovered fiber sourcing and single-pass inkjet capacity expansion.
Among North American integrated operators, International Paper and Packaging Corporation of America exemplify scale-driven archetypes with mill-direct pricing power and recycled-content specialization across containerboard networks. Smurfit Westrock anchors European e-commerce supply through integrated corrugated operations spanning multiple countries. These three represent the concentration end of a spectrum that fragments toward hundreds of regional converters competing on digital agility and custom specification response.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Westrock |
| Packaging Corporation of America |
| Sonoco |
| Packwire |
| UPrinting |
| Paper Mart |
| Green Bay Packaging |
| Berlin Packaging |
| Others |
Supply & Pricing Matrix
Six-week FSC chain-of-custody audit cycles now govern converter qualification timelines, compressing supplier panels and concentrating pricing leverage with integrated pulp-to-box operators possessing captive linerboard capacity.
Pricing Analysis
Certification level creates the primary spread, with FSC-certified retail-grade mailers commanding premium positioning over standard recycled-content specifications. Volume-scale tiering separates enterprise fulfillment contracts from sub-500-unit digital runs, while customization depth and barrier coating compliance add further differentiation layers. Pricing pressure stems from OCC feedstock volatility tied to Chinese import quota fluctuations, squeezing non-integrated converters lacking long-term recovered fiber agreements. Small e-commerce merchants show highest price sensitivity, whereas subscription services prioritize specification compliance over unit cost.
Supply Chain Analysis
Sweden and Finland anchor European virgin kraft linerboard production, while the United States and Germany concentrate integrated corrugated manufacturing serving e-commerce fulfillment networks. Raw material flows draw from OCC recovery streams, unbleached softwood pulp, and water-based barrier coating formulations. Single-source vulnerability sits with three Nordic suppliers controlling majority virgin kraft capacity for high-tear-strength retail specifications. Distribution runs through mill-direct contracts to major fulfillment operators, supplemented by regional converter networks handling short-run customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where digital print workflow integration and same-day turnaround guarantees expand faster than commodity box production.
For Market Incumbents: Consolidate backward integration into recovered fiber sourcing to offset OCC price volatility, while expanding single-pass inkjet capacity to capture subscription commerce refresh cycles. Amazon and Zalando specification mandates threaten distributor-mediated channels, making direct web-to-pack portal investment essential for retaining enterprise accounts. For New Entrants and Emerging Players: Differentiate on monsoon-resistant barrier technology for India e-commerce localization, where Flipkart and Amazon India are qualifying new suppliers. White-space exists in BIS-certified corrugated for Maharashtra and Karnataka fulfillment hubs, with food-contact compliance as the entry wedge. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-tier converter fragmentation creates roll-up opportunity around digital production assets and FSC certification infrastructure. Target regional specialists with installed single-pass inkjet and established brand-direct relationships. The signal to watch is EU Packaging and Packaging Waste Regulation enforcement tightening, which accelerates qualification barriers and supplier panel contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber | Captive OCC supply insulates margins from Chinese import quota volatility. |
| Single-Pass Inkjet Capacity Expansion | Sub-500-unit economics capture subscription commerce weekly refresh demand. |
| Direct-to-Brand Web-to-Pack Portal | Shopify merchant bypass of distributors concentrates specification influence. |
| Water-Based Barrier Coating Qualification | Fluorochemical-free formulations secure EU food-contact compliance ahead of REACH prohibition. |
| Regional Converter Acquisition | FSC-certified mid-tier assets provide immediate capacity in Germany and France fulfillment corridors. |
Research Methodology
Cross-validation between converter production data and e-commerce fulfillment procurement disclosures anchors the qualitative findings, combining primary interviews with corrugated plant managers, packaging specification leads at Amazon and Zalando, digital print workflow engineers, and FSC certification auditors alongside secondary validation through EPA Comprehensive Procurement Guidelines, EU Packaging and Packaging Waste Regulation filings, OCC trade flow databases, and containerboard mill capacity reports. Bottom-up demand modeling from end-use segments triangulates against top-down supply-side capacity assessments.
Sensitivity analysis around OCC price trajectories and digital print adoption curves informs the analytical framework across the projection horizon, with segmentation modeled by product construction, end-use compliance tier, size specification, and sustainability positioning. CAGRs derive from production volume trends correlated with e-commerce shipment growth indices and subscription service expansion rates, incorporating linerboard mill operating rates and converter digital capacity installation timelines as industry-specific inputs.
Material uncertainties — regulatory enforcement timing on PFAS barriers, Chinese recovered fiber import policy shifts, and single-pass inkjet technology cost curves — sit outside the modeled envelope. Forecasts reflect documented assumptions about fulfillment network localization pace and brand sustainability pledge conversion. Recalibration cycles align with material shifts in EU extended producer responsibility fee structures and FSC audit interval revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Greyboard Market