
 Permethrin Market | 2026-2036
Permethrin Market Size, Share, and Industry Trends Forecast 2026-2036
Permethrin Market Analysis
The EU Green Deal's Farm to Fork strategy is expanding the regulatory perimeter for synthetic pyrethroids, pushing formulators toward lower-volume, higher-efficacy delivery systems. BASF SE leverages its integrated isocyanate and agrochemical pipeline to secure active ingredient supply continuity. Bayer AG sustains market presence through its veterinary medicine channel, where permethrin-based ectoparasiticides retain strong clinician loyalty. Syngenta Group anchors its position in public health vector control through institutional procurement relationships with WHO-prequalified programs.
Permethrin is a synthetic pyrethroid insecticide modeled on natural pyrethrins from Chrysanthemum cinerariifolium, characterized by a 3-phenoxybenzyl alcohol ester structure with photostability superior to botanical analogs. It functions as a sodium channel modulator in arthropod nervous systems, delivering rapid knockdown and residual activity for agricultural, household, and veterinary applications. Emulsifiable concentrates dominate volume shipments due to established blending infrastructure and compatibility with aerial and ground spray equipment. Public health applications represent the fastest-expanding demand pool, driven by dengue and malaria vector control programs in tropical zones. Wettable powder formulations retain share in livestock producer segments where dilution flexibility and tank-mix compatibility with endectocides matter most.
EPA re-registration requirements under FIFRA mandate aquatic toxicity mitigation labels, reshaping how manufacturers position permethrin near water bodies. REACH authorization pressures in Europe are channeling R&D investment toward encapsulation technologies that reduce environmental loading. The EU F-Gas Regulation indirectly affects permethrin aerosol propellant choices, accelerating transitions to compressed gas systems. Stakeholders must monitor regulatory divergence between jurisdictions where residue tolerance harmonization remains incomplete.
Market Dynamics
Resistance management protocols in Brazil's soybean belt and cotton regions are mandating rotational chemistry, forcing formulators to reposition permethrin within integrated pest management stacks rather than standalone applications.
Growth Catalysts
- Vector control programs:WHO-prequalified dengue and malaria initiatives in tropical zones are expanding institutional procurement of wettable powder and emulsifiable concentrate formulations for indoor residual spraying.
- REACH authorization pressures:Encapsulation R&D investment in Europe is accelerating delivery systems that reduce environmental loading while maintaining arthropod knockdown efficacy.
- Brazilian agricultural expansion:Commercial farming operations in Mato Grosso and Goiás are widening uptake for aerial and ground spray applications against lepidopteran pests.
Market Restraints
- Pyrethroid resistance evolution:Anopheles and Aedes populations across West Africa and Southeast Asia are developing metabolic and target-site insensitivity, compressing residual efficacy windows.
- Aquatic toxicity mitigation:EPA FIFRA re-registration mandates are restricting application buffers near water bodies, eliminating use cases in rice paddies and riparian zones.
- Biological substitute advancement:Bacillus thuringiensis formulations and spinosad products are capturing share in organic-certified horticulture segments.
Strategic Opportunities
- Compressed gas aerosol transition:EU F-Gas Regulation compliance is opening retrofit markets for propellant-free delivery systems in household and professional pest control channels.
- Veterinary ectoparasiticide channel:Clinician loyalty to permethrin-based pour-ons and dips in bovine and ovine segments remains underexploited in Argentina and Uruguay.
- Encapsulation technology convergence:Microencapsulation combined with polymer film-forming agents is enabling extended residual claims in public health tenders.
Industry Challenges
- Formulation chemist scarcity:Expertise in photostabilizer selection and emulsion stability for pyrethroid esters is concentrating among aging technical staff at legacy agrochemical firms.
- Label expansion timelines:Obtaining residue tolerance harmonization across EPA, EFSA, and ANVISA jurisdictions for novel crop uses requires 4-7 year regulatory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permethrin Market |
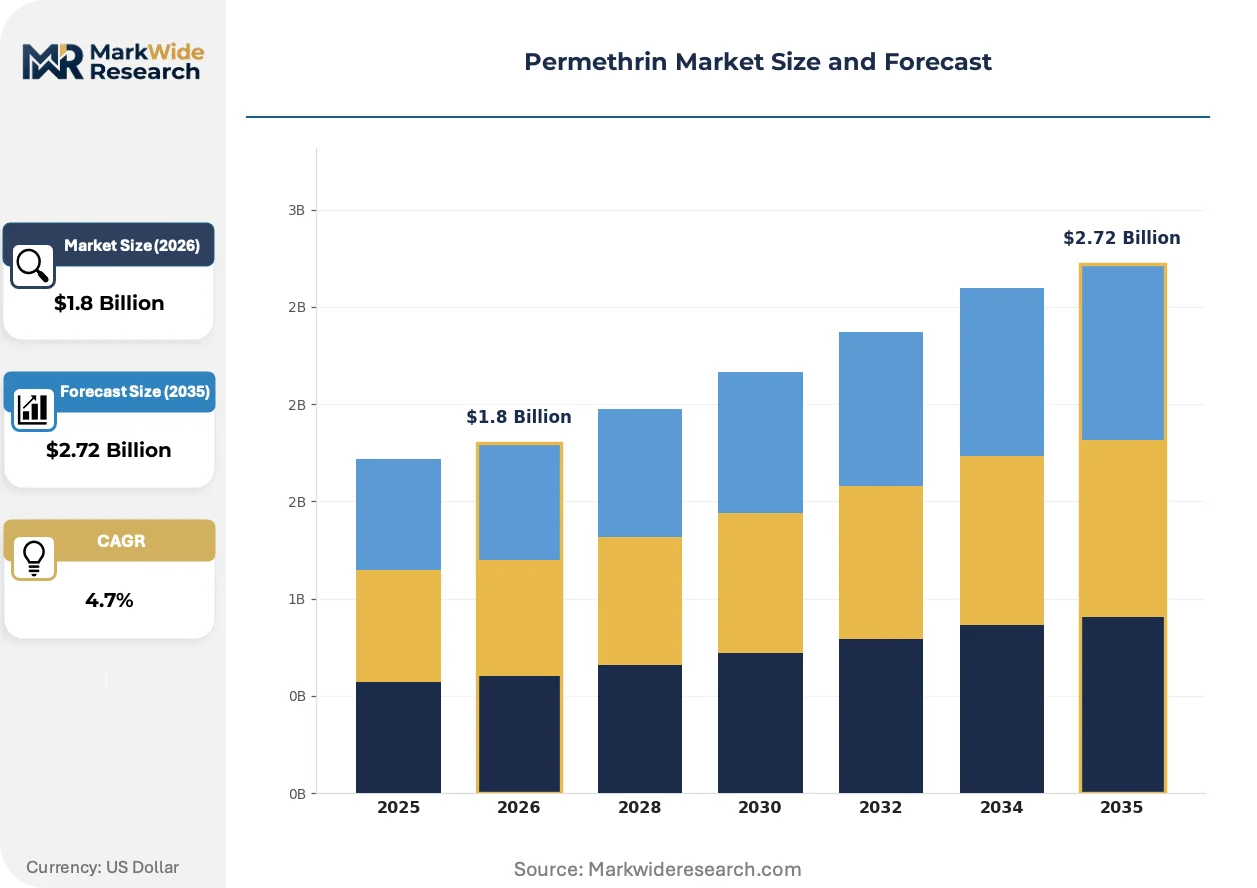
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosols, Liquids, Granules, Emulsifiable Concentrates Application: Agricultural Pest Control, Household Insecticides, Public Health, Veterinary Medicine Formulation: Wettable Powder, Suspension Concentrate, Oil-Miscible, Soluble Liquid End User: Agriculturists, Homeowners, Pest Control Services, Livestock Producers |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Sumitomo Chemical Co., Ltd., FMC Corporation, Tagros Chemicals, Corteva Agriscience, Nufarm Limited, Adama Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permethrin Market Emerging Trajectories
Formulation chemistry is pivoting toward precision delivery architectures that minimize active ingredient loading while preserving biological performance against resistant arthropod strains.
Microencapsulation with polyurea and gelatin-gum arabic wall systems is electrifying residual activity profiles in vector control applications. National malaria control programs in Ethiopia and Tanzania are transitioning procurement specifications toward these extended-release formats. The technology is electrifying competitive positioning among WHO-prequalified suppliers by compressing application frequency requirements and reducing operational logistics burdens.
EPA's aquatic toxicity mitigation labeling under FIFRA is eliminating emulsifiable concentrate use within 100-foot buffer zones of perennial water bodies. Manufacturers are reformulating with drift-reduction adjuvants and coarser droplet spectra to retain agricultural market access. Cotton and soybean applicators in the Mississippi Delta are retrofitting aerial spray nozzles to maintain compliance without sacrificing coverage uniformity.
Institutional procurement consolidation among vector control programs is displacing fragmented distributor networks with direct manufacturer contracts tied to efficacy performance guarantees. WHO-prequalified product lists are becoming the primary qualification gate for malaria initiative funding. This pattern is most visible across sub-Saharan Africa, where Global Fund and PMI procurement centralization is compressing supplier margins while locking in volume commitments for compliant formulators.
Permethrin Market Segmentation
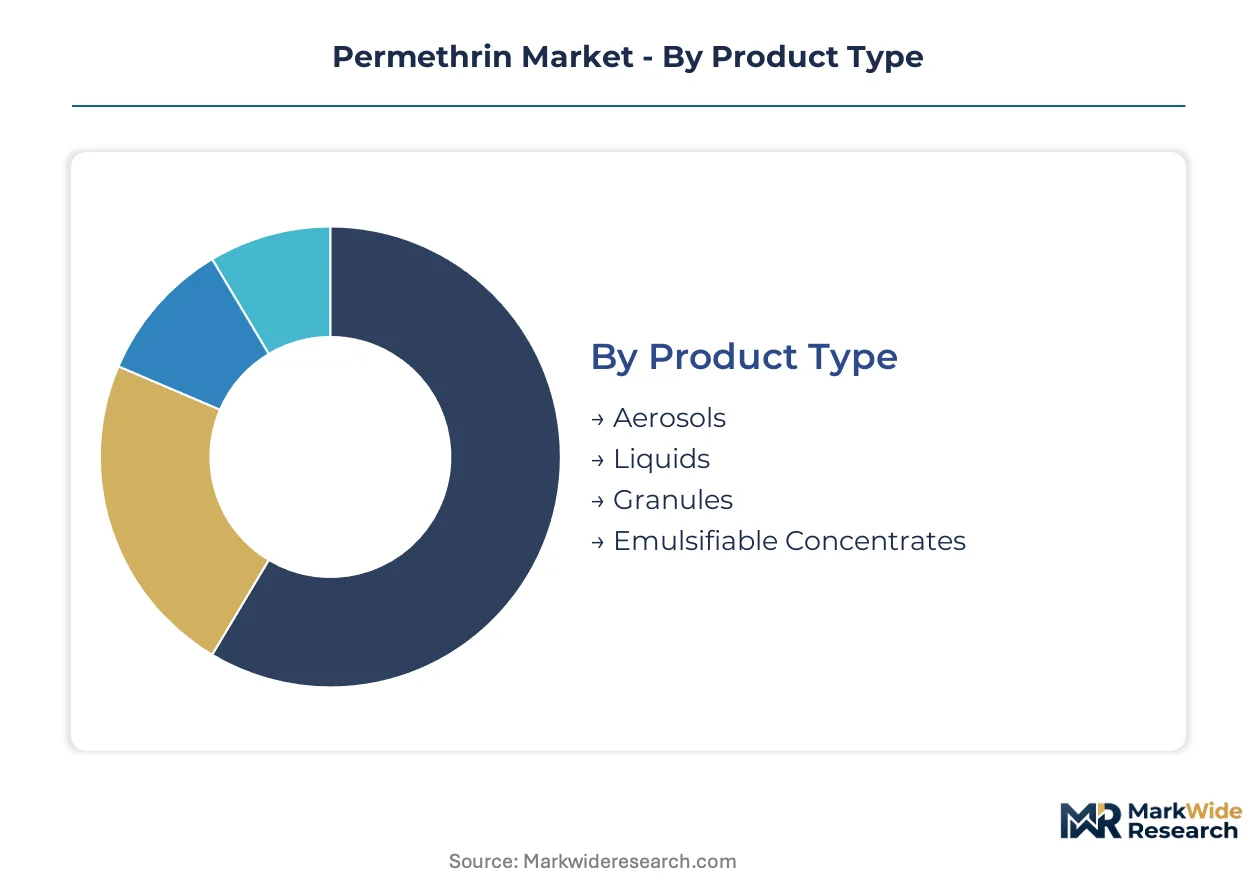
Permethrin's chemical versatility across pyrethroid ester formulations creates divergent supply chain configurations. Each segment demands distinct technical specifications, from photostabilizer loading to emulsion stability, that reshape manufacturing asset allocation and distribution economics.
Product Type:
Supply concentration among legacy agrochemical formulators favors liquid-based delivery systems with established blending infrastructure.
- Emulsifiable Concentrates:Oil-in-water emulsion systems containing 10-50% active ingredient with solvent carriers and surfactant packages. Demand concentrates in Brazil's Mato Grosso soybean belt where aerial spray compatibility and tank-mix flexibility with fungicides drive procurement decisions. EPA FIFRA buffer zone restrictions are forcing nozzle retrofits to retain rice paddy access.
- Aerosols:Pressurized formulations using hydrocarbon or compressed gas propellants with 0.5-1.0% active ingredient loading. Household penetration in urban India and Southeast Asia is accelerating transitions away from F-gas propellants under EU regulatory pressure.
- Liquids:Ready-to-use aqueous solutions with reduced dermal toxicity profiles for consumer handling. Concentrated stock solutions for professional dilution dominate pest control service procurement in North American residential channels.
- Granules:Clay or corn-cob carrier matrices with 1-5% active ingredient for soil incorporation. Turf and ornamental applications in golf course maintenance retain steady offtake despite slower growth trajectories.
Emulsifiable concentrates absorb the bulk of installed capacity; aerosols are expanding most quickly.
Application:
Customer procurement patterns split between institutional tender-based purchasing and discretionary retail acquisition.
- Public Health:WHO-prequalified indoor residual spraying programs specify wettable powder and emulsifiable concentrate formulations for Anopheles and Aedes vector control. Ethiopia and Tanzania are transitioning procurement specifications toward microencapsulated extended-release formats that compress application frequency.
- Agricultural Pest Control:Cotton bollworm and soybean looper management in Brazil's Cerrado biome drives emulsifiable concentrate volume. Resistance management protocols mandating rotational chemistry are repositioning permethrin within integrated pest management stacks rather than standalone applications.
- Household Insecticides:Consumer aerosol and liquid formulations for crawling and flying insect control. Urban densification in tropical zones sustains replacement demand despite biological substitute competition.
- Veterinary Medicine:Ectoparasiticide pour-ons, dips, and sprays for bovine and ovine tick and lice management. Clinician loyalty in Argentina and Uruguay remains underexploited relative to North American saturation.
Public health applications command premium pricing through performance guarantees; agricultural pest control maintains volume leadership.
Formulation:
Margin structures vary with technical complexity of delivery architecture and regulatory qualification burden.
- Wettable Powder:Fine particle dispersions with 10-80% active ingredient and wetting agents for tank-mix suspension. Livestock producer preference in Australia and New Zealand centers on dilution flexibility and compatibility with endectocides like macrocyclic lactones.
- Suspension Concentrate:Aqueous dispersed systems with reduced solvent exposure and improved operator safety profiles. European REACH authorization pressures are channeling R&D investment toward these lower-VOC alternatives.
- Oil-Miscible:Solutions in refined petroleum distillates for ultra-low volume spraying. Spatial repellent applications in malaria-endemic regions require specialized drift management protocols.
- Soluble Liquid:Water-miscible concentrates with glycol ether co-solvents for rapid dilution. Professional pest control service adoption in German and French urban markets favors handling convenience.
Wettable powder formulations retain manufacturing scale; suspension concentrates are climbing the fastest.
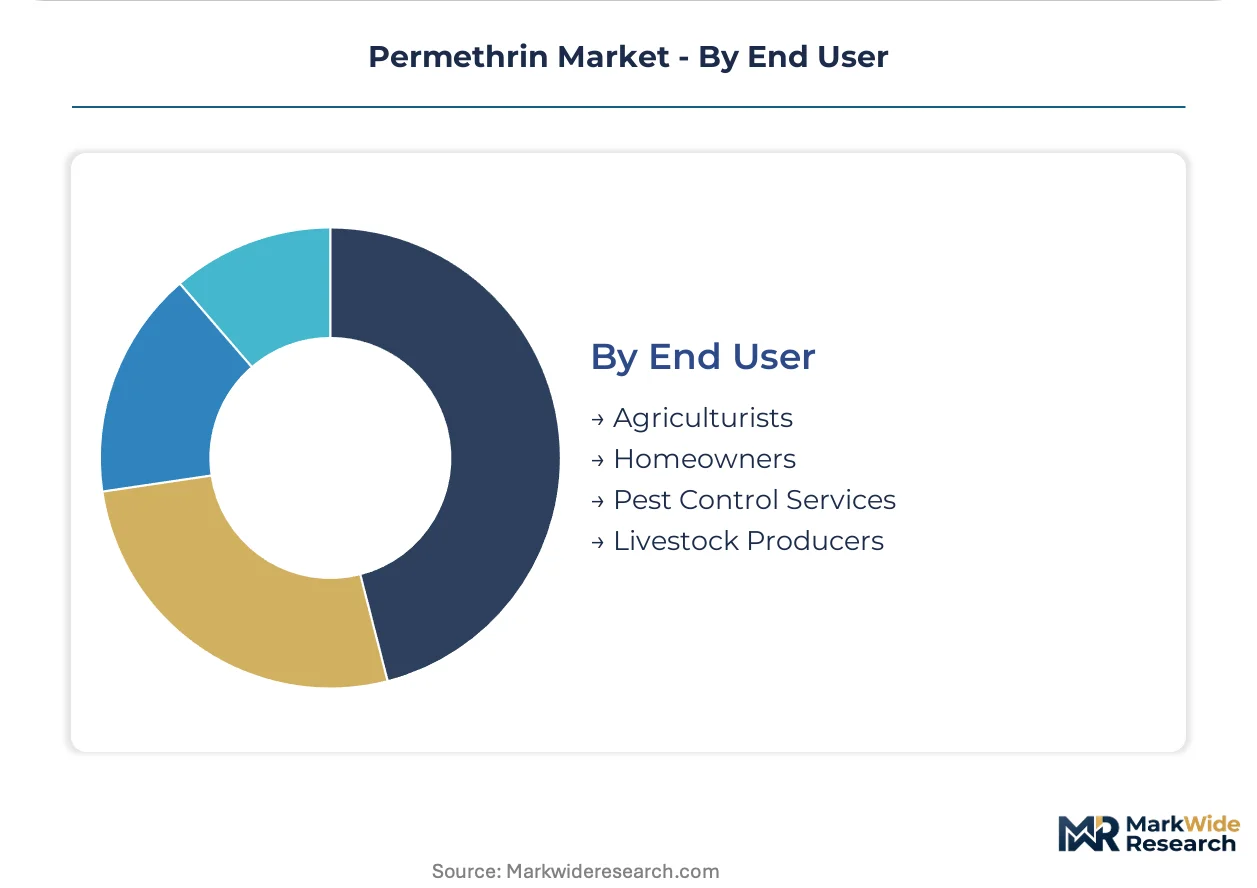
End User:
Purchasing sophistication ranges from price-sensitive commodity buying to outcome-based performance contracting.
- Pest Control Services:Licensed applicators procuring concentrated formulations for commercial and residential treatment. Direct manufacturer relationships are displacing fragmented distributor networks in North American metropolitan markets.
- Agriculturists:Commercial farming operations managing resistance through rotational chemistry protocols. Brazilian cotton and soybean belt expansion in Goiás and Bahia widens aerial and ground spray uptake.
- Livestock Producers:Sheep and cattle operations using pour-ons and dips for ectoparasite management. Seasonal treatment calendars in Patagonian and Uruguayan pastoral systems create predictable demand windows.
- Homeowners:Retail aerosol and ready-to-use liquid purchasers with low switching costs. E-commerce penetration in Indian and Indonesian urban centers is reshaping channel economics.
Pest control services concentrate procurement volume; agriculturists show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors pyrethroid formulation activity, with blending facilities serving Brazil's agricultural belt. Demand concentrates where soybean and cotton expansion meets vector control procurement.
Brazil
ANVISA residue tolerance protocols govern aerial spray applications across Mato Grosso and Goiás cotton belts. EPA-equivalent buffer zone restrictions are compressing rice paddy access, forcing nozzle retrofits in the Cerrado biome. São Paulo formulators supply emulsifiable concentrates to commercial farming operations managing lepidopteran resistance through rotational chemistry stacks.
United States
EPA FIFRA re-registration mandates aquatic toxicity mitigation labels near perennial water bodies. Mississippi Delta cotton applicators retrofit aerial spray nozzles to retain coverage uniformity within 100-foot buffer zones. Texas and Arkansas livestock producers sustain pour-on demand through seasonal ectoparasite treatment calendars.
Germany
REACH authorization pressures channel R&D investment toward encapsulation technologies that reduce environmental loading. BASF SE leverages integrated isocyanate pipelines from Ludwigshafen to secure active ingredient supply continuity. ECHA regulatory divergence from EPA residue harmonization extends label expansion timelines for novel crop uses.
India
Central Insecticides Board registration requirements govern public health vector control procurement for dengue and malaria programs. Maharashtra and Gujarat formulators supply wettable powders to WHO-prequalified indoor residual spraying initiatives. Urban densification in Mumbai and Delhi sustains household aerosol replacement demand despite biological substitute competition.
Australia
APVMA registration protocols align with OECD residue harmonization frameworks for livestock ectoparasiticides. Queensland and New South Wales sheep producers favor wettable powder dilution flexibility for tank-mix compatibility with macrocyclic lactone endectocides. Seasonal treatment windows in pastoral systems create predictable procurement cycles for pour-on formulations.
Permethrin Market Vendor Landscape
The competitive structure tilts toward diversified agrochemical conglomerates with captive pyrethroid supply chains. Formulation expertise concentrates among legacy technical staff at established chemical firms. Three archetypes dominate: integrated isocyanate-to-agrochemical pipelines, veterinary medicine channel specialists, and public health procurement contractors. Capacity expansion and encapsulation technology licensing represent the primary competitive moves reshaping positioning.
Among European-based conglomerates, BASF SE and Bayer AG exemplify divergent strategic anchors within the permethrin value chain. BASF SE occupies a position tied to upstream isocyanate integration, while Bayer AG represents veterinary medicine channel persistence through clinician loyalty frameworks. Syngenta Group sits within the public health procurement tier, anchoring institutional relationships with WHO-prequalified vector control programs. These three entities collectively illustrate how regulatory qualification burdens and formulation chemistry expertise concentrate competitive advantage.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Sumitomo Chemical Co., Ltd. |
| FMC Corporation |
| Tagros Chemicals |
| Corteva Agriscience |
| Nufarm Limited |
| Adama Agricultural Solutions |
| Others |
Supply Flow & Price Mechanics
EPA FIFRA aquatic toxicity mitigation mandates gate qualified supply access for rice paddy and riparian zone applications, compressing margins on standard emulsifiable concentrates while opening premium tiers for drift-reduction formulations and encapsulated extended-release products that command performance-based pricing.
Pricing Analysis
Residual efficacy guarantees anchor value-based pricing in WHO-prequalified public health tenders, where microencapsulated wettable powders command premiums over standard formulations. WHO-prequalification status and encapsulation technology certification stratify pricing across premium, standard, and economy tiers. Pricing pressure stems from pyrethroid resistance evolution compressing residual efficacy windows in West African vector programs. Agricultural pest control buyers in Brazil's Mato Grosso exhibit highest price sensitivity due to rotational chemistry mandates, while institutional procurement programs in Ethiopia and Tanzania show lowest sensitivity tied to performance guarantees.
Supply Chain Analysis
Regional distribution centers in São Paulo's industrial corridor anchor hub-and-spoke patterns serving Brazil's agricultural belt, with secondary nodes in Ludwigshafen and Mumbai supporting European and Asian demand. Active ingredient synthesis concentrates in China, India, and Germany, drawing from 3-phenoxybenzyl alcohol and m-phenoxybenzaldehyde intermediates. Single-source vulnerability in isocyanate feedstocks for encapsulation wall systems creates exposure to BASF SE's Ludwigshafen asset concentration. Distribution runs through direct manufacturer contracts displacing fragmented distributor networks in sub-Saharan malaria control programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and captive isocyanate supply are becoming the decisive levers in a vertical-integration race, as regulatory qualification burdens concentrate competitive advantage among legacy agrochemical conglomerates with upstream chemical assets.
For Market Incumbents: Hedge against biological substitute advancement by deepening backward integration into photostabilizer and emulsion stabilizer chemistries. Secure ANVISA, EPA, and EFSA residue tolerance harmonization for novel crop uses through dedicated regulatory investment units. Lock in volume commitments with Global Fund and PMI procurement centralization through extended-release encapsulation performance guarantees. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for compressed gas aerosol retrofit markets in household and professional pest control channels. Target veterinary ectoparasiticide white space in Argentina and Uruguay where clinician loyalty to permethrin-based pour-ons remains underexploited. Pursue technology licensing from legacy encapsulation specialists rather than greenfield R&D to compress qualification timelines. For Investors and Strategic Acquirers: WHO-prequalification list consolidation is the leading indicator that institutional procurement will concentrate among three to four compliant formulators, compressing supplier margins while locking in volume. Position for five-to-ten year viability through acquisition of microencapsulation technology specialists with existing regulatory dossiers. Watch for EPA FIFRA buffer zone restriction expansion as the signal for drift-reduction adjuvant and coarser droplet formulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Accelerates WHO-prequalification access for extended-release vector control formulations. |
| Backward Integration into Isocyanates | Secures active ingredient supply continuity amid ECHA REACH authorization pressures. |
| Direct Procurement Contracting | Displaces fragmented distributor networks in Global Fund malaria initiative funding. |
| Drift-Reduction Adjuvant Development | Retains rice paddy market access under EPA FIFRA buffer zone mandates. |
| Veterinary Channel Expansion | Captures underexploited clinician loyalty in Patagonian and Uruguayan pastoral systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across formulation chemists, vector control program procurement officers, livestock producer associations, and agrochemical distribution channel partners. EPA FIFRA re-registration documents, ANVISA residue tolerance protocols, ECHA REACH authorization records, and WHO-prequalification product lists supplied validation anchors. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Granularity extended to formulation type, application segment, and regional regulatory cluster, with CAGRs derived from volume and value trajectory convergence. Modeled inputs included resistance management protocol adoption rates in Brazil's Cerrado biome, encapsulation technology penetration in Ethiopian and Tanzanian malaria programs, and compressed gas aerosol transition velocity under EU F-Gas Regulation compliance deadlines throughout the forecast period.
The model assumes a particular technology adoption path for microencapsulation and polymer film-forming agent convergence; alternative pathways for biological substitute advancement would alter the outlook for synthetic pyrethroid demand. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and resistance evolution patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Global Industrial Oils Market