
 Capsular Tension Rings Market | 2026-2036
Capsular Tension Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Capsular Tension Rings Market Outlook
The EU Medical Device Regulation is recalibrating compliance thresholds for intraocular devices across European markets. Alcon Laboratories leverages its vertically integrated manufacturing footprint to sustain cost advantages in PMMA ring production. Morcher GmbH anchors its competitive position through specialized German engineering of custom tension ring geometries. Ophtec BV differentiates via proprietary hydrophilic surface technologies that reduce postoperative inflammatory response.
Capsular tension rings are polymethyl methacrylate or silicone devices implanted during cataract extraction to stabilize the capsular bag in zonular-compromised eyes, typically measuring 10-13 mm in expanded diameter with 0.2-0.3 mm cross-sectional thickness. Their primary function is to maintain capsular integrity during phacoemulsification and intraocular lens insertion. PMMA rings dominate procedural volume due to established biomechanical reliability and surgeon familiarity, while hydrophobic rings capture expanding share in premium cataract segments where reduced posterior capsular opacification matters. Application demand concentrates in cataract surgery as glaucoma treatment and refractive surgery applications remain comparatively nascent channels for tension ring utilization.
FDA 510(k) clearance pathways and the EU MDR conformity assessment framework govern market access for capsular tension rings, with both regulators intensifying scrutiny of biocompatibility documentation and clinical follow-up data. Japan's PMDA maintains distinct pharmaceutical and medical device classification standards that require localized testing protocols for silicone-based variants. Stakeholders must monitor evolving sterilization validation requirements and regional reimbursement determinations for complex cataract procedures to align portfolio investments with shifting compliance burdens and payer incentives.
Market Dynamics
The EU Medical Device Regulation (MDR) is recalibrating compliance thresholds for intraocular devices, forcing manufacturers to restructure clinical evidence portfolios and sterilization validation protocols while ambulatory surgery centers absorb higher procurement costs for certified inventory.
Growth Catalysts
- Aging demographics:Expanding Medicare-covered cataract volumes in the United States and Japan's super-aged society are sustaining procedural demand for zonular stabilization devices in complex cases.
- EU MDR implementation:Stricter conformity assessment frameworks for Class IIb devices are consolidating supplier bases toward established PMMA and silicone ring manufacturers with robust quality management systems.
- Phacoemulsification platform advancement:Femtosecond laser-assisted cataract surgery adoption in German and Japanese academic medical centers is elevating surgical precision requirements that favor standardized tension ring geometries.
Market Restraints
- PMMA raw material concentration:Optical-grade polymethyl methacrylate supply chains concentrate among a limited set of European and Asian chemical processors, exposing device manufacturers to input cost volatility and qualification delays.
- Reimbursement compression:Complex cataract procedure coding in US Medicare and German statutory health insurance systems often fails to differentiate zonular-compromised cases, limiting surgeon willingness to utilize adjunctive devices.
- Silicone biocompatibility documentation:PMDA's distinct pharmaceutical-medical device classification standards for silicone-based variants impose redundant testing protocols that extend Japanese market entry timelines by 18-24 months relative to PMMA equivalents.
Strategic Opportunities
- Indian cataract surgical camps:Government-funded blindness elimination programs and private hospital chains in Maharashtra and Tamil Nadu present volume opportunities for cost-optimized tension ring designs adapted to high-throughput manual small-incision techniques.
- Glaucoma-cataract combination surgery:Minimally invasive glaucoma surgery (MIGS) device integration with phacoemulsification workflows creates demand for modified ring geometries that accommodate angle-based stent placement without capsular distortion.
- EU Green Deal alignment:Medical device sustainability reporting requirements under the Corporate Sustainability Reporting Directive incentivize manufacturers to develop recyclable packaging and reduced-sterilant-burden processing for single-use polymethyl methacrylate implants.
Industry Challenges
- MDR technical documentation:The EU's intensified scrutiny of clinical evaluation reports and post-market surveillance data demands dedicated regulatory affairs personnel that mid-cap ophthalmic device firms struggle to recruit and retain.
- Autoclave sterilization validation:Transition from ethylene oxide to steam sterilization methods for silicone-based rings requires extensive packaging redesign and material stability testing that extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsular Tension Rings Market |
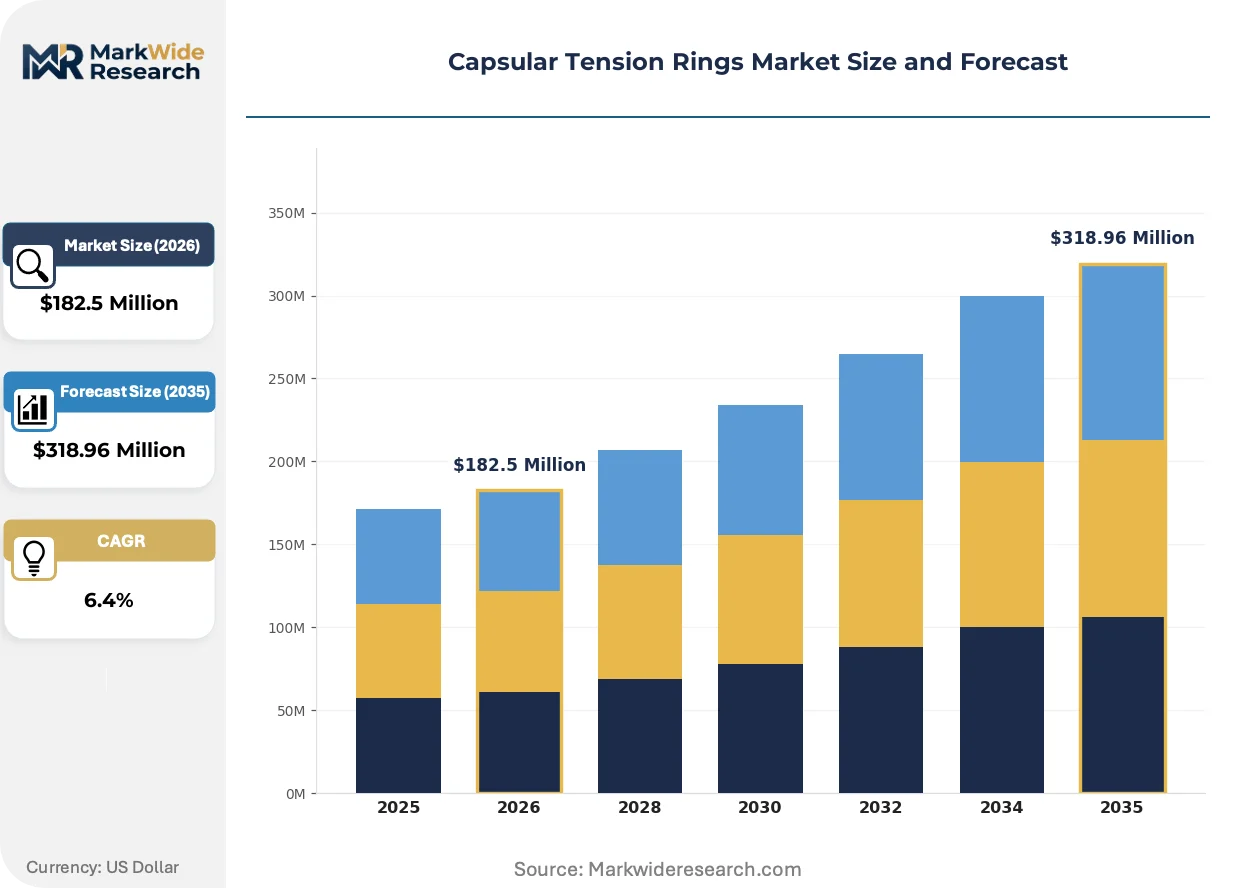
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $318.96 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Rings, PMMA Rings, Hydrophobic Rings, Hydrophilic Rings End User: Ocular Surgeons, Hospitals, Eye Clinics, Ambulatory Surgery Centers Application: Cataract Surgery, Glaucoma Treatment, Refractive Surgery, Lens Implantation Distribution Channel: Online Retail, Medical Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Alcon Laboratories, Morcher GmbH, Ophtec BV, Bausch & Lomb Incorporated, Carl Zeiss Meditec AG, FCI Ophthalmics, Johnson & Johnson Vision, Biotech Visioncare, Rayner Intraocular Lenses Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsular Tension Rings Market Strategic Shifts
Material science advances and regulatory harmonization pressures are converging to reshape capsular tension ring design priorities, with surface modification technologies and automated manufacturing processes gaining traction among premium segment suppliers.
Hydrophobic surface coatings are expanding into capsular tension ring applications to reduce postoperative inflammatory response and posterior capsular opacification incidence. Academic medical centers in Germany and Japan are piloting these modified PMMA devices for diabetic cataract patients with compromised blood-aqueous barriers. The technology is expanding into premium cataract segments where reduced Nd:YAG capsulotomy rates justify higher device costs.
MDR Article 10 clinical evaluation requirements are mandating systematic literature reviews and post-market clinical follow-up studies for all intraocular device modifications. Manufacturers must now generate procedure-specific evidence for zonular-compromised indications rather than relying on predicate device equivalence. German notified bodies are enforcing this most strictly, causing portfolio rationalization among suppliers lacking dedicated clinical affairs infrastructure.
Ambulatory surgery center procurement consolidation is compressing vendor negotiation cycles and standardizing device specifications across multi-facility networks. Large US ophthalmology platforms are replacing individual surgeon preference cards with system-wide formularies that designate single-source tension ring suppliers. This pattern is most visible in Florida and Texas markets where private equity-backed practice aggregation has concentrated surgical volume among fewer purchasing entities.
Capsular Tension Rings Market Segmentation
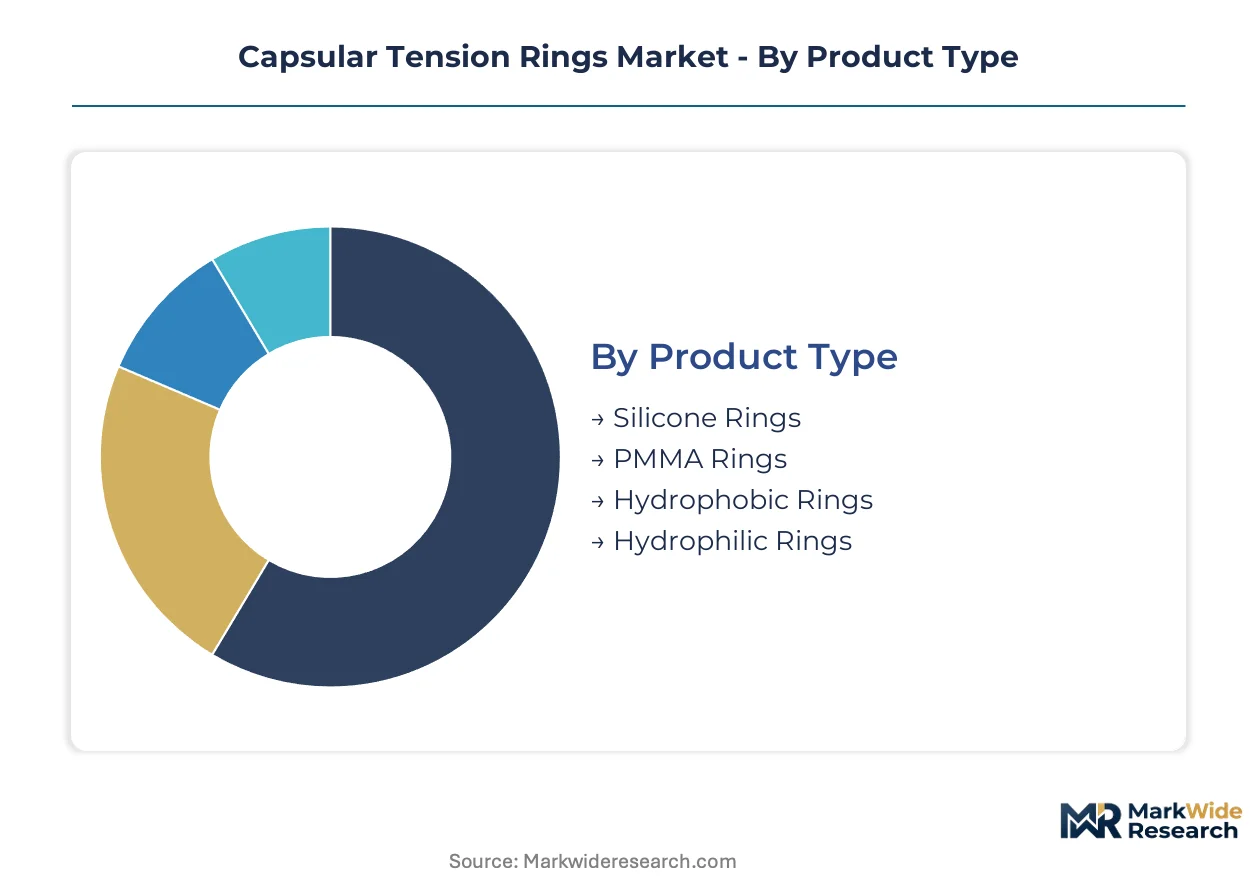
Segmentation in capsular tension rings reflects divergent surgical workflows across facility types and material preferences shaped by biocompatibility requirements. Surgeons select ring compositions based on patient zonular integrity, while procurement channels consolidate around institutional purchasing power.
Product Type:
Material selection separates cost-sensitive high-volume providers from academic centers prioritizing surface engineering.
- PMMA Rings:Polymethyl methacrylate devices dominate procedural volume through established biomechanical reliability and surgeon familiarity across German and Japanese academic medical centers. Medicare-covered cataract volumes in the United States sustain demand despite limited flexibility in insertion.
- Silicone Rings:Elastomeric construction permits compression during insertion and expansion within the capsular bag, attracting adoption in complex zonular dialysis cases. PMDA's distinct pharmaceutical-medical device classification standards for silicone variants impose redundant testing protocols that extend Japanese market entry timelines.
- Hydrophobic Rings:Surface-modified devices reduce posterior capsular opacification incidence in diabetic cataract patients with compromised blood-aqueous barriers.
- Hydrophilic Rings:Proprietary surface technologies from Dutch manufacturers minimize postoperative inflammatory response in premium cataract segments.
Volume sits with PMMA Rings; growth tilts toward Hydrophobic Rings.
End User:
Facility infrastructure determines device specification complexity and reimbursement capture.
- Ambulatory Surgery Centers:High-throughput cataract workflows in Florida and Texas drive standardization on single-source tension ring suppliers through private equity-backed practice aggregation. System-wide formularies replace individual surgeon preference cards, compressing vendor negotiation cycles.
- Hospitals:Academic medical centers in Germany and Japan pilot hydrophobic surface coatings for complex cases, sustaining demand for premium device geometries.
- Ocular Surgeons:Individual practitioners in smaller markets retain preference-based purchasing for specific ring diameters and cross-sectional profiles.
- Eye Clinics:Urban specialty practices concentrate refractive surgery applications where tension ring utilization remains comparatively nascent.
Procurement concentrates at Ambulatory Surgery Centers; capability differentiation persists at Hospitals.
Application:
Procedural indication dictates ring sizing and implantation technique.
- Cataract Surgery:Phacoemulsification platform advancement in German and Japanese centers elevates surgical precision requirements that favor standardized tension ring geometries for zonular-compromised eyes.
- Glaucoma Treatment:Minimally invasive glaucoma surgery integration with phacoemulsification workflows creates demand for modified ring geometries that accommodate angle-based stent placement.
- Refractive Surgery:Lens implantation applications in premium segments utilize tension rings for toric intraocular lens stabilization.
- Lens Implantation:Secondary lens procedures in post-vitrectomy eyes require specialized ring designs for compromised capsular support.
Cataract Surgery commands installed base; Glaucoma Treatment expands most quickly through combination procedure adoption.
Distribution Channel:
Channel selection reflects order scale and regulatory documentation requirements.
- Medical Distributors:Regional ophthalmic supply networks dominate inventory placement for ambulatory surgery center chains, consolidating procurement across multi-facility networks in Maharashtra and Tamil Nadu surgical camps.
- Direct Sales:Manufacturer field representatives support German notified body compliance documentation and sterilization validation protocols for institutional accounts.
- Online Retail:Limited penetration for consumable ophthalmic devices due to sterile packaging integrity requirements and temperature-controlled logistics.
- Specialty Stores:Niche presence in optometric practice supply for anterior segment diagnostic equipment bundling.
Medical Distributors capture volume scale; Direct Sales secures compliance-intensive accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr Valley ophthalmic device manufacturing clusters anchor European supply chains for capsular tension rings, while aging surgical volumes in specific metropolitan markets reshape demand geography across three continents.
United States
Medicare-covered cataract volumes sustain procedural demand for zonular stabilization devices, particularly in Florida and Texas where private equity-backed practice aggregation concentrates purchasing power. FDA 510(k) clearance pathways govern market access with intensifying scrutiny of biocompatibility documentation. Dallas-Fort Worth ambulatory surgery center chains standardize on single-source tension ring suppliers through system-wide formularies.
Germany
Academic medical centers in Berlin and Munich pilot hydrophobic surface coatings for diabetic cataract patients with compromised blood-aqueous barriers. EU Medical Device Regulation conformity assessment frameworks for Class IIb devices consolidate supplier bases toward established manufacturers with robust quality management systems. Stuttgart-area engineering clusters specialize in custom tension ring geometries for complex zonular dialysis cases.
Japan
Super-aged society demographics sustain procedural demand for capsular tension rings in zonular-compromised eyes across Kanto and Kansai regions. PMDA maintains distinct pharmaceutical and medical device classification standards for silicone-based variants that extend market entry timelines. Nagoya academic medical centers elevate surgical precision requirements through femtosecond laser-assisted cataract surgery adoption.
India
Government-funded blindness elimination programs in Maharashtra and Tamil Nadu present volume opportunities for cost-optimized tension ring designs adapted to high-throughput manual small-incision techniques. CDSCO regulates intraocular device imports with localized testing protocols for silicone variants. Chennai private hospital chains consolidate procurement across multi-facility networks for surgical camp deployments.
Capsular Tension Rings Market Competitive Environment
The competitive structure tilts toward vertically integrated ophthalmic multinationals with captive polymer processing capabilities. German engineering specialists and Dutch surface technology firms occupy distinct premium niches against scale-driven American suppliers. Strategic archetypes include PMMA manufacturing generalists, silicone elastomer specialists, and hydrophilic coating innovators. Competitive moves concentrate on sterilization validation protocol transitions and MDR technical documentation consolidation.
Among German GmbH-structured engineering houses, Morcher GmbH exemplifies the custom geometry specialist archetype, while Ophtec BV represents Dutch surface technology differentiation through proprietary hydrophilic platforms. Alcon Laboratories anchors the scale-driven multinational tier with vertically integrated manufacturing footprints spanning multiple regulatory jurisdictions.
| Leading Market Players |
|---|
| Alcon Laboratories |
| Morcher GmbH |
| Ophtec BV |
| Bausch & Lomb Incorporated |
| Carl Zeiss Meditec AG |
| FCI Ophthalmics |
| Johnson & Johnson Vision |
| Biotech Visioncare |
| Rayner Intraocular Lenses Limited |
| Others |
Value Chain & Pricing Dynamics
Optical-grade polymethyl methacrylate spot indices cascade through capsular tension ring manufacturing tiers, compressing margins at standard-grade producers while premium hydrophobic-coated variants retain pricing power through surgeon preference stickiness in German and Japanese academic centers.
Pricing Analysis
Outcome-linked pricing anchors capsular tension ring procurement, with hydrophobic surface coatings commanding premiums tied to reduced Nd:YAG capsulotomy rates in diabetic cataract populations. Three-tier pricing structure across premium, standard, and economy levels separates hydrophilic-coated devices from bare PMMA rings from manual small-incision camp variants. Cost compression in economy tiers intensifies because Indian government tenders prioritize unit cost over surface engineering. Ambulatory surgery center chains exhibit highest price sensitivity through formulary standardization, while academic medical centers demonstrate lowest sensitivity when piloting novel surface modifications.
Supply Chain Analysis
Temperature-controlled air freight from Ruhr Valley polymer processors to Stuttgart-area device manufacturers absorbs disproportionate landed cost share for silicone-based variants requiring sterile packaging integrity. Germany, Japan, and the United States anchor optical-grade PMMA supply through specialized chemical processors. Raw material dependencies draw from methacrylate monomer feedstocks, platinum-cured silicone elastomers, and hydrophilic coating polymers. Single-source vulnerability concentrates in European optical-grade resin qualification protocols. Distribution runs through regional ophthalmic supply networks consolidating multi-facility ambulatory surgery center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capsular tension rings occupy a material-transition inflection as hydrophobic surface coatings displace bare PMMA in premium cataract workflows, forcing portfolio reallocation across manufacturing footprints.
For Market Incumbents: Hedge silicone biocompatibility documentation burdens by accelerating PMMA hydrophobic coating R&D pipelines before PMDA classification standards harden further. Alcon Laboratories and Morcher GmbH should reinforce German notified body relationships through dedicated clinical affairs infrastructure, as MDR Article 10 technical documentation demands consolidate supplier bases toward quality-system-mature incumbents. Backward integration into captive optical-grade resin processing defends margin position against Asian chemical processor volatility. For New Entrants and Emerging Players: Medical distributors in Maharashtra and Tamil Nadu present the most penetrable channel for cost-optimized manual small-incision designs, as Indian government blindness elimination programs prioritize volume throughput over premium surface engineering. Refractive surgery applications remain comparatively nascent white-space territory where toric intraocular lens stabilization protocols lack standardized tension ring geometries. A focused go-to-market angle targets private hospital chain procurement consolidation in Chennai and Hyderabad, bypassing entrenched multinational GPO contracts in developed markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap German engineering houses with MDR-compliant quality systems but strained clinical affairs staffing, as EU notified body backlogs force portfolio rationalization among under-resourced specialists. Long-term viability over the projection horizon rests on surface modification patent estates and sterilization validation protocol transitions from ethylene oxide to steam methods. The signal to watch is PMDA silicone classification standard harmonization with global norms, which would collapse 18-24 month market entry penalties and revalue Japanese distribution capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Consolidation | EU notified body enforcement of Article 10 clinical evaluation requirements filters supplier bases toward quality-system-mature manufacturers with dedicated regulatory infrastructure. |
| Hydrophobic Surface Coating Development | Modified PMMA devices reduce posterior capsular opacification incidence in diabetic cataract patients with compromised blood-aqueous barriers. |
| Sterilization Protocol Transition | Steam sterilization validation for silicone-based rings requires extensive packaging redesign and material stability testing that extends product development cycles. |
| Indian Surgical Camp Volume Entry | Government-funded blindness elimination programs in Maharashtra and Tamil Nadu present procurement scale for cost-optimized tension ring designs adapted to manual small-incision techniques. |
| MIGS Device Integration R&D | Modified ring geometries accommodating angle-based stent placement without capsular distortion capture combination procedure growth in glaucoma-cataract workflows. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with cataract surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA pharmaceutical-medical device classification registers, and CDSCO import testing protocols supplied regulatory pathway intelligence. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Segment-level granularity modeled material composition, end-user facility type, procedural indication, and regional regulatory cluster as core dimensions. CAGRs derived from procedure volume elasticity to aging demographic projections, phacoemulsification platform adoption curves, and reimbursement code differentiation for zonular-compromised cases. Forecast inputs incorporated femtosecond laser-assisted cataract surgery penetration rates and ambulatory surgery center procurement consolidation patterns.
Several conditions sit outside the modeled scope, including unforeseen EU MDR implementation delays, raw material supply disruptions from optical-grade resin processors, and reimbursement recoding for complex cataract procedures. Forecasts reflect assumptions about surgeon training adoption rates for modified ring geometries and sterilization validation timeline completion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Casting Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Neuromodulation Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Platelet Concentration Systems Market