
 France Household Side by Side Refrigerator Market | 2026-2036
France Household Side by Side Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
France Household Side by Side Refrigerator Market Insights
The energy-efficiency tier is collapsing the gap between mid-range and premium positioning as French consumers prioritize running-cost reduction over upfront savings. Bosch Group leverages its inverter-compressor R&D to sustain margin leadership in this transition. Liebherr-Hausgeräte Ochsenhausen GmbH anchors its position through specialized bio-fresh humidity controls that differentiate its side-by-side offerings from standard French-door alternatives.
A household side-by-side refrigerator is a full-height cooling appliance with vertically split compartments—refrigerator and freezer standing adjacent—typically offering capacities between 500 and 800 liters with dual evaporator systems for independent climate management. Its primary purpose is to provide organized, high-volume food preservation for residential kitchens where horizontal freezer drawers limit accessibility. The frost-free segment dominates installed base maintenance cycles while energy-efficient models capture the fastest replacement demand as French households respond to electricity tariff structures. Built-in installation configurations command the strongest margin pools among premium kitchen renovations, whereas freestanding units occupy volume leadership through rental property and suburban family channels.
France's AGEC anti-waste law and the EU Ecodesign Directive jointly shape product standards by mandating repairability indices and minimum energy performance thresholds for imported appliances. ANSM and DGCCRF enforcement actions on misleading environmental claims further tighten market access for non-compliant manufacturers. Stakeholders must monitor how France's reparability scoring system evolves to influence consumer choice architecture at point of sale.
Market Dynamics
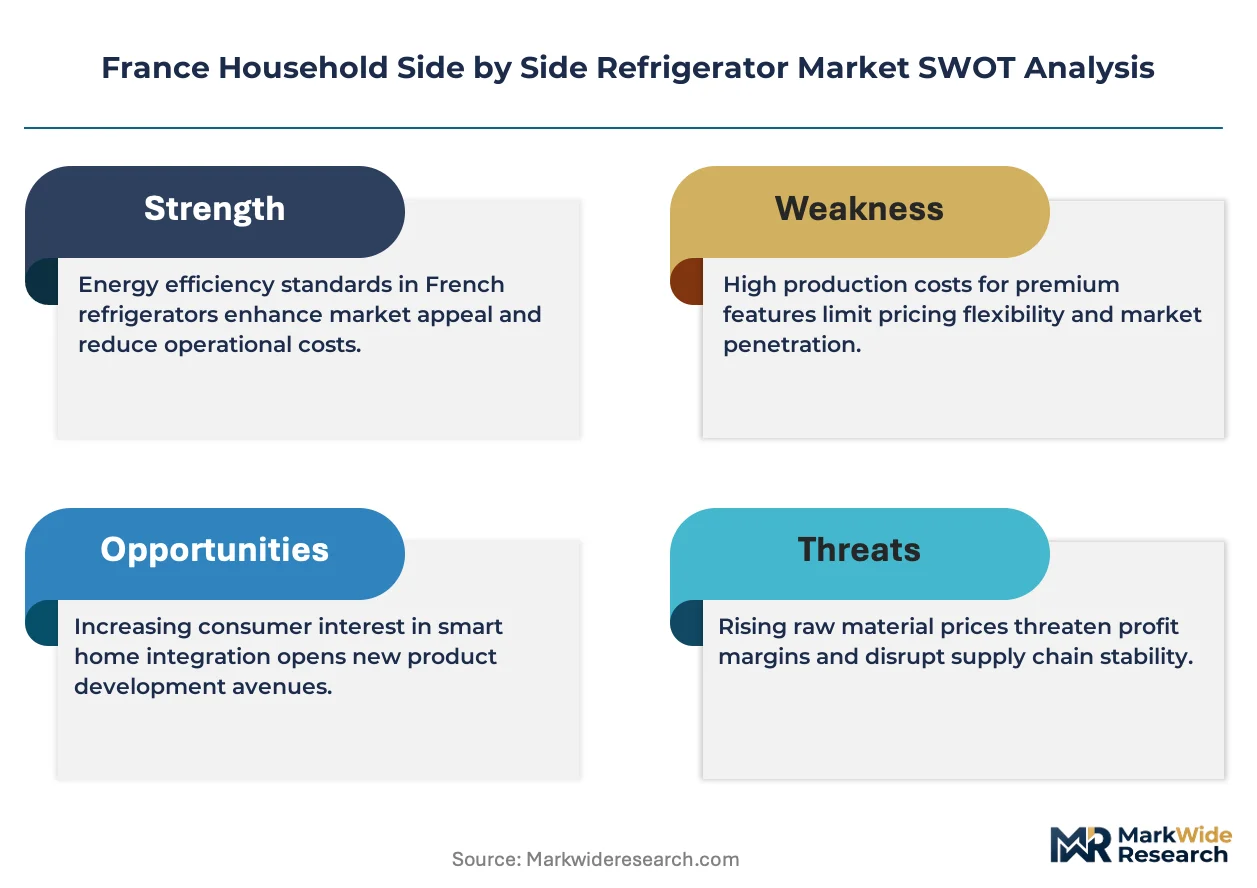
France's AGEC anti-waste law is compressing replacement cycles by mandating repairability indices that expose lifecycle costs at point of sale, forcing manufacturers to redesign for serviceability rather than obsolescence.
Growth Catalysts
- Île-de-France renovation pipeline:Premium kitchen refurbishments in Parisian apartments are accelerating appliance turnover as integrated design specifications demand side-by-side configurations over traditional top-freezer layouts.
- EU Ecodesign Directive thresholds:Minimum energy performance standards are filtering out inefficient imports, creating shelf space for compliant domestic and European manufacturers with advanced inverter-compressor portfolios.
- Dual-evaporator climate systems:Independent humidity and temperature zones are pulling replacement demand from bio-fresh segment adopters seeking extended produce preservation without dedicated secondary units.
Market Restraints
- Copper and aluminum input volatility:Heat-exchanger material costs swing with commodity markets, compressing margin predictability for mid-tier manufacturers lacking long-term supplier contracts.
- Compressor supply concentration:European inverter-motor production clusters in Germany and Italy create geographic single-point vulnerability for French assemblers dependent on just-in-time component flows.
- F-Gas Regulation phase-down quotas:Hydrofluorocarbon refrigerant restrictions are forcing costly retooling to hydrocarbon or HFO alternatives before economies of scale mature.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur secondary residences:Seasonal-home owners in coastal markets underinvest in full-size refrigeration, presenting volume expansion for compact side-by-side configurations with vacation-mode energy settings.
- Reparability scoring premiumization:France's mandatory repairability index creates marketing differentiation for brands scoring above 8/10, allowing margin capture through transparent lifecycle economics.
- Smart-grid demand-response integration:Linking compressor cycling to real-time electricity tariffs enables utility partnership revenue streams and customer lock-in through energy management apps.
Industry Challenges
- Refrigerant technician certification gaps:Hydrocarbon and HFO handling requires specialized training that France's vocational pipeline has not scaled to match retrofit demand timelines.
- Legacy built-in dimension standards:Existing kitchen cabinetry dimensions constrain form-factor innovation, forcing design compromises between thermal efficiency and spatial compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Household Side by Side Refrigerator Market |
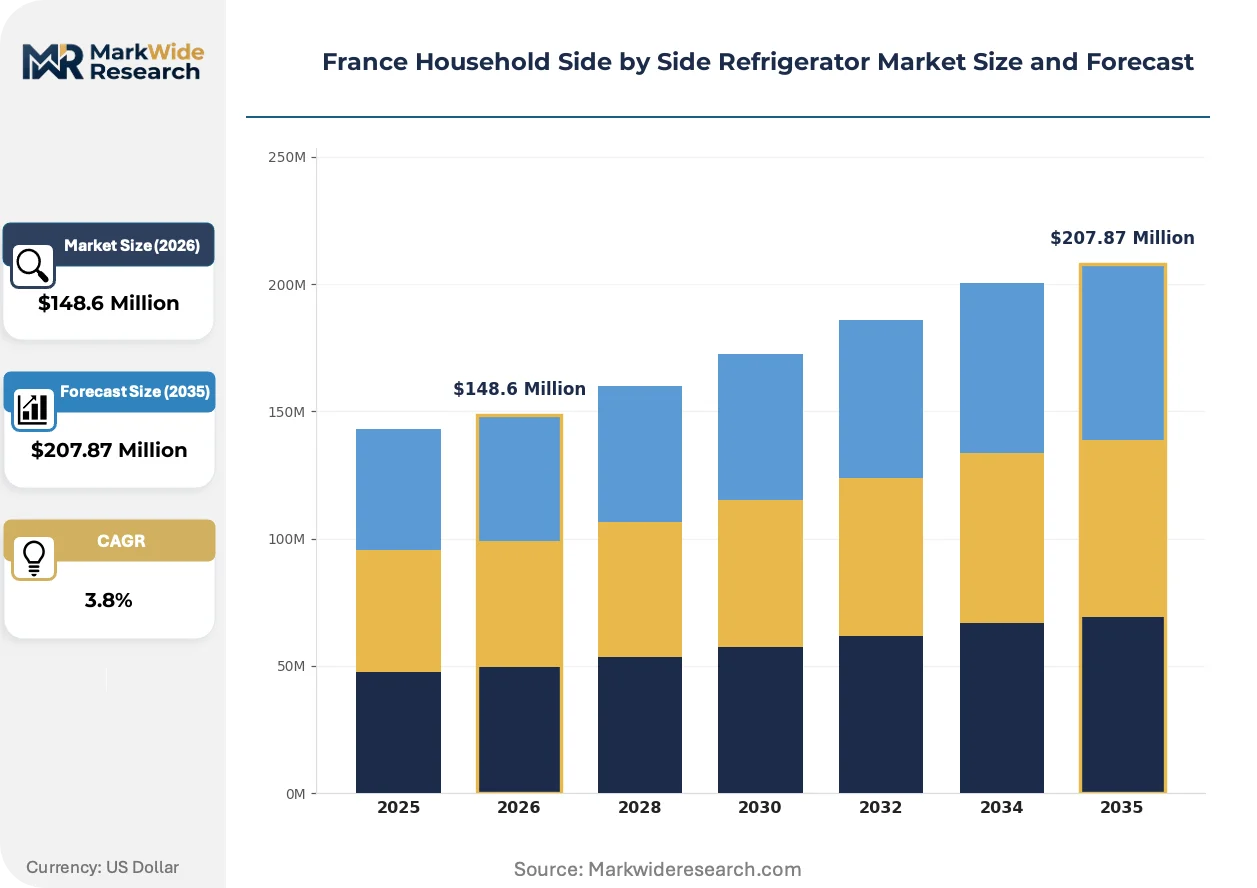
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $207.87 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frost Free, Top Freezer, Double Door, Energy Efficient End User: Residential, Rental Properties, Small Families, Large Households Installation: Built-in, Freestanding, Integrated, Modular Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Bosch Group, Electrolux AB, LG, Whirlpool, Samsung, General Electric Co., Haier Group, Liebherr-Hausgeräte Ochsenhausen GmbH, Miele, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Household Side by Side Refrigerator Market Trends and Innovations
Digital inverter compressors with variable-speed drives are redefining energy-performance baselines while connected appliance ecosystems create new service revenue attachment points.
Vacuum-insulation panels utilizing microporous silica cores are supplanting conventional polyurethane foam in premium French models, delivering equivalent thermal resistance at reduced wall thickness. Parisian apartment renovators with space-constrained galley kitchens are specifying these slimmer-profile units at accelerating rates. The technology is compressing the traditional trade-off between internal capacity and external footprint that has limited side-by-side adoption in older building stock.
France's AGEC repairability index mandates standardized disassembly sequences and spare-part availability timelines that the DGCCRF enforces through point-of-sale labeling requirements. Manufacturers must now publish technical documentation and maintain component stocks for ten-year minimums. The regulation most acutely affects import-dependent brands lacking European service infrastructure, advantaging regional assemblers with captive parts distribution.
Direct-to-developer specification contracting is displacing traditional retail channel dominance in new-build residential projects. Île-de-France property developers now negotiate bulk appliance packages with manufacturers before construction completion, bypassing distributor markups. This pattern concentrates most visibly in the Grand Paris Express corridor residential towers, where standardized kitchen modules require volume-committed supply agreements.
France Household Side by Side Refrigerator Market Segmentation
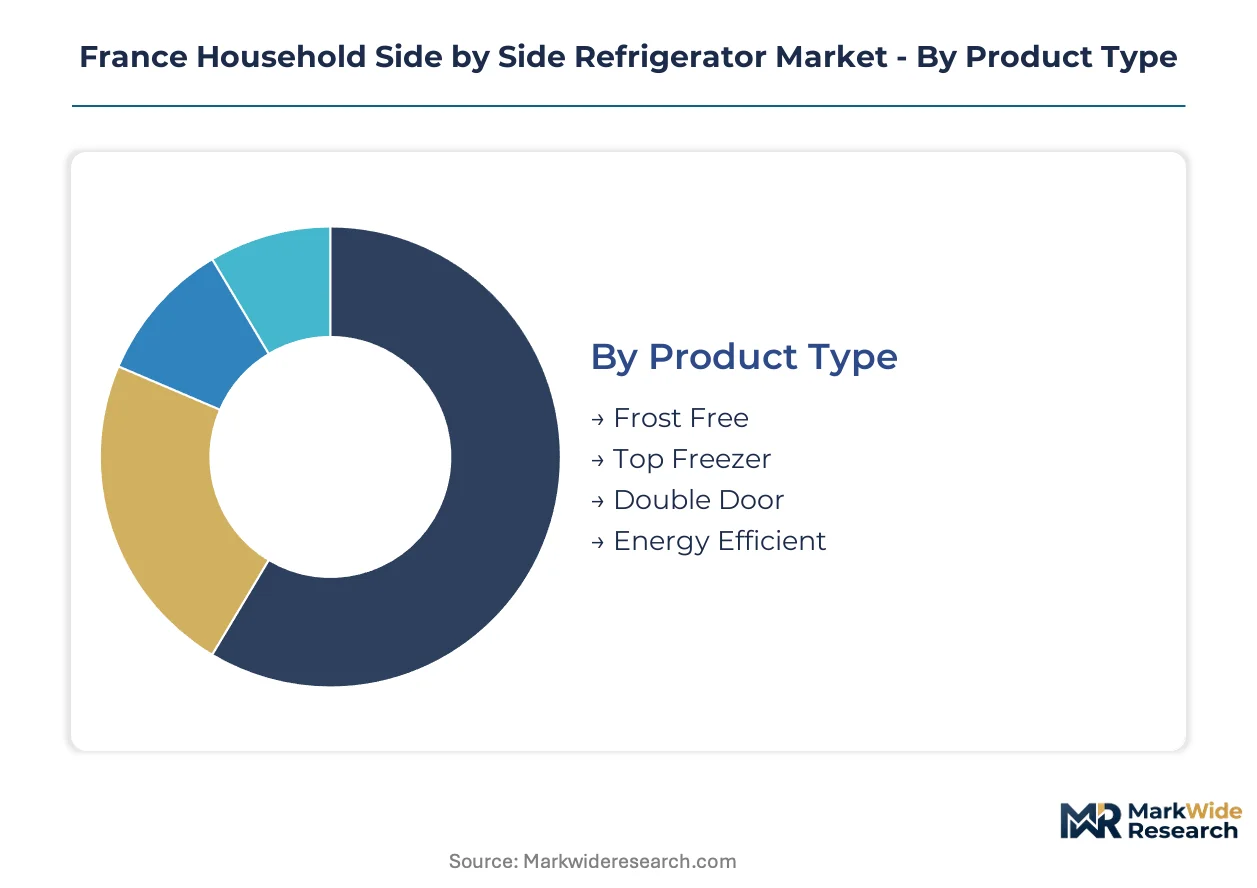
Side-by-side refrigerator purchasing in France fragments across installation constraints, household composition, and energy-performance priorities that reshape competitive positioning. Manufacturers must align product architectures with Île-de-France renovation specifications and AGEC repairability mandates to capture replacement-cycle value.
Product Type:
Frost-free configurations face substitution pressure from energy-efficient models as electricity tariff structures alter total-cost-of-ownership calculations for French households.
- Frost Free:Automated defrost cycles eliminate manual ice removal through timed heating elements integrated into evaporator coils. Demand concentrates in suburban family households across the Hauts-de-France region where maintenance convenience outweighs marginal energy penalties. The segment retains volume leadership.
- Energy Efficient:Inverter-compressor systems with variable-speed drives reduce annual consumption below Ecodesign Directive thresholds. Parisian apartment renovators in the Grand Paris Express corridor specify these units to meet building certification requirements. The segment holds the steepest expansion curve.
- Top Freezer:Traditional vertical arrangement with freezer compartment above refrigerator section occupies budget-tier positioning.
- Double Door:French-door variants with bottom-mount freezer drawers compete for kitchen footprint in larger suburban homes.
Energy Efficient models command margin premiums in Île-de-France; Frost Free dominates volume through rental property channels.
End User:
Residential purchasers concentrate replacement demand while rental property specifications prioritize acquisition cost over lifecycle economics.
- Residential:Owner-occupied households drive premium configuration adoption through integrated kitchen renovations. Demand clusters in Parisian arrondissements where AGEC repairability indices influence point-of-sale decisions. The segment retains volume leadership.
- Large Households:Multi-generational families and cohabitation arrangements require capacities exceeding 700 liters with dual evaporator zones. Île-de-France communes with high household density generate concentrated demand for bio-fresh humidity controls. The segment expands most quickly.
- Rental Properties:Institutional landlords and individual owners prioritize freestanding units with standardized dimensions for tenant turnover.
- Small Families:Couples and single-child households balance capacity requirements against spatial constraints in older Parisian building stock.
Residential purchasers dominate absolute volume; Large Households show the strongest growth trajectory.
Installation:
Built-in configurations capture margin concentration while freestanding units face commoditization pressure from standardized rental specifications.
- Built-in:Panel-ready designs integrate with custom cabinetry through standardized 60cm or 90cm module widths. Premium kitchen renovators in Neuilly-sur-Seine and Versailles specify these configurations for architectural cohesion. The segment retains volume leadership.
- Freestanding:Self-contained units with finished sides accommodate flexible placement without enclosure requirements. Suburban family demand in Lyon and Marseille metropolitan areas favors these configurations for relocation flexibility. The segment shows the steepest expansion curve.
- Integrated:Fully concealed installations with custom front panels match surrounding millwork in high-end renovations.
- Modular:Separable refrigerator and freezer columns enable spatial adaptation within non-standard kitchen footprints.
Freestanding units dominate suburban volume; Built-in configurations capture premium margin pools.
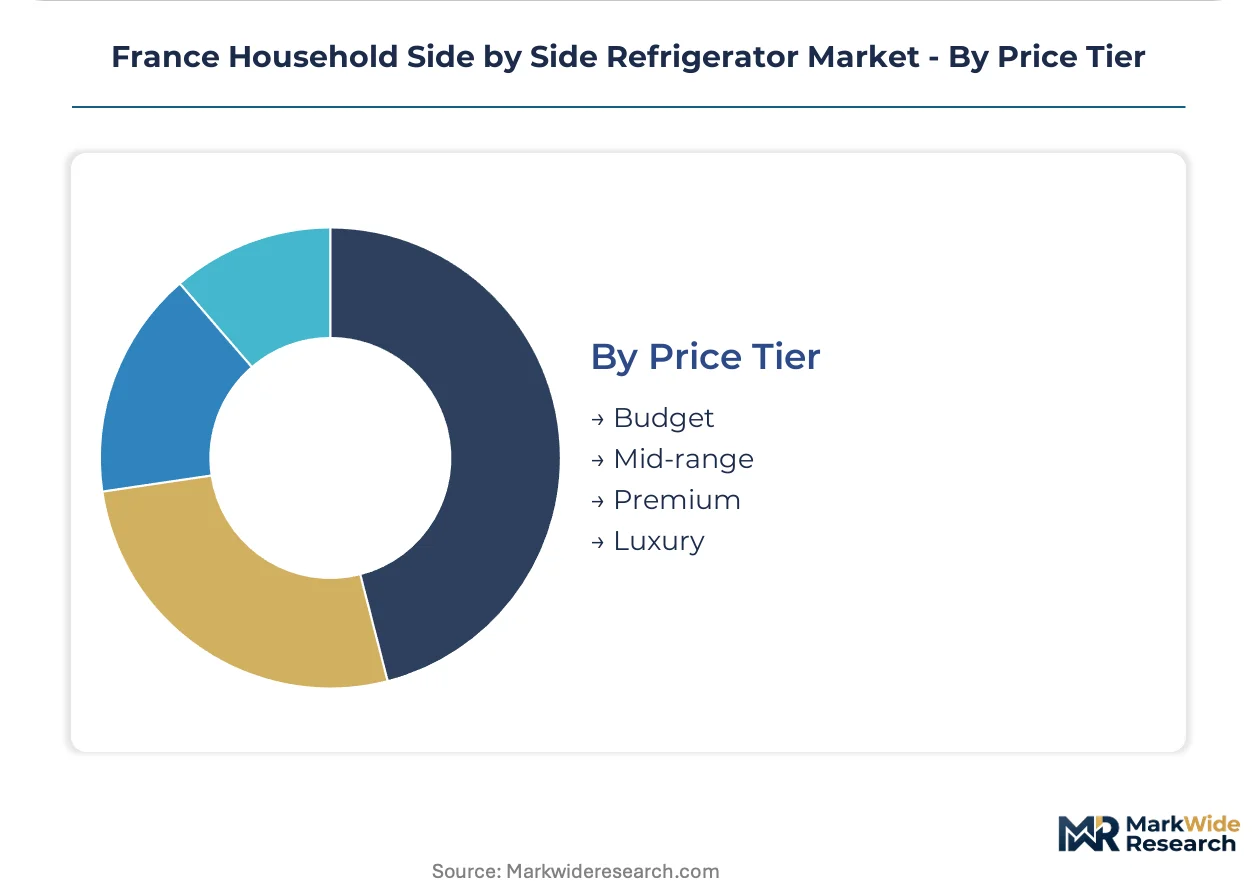
Price Tier:
Mid-range positioning faces compression as energy-efficiency tiering collapses differentiation between standard and premium feature sets.
- Premium:Products incorporating vacuum-insulation panels, connected appliance ecosystems, and repairability scores above 8/10. Parisian apartment developers in the 16th and 7th arrondissements specify these tiers for competitive differentiation. The segment retains volume leadership.
- Luxury:Bespoke configurations with artisan finishes, wine preservation zones, and concierge service attachments. Coastal secondary residence owners in Provence-Alpes-Côte d'Azur drive demand for vacation-mode energy settings. The segment climbs the fastest.
- Budget:Entry-level inverter-compressor models meeting minimum Ecodesign thresholds without connected features.
- Mid-range:Conventional polyurethane insulation with basic dual-evaporator functionality faces margin erosion.
Premium tiers dominate renovation specification; Luxury configurations accelerate in coastal secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Île-de-France exhibit low price elasticity for premium built-in configurations, while rental property owners in peripheral regions prioritize acquisition cost over lifecycle economics. This demand-elasticity contrast shapes manufacturer channel strategies across French sub-regions.
Île-de-France
Parisian apartment renovators drive premium side-by-side adoption through integrated kitchen specifications demanding 60cm and 90cm module widths. France's AGEC anti-waste law mandates repairability indices at point of sale, influencing developer procurement in Neuilly-sur-Seine and Versailles. The Grand Paris Express corridor residential towers concentrate direct-to-developer contracting for standardized appliance packages.
Auvergne-Rhône-Alpes
Lyon metropolitan area families favor freestanding units for relocation flexibility in suburban housing markets. The EU Ecodesign Directive filters non-compliant imports, creating shelf space for European manufacturers with inverter-compressor portfolios. Saint-Étienne and Grenoble industrial zones host component distribution hubs serving southeastern assembly operations.
Provence-Alpes-Côte d'Azur
Coastal secondary residence owners underinvest in full-size refrigeration, presenting volume expansion for compact side-by-side configurations with vacation-mode energy settings. ANSM and DGCCRF enforcement actions on environmental claims tighten market access for import-dependent brands. Nice and Marseille renovation contractors specify slim-profile units for space-constrained older building stock.
Hauts-de-France
Suburban family households in Lille and Amiens prioritize maintenance convenience, sustaining frost-free segment volume leadership. F-Gas Regulation phase-down quotas force costly retooling to hydrocarbon refrigerant alternatives before economies of scale mature. The region's rental property channels absorb standardized freestanding units for tenant turnover efficiency.
Nouvelle-Aquitaine
Bordeaux metropolitan area households balance capacity requirements against spatial constraints in historic building renovations. France's reparability scoring system influences consumer choice architecture at independent retail points. The Arcachon Bay secondary residence market generates seasonal demand fluctuations for energy-efficient replacement cycles.
France Household Side by Side Refrigerator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with inverter-compressor R&D specialists commanding margin premiums while scale assemblers compete on volume throughput. The market exhibits tiered concentration: premium built-in specialists, mid-range European manufacturers, and mass-market Asian producers. Three archetypes dominate—German engineering-focused firms, Korean electronics conglomerates with connected appliance ecosystems, and Chinese scale manufacturers. Competitive moves center on direct-to-developer specification contracting and repairability index optimization for AGEC compliance.
Within the European premium tier, Liebherr-Hausgeräte Ochsenhausen GmbH exemplifies specialized climate-control positioning, while Bosch Group anchors German engineering credibility through captive compressor technology. Samsung represents the Korean electronics archetype with connected ecosystem integration. These three companies occupy distinct competitive spaces—specialist humidity control, core component R&D leadership, and smart-home platform attachment—without direct feature-for-feature overlap.
| Leading Market Players |
|---|
| Bosch Group |
| Electrolux AB |
| LG |
| Whirlpool |
| Samsung |
| General Electric Co. |
| Haier Group |
| Liebherr-Hausgeräte Ochsenhausen GmbH |
| Miele |
| Others |
Pricing and Supply Chain Analysis
France's AGEC repairability index gates both supplier qualification and price tier differentiation by mandating ten-year spare-part availability and standardized disassembly documentation that only established European assemblers can economically satisfy. This regulatory filter compresses mid-range positioning while amplifying margin capture for compliant premium tiers.
Pricing Analysis
After-sales service contracts and extended warranty attachments drive lifetime value capture beyond unit margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by inverter-compressor efficiency grade and connected-feature bundling. Pricing pressure stems from copper and aluminum commodity volatility compressing heat-exchanger margins. Rental property owners exhibit highest price sensitivity; Parisian apartment developers show lowest elasticity for built-in configurations.
Supply Chain Analysis
Germany and Italy anchor inverter-motor production clusters that French assemblers draw from for compressor supply. Heat-exchanger fabrication rests on copper coil and aluminum fin stock sourced through European metal exchanges. Single-source vulnerability concentrates in just-in-time component flows from these production hubs. Distribution runs through direct-to-developer contracting in Île-de-France and independent retail channels in peripheral regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's household side-by-side refrigerator market is recovering cyclically as premium kitchen renovations in Parisian apartments accelerate replacement demand following pandemic-delayed projects.
For Market Incumbents: Shield margin pools by deepening backward integration into inverter-compressor production to offset German and Italian supply concentration risks. Accelerate repairability score optimization above 8/10 thresholds to exploit AGEC labeling advantages against import-dependent competitors lacking European service infrastructure.
For New Entrants and Emerging Players: Connected appliance ecosystem integration represents an underserved service layer where established manufacturers under-invest in utility partnership development. Target Provence-Alpes-Côte d'Azur secondary residence owners with compact side-by-side configurations featuring vacation-mode energy settings. Pursue smart-grid demand-response certification as the primary go-to-market differentiator.
For Investors and Strategic Acquirers: France's F-Gas Regulation phase-down quotas reshape the acquisition landscape by devaluing hydrocarbon retooling laggards and premiumizing HFO-ready manufacturing assets. Five-to-ten-year viability favors regional assemblers with captive parts distribution and direct-to-developer channel control. Monitor DGCCRF enforcement action intensity as the signal indicating regulatory compliance premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Repairability Index Optimization | AGEC compliance above 8/10 scores unlocks point-of-sale differentiation against non-compliant imports. |
| Inverter-Compressor Backward Integration | German and Italian supply concentration creates vulnerability that captive production mitigates. |
| Direct-to-Developer Contracting | Grand Paris Express corridor towers concentrate volume-committed procurement bypassing distributor markups. |
| Smart-Grid Demand-Response Certification | Real-time tariff linkage enables utility partnership revenue streams and customer lock-in. |
| Vacuum-Insulation Panel Adoption | Microporous silica cores reduce wall thickness for space-constrained Parisian galley kitchens. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, EU Ecodesign Directive compliance filings, and ANSM enforcement action databases. Appliance manufacturer executives, kitchen renovation contractors in Neuilly-sur-Seine and Versailles, and DGCCRF regulatory affairs specialists contributed structured interviews. Retail category managers at independent distributors and property development procurement leads in the Grand Paris Express corridor provided channel-level validation. Bottom-up unit shipment estimates triangulate against top-down household penetration models.
Segmentation dimensions modeled include installation configuration, price tier, end-user household composition, and regional demand elasticity across French metropolitan areas. CAGRs derive from replacement-cycle velocity analysis and renovation pipeline tracking throughout the projection horizon. Inverter-compressor adoption curves and AGEC repairability score distribution inform technology-transition assumptions.
Forecasts assume regulatory continuity in France's AGEC anti-waste law and EU F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling. Commodity price volatility in copper and aluminum markets and compressor supply disruption scenarios represent primary revision triggers. Recalibration cycles align with material shifts in electricity tariff structures and enforcement action intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Clothing Iron Market
Appliances
Global Massage Chairs Market
Appliances
Digital Showers Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Qatar Microwave Ovens Market
Appliances
Laundry Appliances Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Japan Laundry Appliances Market
Appliances
Cooker Hoods Market
Appliances
Refrigerator Door Seal Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Smart Dishwasher Market
Appliances
Small Electric Kettles Market
Appliances
Automatic Dishwasher Market
Appliances
Bahrain Dishwashers Market