
 Coffee Beauty Products Market | 2026-2036
Coffee Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Beauty Products Market Analysis
Subscription-based replenishment models for coffee-infused skincare routines is realigning how brands capture lifetime value. L'Oréal leverages its dermatological testing infrastructure to anchor premium positioning for caffeine-based eye serums. mCaffeine specializes in vegan-certified coffee scrubs that dominate India's direct-to-consumer channel. Estée Lauder extends its prestige distribution network to place cold-brew extract formulations in travel retail.
Coffee beauty products incorporate roasted Coffea arabica or Coffea canephora extracts standardized for chlorogenic acid and caffeine content, typically formulated at concentrations between one and five percent to deliver antioxidant and vasoconstrictive benefits for topical application. Skincare applications lead volume as under-eye treatments and cellulite creams command the highest per-unit margins, while haircare masks represent the fastest-expanding category driven by scalp circulation claims. Scrubs within the product type dimension occupy the mass-market entry point, whereas oils concentrate in professional spa channels where service pricing supports premium extraction grades.
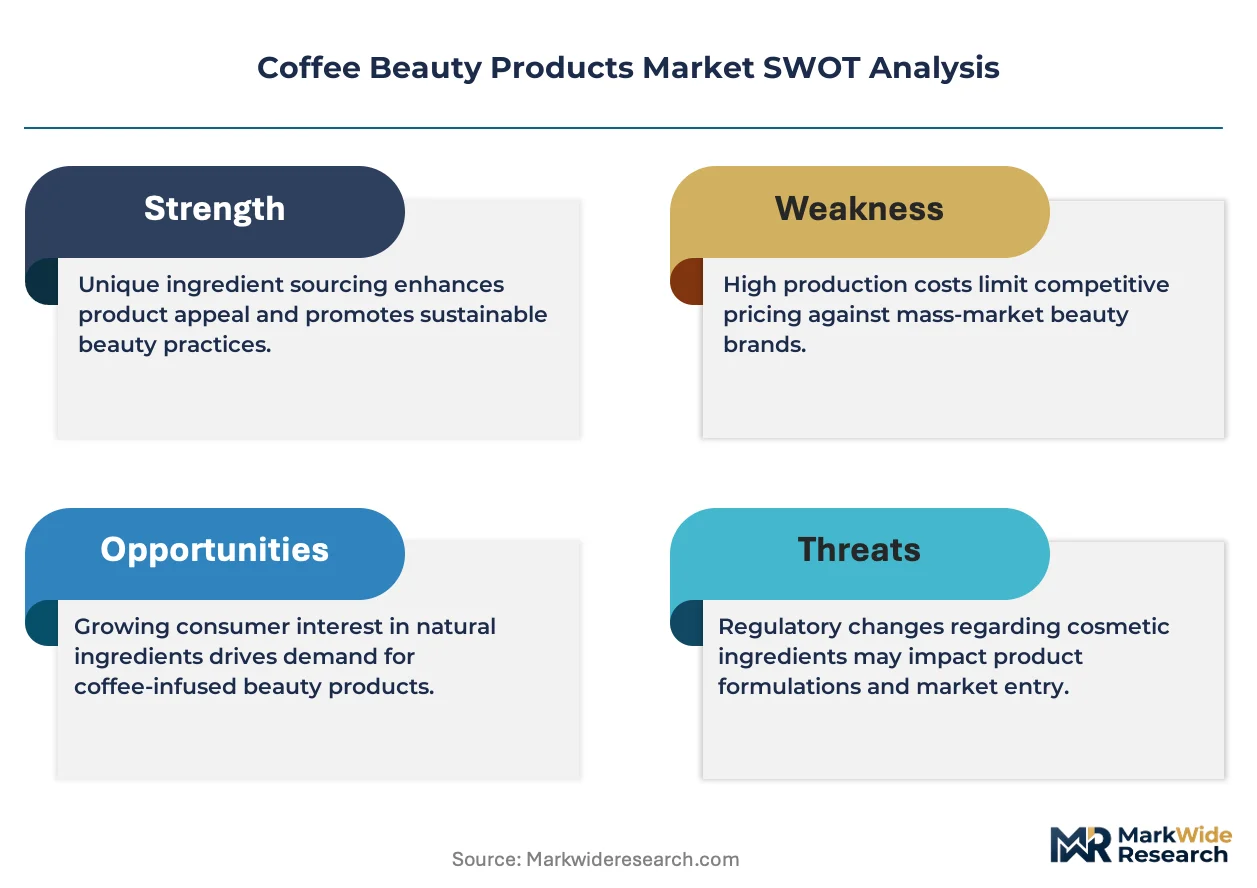
REACH registration requirements in Europe mandate full toxicological profiling for coffee-derived raw materials, while the FDA in the United States exercises post-market surveillance over caffeine concentration claims in cosmetic labeling. India's FSSAI and CDSCO maintain overlapping jurisdiction where cosmetic-cosmeceutical boundaries blur for coffee extract products promising functional skin benefits. Stakeholders must monitor evolving classification decisions that determine whether antioxidant claims trigger pharmaceutical regulation rather than cosmetic compliance.
Market Dynamics
REACH registration requirements in Europe are forcing full toxicological profiling for coffee-derived raw materials, compressing supplier timelines and favoring vertically integrated extractors with in-house compliance capabilities over fragmented commodity traders.
Growth Catalysts
- Cellulite treatment demand:Aesthetic clinics in Brazil and South Korea are standardizing caffeine-infused body contouring protocols, driving bulk procurement of standardized chlorogenic acid extracts.
- REACH compliance infrastructure:European formulators with pre-registered coffee extract dossiers capture shelf space as smaller competitors exit due to registration cost barriers.
- Cold-brew extraction technology:Low-temperature processing preserves antioxidant potency, enabling premium positioning for spa-grade oils in professional service channels.
Market Restraints
- Raw material concentration:Coffea canephora bean supply clusters in Vietnam and Indonesia, exposing formulators to monsoon-driven crop volatility and freight cost spikes.
- Regulatory friction:India's FSSAI and CDSCO maintain overlapping jurisdiction where antioxidant claims trigger pharmaceutical rather than cosmetic classification, delaying product launches.
- Substitution threat:Synthetic caffeine from pharmaceutical suppliers offers price stability that natural extracts cannot match, pressuring mid-market scrub margins.
Strategic Opportunities
- Scalp care expansion:Haircare masks with circulation claims represent the fastest-expanding category, with Korean beauty retailers creating dedicated caffeine hair treatment sections.
- Subscription replenishment:Direct-to-consumer channels in India capture lifetime value through automated serum refills, reducing customer acquisition costs for challenger brands.
- Travel retail penetration:Prestige cold-brew formulations command duty-free price premiums in Dubai and Singapore airport corridors.
Industry Challenges
- Certification timeline compression:Vegan certification for coffee scrubs requires supply chain audits of bean sourcing through extraction, extending new product introduction cycles.
- Formulation stability expertise:Caffeine degradation in aqueous bases demands specialized chemistry talent scarce outside established cosmetic science hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Beauty Products Market |
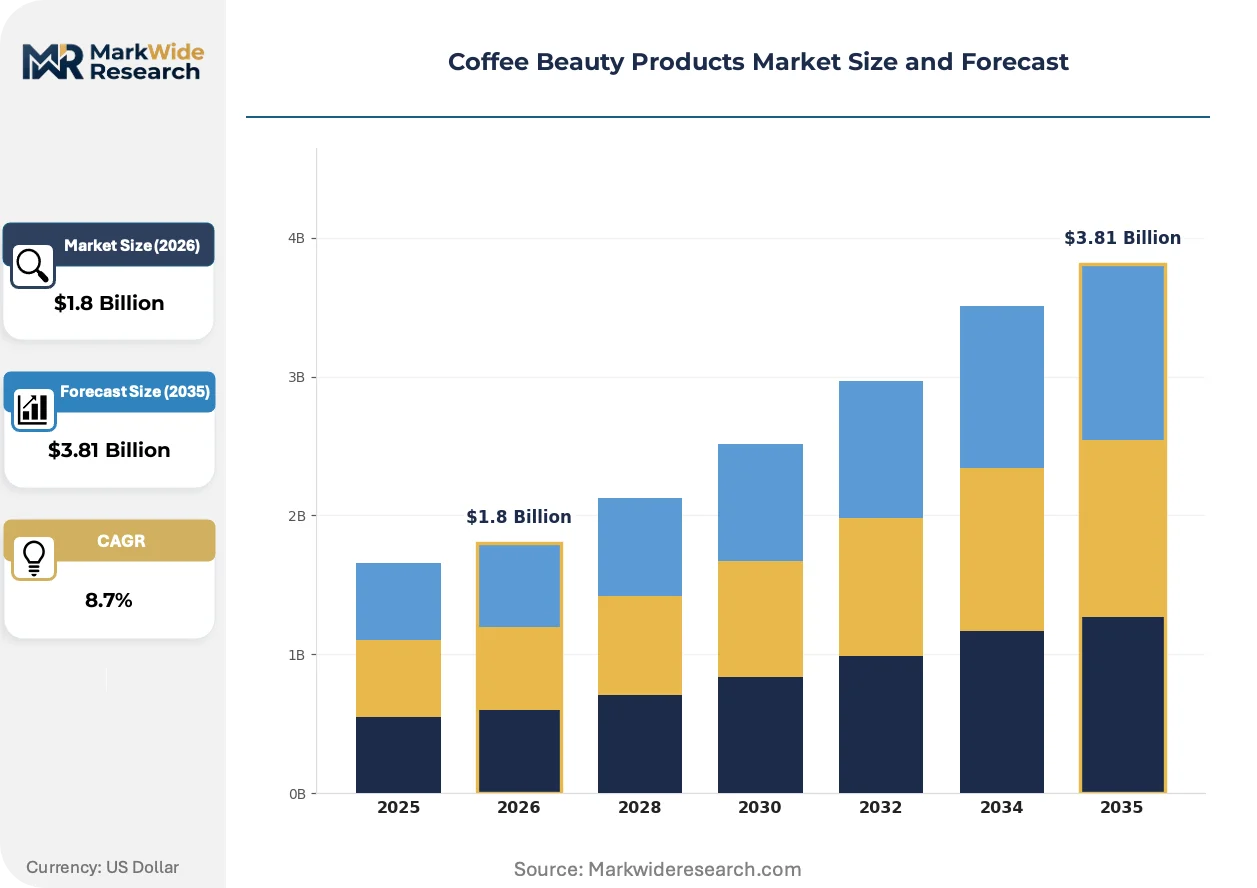
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Scrubs, Oils, Masks Application: Skincare, Haircare, Bath, Body Care Ingredient Source: Organic, Sustainable, Natural, Synthetic Target Audience: Men, Women, Teens, Professionals |
| Companies Covered | Procter & Gamble, Avon Products, L'Oréal, Java Skin Care, Shiseido, Estée Lauder, mCaffeine, Bean Body Care, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Beauty Products Market Emerging Trajectories
Formulation science and channel economics are reshaping how coffee extracts move from commodity inputs to differentiated beauty solutions. Three developments are compressing legacy supply arrangements and creating new value capture points.
Cold-brew extraction is overtaking traditional heat-processed methods for premium skincare applications. Low-temperature steeping preserves chlorogenic acid integrity that thermal degradation destroys. Prestige formulators in France and Japan specify cold-brew grades for eye serums commanding professional channel price premiums. This technology is overtaking heat-processed extracts in spa-grade oil segments where efficacy claims must withstand dermatological scrutiny.
REACH ingredient disclosure mandates in Europe are tightening toxicological documentation requirements for botanical extracts. ECHA's 2024 updated guidance on plant-derived substances requires reproductive toxicity data for concentrations above threshold limits. Under-eye treatment manufacturers reformulating for compliance are consolidating supplier bases to pre-registered extractors with complete dossier portfolios.
Specialty skincare retailers are expanding shelf space allocation for caffeine-infused products based on scan velocity data. Sephora and Douglas have created dedicated clean beauty sub-sections highlighting antioxidant ingredient stories. This merchandising shift is most visible in Germany and the United Kingdom where consumer education on chlorogenic acid benefits has advanced through influencer dermatologist content.
Coffee Beauty Products Market Segmentation
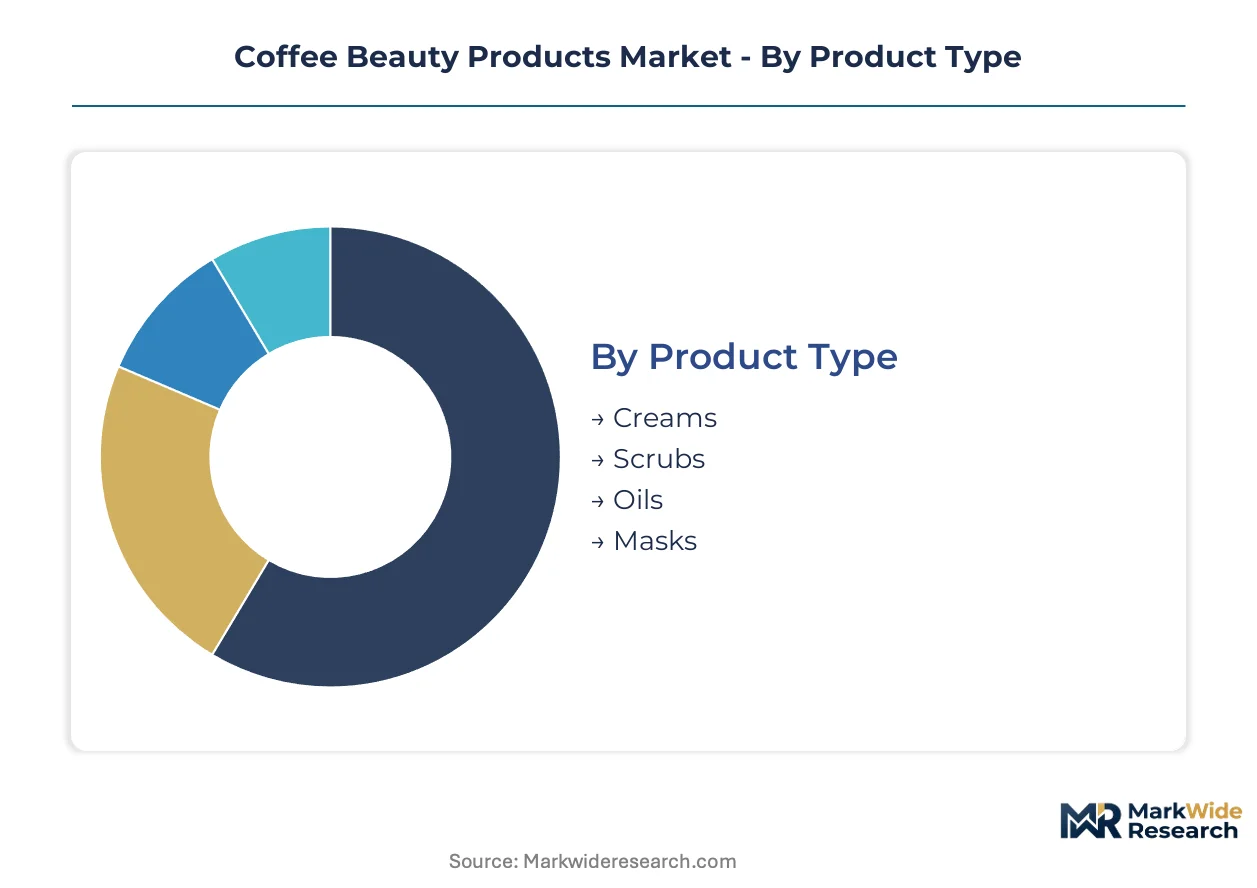
Coffee beauty products fragment across four distinct axes that determine formulation chemistry, regulatory pathway, and channel economics. Each segmentation dimension carries specific implications for margin structure and competitive positioning.
Product Type:
Formulation viscosity and delivery mechanism define performance claims and price positioning across the category.
- Creams:Emulsion-based vehicles carrying one to five percent caffeine concentration dominate under-eye and cellulite treatment applications. Brazilian aesthetic clinics standardize these formulations for body contouring protocols, driving bulk procurement of chlorogenic acid extracts.
- Scrubs:Physical exfoliants with ground coffee particles serve as mass-market entry points where vegan certification requirements extend supply chain audit timelines. India's direct-to-consumer brands capture lifetime value through subscription replenishment of these accessible formats.
- Oils:Lipid-soluble extracts concentrate in professional spa channels where service pricing supports cold-brew extraction grades.
- Masks:Rinse-off formats with sustained skin contact time enable higher active loading for antioxidant claims.
Creams lead on scale; scrubs lead on momentum.
Application:
End-use physiology determines regulatory scrutiny and margin capture potential.
- Skincare:Topical facial applications command the highest per-unit margins, with under-eye serums leveraging vasoconstrictive caffeine mechanisms. Korean beauty retailers have created dedicated caffeine treatment sections based on scan velocity data.
- Haircare:Scalp circulation claims represent the fastest-expanding category, with masks and serums targeting follicle stimulation. Professional salon channels in Japan specify cold-brew extract grades for premium positioning.
- Bath:Immersion products face formulation stability challenges as caffeine degrades in aqueous bases, demanding specialized chemistry expertise.
- Body Care:Cellulite and contouring applications concentrate demand in Brazil and South Korea where aesthetic clinics drive protocol standardization.
Skincare dominates revenue capture; haircare shows steepest expansion trajectory.
Ingredient Source:
Raw material provenance determines certification burden and price tier placement.
- Organic:Certified cultivation restricts supplier pools to farms meeting soil and processing standards, compressing extract availability during harvest volatility.
- Sustainable:Traceability documentation from bean to extraction satisfies ESG procurement mandates at European prestige formulators.
- Natural:Non-certified botanical extracts occupy mid-market positioning where REACH registration costs filter out smaller commodity traders.
- Synthetic:Pharmaceutical-grade caffeine offers price stability that natural extracts cannot match, pressuring mass-market scrub margins.
Natural sources anchor volume; sustainable sources gain share fastest.
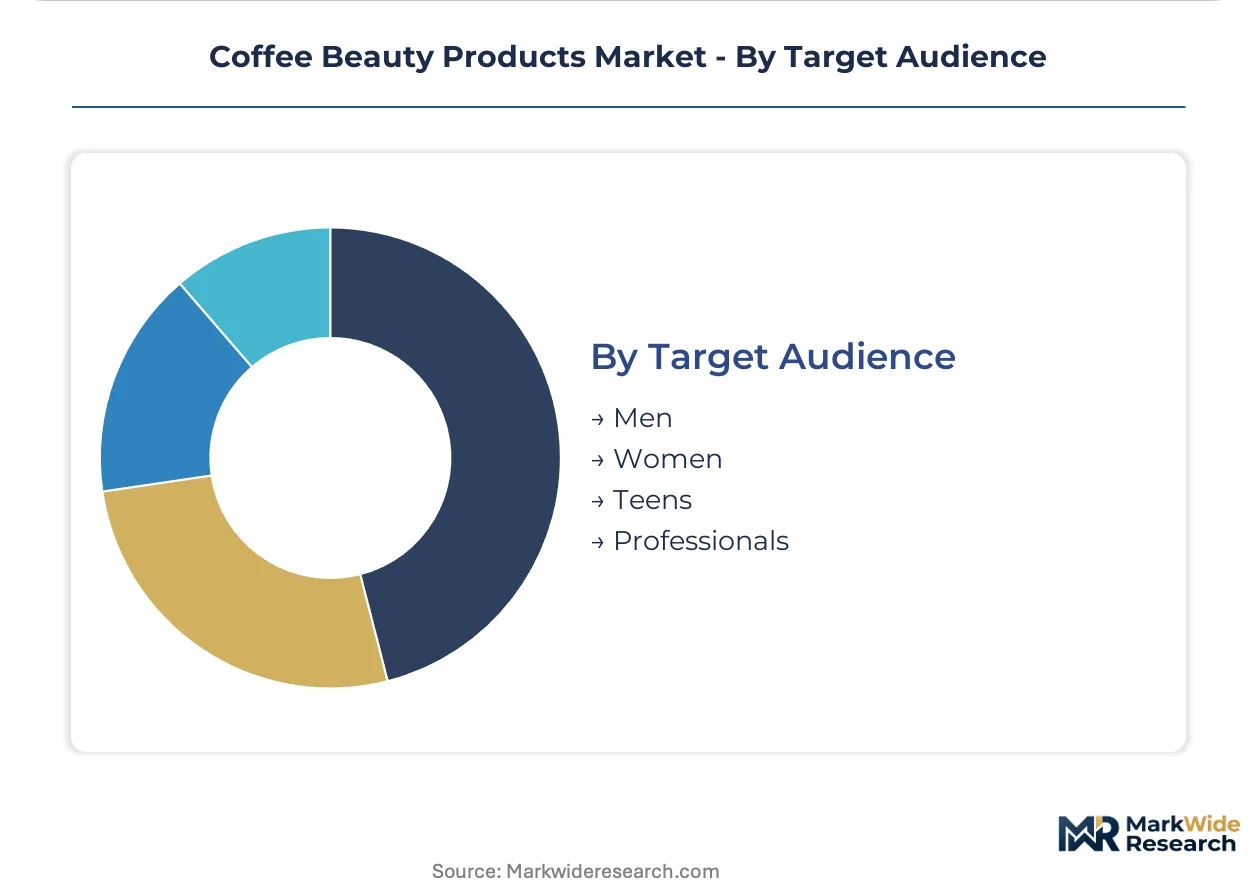
Target Audience:
Demographic specificity shapes marketing investment and channel selection.
- Women:Core purchasers across all product types, with highest engagement in anti-aging and cellulite treatment segments.
- Men:Emerging demand concentrates in scalp care and grooming-adjacent formats, with Korean and Japanese markets showing earliest adoption.
- Teens:Entry-price scrubs and masks dominate, with influencer dermatologist content driving education on chlorogenic acid benefits.
- Professionals:Time-constrained users favor subscription replenishment and travel retail formats in Dubai and Singapore corridors.
Women retain volume leadership; men represent the fastest-climbing demographic segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands aesthetic clinic procurement volumes while India drives direct-to-consumer subscription adoption, revealing divergent channel maturities across major demand centers.
Brazil
Aesthetic clinics in São Paulo and Rio de Janeiro standardize caffeine-infused body contouring protocols, creating institutional procurement demand for chlorogenic acid extracts. ANVISA maintains cosmetic registration pathways distinct from pharmaceutical classification, though antioxidant claims require substantiation dossiers. Domestic coffee extract suppliers in Minas Gerais partner with regional beauty manufacturers to shorten supply chains.
India
Direct-to-consumer challenger brands capture lifetime value through automated serum refill subscriptions, reducing customer acquisition costs in the scrubs and masks segments. FSSAI and CDSCO maintain overlapping jurisdiction where cosmetic-cosmeceutical boundaries blur, delaying launches for products promising functional skin benefits. Karnataka-based extractors supply vegan-certified coffee scrubs to brands dominating India's e-commerce channels.
South Korea
Korean beauty retailers create dedicated caffeine hair treatment sections based on scan velocity data, accelerating scalp care category expansion. MFDS regulates cosmetic caffeine concentrations with post-market surveillance protocols. Seoul-based formulators lead cold-brew extraction adoption for professional spa-grade oils targeting follicle stimulation claims.
United States
Prestige formulators leverage dermatological testing infrastructure to anchor premium positioning for caffeine-based eye serums in specialty retail. FDA exercises post-market surveillance over caffeine concentration claims in cosmetic labeling rather than pre-market approval. California-based clean beauty brands pioneer chlorogenic acid education through influencer dermatologist partnerships.
Germany
Specialty retailers expand shelf space allocation for caffeine-infused products based on velocity metrics, with dedicated clean beauty sub-sections highlighting antioxidant ingredient stories. ECHA's updated REACH guidance mandates reproductive toxicity data for botanical extracts above threshold limits. Frankfurt and Munich clusters consolidate supplier bases to pre-registered extractors with complete dossier portfolios.
Coffee Beauty Products Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with prestige houses controlling professional channels while agile challengers dominate direct-to-consumer entry points. The vendor base organizes into three tiers: multinational conglomerates with dermatological testing infrastructure, regional specialists with vegan certification capabilities, and private-label contract manufacturers serving mass-market retailers. Consolidation pressures favor vertically integrated extractors with in-house REACH compliance capabilities. Strategic moves concentrate on supplier base consolidation and cold-brew extraction technology licensing.
Among multinational beauty conglomerates, L'Oréal and Estée Lauder occupy positions anchored by prestige distribution networks and dermatological validation infrastructure. mCaffeine represents the specialist archetype with vegan-certified formulations and direct-to-consumer channel expertise. Shiseido exemplifies regional scale players extending cold-brew extraction capabilities across Asian professional spa channels.
| Leading Market Players |
|---|
| Procter & Gamble |
| Avon Products |
| L'Oréal |
| Java Skin Care |
| Shiseido |
| Estée Lauder |
| mCaffeine |
| Bean Body Care |
| Unilever |
| Others |
Supply Flow & Price Mechanics
REACH registration mandates in Europe gate qualified supply access and premium-tier pricing power, compressing supplier timelines to favor vertically integrated extractors with complete toxicological dossiers over fragmented commodity traders unable to absorb compliance costs.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for Coffea canephora extracts, though monsoon-driven crop volatility preserves premium tiers for cold-brew grades. Pricing stratifies across premium spa-grade oils, standard cosmetic-grade extracts, and economy-positioned synthetic caffeine alternatives. Cost compression in mass-market scrubs intensifies because pharmaceutical-grade synthetic caffeine offers price stability natural extracts cannot match. Mass-market retailers show highest price sensitivity; prestige formulators in professional channels demonstrate lowest.
Supply Chain Analysis
Vegan certification requirements extend supply chain audit timelines from bean sourcing through extraction, filtering supplier pools to operations capable of documenting cultivation standards. Raw material supply draws from Vietnam, Indonesia, and Brazil, with domestic extractors in Minas Gerais and Karnataka shortening regional manufacturer lead times. Single-source vulnerability concentrates in Vietnamese Robusta harvests exposed to climate volatility. Distribution runs through specialty skincare retailers, direct-to-consumer subscriptions, and professional spa service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-brew extraction technology adoption expands margin capture potential by preserving antioxidant potency that commands professional channel premiums, while synthetic caffeine substitution pressures mid-market positioning.
For Market Incumbents: Anchor dermatological testing infrastructure to defend premium eye serum positioning against challenger brands lacking clinical validation capabilities. Consolidate supplier bases to pre-registered extractors with REACH-compliant dossiers before registration cost barriers eliminate smaller competitors. Deepen backward integration into chlorogenic acid extraction to secure supply continuity during Vietnam harvest volatility. For New Entrants and Emerging Players: MFDS post-market surveillance protocols in South Korea open a window for scalp care specialists to capture dedicated retail shelf space before category saturation. Target men's grooming-adjacent caffeine hair treatments in Seoul and Tokyo where adoption curves remain underpenetrated. Deploy subscription replenishment models in India's direct-to-consumer channels to reduce customer acquisition costs against established incumbents. For Investors and Strategic Acquirers: Roll-up economics work for vegan-certified coffee scrub specialists because certification audit costs create scale advantages that fragment smaller competitors. Five-to-ten year viability hinges on cold-brew extraction technology licensing portfolios rather than commodity-grade heat-processed capacity. Watch for ECHA guidance updates on reproductive toxicity thresholds as inflection indicators for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Brew Extraction Licensing | Low-temperature processing preserves chlorogenic acid integrity for spa-grade oil premiums in France and Japan. |
| Vegan Certification Investment | Supply chain audits from bean to extraction satisfy ESG procurement mandates at European prestige formulators. |
| Subscription Replenishment Launch | Automated serum refills capture lifetime value and reduce acquisition costs in India's e-commerce channels. |
| Supplier Base Consolidation | Pre-registered extractors with complete REACH dossiers capture shelf space as compliance costs filter competitors. |
| Scalp Care Category Expansion | Dedicated caffeine hair treatment sections in Korean beauty retailers accelerate the fastest-expanding application segment. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulators, regulatory affairs specialists at extractors, specialty retail category buyers, and professional spa procurement managers with secondary validation against REACH registration databases, ECHA guidance documents, ANVISA cosmetic filings, and customs trade records for coffee-derived raw materials. Bottom-up volume builds across product type and application segments triangulated against top-down market sizing from beauty industry associations.
Historical reference periods anchored the projection framework, with growth trajectories modeled across the analysis window by product type, application, ingredient source, and target audience dimensions. CAGRs derived from segment-level growth rates weighted by current revenue contribution, incorporating cold-brew extraction adoption curves, regulatory compliance timeline compression, and channel shift dynamics between specialty retail and direct-to-consumer.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA threshold revisions or sustained Vietnamese monsoon disruption. Model outputs reflect assumptions on certification adoption rates and synthetic caffeine substitution elasticity. A model refresh is warranted upon material change in REACH enforcement intensity or cold-brew extraction technology licensing availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
UAE Beauty Industry Market