
 Asia-Pacific Cancer Therapy Market | 2026-2036
Asia-Pacific Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cancer Therapy Market Outlook
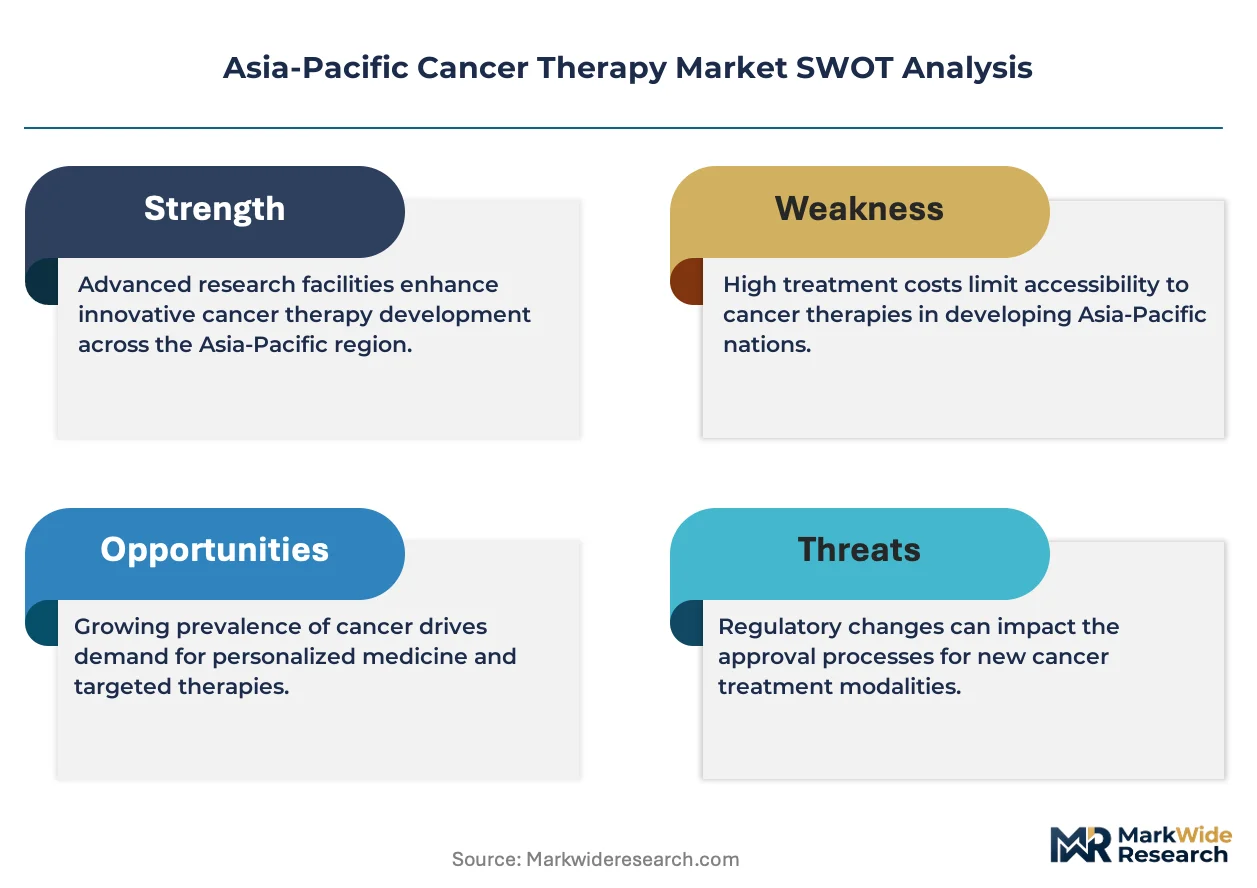
Oncology-trained physician capacity is unwinding across Southeast Asia, where specialist density lags patient need by wide margins. F. Hoffmann-La Roche Ltd leverages its diagnostic-therapy pairing to anchor companion testing workflows in Japan and South Korea. Bristol-Myers Squibb Company competes through checkpoint inhibitor development, while AstraZeneca dominates EGFR-mutation targeted therapy positioning in China and Australia.
Asia-Pacific cancer therapy encompasses systemic and localized interventions designed to eliminate, control, or palliate malignant disease, spanning cytotoxic small molecules, monoclonal antibodies, cellular therapies, and external beam or particle radiation delivered at 1.8–2.0 Gy standard fractionation or hypofractionated regimens. Its primary purpose is to improve overall survival and quality-of-life endpoints across diverse tumor histologies and staging profiles. Immunotherapy now leads value generation as PD-1/PD-L1 inhibitors expand into earlier lines of treatment across lung and gastric malignancies, while targeted therapy occupies the fastest-growing margin pool driven by liquid biopsy-informed patient selection. Chemotherapy sustains volume dominance in cost-sensitive public hospital systems across India and Indonesia, though its share of new-patient initiations is compressing.
Japan's PMDA, Australia's TGA, and China's NMPA each operate distinct review frameworks that shape trial design requirements and market access timelines for sponsors seeking multi-country launches. India's CDSCO and South Korea's MFDS add further complexity through local manufacturing and bridging study mandates that influence regional supply planning. Stakeholders must monitor convergence between China's GB standards for biologics manufacturing and ICH Q5A viral safety guidelines, as this alignment will determine which facilities qualify for cross-border commercial supply without redundant validation.
Market Dynamics
Japan's PMDA accelerated approval pathways are compressing time-to-market for novel immuno-oncology biologics while simultaneously fragmenting competitive positioning across China's tier-one cities where proton therapy centers and CAR-T manufacturing facilities cluster.
Growth Catalysts
- Accelerated Regulatory Pathways:Japan's PMDA Sakigake designation and China's NMPA breakthrough therapy status compress clinical development timelines for PD-1/PD-L1 inhibitors, pulling forward revenue recognition for sponsors targeting lung and gastric malignancies.
- Liquid Biopsy Integration:Companion diagnostic workflows pairing tissue-agnostic biomarker detection with targeted therapy selection are expanding addressable patient pools in South Korea and Australia beyond traditional histology-based prescribing.
- Cellular Therapy Manufacturing:China is concentrating CAR-T production capacity in Shanghai and Beijing biotech clusters, reducing per-dose production costs through scale economies and domestic viral vector supply.
Market Restraints
- Specialist Physician Scarcity:Southeast Asia's oncology-trained physician density lags patient need by wide margins, capping treatment initiation rates in Indonesia, Vietnam, and the Philippines regardless of drug availability.
- Reimbursement Compression:India's CDSCO price controls on essential oncology medicines compress margin pools for imported innovator therapies, forcing portfolio rationalization toward locally manufactured generics.
- Cold Chain Infrastructure Gaps:Last-mile distribution of temperature-sensitive cellular therapies faces continuity failures across archipelagic geographies and mountainous terrain in Indonesia and the Philippines.
Strategic Opportunities
- Radiotherapy Capacity Expansion:Proton and heavy ion therapy centers remain underpenetrated across Southeast Asia, creating first-mover positioning for equipment vendors and service operators in Thailand and Malaysia.
- Domestic Biologics Manufacturing:China's GB standards convergence with ICH Q5A viral safety guidelines positions domestic CMOs for cross-border commercial supply to Australia and South Korea without redundant validation.
- Hypofractionated Regimen Adoption:Shorter-course radiation protocols are penetrating Australia's public hospital systems, displacing conventional fractionation and expanding linear accelerator throughput per installed unit.
Industry Challenges
- Bridging Study Requirements:South Korea's MFDS and India's CDSCO mandate local or regional clinical data for biologics registration, extending development timelines and complicating multi-country launch sequencing for sponsors.
- Quality Control Talent Gap:GMP-qualified personnel for cell therapy manufacturing remain concentrated in Japan and China, constraining facility expansion in secondary Asia-Pacific markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cancer Therapy Market |
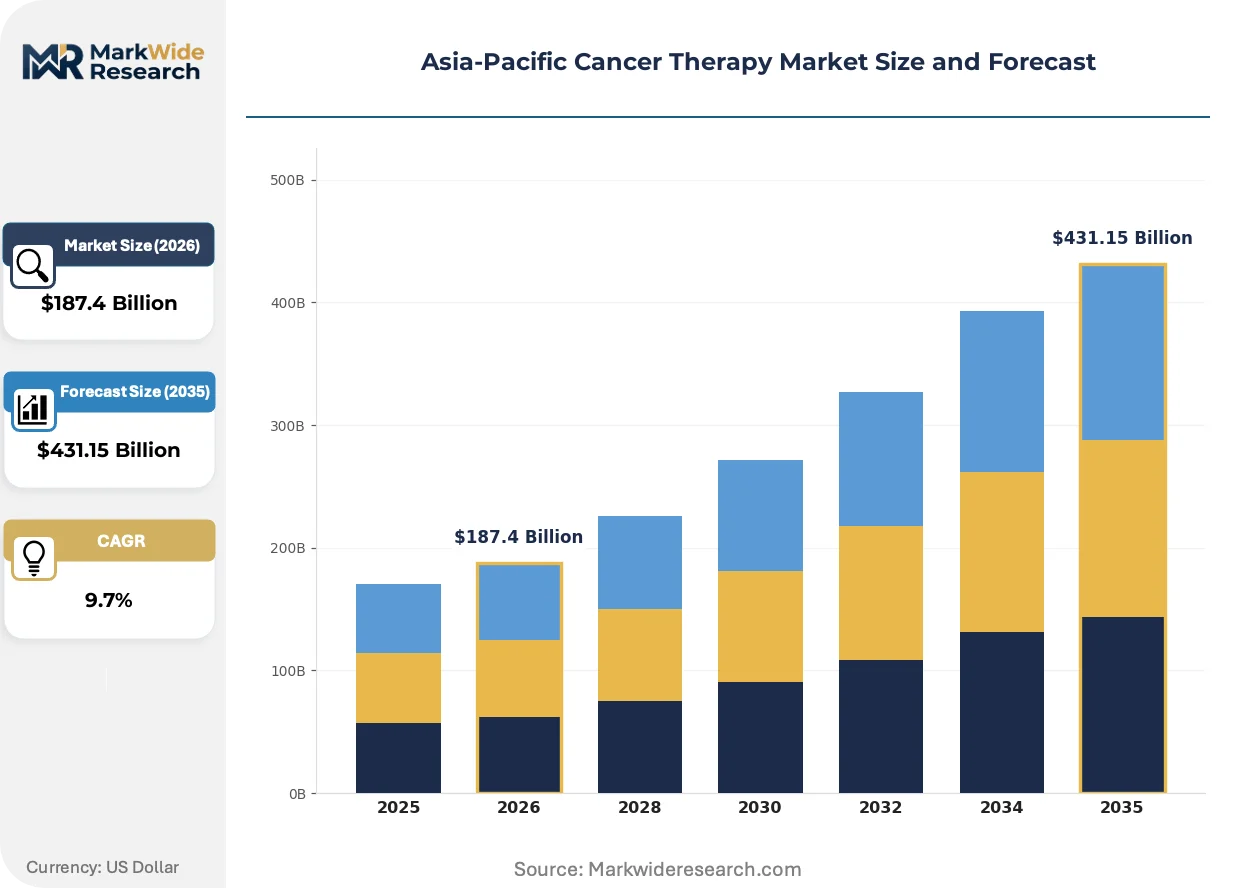
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer End User: Hospitals, Clinics, Oncology Centers, Home Care Delivery Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Merck & Co. Inc., Bayer AG, Amgen Inc., AstraZeneca, Johnson & Johnson Services, Inc., F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Novartis AG, Pfizer Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cancer Therapy Market Strategic Shifts
Immuno-oncology is actively displacing chemotherapy as the value-generating backbone of cancer care across the Asia-Pacific region, while regulatory convergence and procurement centralization reshape how therapies reach patients.
CAR-T cell therapy is bifurcating into autologous and allogeneic production paradigms with distinct supply chain architectures. China's NMPA has approved multiple domestic autologous products for hematologic malignancies, driving hospital-based apheresis and cryopreservation infrastructure investment in Beijing and Shanghai. Allogeneic platforms are compressing manufacturing lead times from weeks to days, enabling outpatient administration models that displace inpatient capacity constraints.
Australia's TGA is aligning its priority review pathways with FDA breakthrough therapy criteria, reducing regulatory lag for sponsors pursuing simultaneous US and Asia-Pacific submissions. This convergence compresses market access timelines for checkpoint inhibitors and antibody-drug conjugates. Multinational sponsors are responding by front-loading Australian sites in global Phase III protocols to capture early revenue recognition.
Hospital procurement consortia in China's tier-one cities are consolidating purchasing authority for high-cost oncology biologics, displacing fragmented individual hospital tendering. Shanghai's municipal health commission now negotiates centralized volume agreements for PD-1 inhibitors, compressing net prices while guaranteeing minimum offtake volumes. This concentration is visible across Guangdong and Jiangsu provinces, where provincial procurement platforms aggregate demand from dozens of tertiary hospitals.
Asia-Pacific Cancer Therapy Market Segmentation
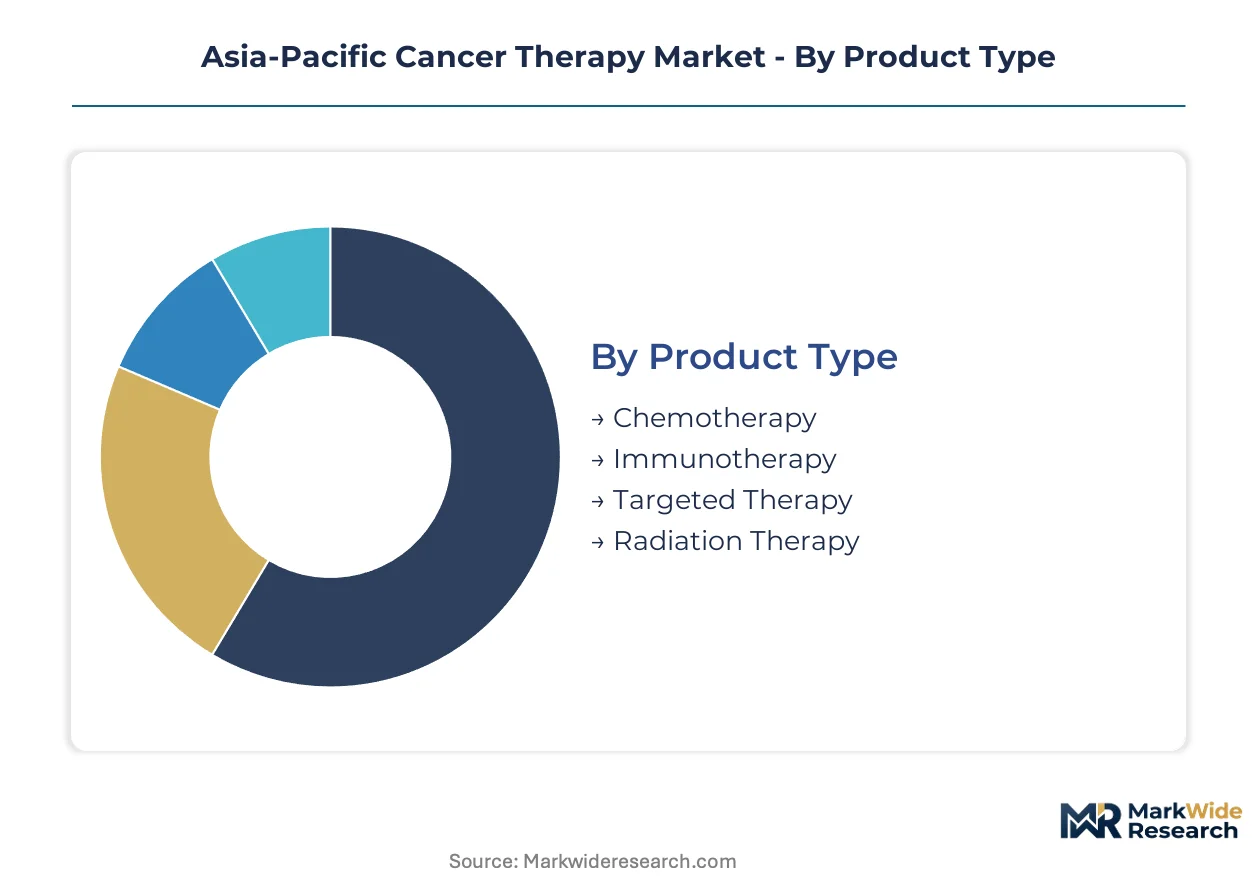
Asia-Pacific cancer therapy segmentation reveals how treatment modalities, disease indications, and care settings fragment procurement authority across hospital consortia, specialty clinics, and emerging home infusion networks. Channel concentration in China's tier-one cities and Japan's academic medical centers shapes which segments capture margin versus volume.
Product Type:
Hospital-based oncology departments in China and Japan route high-value biologics through centralized pharmacy committees, while India's public sector procurement channels favor cost-optimized cytotoxic agents.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors administered via intravenous infusion in tertiary hospitals. Demand concentrates in Japan's PMDA-accelerated approval pathway and China's breakthrough therapy designation, where lung and gastric malignancy indications dominate new-patient initiations.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies selected through companion diagnostic workflows. China's NMPA-approved liquid biopsy platforms in Shanghai and Beijing are expanding addressable pools beyond tissue-based testing constraints.
- Chemotherapy:Cytotoxic agents—platinum compounds, taxanes, alkylating agents—remain volume-dominant in India's CDSCO-negotiated essential medicine lists and Indonesia's public hospital systems despite compressing first-line share.
- Radiation Therapy:External beam photon, proton, and heavy ion delivery systems. Proton centers cluster in China's tier-one cities and Japan's metropolitan corridors, while cobalt-60 units persist in Southeast Asia's cost-constrained environments.
Immunotherapy dominates installed base in Japan and South Korea. Targeted therapy is where expansion concentrates across China's biotech clusters.
Therapy Area:
Malignancy-specific protocols determine reimbursement tiering and clinical trial site selection, with lung and breast cancer commanding the deepest sponsor investment across Asia-Pacific regulatory frameworks.
- Lung Cancer:Non-small cell and small cell histologies drive PD-1/PD-L1 inhibitor adoption. Australia's TGA priority review pathway and China's NMPA breakthrough status compress access timelines for EGFR-mutation and ALK-rearrangement targeted combinations.
- Breast Cancer:HER2-positive, hormone receptor-positive, and triple-negative subtypes segment treatment algorithms. CDK4/6 inhibitor access expands in Japan's universal coverage system while India's CDSCO price controls limit innovator therapy penetration.
- Colorectal Cancer:MSI-high and RAS-wildtype biomarker segments guide immunotherapy and EGFR inhibitor selection. South Korea's MFDS biomarker-linked reimbursement shapes prescribing in Seoul's tertiary centers.
- Prostate Cancer:Androgen deprivation therapy backbone with PARP inhibitor expansion in homologous recombination-deficient segments. Australia's TGA approvals for novel hormonal agents outpace Southeast Asian registration timelines.
Lung cancer commands the steepest pipeline investment. Breast cancer exhibits the broadest reimbursement coverage variance across national systems.
End User:
Site-of-care economics fragment procurement scale, with hospital consortia aggregating biologics purchasing while home infusion networks capture subcutaneous administration shifts.
- Hospitals:Tertiary academic medical centers with embedded radiation oncology and cellular therapy infrastructure. China's provincial procurement platforms in Guangdong and Jiangsu consolidate PD-1 inhibitor tendering across dozens of institutions.
- Oncology Centers:Dedicated cancer hospitals and day-care infusion units. India's regional cancer centers in Delhi, Mumbai, and Chennai concentrate radiation therapy capacity and clinical trial access.
- Clinics:Community and specialty physician practices handling stable-disease monitoring and oral therapy management. Australia's general practitioner-led oncology networks extend into regional and rural access.
- Home Care:Subcutaneous immunotherapy and oral targeted agent administration. Japan's aging population demographics and reimbursement for home nursing support expansion.
Hospitals retain biologics purchasing concentration. Home care is gaining share fastest in Japan's reimbursement-advantaged environments.
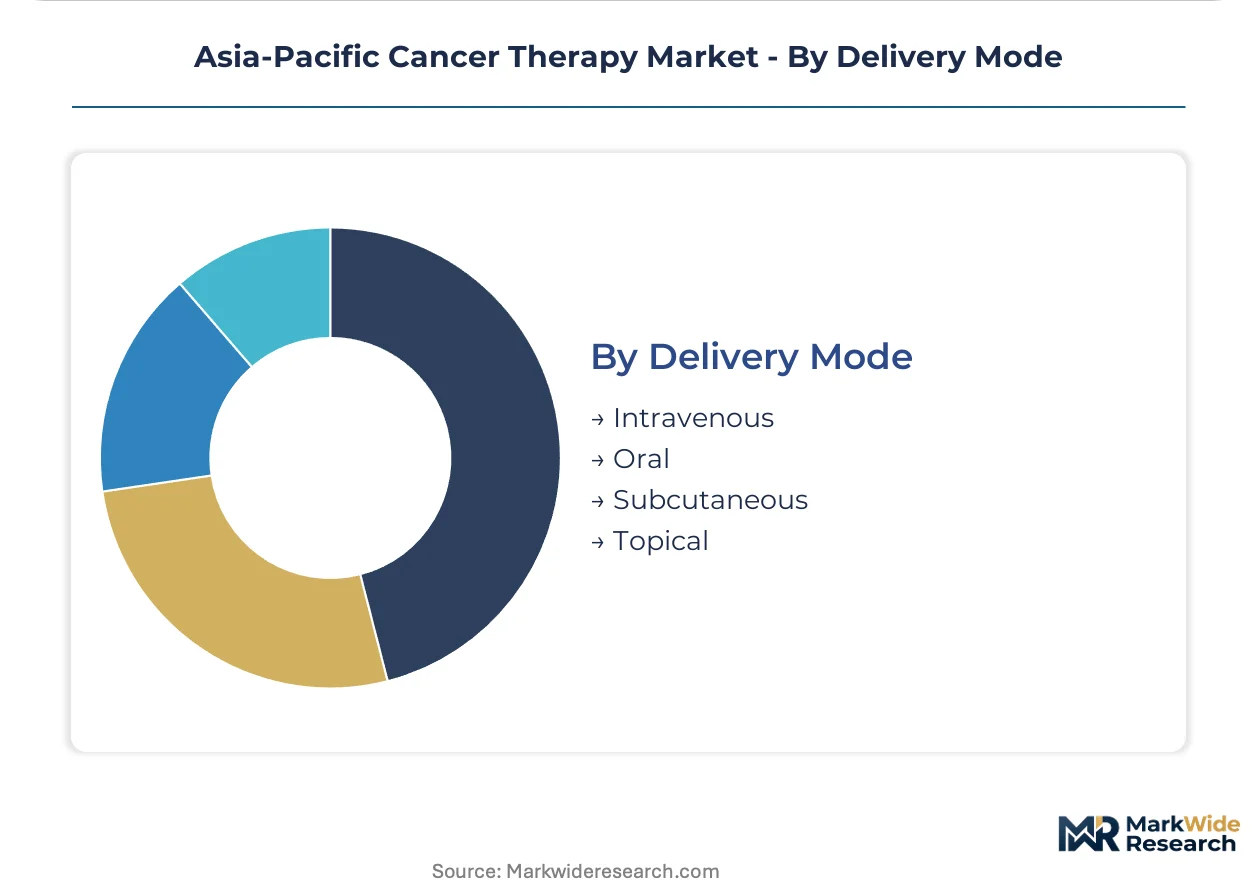
Delivery Mode:
Route of administration determines cold chain requirements, pharmacy compounding complexity, and site-of-care flexibility across Asia-Pacific distribution networks.
- Intravenous:Infusion-center administration for monoclonal antibodies, checkpoint inhibitors, and cytotoxic combinations. China's hospital-based infusion centers require GMP-compliant compounding pharmacies.
- Oral:Tyrosine kinase inhibitors and hormone therapies enabling outpatient management. India's domestic manufacturing of generic oral oncology medicines supplies cost-sensitive public programs.
- Subcutaneous:Fixed-dose formulations reducing infusion center burden. Australia's TGA approvals for subcutaneous checkpoint inhibitors support day-care unit throughput expansion.
- Topical:Limited to skin cancer and palliative applications. Southeast Asia's dermatology-oncology crossover clinics in Thailand and Malaysia concentrate utilization.
Intravenous dominates biologics delivery infrastructure. Subcutaneous formulations are climbing the fastest as sponsors pursue site-of-care economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA breakthrough therapy designations and Japan's PMDA Sakigake pathways anchor regulatory momentum across the Asia-Pacific region. Hospital infrastructure expansion and biologics manufacturing clustering concentrate investment in specific metropolitan corridors.
China
Lung and gastric malignancy patient volumes drive PD-1/PD-L1 inhibitor demand through Shanghai and Beijing hospital networks. NMPA accelerated reviews compress development timelines for domestic biotech sponsors. CAR-T manufacturing facilities cluster in Yangtze River Delta biotech parks, reducing per-dose production costs through integrated viral vector supply chains.
Japan
Aging demographics expand addressable pools for immuno-oncology agents across Kanto and Kansai metropolitan treatment centers. PMDA Sakigake designation pulls forward revenue recognition for sponsors targeting earlier lines of therapy. Academic medical centers in Tokyo and Osaka concentrate radiation oncology infrastructure and clinical trial site density.
India
Cost-sensitive public hospital systems sustain chemotherapy volume dominance despite innovator therapy penetration limits. CDSCO price controls on essential oncology medicines compress margin pools for imported biologics, favoring domestic generic manufacturing. Regional cancer centers in Delhi, Mumbai, and Chennai concentrate radiation therapy capacity and specialist physician training programs.
Australia
TGA priority review alignment with FDA breakthrough criteria reduces regulatory lag for simultaneous US-Asia-Pacific submissions. Subcutaneous checkpoint inhibitor approvals expand day-care unit throughput in New South Wales and Victoria public hospital systems. General practitioner-led oncology networks extend regional and rural access beyond metropolitan tertiary centers.
South Korea
MFDS biomarker-linked reimbursement shapes prescribing patterns in Seoul's tertiary oncology centers. Liquid biopsy platform adoption expands addressable patient pools beyond traditional tissue-based testing constraints. Bridging study mandates for biologics registration extend development timelines while securing regional data packages for multi-country launches.
Asia-Pacific Cancer Therapy Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific cancer therapy market. The upper tier commands companion diagnostic pairing capabilities and multi-country regulatory submission infrastructure. Specialists occupy targeted therapy niches defined by biomarker-specific development programs. Competitive moves concentrate on strategic partnerships for manufacturing scale and geographic licensing arrangements for market access acceleration.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd and AstraZeneca exemplify archetypes anchored by diagnostic-therapy pairing and targeted therapy positioning respectively. Bristol-Myers Squibb Company occupies a checkpoint inhibitor development position. These entities represent contrasting strategic postures: one leveraging diagnostic infrastructure to lock in companion testing workflows, another dominating EGFR-mutation therapy segments across China and Australia.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Bayer AG |
| Amgen Inc. |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
CAR-T manufacturing scale economies in Shanghai and Beijing biotech parks compress per-dose production costs while simultaneously anchoring price floors for cellular therapies across the Asia-Pacific region. This concentration of GMP-compliant viral vector supply chains in China's Yangtze River Delta creates asymmetric pricing power for domestic sponsors versus import-dependent competitors in Southeast Asia.
Pricing Analysis
Japan's universal coverage system sustains premium checkpoint inhibitor pricing against India's CDSCO-negotiated essential medicine lists where chemotherapy generics dominate. Three-tier pricing structure across premium innovator biologics, mid-tier biosimilars, and economy cytotoxic generics segments patient access by reimbursement tier. Pricing pressure stems from China's provincial procurement platforms aggregating PD-1 inhibitor demand across Guangdong and Jiangsu hospitals. Public hospital systems in Indonesia and Vietnam exhibit highest price sensitivity, while Japan's aging population coverage mandates demonstrate lowest elasticity.
Supply Chain Analysis
Port congestion at Shanghai Yangshan and Singapore's PSA terminals elevates inbound logistics costs for temperature-sensitive monoclonal antibodies and cryopreserved cellular therapies. Active pharmaceutical ingredient production concentrates in India and China, with viral vector manufacturing clustering in Shanghai, Beijing, and Osaka biotech corridors. Cold chain continuity for CAR-T therapies hinges on liquid nitrogen logistics networks spanning archipelagic Southeast Asia. Single-source vulnerability persists for GMP-qualified cell therapy manufacturing talent concentrated in Japan and China. Distribution runs through hospital-based pharmacy committees in tier-one cities and regional cancer centers in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific cancer therapy market is cycling through a post-pandemic demand recovery as deferred oncology diagnoses translate into treatment initiations across hospital networks. This cyclical upswing is anchored by China's NMPA accelerated review backlog clearing and Japan's PMDA Sakigake designation pipeline maturation.
For Market Incumbents: Consolidate companion diagnostic infrastructure to lock in testing workflows ahead of liquid biopsy platform proliferation from emerging Chinese biotechs. Deepen backward integration into viral vector manufacturing to secure supply continuity as GMP talent scarcity intensifies across Southeast Asia. Anchor capacity expansion in Australia's TGA-aligned regulatory cluster to capture simultaneous US-Asia-Pacific submission synergies.
For New Entrants and Emerging Players: Australia's TGA priority review pathway offers fastest regulatory validation for checkpoint inhibitor and antibody-drug conjugate candidates with FDA breakthrough alignment. Target proton and heavy ion therapy capacity gaps across Thailand and Malaysia where radiotherapy infrastructure remains underpenetrated relative to patient need. Pursue subcutaneous formulation development to displace infusion-center dependence and capture Japan's home care reimbursement expansion.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among domestic Chinese biotechs with NMPA-approved CAR-T manufacturing facilities and provincial procurement platform offtake guarantees. Long-term viability across the projection horizon favors entities with integrated diagnostic-therapy pairing capabilities and multi-country regulatory submission infrastructure. Monitor China's GB standards convergence with ICH Q5A viral safety guidelines as the inflection signal determining which CMOs qualify for cross-border commercial supply without redundant validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Japan's PMDA Sakigake designation compresses time-to-market for novel immuno-oncology biologics. |
| Manufacturing Scale-Up | CAR-T production clustering in Shanghai biotech parks reduces per-dose costs through integrated viral vector supply. |
| Clinical Trial Advancement | Australia's TGA priority review alignment with FDA criteria accelerates simultaneous US-Asia-Pacific submissions. |
| Licensing Agreement | Companion diagnostic workflows with liquid biopsy platforms expand addressable patient pools beyond tissue constraints. |
| Pipeline Diversification | Allogeneic cell therapy platforms compress manufacturing lead times from weeks to days for outpatient models. |
Study Parameters
Cross-validation between primary interviews with oncology drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings alongside secondary validation. Primary fieldwork drew from NMPA and PMDA submission databases, ClinicalTrials.gov protocol records, and hospital formulary listings across China's provincial procurement platforms. Bottom-up patient-flow modeling and top-down revenue triangulation reconcile volume and value estimates across the analysis window.
Sensitivity analysis across treatment line, administration route, patient population, and regional regulatory cluster dimensions stress-tests forecast robustness. Modeled CAGRs derive from segmented patient initiation rates, pricing trajectory assumptions, and competitive entry timing throughout the forecast period. Industry-specific inputs include biomarker prevalence rates, reimbursement pathway conversion probabilities, and manufacturing capacity utilization curves for GMP-certified cell therapy facilities.
Underlying assumptions cover regulatory approval timelines, reimbursement listing decisions, and manufacturing scale-up execution, with deviation risk concentrated in China's provincial procurement price negotiations and Southeast Asia's cold chain infrastructure buildout. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Immuno-Oncology Market
Oncology
Cancer Cachexia Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Metastatic Breast Cancer Market
Oncology
Head and Neck Cancer Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
North America Proton Therapy Market
Oncology
Testicular Cancer Treatment Market
Oncology
North America Veterinary Oncology Market
Oncology
Radiation Therapy Software Market
Oncology
Global Cancer Treatment Market
Oncology
Global Proton Therapy Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Metastases Spinal Tumor Market