
 Scoliosis Treatment Market | 2026-2036
Scoliosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Scoliosis Treatment Market Outlook
Software-enabled surgical planning and remote monitoring is shifting the commercial model from hardware-only sales toward bundled care contracts. Medtronic leverages its spine robotics platform to anchor premium positioning in deformity correction. Zimmer Biomet competes through specialized pediatric instrumentation lines that extend its orthopedic footprint. NuVasive differentiates via minimally invasive lateral approaches that reduce tissue disruption in adolescent idiopathic cases.
Scoliosis treatment encompasses mechanical, surgical, and rehabilitative interventions to correct lateral spinal curvature exceeding ten degrees Cobb angle, with bracing typically prescribed for curves between twenty-five and forty degrees in skeletally immature patients. Surgery remains reserved for progressive curves exceeding forty to fifty degrees, often involving posterior spinal fusion with titanium alloy instrumentation. The bracing segment sustains the largest patient volume due to conservative first-line protocols, while the surgery segment captures the dominant share of procedure value through implant-intensive fusion systems. Physical therapy and rehabilitation represent the fastest-expanding category as payers mandate pre-operative optimization and post-operative functional recovery pathways.
The FDA governs spinal implant safety through 510(k) premarket notification and PMA pathways, with ISO 14155 clinical investigation standards shaping trial design for novel devices. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence requirements for CE-marked spinal systems, directly affecting market access timelines for manufacturers. Stakeholders must monitor reimbursement parity between robotic-assisted and conventional open procedures as coverage decisions will determine capital deployment into navigation and planning platforms.
Market Dynamics
Software-enabled surgical planning is compressing decision timelines for deformity correction, forcing device manufacturers to bundle hardware with predictive analytics and remote monitoring capabilities to retain procurement relationships.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for spinal implants compresses development cycles, allowing novel instrumentation to reach pediatric orthopedic centers faster than under PMA requirements.
- Remote patient monitoring platforms:Post-operative telemetry reduces revision rates and readmission penalties, creating reimbursement incentives for integrated care contracts across academic medical centers.
- Physical therapy protocol expansion:Payer mandates for pre-operative optimization and post-surgical rehabilitation extend the addressable patient funnel beyond surgical candidates alone.
Market Restraints
- Titanium alloy supply concentration:Implant-grade Ti-6Al-4V sourcing clusters with limited specialty metallurgy suppliers, exposing manufacturers to input cost volatility and geopolitical disruption.
- EU MDR clinical evidence requirements:Stricter post-market surveillance and extended CE-marking timelines delay market access for novel spinal systems, compressing effective patent life.
- Conservative bracing substitution:Boston brace and Rigo-Cheneau protocols retain strong clinical adherence for curves under forty degrees, limiting surgical conversion in skeletally immature populations.
Strategic Opportunities
- AI-assisted Cobb angle measurement:Machine learning algorithms applied to radiographic analysis reduce inter-observer variability, enabling earlier detection protocols in school screening programs.
- India pediatric orthopedic expansion:Underpenetrated scoliosis correction capacity in tertiary hospitals creates whitespace for training partnerships and equipment leasing models.
- Japan METI aging spine initiative:Government-funded research consortia target adult degenerative scoliosis, opening reimbursement pathways for motion-preserving alternatives to fusion.
Industry Challenges
- Pediatric orthopedic surgeon scarcity:Fellowship-trained deformity specialists cluster at academic hubs, constraining procedure volume expansion into community hospital settings.
- Robotic platform integration complexity:Navigation systems require substantial OR workflow reconfiguration and staff retraining, slowing capital deployment despite demonstrated accuracy gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scoliosis Treatment Market |
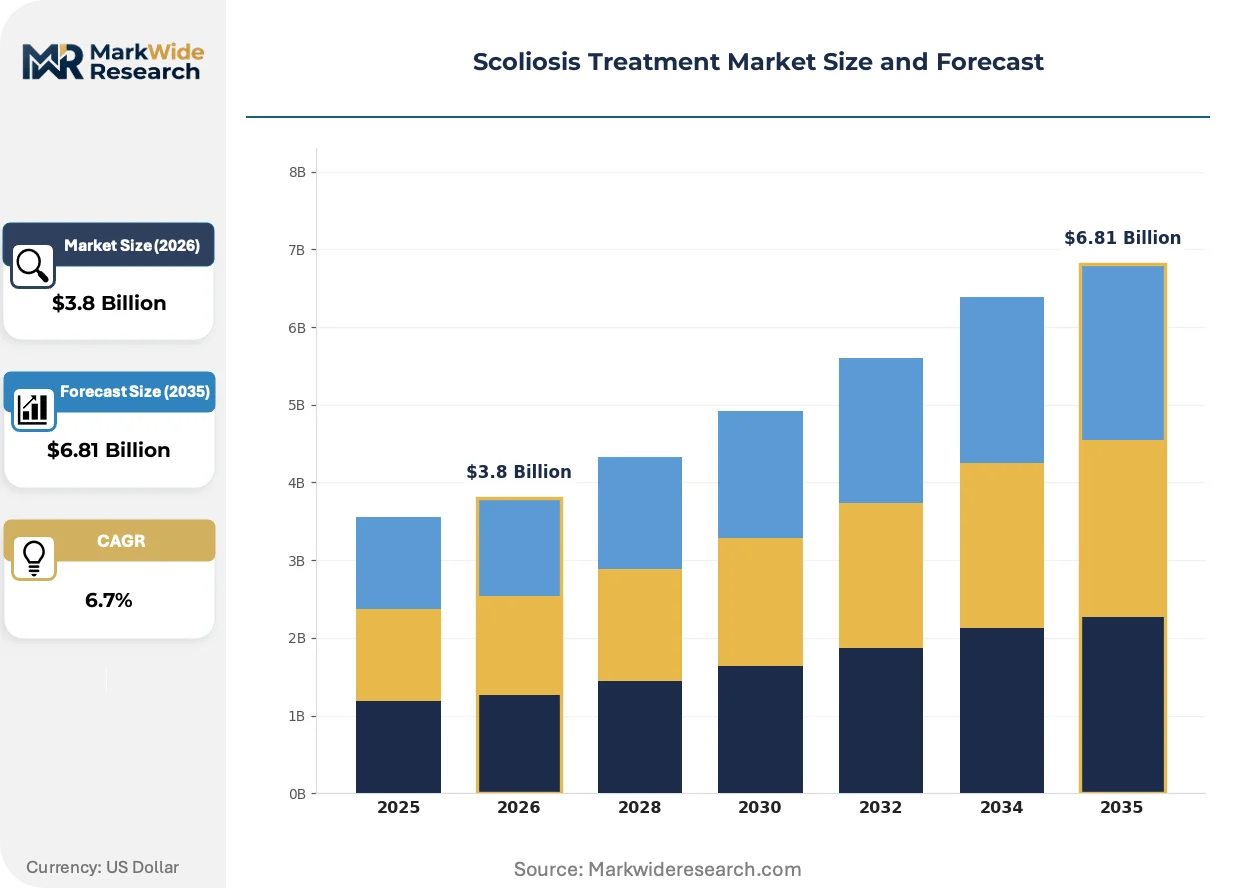
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Bracing, Surgery, Physical Therapy, Rehabilitation Patient Age Group: Pediatric Patients, Adolescents, Adults, Seniors Severity Level: Mild, Moderate, Severe, Progressive Diagnostic Method: X-ray, MRI, CT Scan, Physical Examination |
| Companies Covered | Medtronic, Zimmer Biomet, Stryker Corporation, DePuy Synthes, NuVasive, Orthofix International, Globus Medical, Boston Orthotics & Prosthetics, Aspen Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scoliosis Treatment Market Strategic Shifts
Digital twin modeling of spinal biomechanics is displacing empirical planning, enabling patient-specific rod contouring and screw trajectory optimization before incision. This convergence of imaging, simulation, and additive manufacturing is compressing revision rates while elevating hardware specifications.
Patient-specific 3D-printed titanium instrumentation is rewriting surgical preparation protocols. Deformity centers at Johns Hopkins and Rady Children's Hospital now routinely commission anatomical models and custom bending templates from pre-operative CT datasets. This capability compresses intraoperative fluoroscopy exposure and reduces construct revision rates, though capital requirements limit adoption to high-volume academic sites.
The EU Medical Device Regulation's Annex XVI expansion reclassifies certain software-as-medical-device applications, including automated Cobb angle measurement tools. This creates parallel conformity assessment obligations for algorithm developers previously operating outside CE-marking scope. European pediatric centers now demand MDR-certified planning platforms, filtering vendor participation toward established orthopedic device manufacturers with notified body relationships.
Hospital purchasing committees are unbundling implant procurement from navigation and planning services, treating these as separate capital and operating expenditure lines. This fragmentation favors modular platform architectures over closed ecosystems, particularly in United States health systems facing tightened capital allocation scrutiny. Tier-one academic centers increasingly source hardware from one vendor while contracting analytics and remote monitoring from specialized health IT firms.
Scoliosis Treatment Market Segmentation
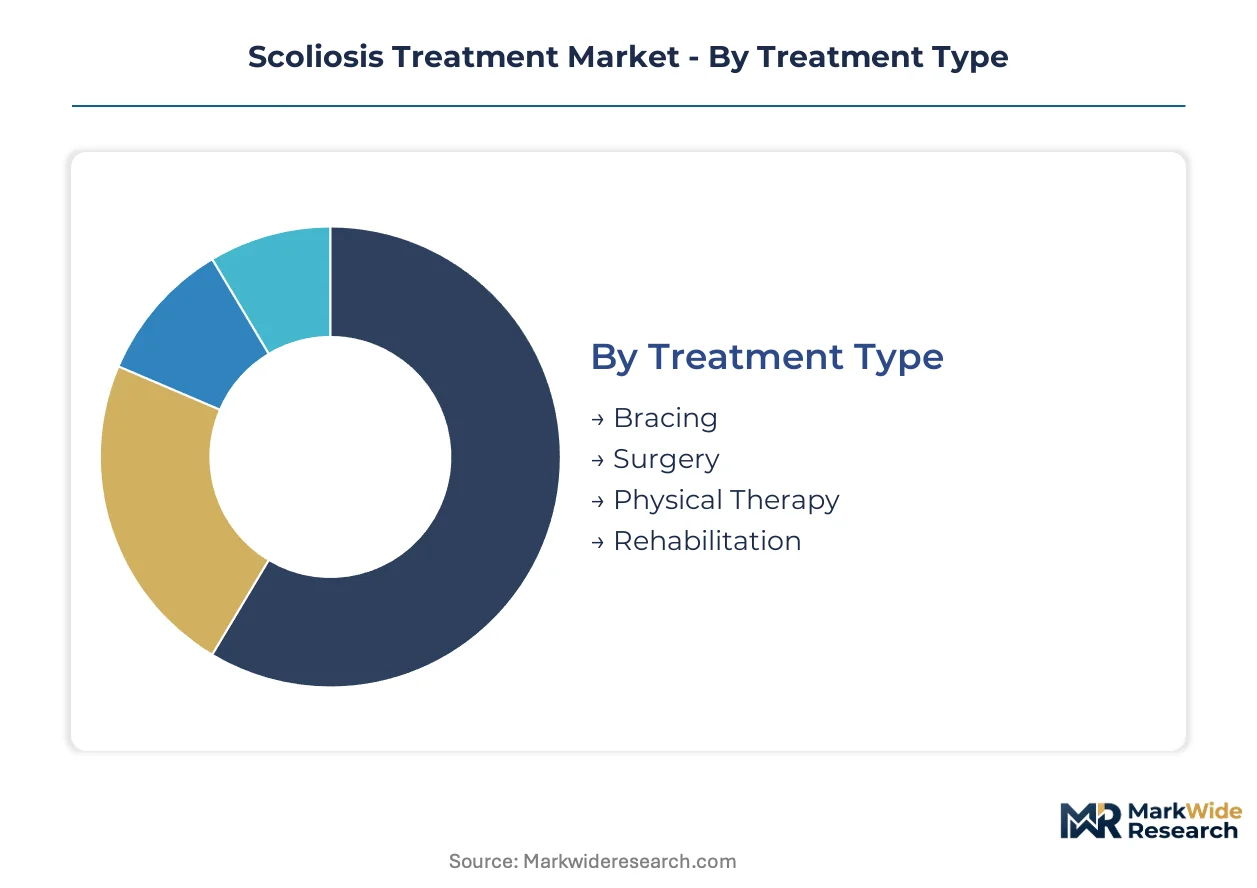
Scoliosis treatment markets fragment across intervention intensity, patient life stage, and diagnostic workflow. Supply chain configuration varies sharply between implant-intensive surgical segments and consumable-driven conservative protocols. Understanding these divisions clarifies where capital deployment concentrates versus where volume expansion occurs.
Treatment Type:
Implant-grade titanium sourcing clusters with limited specialty metallurgy suppliers, exposing surgical segments to input cost volatility while bracing and rehabilitation segments face polymer and composite material constraints.
- Surgery:Posterior spinal fusion with titanium alloy instrumentation dominates procedure value through implant-intensive construct systems. Demand concentrates at academic medical centers in the United States where fellowship-trained deformity specialists cluster, constrained by OR capacity and capital equipment cycles.
- Bracing:Boston brace and Rigo-Cheneau protocols sustain the largest patient volume through conservative first-line prescription for curves between twenty-five and forty degrees. Boston Children's Hospital and Rady Children's Hospital anchor fabrication capacity, with polymer supply chains routing through specialized orthotics manufacturers.
- Physical Therapy:Schroth method and SEAS protocols target muscular imbalance correction through specialized physiotherapist networks.
- Rehabilitation:Post-operative functional recovery programs extend institutional stay revenue through payer-mandated pathways.
Surgery absorbs the bulk of installed capacity; Physical Therapy is expanding most quickly.
Patient Age Group:
Reimbursement intensity varies by skeletal maturity status, with pediatric and adolescent segments commanding premium rates for growth-sparing instrumentation.
- Pediatric Patients:Early-onset scoliosis under age ten demands magnetically controlled growing rods and vertical expandable prosthetic titanium rib systems. Johns Hopkins and Children's Hospital of Philadelphia anchor referral volume, with FDA humanitarian device exemption pathways accelerating novel implant access.
- Adolescents:Idiopathic scoliosis peaks at ages ten to eighteen, driving the highest absolute procedure volume. United States pediatric orthopedic centers cluster screening and bracing protocols around school-based detection programs.
- Adults:Degenerative scoliosis emerges with disc collapse and facet arthropathy, often presenting with radiculopathy requiring decompression.
- Seniors:Osteoporotic bone quality complicates fixation, shifting demand toward cement-augmented screws and less invasive stabilization.
Adolescents capture the dominant share of intervention volume; Seniors present the steepest expansion trajectory as aging demographics reshape case mix.
Severity Level:
Curve magnitude thresholds determine intervention eligibility, with supply chains bifurcating between off-the-shelf bracing components and patient-specific surgical instrumentation.
- Moderate:Curves between twenty-five and forty degrees Cobb angle trigger bracing protocols in skeletally immature patients. Boston brace manufacturing concentrates in specialized orthotics facilities serving United States metropolitan corridors.
- Severe:Curves exceeding fifty degrees typically mandate posterior spinal fusion with segmental instrumentation. Custom rod contouring and screw trajectory planning absorb substantial pre-operative resource allocation.
- Mild:Curves under twenty-five degrees receive observation protocols with periodic radiographic surveillance.
- Progressive:Documented curve progression of five degrees or more between visits escalates intervention intensity regardless of absolute magnitude.
Severe cases command the highest per-patient resource consumption; Progressive classifications are gaining share fastest as monitoring protocols extend detection sensitivity.
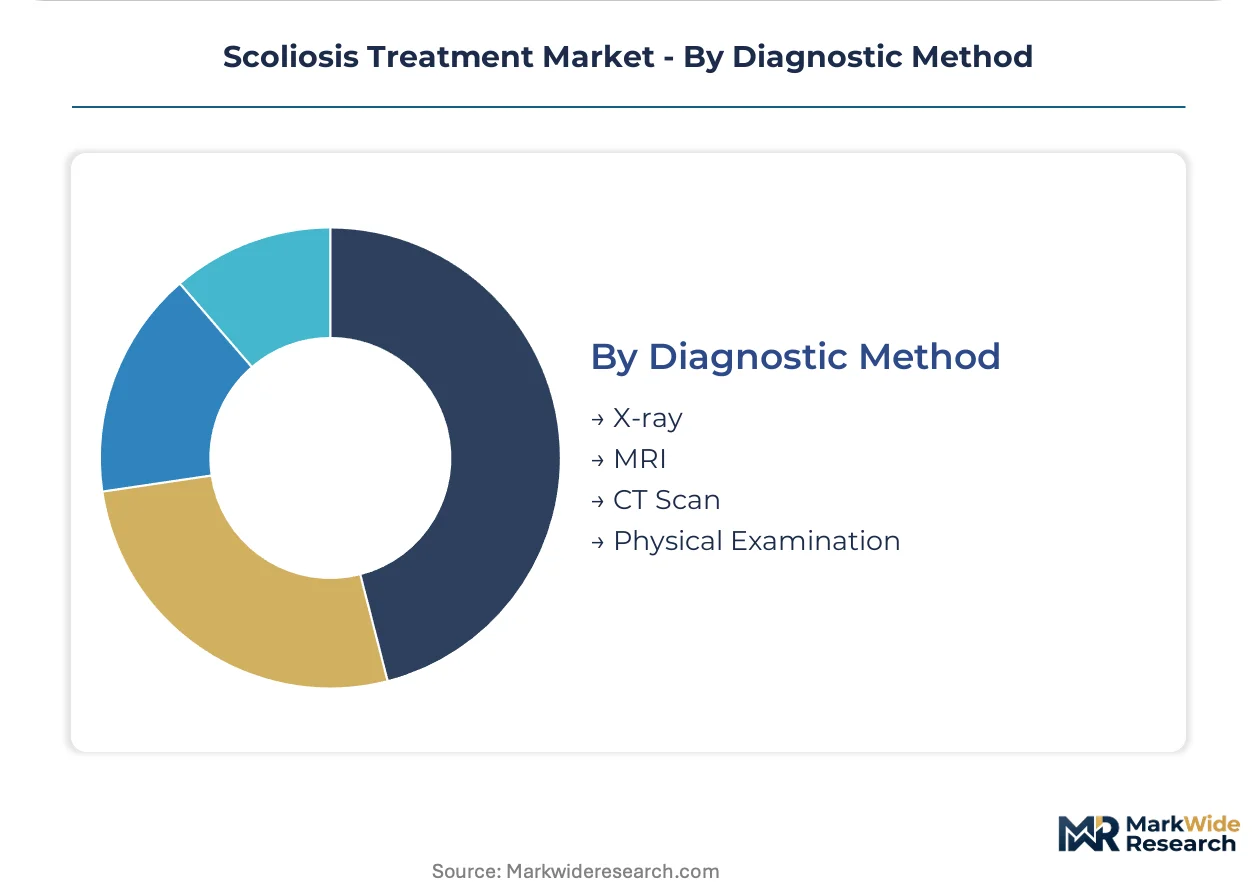
Diagnostic Method:
Radiation exposure concerns and reimbursement parity shape modality selection, with digital workflow integration determining capital deployment patterns.
- X-ray:Standing full-spine radiography remains the reference standard for Cobb angle measurement despite cumulative radiation exposure concerns. United States orthopedic centers deploy EOS low-dose biplanar systems to reduce lifetime exposure burden in pediatric populations.
- MRI:Magnetic resonance imaging excludes intraspinal anomalies in atypical curve patterns and pre-operative neural element assessment. Tertiary centers in Germany and Switzerland anchor high-field system density.
- CT Scan:Pre-operative three-dimensional planning enables patient-specific screw trajectory mapping and rod contouring simulation.
- Physical Examination:Adam's forward bend test and scoliometer measurement anchor school screening and primary care detection protocols.
X-ray retains the dominant installed base; CT Scan is climbing the fastest as surgical planning software tightens integration with additive manufacturing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the dominant share of scoliosis treatment value while manufacturing concentrates among German precision instrument makers and Chinese titanium processors. This production-consumption divide shapes procurement patterns across major orthopedic markets.
United States
Pediatric orthopedic centers at Johns Hopkins and Rady Children's Hospital drive demand for patient-specific instrumentation and robotic navigation platforms. FDA 510(k) premarket notification pathways accelerate device clearance timelines relative to European PMA-equivalent processes. Philadelphia and Boston anchor the highest-density clusters of fellowship-trained deformity specialists, constraining procedure volume expansion into community settings.
Germany
University hospitals in Heidelberg and Munich lead adoption of EOS low-dose biplanar imaging systems for pediatric screening programs. EU Medical Device Regulation Annex XVI reclassifications impose parallel conformity obligations on software-as-medical-device developers. The Baden-Württemberg precision engineering corridor supplies specialized CNC rod-bending equipment to deformity centers across Western Europe.
Japan
Government-funded METI research consortia target adult degenerative scoliosis through motion-preserving alternatives to fusion surgery. PMDA consultation procedures for novel spinal devices compress regulatory timelines for domestic manufacturers. Tokyo and Osaka academic medical centers anchor training partnerships expanding correction capacity into underpenetrated prefectural hospitals.
India
Tertiary hospitals in Maharashtra and Karnataka present whitespace for equipment leasing models and surgeon training partnerships. CDSCO medical device rules impose import licensing requirements on spinal implant distributors that domestic manufacturers circumvent. Delhi-NCR and Chennai pediatric orthopedic departments report capacity constraints against rising adolescent idiopathic case detection.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex deformity surgery at designated supra-regional centers in London and Birmingham. MHRA post-market surveillance requirements align with EU MDR evidence standards despite regulatory divergence. The Oxford-Cambridge-London golden triangle anchors digital health startups developing AI-assisted Cobb angle measurement tools.
Scoliosis Treatment Market Competitive Environment
Top-tier vendors anchor premium positioning through robotics platforms and patient-specific instrumentation, while mid-tier specialists compete on pediatric-focused product lines and regional distribution density. The vendor base stratifies across three tiers: integrated orthopedic conglomerates with spine robotics capabilities, dedicated spinal device manufacturers with minimally invasive specialization, and regional orthotics fabricators serving bracing protocols. Competitive positioning hinges on bundling hardware with surgical planning software and securing procurement relationships at academic medical centers.
Among the integrated orthopedic conglomerates, Medtronic, Zimmer Biomet, and NuVasive occupy positions exemplifying distinct strategic archetypes. Medtronic represents the robotics-anchored tier through its spine platform integration. Zimmer Biomet sits within the pediatric instrumentation specialization vector. NuVasive exemplifies minimally invasive lateral approach positioning for adolescent idiopathic cases. These three companies collectively illustrate how hardware vendors are compressing decision timelines by bundling predictive analytics and remote monitoring capabilities with implant systems.
| Leading Market Players |
|---|
| Medtronic |
| Zimmer Biomet |
| Stryker Corporation |
| DePuy Synthes |
| NuVasive |
| Orthofix International |
| Globus Medical |
| Boston Orthotics & Prosthetics |
| Aspen Medical Products |
| Others |
Value Chain & Pricing Dynamics
EU MDR Annex XVI sustainability and clinical evidence mandates gate qualified supply access and premium-tier pricing eligibility for spinal device manufacturers seeking CE-marked market entry.
Pricing Analysis
Margin tightening in implant-grade titanium instrumentation reflects Ti-6Al-4V feedstock cost volatility and concentrated specialty metallurgy sourcing. Three-tier pricing structure across premium patient-specific systems, standard modular constructs, and economy off-the-shelf components stratifies by customization level and FDA clearance tier. Pricing pressure accelerates in standard segments as hospital purchasing committees unbundle hardware from navigation services. Academic medical centers demonstrate lowest price sensitivity; community hospitals facing capital allocation scrutiny exhibit highest.
Supply Chain Analysis
Workforce availability constraints in German precision engineering corridors and Chinese titanium processing hubs shape manufacturing capacity for spinal instrumentation. Implant-grade Ti-6Al-4V draws from limited specialty metallurgy suppliers; polymer composites for bracing anchor in United States orthotics fabrication networks. Single-source vulnerability concentrates in aerospace-qualified titanium mills. Distribution runs through specialized orthopedic device distributors serving academic medical centers and GPO-contracted health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors bundling surgical planning software with implant hardware, with EU MDR compliance costs forcing sub-scale orthopedics manufacturers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into implant-grade titanium feedstock to insulate margin structures from aerospace mill pricing volatility. Fortify notified body relationships for EU MDR Annex XVI software reclassifications before algorithm developers capture planning platform share. Priority levers include captive metallurgy sourcing and MDR certification investment. For New Entrants and Emerging Players: Direct-to-surgeon digital training platforms offer lower-friction entry than capital-intensive implant manufacturing. Target underpenetrated Indian tertiary hospitals through equipment leasing and remote proctoring partnerships. White-space concentrates in AI-assisted Cobb angle screening tools awaiting FDA 510(k) and MDR certification. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for patient-specific 3D-printed instrumentation is the leading indicator that surgical planning software valuations will detach from hardware multiples. Long-term viability favors platforms with bundled analytics and remote monitoring capabilities. Acquisition targets include MDR-ready algorithm developers and pediatric-focused orthotics fabricators with established hospital relationships.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Annex XVI software reclassifications demand notified body relationships for algorithm developers. |
| Hospital System Partnership | Bundled care contracts at Johns Hopkins and Rady Children's anchor premium positioning. |
| Software Companion Development | Digital twin modeling and remote monitoring differentiate implant procurement beyond hardware. |
| Backward Integration into Titanium | Captive Ti-6Al-4V sourcing mitigates aerospace mill pricing volatility and supply disruption. |
| Reimbursement Strategy | Parity between robotic-assisted and conventional procedures determines navigation platform deployment. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures, complemented by interviews with pediatric orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and spinal device regulatory affairs leads. Secondary sources included CMS Medicare reimbursement data, ISO 14155 clinical investigation standards, and titanium trade flow records. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated for segmentation calibration.
Market size outputs and growth trajectories across the projection horizon reflect procedure volume modeling by treatment type, patient age group, severity level, and diagnostic method, with geographic regulatory clusters as an additional dimension. CAGRs were derived from installed base expansion rates, replacement cycles, and pricing trend assumptions. Forecast inputs incorporated FDA clearance timelines, EU MDR transition schedules, and pediatric orthopedic surgeon fellowship pipeline data.
The model holds under stable regulatory pathways and reimbursement parity; deviation in FDA 510(k) enforcement discretion, EU MDR notified body capacity, or titanium supply chain disruption would shift volume and value projections. Forecasts reflect documented assumptions regarding procedure migration patterns and software adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Spinal Pumps Market