
 South Korea Parcel Delivery Market | 2026-2036
South Korea Parcel Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Parcel Delivery Market Insights
Market Context
MFDS enforcement of cold-chain integrity standards for pharmaceutical parcels is hardening compliance costs for new entrants. CJ Logistics leverages its nationwide hub network to sustain temperature-controlled capacity across last-mile routes. Hyundai Glovis anchors automotive parts delivery with dedicated fleet assets. Korea Post competes on universal service obligations while navigating rural cost structures.
Technical Definition and Segment Structure
South Korea parcel delivery encompasses the collection, sortation, line-haul transport, and final distribution of packaged goods weighing under 30 kilograms, utilizing barcode scanning, automated sortation, and route-optimization algorithms to achieve next-day or same-day service commitments. The primary commercial purpose is bridging the fulfillment gap between e-commerce sellers and end consumers in a market where mobile ordering penetration exceeds most OECD peers. Express delivery dominates revenue pools due to premium pricing for speed-guaranteed service, while same-day delivery represents the fastest-expanding segment as quick-commerce platforms pressure carriers to compress cycle times. Locker pickup is maturing as a density play in apartment complexes, though door-to-door retains margin concentration in B2B corporate contracts.
Regulatory Frame and Outlook
MFDS, the Ministry of Employment and Labor, and the Personal Information Protection Commission collectively shape carrier operations through pharmaceutical handling rules, driver working-hour caps, and delivery data privacy requirements. The Ministry of Land, Infrastructure and Transport's urban logistics zone designations directly determine where automated sorting facilities and electric vehicle depots can deploy. Stakeholders must monitor whether drone delivery corridor approvals accelerate beyond current pilot zones or stall under aviation safety review.
Market Dynamics
The Ministry of Land, Infrastructure and Transport's logistics automation mandates are forcing carriers to retrofit legacy sortation infrastructure with robotic systems and electric vehicle fleets before compliance deadlines.
Growth Catalysts
- E-commerce fulfillment density:Mobile-first retail platforms generate parcel volumes that saturate existing last-mile capacity in Seoul and Busan metropolitan zones.
- MFDS cold-chain mandates:Pharmaceutical integrity standards create specialized handling requirements that premium carriers monetize through temperature-guaranteed service tiers.
- Quick-commerce velocity expectations:30-minute grocery delivery platforms compress cycle-time benchmarks across the entire carrier network.
Market Restraints
- Driver hour caps:The Ministry of Employment and Labor's working-time regulations constrain fleet utilization rates during peak volume windows.
- Seoul-Gyeonggi corridor congestion:Road infrastructure saturation in the capital region extends transit times and fuel burn disproportionately.
- Apartment complex access friction:Security protocols and elevator capacity limits create last-mile handoff delays in high-rise residential clusters.
Strategic Opportunities
- Drone corridor expansion:Ministry of Land, Infrastructure and Transport pilot zones on Jeju Island and rural Gangwon province test beyond-visual-line-of-sight regulations for island and mountain delivery.
- Locker network densification:Unattended pickup infrastructure in new apartment developments reduces failed delivery attempts and driver redispatch costs.
- Reverse logistics monetization:E-commerce return volumes create incremental revenue streams through consolidated collection routing.
Industry Challenges
- Automation technician scarcity:Robotic sortation maintenance requires mechatronics skills that outpace vocational training pipeline output.
- Legacy system integration:Carrier ERP platforms must interface with marketplace order management APIs without disrupting real-time tracking reliability.
Report Scope
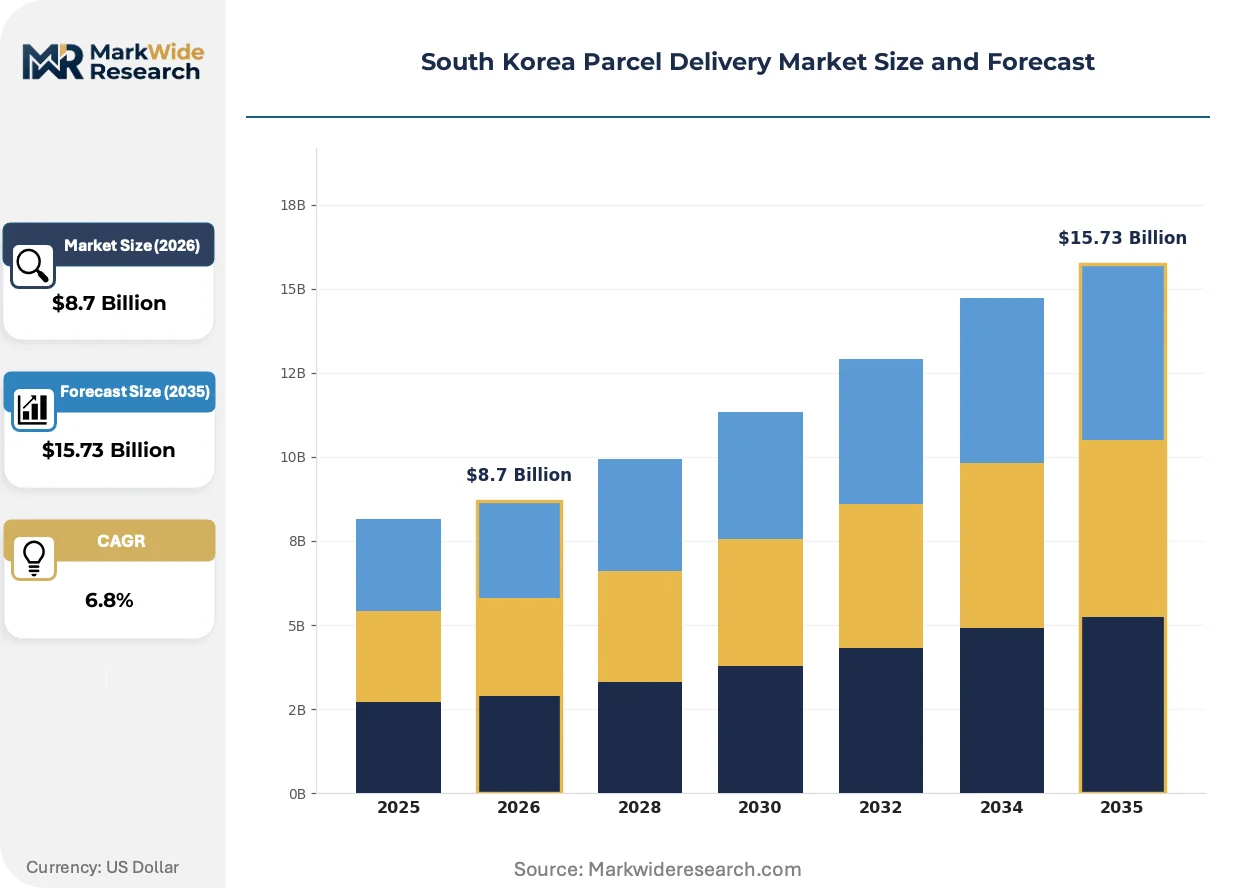
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Parcel Delivery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Same-Day Delivery, Scheduled Delivery, International Shipping Customer Type: Retail Customers, E-commerce Businesses, Corporate Clients, Small Enterprises Delivery Mode: Door-to-Door, Locker Pickup, In-Store Pickup, Drone Delivery Package Size: Small Packages, Medium Packages, Large Packages, Oversized Items |
| Companies Covered | Logen Logistics, Hyundai Glovis, CJ Logistics, Daesin Logistics, Dongbu Express, Korea Post, Lotte Global Logistics, FedEx, Hanjin Transportation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Parcel Delivery Market Trends and Innovations
Parcel delivery infrastructure is bifurcating between hyperlocal micro-fulfillment nodes and centralized automated hubs, with carriers betting on diverging capital deployment strategies.
Autonomous mobile robots in sortation facilities are decentralizing parcel handling from fixed conveyor belts to flexible zone-based processing. CJ Logistics and Lotte Global Logistics deploy AMR fleets that reconfigure floor layouts based on daily volume patterns. This shift is decentralizing hub economics toward smaller, adaptive facilities that reduce line-haul distances to last-mile depots.
MFDS pharmaceutical transport certification requirements are hardening cold-chain documentation standards for biologics and vaccines. Carriers must deploy continuous temperature monitoring with blockchain-anchored custody records. Temperature-sensitive B2B contracts now require dedicated refrigerated vehicle pools that lock out general freight operators lacking MFDS accreditation.
Subscription-based delivery passes are displacing per-shipment pricing for heavy e-commerce users. Coupang and Naver Shopping bundle unlimited delivery into membership tiers that shift carrier revenue toward fixed-fee structures. This pattern concentrates volume with integrated platform-owned logistics arms while pressuring independent carriers to match service levels at compressed unit economics.
South Korea Parcel Delivery Market Segmentation
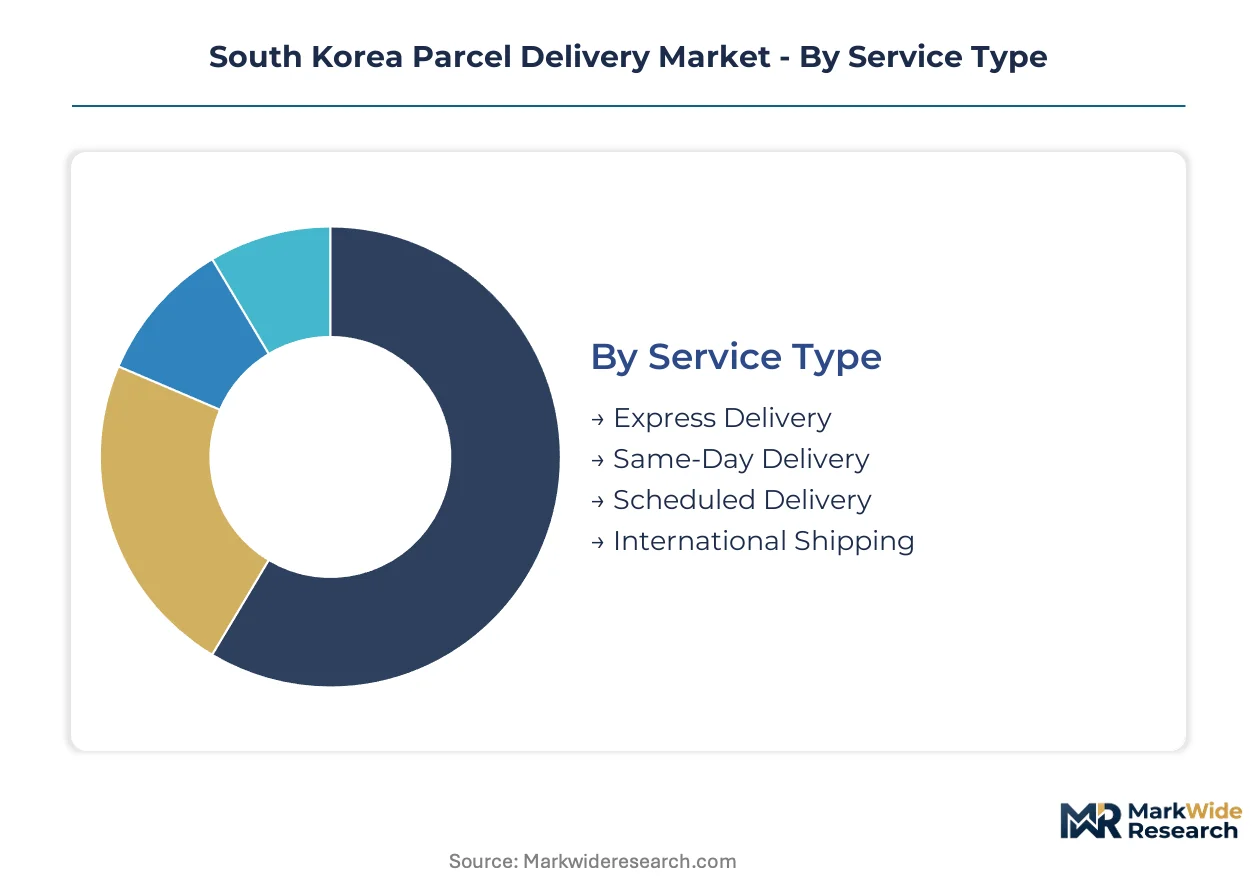
Service differentiation in South Korea's parcel market reflects divergent buyer willingness to pay for velocity and reliability. Carrier profitability hinges on matching infrastructure deployment to the specific cost-to-serve economics of each segment combination.
Service Type:
Speed expectations separate premium buyers from cost-sensitive shippers across Seoul and Busan corridors.
- Express Delivery:Next-day guaranteed service with barcode-tracked custody chains commands the highest unit economics. Corporate contract demand in Gangnam and Yeouido financial districts sustains dedicated fleet allocation during peak windows.
- Same-Day Delivery:Compressed cycle-time fulfillment requires micro-fulfillment node proximity to dense residential clusters. Quick-commerce platforms in Gyeonggi province are forcing carriers to reposition inventory within 10-kilometer radii of major apartment complexes.
- Scheduled Delivery:Appointment-based arrival windows reduce failed delivery costs for bulky items. Furniture and appliance retailers leverage this tier to coordinate installation crew dispatch.
- International Shipping:Customs brokerage integration and Incheon Airport cargo capacity determine competitive positioning. Cross-border e-commerce sellers to Southeast Asia drive volume concentration.
Volume sits with Express Delivery; growth tilts toward Same-Day Delivery.
Customer Type:
Account scale dictates whether carriers pursue direct relationships or platform-mediated access.
- Retail Customers:Individual senders with sporadic, low-weight shipments generate the highest per-unit acquisition costs. Mobile app onboarding and convenience store drop-off networks reduce friction in this fragmented base.
- E-commerce Businesses:High-frequency, predictable volume from marketplace sellers enables route-density optimization. Coupang and Naver Shopping integration requirements force API standardization investments.
- Corporate Clients:B2B contracts with manufacturing and financial services demand SLA-backed performance guarantees. Dedicated account management and customized reporting justify retention spending.
- Small Enterprises:Local retailers and service businesses exhibit price elasticity and limited shipment frequency. Aggregator platforms capture this segment through pooled pricing structures.
Revenue concentrates with E-commerce Businesses; margin expansion targets Corporate Clients.
Delivery Mode:
Final-handoff infrastructure choices reshape driver productivity and customer convenience trade-offs.
- Door-to-Door:Direct residential delivery retains premium pricing power but faces apartment access friction. Elevator wait times and security gate protocols compress daily drop counts in high-rise districts.
- Locker Pickup:Unattended collection points in apartment lobbies and convenience stores reduce redispatch costs. New residential development mandates in Seoul metropolitan area accelerate deployment density.
- In-Store Pickup:Retail partner locations extend carrier reach without dedicated fleet expansion. Emart and CU convenience store networks provide established pickup infrastructure.
- Drone Delivery:Beyond-visual-line-of-sight trials on Jeju Island test regulatory tolerance for automated aerial distribution. Mountainous terrain and island geography create use cases where ground delivery costs exceed aerial alternatives.
Door-to-Door dominates current volume; Locker Pickup shows steepest expansion trajectory.
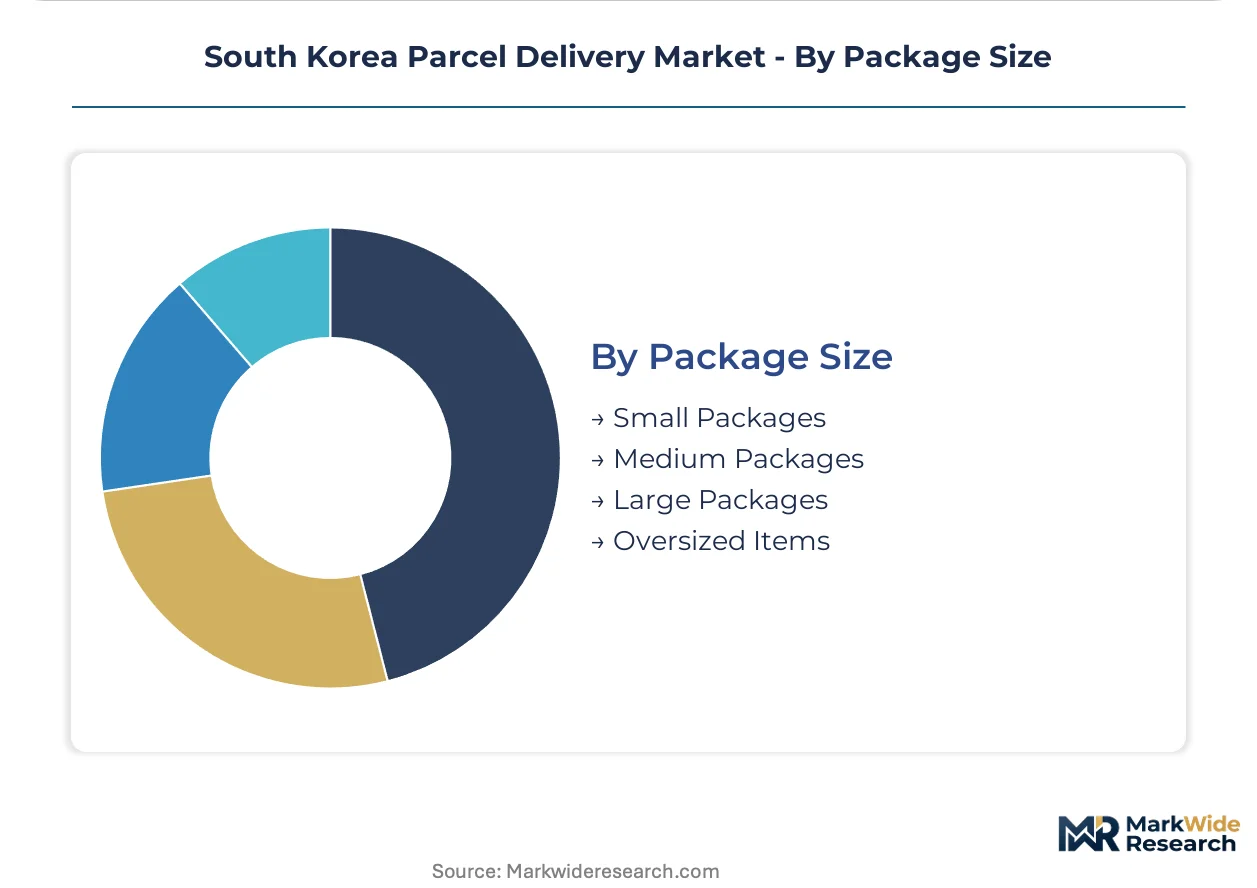
Package Size:
Dimensional weight pricing and handling automation requirements segment operational capabilities.
- Small Packages:Items under 2 kilograms fit automated sortation conveyors and standard delivery pouches. Mobile commerce accessories and cosmetics drive the highest shipment frequency.
- Medium Packages:The 2-10 kilogram bracket captures apparel, electronics, and household goods bulk. This tier balances sortation efficiency with sufficient revenue per piece to cover last-mile costs.
- Large Packages:Furniture, appliances, and bulk consumables require two-person handling and specialized vehicle configurations. Installation service bundling differentiates carrier offerings.
- Oversized Items:Exceeding standard conveyor dimensions, these shipments bypass automated hubs for manual processing. Flat-rate pricing pressure from e-commerce platforms squeezes profitability.
Medium Packages anchor operational scale; Large Packages attract premium service development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area's logistics automation tax incentives and Gyeonggi province fulfillment center clustering concentrate parcel volume and carrier capital deployment. MFDS cold-chain mandates and Ministry of Employment and Labor driver hour caps reshape operational economics across all sub-regions.
Seoul Capital Area
E-commerce platform fulfillment density and quick-commerce micro-fulfillment nodes drive parcel saturation in Gangnam and Yeouido corridors. The Ministry of Land, Infrastructure and Transport's urban logistics zone designations determine where automated sorting facilities and electric vehicle depots deploy. Apartment complex locker mandates in Songpa and Mapo districts accelerate unattended pickup infrastructure density.
Busan-Ulsan
Port-centric international shipping volumes and cross-border e-commerce export flows anchor carrier customs brokerage investments. MFDS pharmaceutical export certification requirements harden cold-chain documentation standards for biologics transiting through Busan Port. The Busan-Jinhae logistics belt concentrates temperature-controlled warehousing capacity serving Southeast Asian trade lanes.
Daegu-Gyeongbuk
Textile and electronics manufacturing clusters generate B2B parcel flows with SLA-backed performance requirements. The Ministry of Employment and Labor's regional working-time enforcement creates driver utilization constraints during peak export windows. Daegu's Seongseo Industrial Complex anchors dedicated fleet allocation for automotive parts suppliers.
Daejeon-Sejong
Government administrative district concentration and public procurement logistics sustain steady B2B parcel demand. The Sejong smart city initiative tests drone delivery corridors and autonomous vehicle last-mile pilots under Ministry of Land, Infrastructure and Transport oversight. Daejeon's central highway junction position optimizes line-haul transit times to both Seoul and Busan corridors.
Gwangju-Honam
Agricultural product e-commerce platforms and regional food delivery services expand same-day delivery requirements. Rural route density challenges and aging driver demographics pressure carrier cost structures in Jeollanam-do hinterlands. The Gwangju metropolitan area's new apartment developments incorporate mandatory parcel locker installations under revised building codes.
South Korea Parcel Delivery Market Competitive Landscape
Seoul-based integrated logistics groups anchor the premium service tier; regional specialists and platform-captive operators hold differentiated positions in cost-sensitive segments. Market structure tilts toward consolidation as automation capital requirements and regulatory compliance costs squeeze sub-scale carriers. Three archetypes dominate: nationwide hub-network operators with cold-chain certification, platform-integrated delivery arms with captive volume, and niche specialists in pharmaceutical or automotive verticals. Dominant competitive moves include hub automation retrofitting and electric vehicle fleet conversion ahead of Ministry of Land, Infrastructure and Transport mandates.
Within the nationwide hub-network tier, CJ Logistics and Lotte Global Logistics exemplify carriers leveraging scale to absorb automation capital burdens and sustain temperature-controlled capacity across last-mile routes. Hyundai Glovis occupies a position as the automotive vertical anchor, with dedicated fleet assets serving parts delivery requirements. Korea Post represents the universal service obligation archetype, navigating rural cost structures while competing on coverage breadth rather than velocity premiums.
| Leading Market Players |
|---|
| Logen Logistics |
| Hyundai Glovis |
| CJ Logistics |
| Daesin Logistics |
| Dongbu Express |
| Korea Post |
| Lotte Global Logistics |
| FedEx |
| Hanjin Transportation |
| Others |
Pricing and Supply Chain Analysis
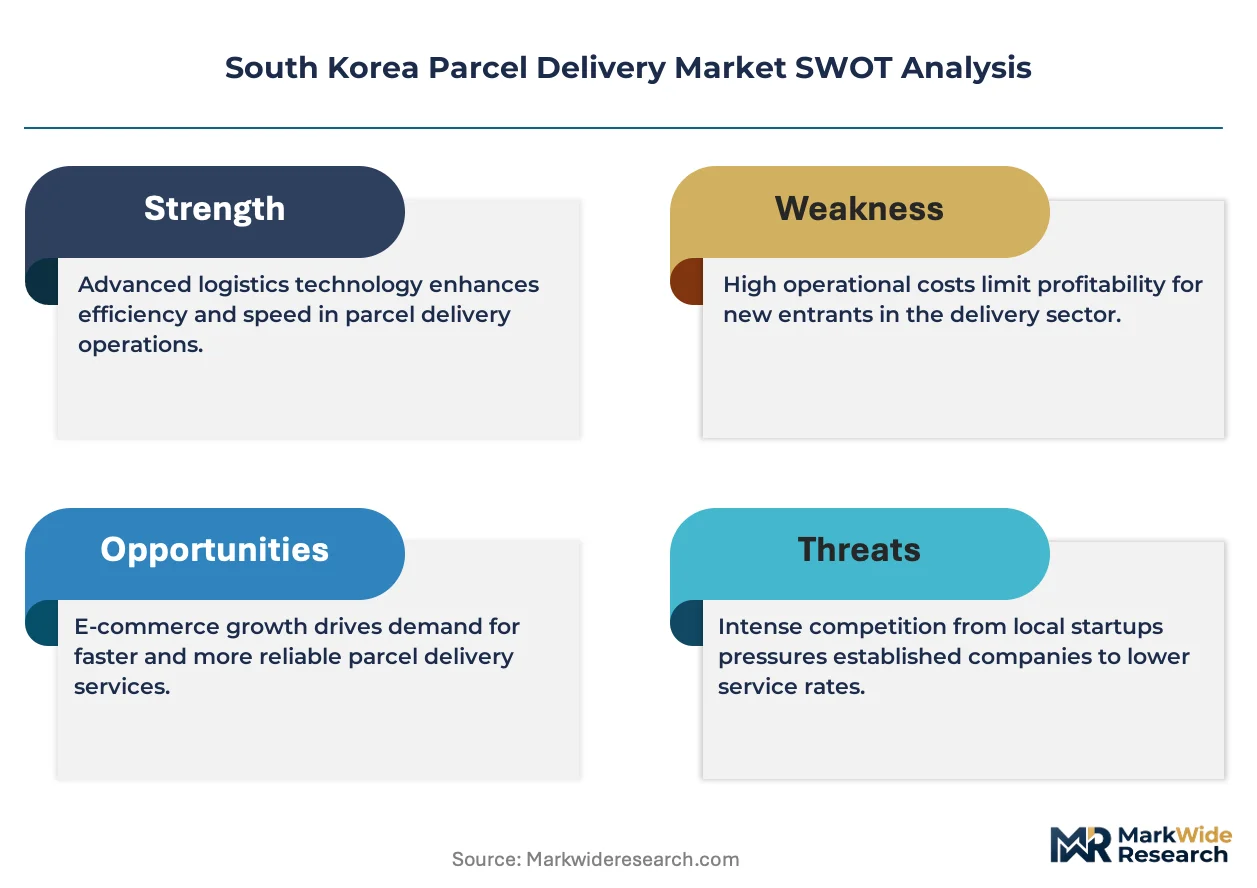
Family-owned logistics conglomerates anchored in Seoul and Busan preserve pricing discipline through captive hub networks while resisting margin erosion from platform-owned delivery arms. Their multi-decade facility ownership patterns insulate sortation economics from third-party warehousing cost volatility.
Pricing Analysis
Lead-time-driven pricing separates guaranteed next-day service premiums from deferred economy tiers in parcel contracts. Three-tier pricing structure across premium, standard, and economy levels captures divergent shipper willingness to pay for velocity certainty. Price differentiation rests on temperature certification grade and volume scale commitments in B2B pharmaceutical contracts. Cost compression in economy tiers is intensifying because quick-commerce platforms bundle delivery into membership fees. Small enterprises exhibit highest price sensitivity while corporate clients with SLA requirements show lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Gyeonggi province anchor hub-and-spoke patterns feeding last-mile depots across Seoul metropolitan corridors. Geographic supply concentration centers on South Korea domestic manufacturing, with secondary dependencies on Chinese electronics components and Southeast Asian packaging materials. Raw material inputs draw from polyethylene film suppliers, corrugated cardboard producers, and electric vehicle battery manufacturers for fleet conversion. Single-source vulnerability in automated sortation equipment creates procurement risk. Distribution runs through carrier-operated line-haul networks terminating at apartment complex lockers and convenience store partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's parcel delivery sector sits in an automation-transition phase as autonomous mobile robots displace fixed conveyor infrastructure in legacy hubs.
For Market Incumbents: Deploy electric vehicle fleet conversion ahead of Ministry of Land, Infrastructure and Transport mandates to secure operational continuity. Retrofit existing sortation hubs with robotic systems before compliance deadlines harden. Platform-owned logistics arms threaten volume concentration; defend through cold-chain certification investments that lock out general freight competitors. For New Entrants and Emerging Players: Convenience store networks offer established pickup infrastructure without dedicated depot capital. Rural Jeollanam-do routes present underpenetrated corridors where aging driver demographics create service gaps. Target pharmaceutical verticals requiring MFDS temperature accreditation that incumbent generalists lack. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional carriers in Gwangju-Honam corridor facing automation capital burdens. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than pure scale. Monitor drone delivery corridor approvals on Jeju Island as inflection indicator for aerial last-mile economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Hub Retrofit | Ministry of Land, Infrastructure and Transport mandates force robotic sortation deployment before compliance deadlines. |
| Electric Fleet Conversion | Carbon reduction targets and urban logistics zone designations accelerate depot electrification requirements. |
| Cold-Chain Certification | MFDS pharmaceutical transport rules create defensible moats against general freight competitors. |
| Locker Network Densification | Seoul metropolitan building codes mandate parcel locker installation in new apartment developments. |
| Drone Corridor Expansion | Beyond-visual-line-of-sight trials on Jeju Island test regulatory tolerance for automated aerial distribution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Korea parcel delivery analysis. Primary interviews with carrier operations directors, e-commerce platform logistics managers, and Ministry of Land, Infrastructure and Transport officials combined with secondary validation from Korea Logistics Association statistics and MFDS pharmaceutical transport guidelines. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Segment-level granularity modeled service type, customer category, delivery mode, and package size dimensions across the projection horizon. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated e-commerce penetration curves, automation capital expenditure cycles, and electric vehicle fleet replacement schedules.
Several conditions sit outside the modeled scope, including potential drone delivery regulatory reversals and abrupt platform logistics arm consolidation. Forecasts reflect base-case assumptions about Ministry of Employment and Labor driver hour enforcement and fuel cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market