
 Asean Freight and Logistics Market | 2026-2036
Asean Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
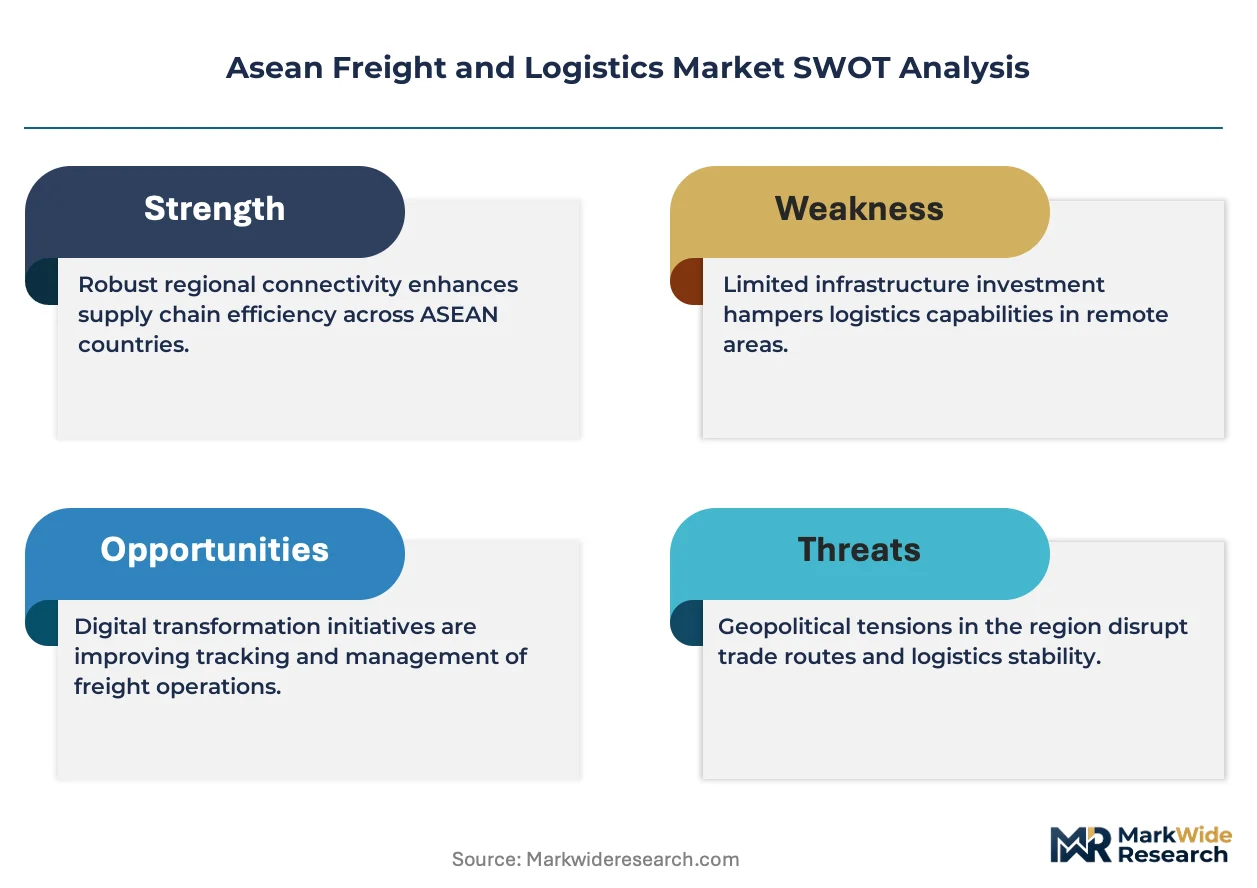
Asean Freight and Logistics Market Outlook
Cross-border trucking corridors between Thailand, Vietnam, and Malaysia are narrowing as customs harmonization under the ASEAN Single Window accelerates clearance speeds. DHL Group leverages its bonded warehouse network to anchor premium express lanes across the Mekong sub-region. Kerry Logistics competes through port-centric distribution parks in Indonesia and the Philippines. SF Express extends its air-ground intermodal footprint to capture intra-ASEAN e-commerce parcel flows.
Asean freight and logistics encompasses the physical movement, storage, and coordination of goods across multimodal networks spanning road, sea, air, and rail infrastructure, typically operating within temperature bands of minus 25°C to ambient for specialized cargo and requiring customs brokerage integration for cross-border legality. Its primary commercial purpose is reducing inventory carrying costs while meeting delivery windows for manufacturers and retailers operating just-in-time supply chains. Freight forwarding commands disproportionate margin capture due to documentation complexity and carrier rate arbitrage across fragmented ASEAN flag fleets. Road freight dominates volume throughput owing to archipelagic geography and underdeveloped rail trunk lines outside Thailand and Malaysia. E-commerce end users are restructuring warehousing demand toward micro-fulfillment nodes in Jakarta, Bangkok, and Ho Chi Minh City.
ASEAN Secretariat trade facilitation protocols, Thailand's Department of Land Transport weight-bridge enforcement, and Indonesia's Ministry of Transportation domestic cabotage rules collectively shape fleet specifications, cross-border permit quotas, and foreign operator market access. Vietnam's Ministry of Finance customs valuation directives are tightening transfer-pricing scrutiny on logistics contract structures. Stakeholders must monitor which ASEAN member states advance mutual recognition agreements for driver qualifications and vehicle safety standards, as these will determine corridor economics and fleet deployment priorities.
Market Dynamics
ASEAN Single Window protocols are compressing customs clearance windows from days to hours, forcing freight operators to restructure bonded warehouse networks and cross-border fleet deployment around real-time data visibility rather than buffer inventory.
Growth Catalysts
- E-commerce fulfillment density:Jakarta, Bangkok, and Ho Chi Minh City micro-fulfillment nodes are absorbing warehouse investment as same-day delivery expectations harden.
- ASEAN Single Window harmonization:Cross-border permit quotas and customs documentation standardization is reducing trucking corridor friction between Thailand, Vietnam, and Malaysia.
- Domestic cabotage liberalization:Indonesia's Ministry of Transportation rules are opening intra-archipelago shipping lanes to foreign-flag vessel participation.
Market Restraints
- Fuel cost volatility:Diesel price swings compress road freight margins across archipelagic routes where modal substitution remains impractical.
- Driver qualification fragmentation:Absence of mutual recognition agreements for commercial licenses forces redundant certification across Thailand, Malaysia, and Vietnam corridors.
- Port concentration risk:Singapore and Tanjung Pelepas handle disproportionate transshipment volume, creating single-point vulnerability for ASEAN-wide supply chains.
Strategic Opportunities
- Laos-Cambodia corridor development:Mekong sub-region road-rail intermodal gaps present first-mover advantage for bonded logistics park investment.
- Cold chain pharmaceutical distribution:Temperature-controlled last-mile networks for vaccines and biologics remain underdeveloped outside Jakarta and Manila.
- Digital freight matching platforms:Real-time load-truck pairing algorithms are penetrating ASEAN road haulage at subscale, creating platform consolidation potential.
Industry Challenges
- Customs valuation scrutiny:Vietnam's Ministry of Finance transfer-pricing directives are forcing logistics contract restructuring and documentation depth upgrades.
- Legacy warehouse management system integration:Real-time inventory visibility requirements clash with on-premise ERP architectures prevalent in Indonesian and Philippine distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asean Freight and Logistics Market |
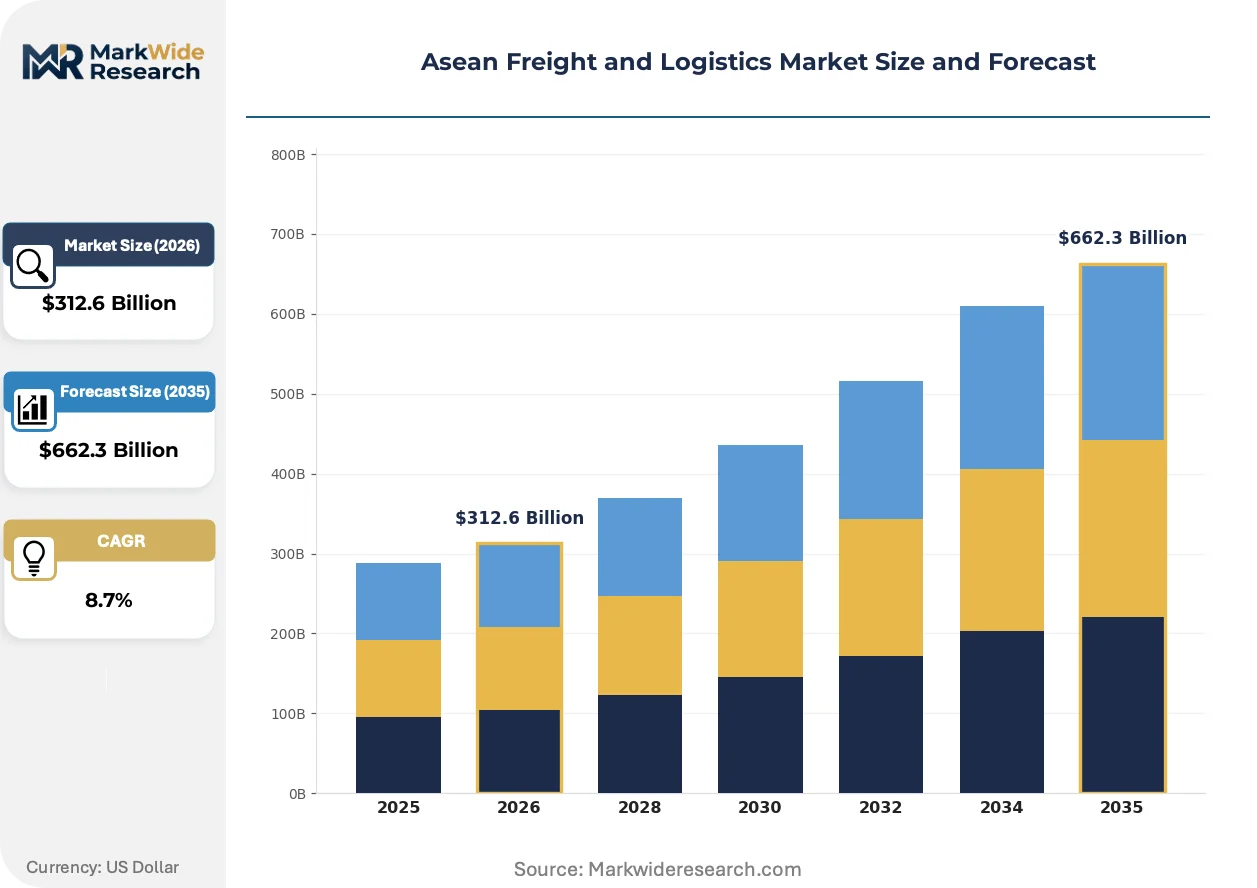
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding End User: Manufacturers, Retailers, E-Commerce, Food & Beverage Delivery Mode: Road, Rail, Air, Sea Capacity: Small Scale, Medium Scale, Large Scale, Bulk |
| Companies Covered | DHL Group, DSV A/S, Kuehne+Nagel, A.P. Moller - Maersk, SF Express, Kerry Logistics, Tiong Nam Logistics Holdings Bhd, YCH Group, CJ Logistics, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asean Freight and Logistics Market Strategic Shifts
Digital freight platforms and automated customs interfaces are compressing transaction friction across ASEAN multimodal networks, while sustainability disclosure requirements reshape fleet procurement criteria and warehouse energy specifications.
Blockchain-enabled bill-of-lading documentation is rendering obsolete paper-based customs submission workflows that previously required physical presence at port authority offices. Indonesian and Vietnamese freight forwarders with bonded warehouse networks are adopting distributed ledger verification for cross-border trucking manifests. This compression of documentation latency is rendering obsolete the competitive advantage of established brokers who previously captured margin through document processing speed.
Thailand's Department of Land Transport weight-bridge enforcement mandates are tightening axle-load compliance and forcing fleet renewal toward lighter composite chassis configurations. Road freight operators face accelerated depreciation schedules on non-compliant tractor units. Malaysian and Vietnamese cross-border carriers are responding with telematics-based load distribution monitoring to preempt enforcement penalties.
Shippers are consolidating vendor relationships around integrated logistics providers capable of warehouse-to-last-mile execution within single contract frameworks. Fragmented freight forwarding and standalone trucking arrangements are losing share to operators with captive distribution park assets. This consolidation pattern is most visible in Indonesian consumer goods distribution, where manufacturers are reducing forwarder counts from dozens to single-digit preferred partnerships.
Asean Freight and Logistics Market Segmentation
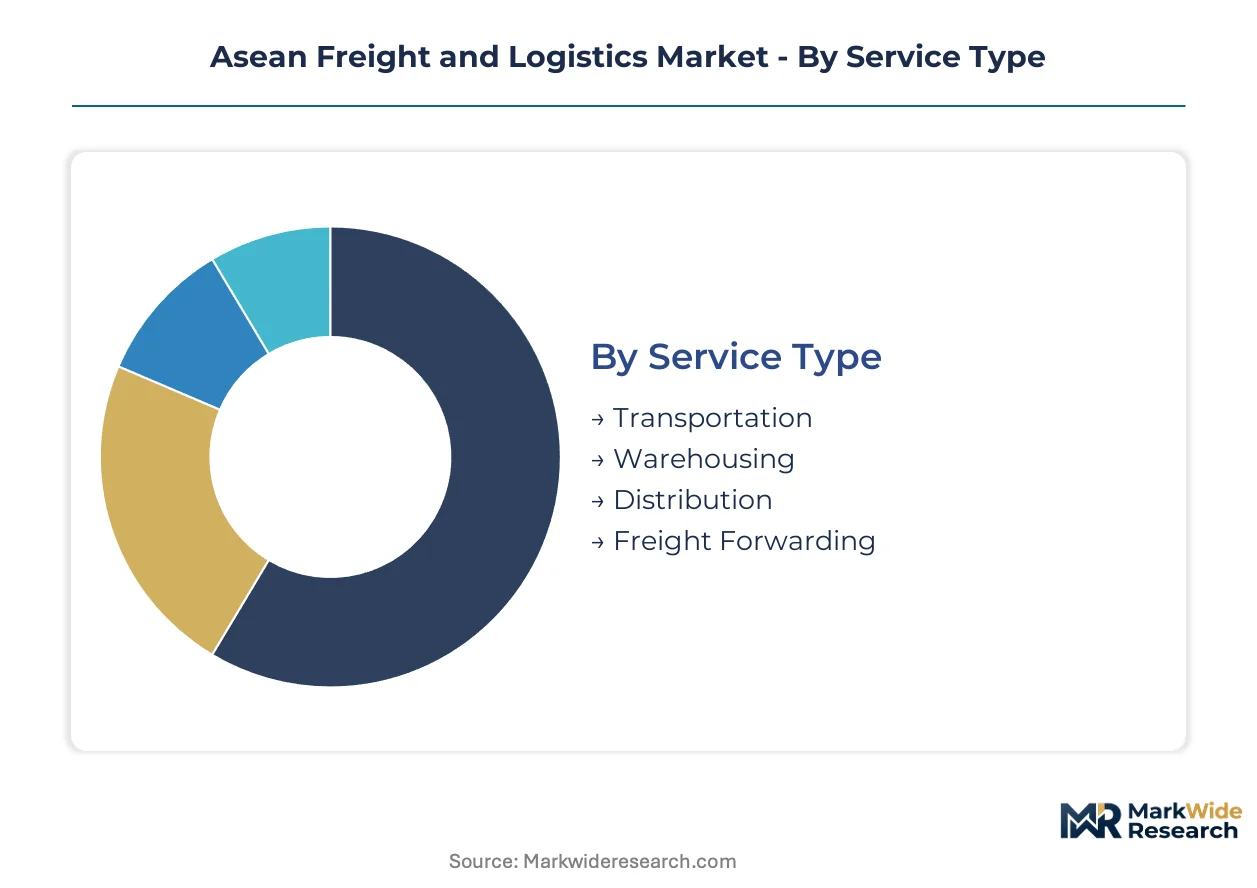
Segmentation in ASEAN freight and logistics reveals how service specialization, infrastructure constraints, and customer scale reshape procurement patterns. Each dimension exposes distinct margin structures and capital deployment requirements across archipelagic and continental sub-regions.
Service Type:
After-sales service intensity varies sharply across logistics functions, with asset-heavy segments demanding sustained maintenance networks and asset-light services relying on relationship management.
- Transportation:Fleet ownership and driver management dominate operating models, with diesel-powered road haulage absorbing the majority of intra-ASEAN ton-kilometers. Indonesian domestic lanes and Thailand-Vietnam corridors concentrate demand as manufacturers relocate production to lower-cost manufacturing zones.
- Warehousing:Temperature-controlled facilities and automated storage systems define competitive differentiation, particularly for pharmaceutical and electronics inventories. Jakarta, Bangkok, and Ho Chi Minh City micro-fulfillment nodes are absorbing investment as same-day delivery expectations harden.
- Distribution:Last-mile network density determines service levels, with urban congestion forcing route optimization investments. E-commerce platforms are consolidating vendor relationships around integrated warehouse-to-door providers.
- Freight Forwarding:Documentation expertise and carrier rate arbitrage generate margin capture across fragmented ASEAN flag fleets. Customs brokerage integration remains essential for cross-border legality.
Transportation holds the largest share; momentum sits with Warehousing.
End User:
Customer scale and inventory velocity requirements segment logistics procurement into distinct contract structures and service level agreements.
- Manufacturers:Just-in-time supply chains demand precise delivery windows and real-time visibility, with automotive and electronics producers driving premium service adoption. Vietnam's northern industrial provinces and Indonesia's Batam-Bintan corridor concentrate contract logistics demand.
- E-Commerce:Parcel volumes and returns processing complexity are restructuring fulfillment networks toward urban micro-nodes. Cross-border ASEAN e-commerce flows are accelerating air-ground intermodal investments.
- Retailers:Seasonal demand spikes and omnichannel inventory synchronization require flexible capacity arrangements. Department store chains in Thailand and Malaysia are consolidating forwarder partnerships.
- Food & Beverage:Temperature-controlled integrity and shelf-life constraints mandate specialized cold chain infrastructure. Pharmaceutical distribution networks are extending into perishable food logistics.
Manufacturers anchor current revenue; E-Commerce is climbing the fastest.
Delivery Mode:
Infrastructure availability and cargo characteristics determine modal selection across archipelagic geography and continental corridors.
- Road:Flexible routing and door-to-door capability dominate volume throughput despite fuel cost volatility. Archipelagic geography limits modal substitution for short-haul movements.
- Sea:Containerized and bulk cargo movements rely on Singapore and Tanjung Pelepas transshipment concentration. Indonesia's domestic cabotage liberalization is opening intra-archipelago lanes to foreign-flag participation.
- Air:Time-definite express and high-value electronics shipments justify premium pricing. Intra-ASEAN e-commerce parcel flows are expanding air freight belly capacity utilization.
- Rail:Thailand and Malaysia operate the only developed trunk lines, with Laos-China rail connections opening new corridor possibilities. Mekong sub-region intermodal gaps present first-mover investment potential.
Road commands volume leadership; Air is gaining share fastest.
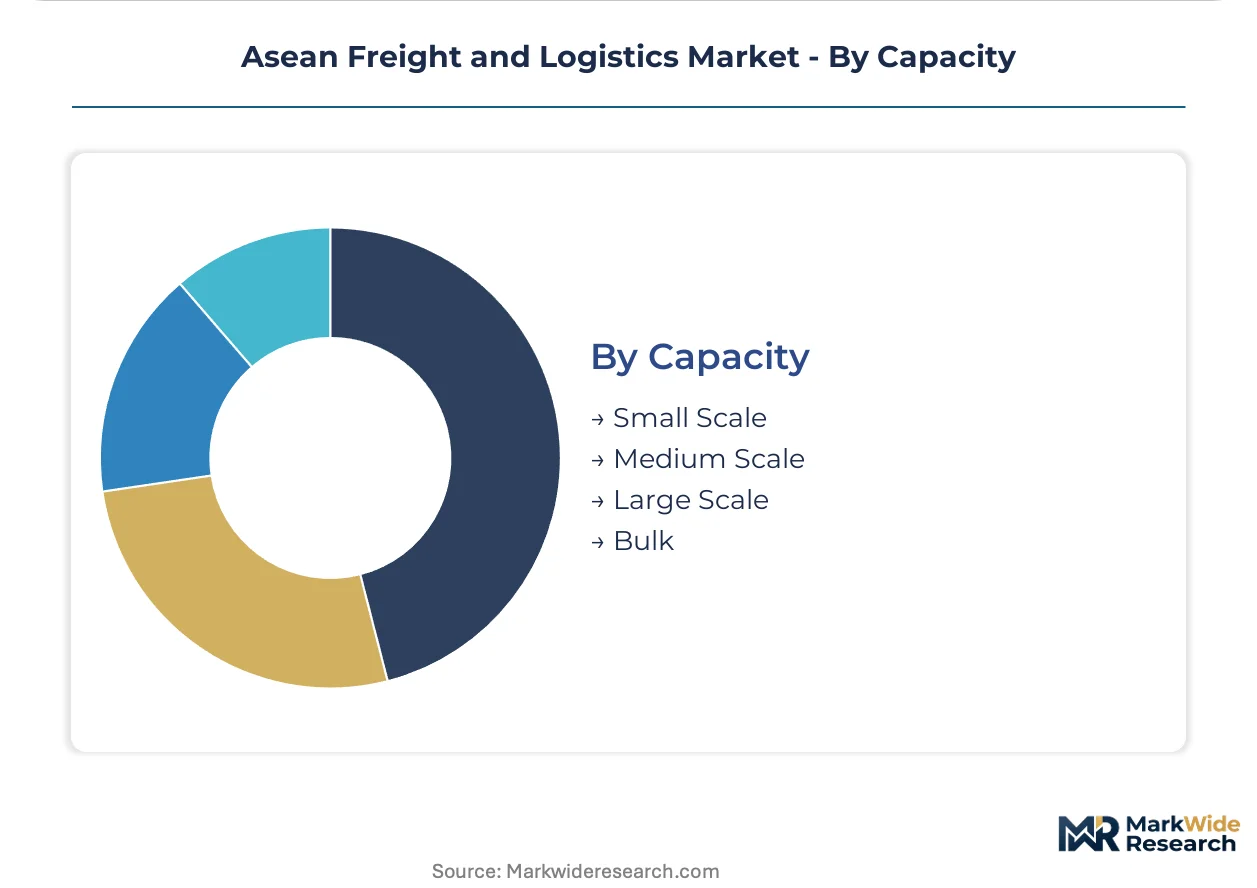
Capacity:
Shipment scale and consolidation economics segment procurement between dedicated and shared infrastructure arrangements.
- Large Scale:Dedicated fleet and warehouse contracts serve high-volume shippers with predictable demand patterns. Major consumer goods manufacturers in Indonesia are reducing forwarder counts to single-digit preferred partnerships.
- Bulk:Commodity movements and project cargo require specialized handling equipment and charter arrangements. Mining and agricultural exports drive Indonesian and Malaysian port throughput.
- Medium Scale:Shared user facilities and scheduled groupage services balance cost and service for mid-tier shippers. Third-party logistics providers are expanding distribution park assets to capture this segment.
- Small Scale:Parcel and less-than-truckload movements rely on network density and consolidation efficiency. Digital freight matching platforms are penetrating this segment at subscale.
Large Scale dominates contract value; Bulk shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore commands premium freight rates through transshipment dominance while Indonesia absorbs capacity investments at compressed margins. This pricing-power asymmetry shapes capital deployment across Southeast Asian logistics networks.
Indonesia
Domestic cabotage liberalization and e-commerce fulfillment density are driving warehouse expansion in Jakarta and Surabaya. The Ministry of Transportation's revised shipping regulations are opening intra-archipelago lanes to foreign-flag vessel participation. Batam-Bintan corridor manufacturers are consolidating forwarder partnerships to single-digit preferred networks.
Thailand
Cross-border trucking volumes to Vietnam and Malaysia are accelerating as manufacturing relocates to lower-cost zones. The Department of Land Transport enforces stricter weight-bridge compliance, forcing fleet renewal toward lighter composite chassis. Eastern Economic Corridor industrial estates are absorbing bonded logistics park investment for just-in-time automotive supply chains.
Vietnam
Northern industrial provinces near Hanoi are generating contract logistics demand from electronics and textile producers. The Ministry of Finance tightens transfer-pricing scrutiny on logistics contract structures, forcing documentation depth upgrades. Hai Phong port-centric distribution parks are expanding cold chain capacity for pharmaceutical exports.
Singapore
Transshipment concentration at PSA terminals creates single-point vulnerability for ASEAN-wide supply chains. The Maritime and Port Authority advances digital port clearance systems compressing vessel turnaround times. Jurong Island chemical logistics clusters are integrating blockchain-enabled documentation workflows.
Malaysia
Port Klang and Tanjung Pelepas handle disproportionate container volume, driving intermodal investments toward southern Thailand corridors. The Road Transport Department harmonizes cross-border permit quotas with Thai counterparts under ASEAN Single Window protocols. Iskandar Malaysia distribution parks are capturing Singapore spillover demand for regional fulfillment.
Asean Freight and Logistics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The ASEAN freight market structures around three tiers: global network operators with bonded warehouse assets, regional port-centric distributors, and digital freight matching platforms penetrating at subscale. Consolidation pressures favor integrated providers capable of warehouse-to-last-mile execution within single contract frameworks. Dominant competitive moves include strategic partnerships with e-commerce platforms and geographic expansion through distribution park development.
Among global network operators, DHL Group anchors premium express lanes across the Mekong sub-region through its bonded warehouse infrastructure. Kerry Logistics occupies a position within the port-centric distribution tier, exemplifying asset-heavy models concentrated in Indonesia and Philippine logistics parks. SF Express represents the air-ground intermodal archetype, capturing intra-ASEAN e-commerce parcel flows through integrated network density.
| Leading Market Players |
|---|
| DHL Group |
| DSV A/S |
| Kuehne+Nagel |
| A.P. Moller - Maersk |
| SF Express |
| Kerry Logistics |
| Tiong Nam Logistics Holdings Bhd |
| YCH Group |
| CJ Logistics |
| Others |
Value Chain & Pricing Dynamics
Singapore's transshipment concentration at PSA terminals generates premium freight rates that cascade through ASEAN-wide supply chains, while Indonesian domestic lanes absorb capacity investments at compressed margins. This pricing-power asymmetry between hub markets and archipelagic routes shapes carrier deployment decisions and shipper procurement strategies across Southeast Asian logistics networks.
Pricing Analysis
The customization-premium spread separates configured-to-order bonded warehouse contracts from standard port-to-port forwarding arrangements. Three-tier pricing structure across premium express, standard scheduled, and economy deferred levels captures service differentiation, with volume scale and customs brokerage integration as primary price differentiation drivers. Pricing pressure stems from digital freight platforms compressing transaction friction and eroding documentation-speed premiums previously captured by established brokers. E-commerce parcel shippers exhibit highest price sensitivity, while pharmaceutical cold chain operators accept premium positioning for temperature integrity guarantees.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor supplier relationships across Indonesian, Thai, and Vietnamese freight corridors. Geographic supply concentration rests on Singapore hub infrastructure, Malaysian port-centric distribution parks, and Indonesian domestic shipping lanes. Diesel fuel, composite chassis materials, and bonded warehouse space constitute critical input dependencies. Single-point vulnerability at Singapore and Tanjung Pelepas transshipment nodes presents structural supply chain risk. Distribution runs through integrated warehouse-to-last-mile providers consolidating previously fragmented forwarder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated e-commerce platforms and consumer goods manufacturers reducing forwarder counts from dozens to single-digit preferred partnerships, fragmenting incumbent margin capture across ASEAN logistics markets.
For Market Incumbents: Pre-empt platform-driven margin compression by deepening captive distribution park assets in Jakarta, Bangkok, and Ho Chi Minh City micro-fulfillment nodes. Secure bonded warehouse capacity adjacent to Thailand-Vietnam cross-border corridors before ASEAN Single Window harmonization eliminates documentation-speed advantages. Certification investment in cold chain pharmaceutical handling creates defensible positioning against digital freight matching entrants lacking temperature-controlled infrastructure.
For New Entrants and Emerging Players: Laos-Cambodia Mekong corridor underpenetration offers first-mover advantage for bonded logistics park development where road-rail intermodal gaps persist. Target cold chain pharmaceutical distribution outside Jakarta and Manila, where temperature-controlled last-mile networks remain underdeveloped. Pursue strategic partnerships with regional e-commerce platforms seeking warehouse-to-door execution capabilities rather than fragmented forwarding arrangements.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because shippers are consolidating vendor relationships around integrated providers capable of single-contract warehouse-to-last-mile execution. Acquisition target archetype: regional port-centric distributors with captive distribution park assets in Indonesia or the Philippines. Monitor mutual recognition agreements for driver qualifications across Thailand, Malaysia, and Vietnam as inflection indicator for corridor economics and fleet deployment priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Network Expansion | DHL Group anchors premium express lanes across Mekong sub-region through customs-integrated facilities. |
| Port-Centric Distribution Park Development | Kerry Logistics captures Indonesian and Philippine demand through asset-heavy logistics park concentration. |
| Air-Ground Intermodal Integration | SF Express extends network density to capture intra-ASEAN e-commerce parcel flows. |
| Digital Freight Platform Deployment | Real-time load-truck pairing algorithms penetrate ASEAN road haulage at subscale, creating consolidation potential. |
| Cold Chain Infrastructure Investment | Temperature-controlled last-mile networks for vaccines and biologics remain underdeveloped outside major metros. |
Study Parameters
Desk research of customs trade databases, ASEAN Secretariat protocol documentation, and national transportation ministry filings preceded structured interviews with freight forwarding executives, bonded warehouse operators, cross-border trucking fleet managers, and e-commerce logistics procurement leads. Primary fieldwork combined with secondary validation from carrier rate filings, port authority throughput statistics, and logistics park development permits. Bottom-up segmentation modeling triangulated against top-down macroeconomic trade flow projections.
Assumptions held fixed include ASEAN Single Window implementation timelines, Indonesian cabotage liberalization progression, and regional fuel cost trajectories; sensitivity analysis varied cross-border permit quota harmonization speeds and driver qualification mutual recognition adoption rates. Segmentation dimensions modeled encompass service type, end-user industry, delivery mode, and capacity tier across the projection horizon. CAGRs derived from historical trade volume elasticities and infrastructure capacity expansion schedules, with e-commerce fulfillment density and pharmaceutical cold chain demand as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital freight platforms or state-sponsored logistics consolidators would shift outcomes. Macroeconomic deviation, regulatory enforcement changes, or technological disruption in automated customs interfaces would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
North America Freight Forwarding Market