
 United States Air Freight Market | 2026-2036
United States Air Freight Market Size, Share, and Industry Trends Forecast 2026-2036
United States Air Freight Market Intelligence
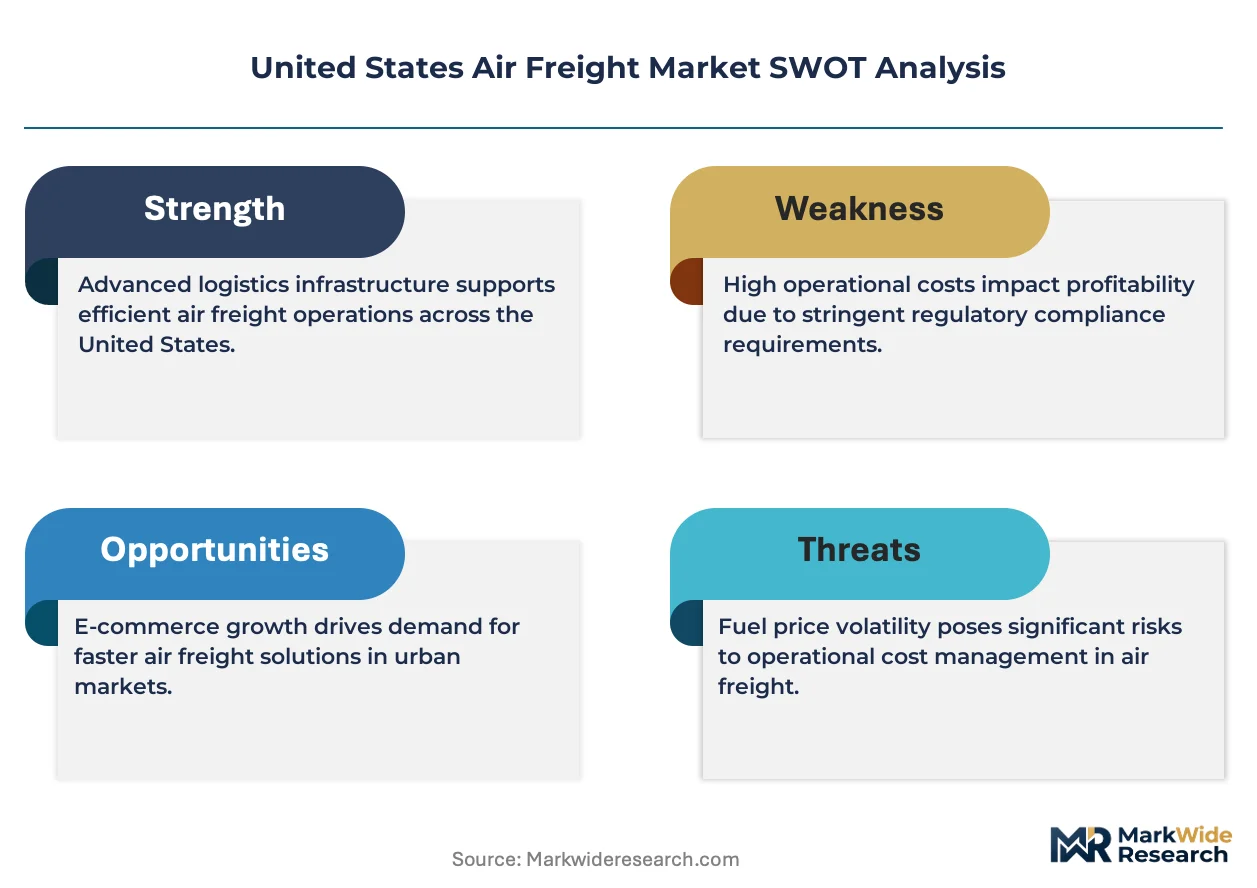
Integrated door-to-door service bundling is consolidating buyer preference away from standalone airport-to-airport contracts. FedEx Corp leverages its Memphis superhub infrastructure to sustain overnight express dominance across domestic lanes. United Parcel Service Inc anchors its air network through Louisville, where specialized healthcare logistics competes with DHL Group's Cincinnati operations. Atlas Air Worldwide Holdings dominates freighter capacity leasing to e-commerce platforms and retailers seeking dedicated lift without fleet ownership.
United States air freight encompasses the commercial transport of goods via fixed-wing aircraft operating within domestic and international lanes serving US origins or destinations, utilizing narrow-body, wide-body, and dedicated freighter configurations with payload capacities from 15,000 to 130,000 pounds to achieve transit speeds of 400-575 mph for time-critical supply chains. The service type dimension shows express offerings commanding premium pricing while same-day delivery posts the fastest expansion as medical and semiconductor shippers prioritize speed over cost. Temperature-controlled cargo within the cargo type classification carries outsized margin contribution due to specialized handling infrastructure and regulatory compliance requirements that general cargo lanes cannot easily replicate.
The FAA enforces aircraft certification and operational safety standards that directly shape fleet renewal timelines and freighter conversion economics, while TSA cargo screening mandates dictate ground handling infrastructure investments at major hubs. DOT consumer protection frameworks and NHTSA surface connectivity rules influence last-mile handoff design in door-to-door delivery models. Stakeholders must weigh freighter fleet commitments against sustainable aviation fuel pathways as EPA emissions scrutiny intensifies for domestic aviation operations.
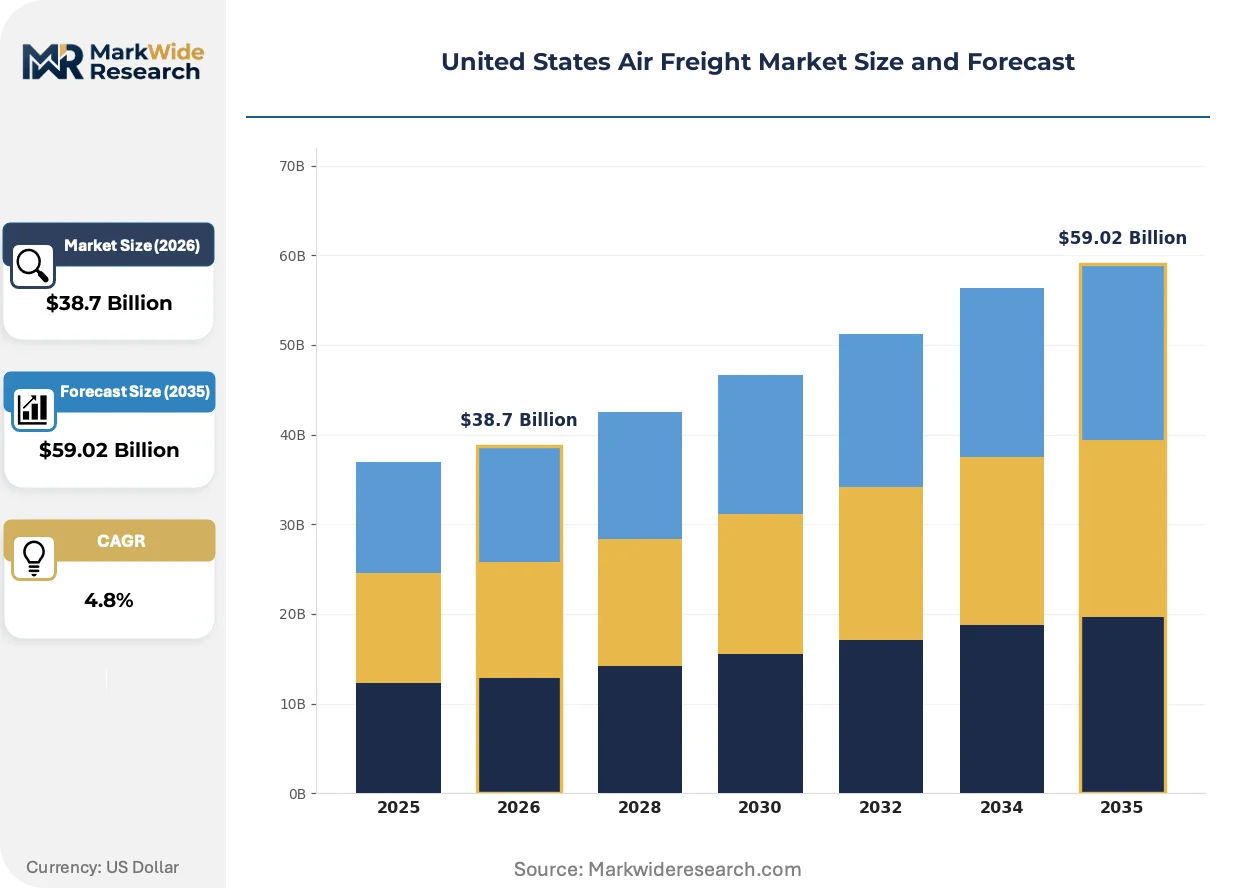
Market Dynamics
The FAA's NextGen air traffic modernization is compressing flight corridors between California and Texas cargo hubs, forcing carriers to reoptimize hub-and-spoke networks around real-time capacity allocation rather than static schedules.
Growth Catalysts
- Biologics cold-chain expansion:Temperature-sensitive pharmaceutical therapies now require dedicated freighter lanes with validated thermal packaging, pulling volume away from general cargo networks.
- E-commerce fulfillment density:Amazon, Walmart, and Target distribution centers cluster within 50 miles of Memphis, Louisville, and Cincinnati superhubs, creating self-reinforcing cargo gravity.
- Sustainable aviation fuel mandates:The EPA's domestic aviation emissions scrutiny under the Inflation Reduction Act is accelerating carrier investment in SAF-compatible freighter fleets.
Market Restraints
- Pilot labor scarcity:FAA certification timelines for cargo-rated aviators stretch 18-24 months, constraining fleet utilization at peak demand periods.
- Freighter conversion backlog:Narrow-body feedstock shortages at conversion facilities in China and Israel delay dedicated cargo capacity additions by 8-14 months.
- Jet fuel price volatility:Kerosene derivative costs swing 30-40% annually, eroding margin predictability on fixed-rate express contracts.
Strategic Opportunities
- Same-day medical corridors:Organ transplant networks and cell therapy distributors now pay 4-6x standard rates for guaranteed morning delivery windows.
- Drone last-mile integration:FAA Part 135 waivers for autonomous cargo drones are opening 50-150 mile radius feeder routes from secondary airports.
- Pharmaceutical serialization:FDA DSCSA track-and-trace mandates are forcing manufacturers toward integrated air freight partners with validated chain-of-custody systems.
Industry Challenges
- TSA cargo screening bottlenecks:Piece-level explosives detection at origin airports adds 4-6 hours to ground handling, compressing express network windows.
- Legacy warehouse management integration:EDI protocol mismatches between carrier systems and shipper ERP platforms delay real-time visibility deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Air Freight Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express, Standard, Charter, Same-Day End User: E-Commerce, Manufacturing, Pharmaceuticals, Automotive Delivery Model: Door-to-Door, Airport-to-Airport, Hub-and-Spoke, On-Demand Cargo Type: General Cargo, Temperature-Controlled, Dangerous Goods, Oversized Freight |
| Companies Covered | FedEx Corp, United Parcel Service Inc, DHL Group, Atlas Air Worldwide Holdings, Kuehne + Nagel International AG, DSV AS, Expeditors International, C.H. Robinson Worldwide Inc, CEVA Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Air Freight Market Strategic Shifts & Innovations
Digital freight matching platforms are disintermediating traditional forwarder relationships, while predictive maintenance analytics and autonomous ground handling equipment reshape hub economics.
Digital twin technology for cargo loading optimization is modularizing how airlines configure belly freight versus dedicated freighter deployment. Pharmaceutical shippers now demand simulation-validated lane risk assessments before awarding contracts. The technology is modularizing capacity planning from seasonal schedules into weekly reoptimization cycles.
The FAA's Safety Management System expansion mandates proactive hazard reporting from all Part 121 cargo operators. Carriers must now integrate flight data monitoring with maintenance logs for audit trails. Temperature-controlled biologics lanes face the steepest compliance cost escalation as documentation requirements tighten.
Shippers are unbundling express guarantees from full door-to-door service, negotiating airport-to-airport rates with separate last-mile contracts. Medical device distributors pioneered this split procurement model. The pattern now spreads through semiconductor and aerospace component supply chains originating in Austin and Phoenix industrial corridors.
United States Air Freight Market Segmentation
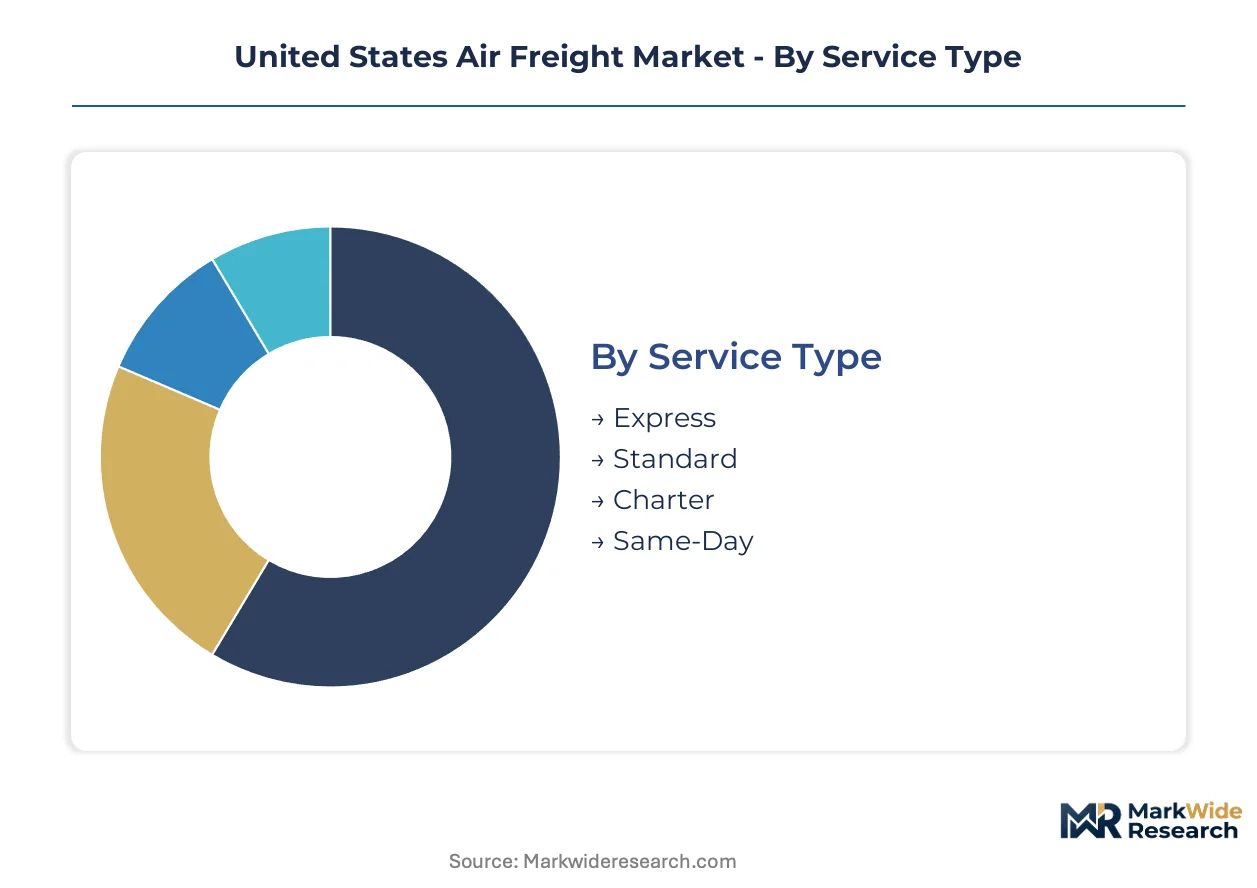
Air freight segmentation in the United States reflects divergent operational economics across speed tiers and cargo handling complexity. Carrier network design and infrastructure investment priorities hinge on which segments command volume concentration and margin contribution.
Service Type:
Transit velocity specifications differentiate operational requirements and pricing power across service tiers, with network density and aircraft utilization rates varying substantially by commitment window.
- Express:Overnight and deferred two-day offerings utilize dedicated freighter fleets and superhub sorting infrastructure to guarantee time-definite delivery. Pharmaceutical distributors and semiconductor manufacturers in the California-to-Texas corridor anchor volume concentration, paying premiums for morning arrival certainty that supports just-in-time production schedules.
- Same-Day:Emergency and critical shipment services deploy chartered narrow-body aircraft or belly capacity on next-available passenger flights, achieving door-to-door transit under 12 hours. Organ transplant networks and cell therapy cold-chain distributors in Boston, Houston, and Los Angeles drive demand concentration, accepting rates 4-6x standard express levels for validated thermal integrity across ultra-short windows.
- Standard:Three-to-five-day deferred air freight leverages excess belly capacity on scheduled passenger routes, optimizing cost over velocity for less time-sensitive general cargo.
- Charter:Full-aircraft capacity leases accommodate project freight, oversized shipments, or peak season overflow beyond scheduled network constraints.
Express leads on scale; Same-Day leads on momentum.
End User:
Shipper industry verticals impose distinct handling protocols, documentation requirements, and network reliability standards that reshape carrier service configuration.
- E-Commerce:Amazon, Walmart, and Target distribution networks generate parcel density within 50 miles of Memphis, Louisville, and Cincinnati superhubs, creating self-reinforcing cargo gravity that justifies dedicated feeder aircraft and automated sortation investments.
- Pharmaceuticals:Temperature-sensitive biologics and cell therapies require validated cold-chain infrastructure with continuous monitoring, pulling volume toward carriers with FDA-audited handling facilities and specialized thermal packaging partnerships.
- Manufacturing:Aerospace components and industrial machinery shipments prioritize damage-resistant handling and lift capacity over speed, utilizing wide-body belly freight for cost-efficient transcontinental movement.
- Automotive:Just-in-time production line feeds and aftermarket parts distribution demand precise arrival scheduling to avoid assembly stoppage penalties at plants in Michigan, Tennessee, and South Carolina.
E-Commerce dominates volume throughput; Pharmaceuticals commands margin expansion.
Delivery Model:
Contractual scope boundaries determine asset ownership, liability allocation, and visibility system integration requirements between carriers and shippers.
- Door-to-Door:Integrated service bundles encompassing first-mile pickup, air transit, and last-mile delivery command premium positioning as buyers consolidate procurement away from fragmented airport-to-airport contracts.
- Airport-to-Airport:Traditional port-to-port offerings persist among cost-sensitive industrial shippers with established ground transportation relationships, though share erodes as integrated competitors deepen last-mile density.
- Hub-and-Spoke:Centralized sorting and aircraft routing through Memphis, Louisville, or Cincinnati superhubs optimizes network efficiency for express parcel density but adds transit time versus point-to-point alternatives.
- On-Demand:Dynamic capacity matching through digital freight platforms enables spot-market access for unpredictable shipment volumes, displacing forwarder relationships for non-contract freight.
Door-to-Door captures preference consolidation; On-Demand gains share fastest among non-contract volume.
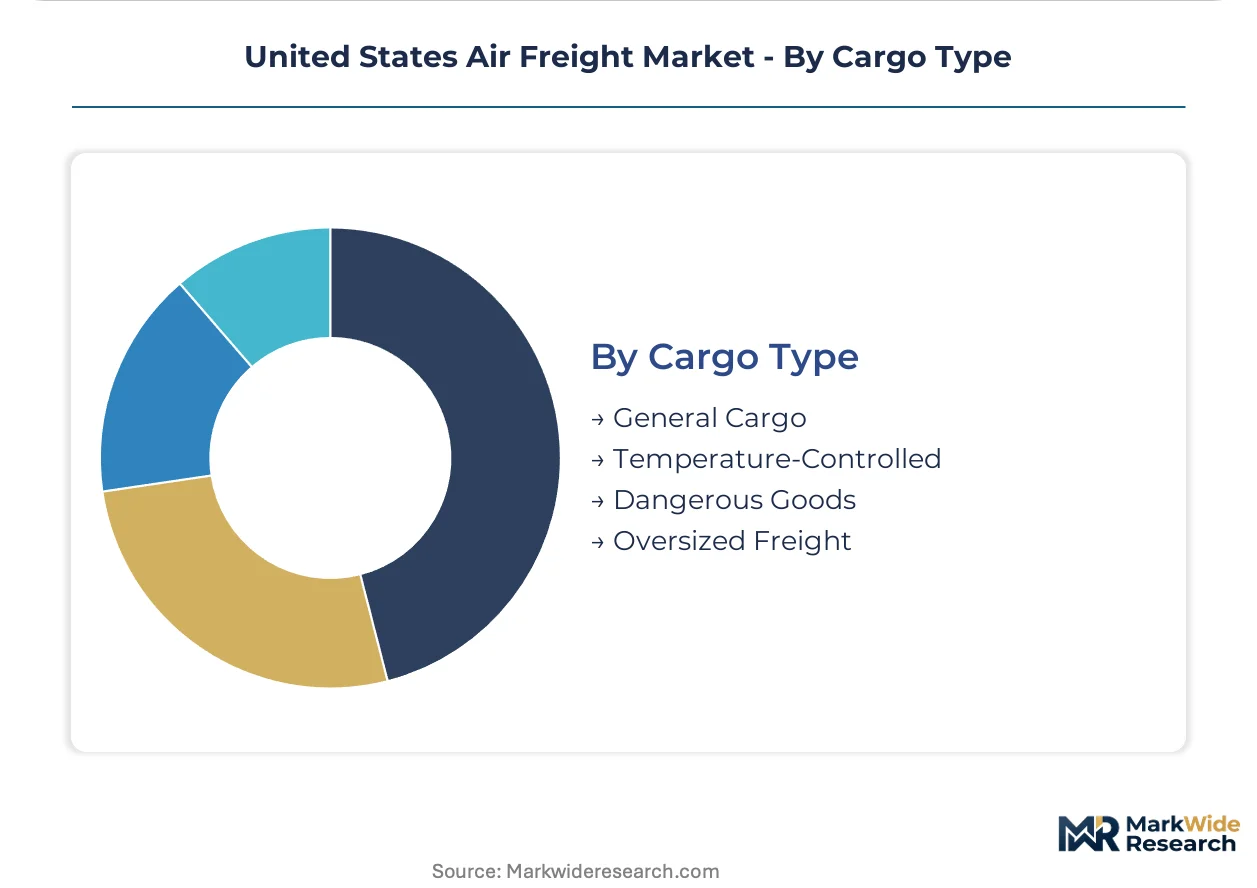
Cargo Type:
Physical handling characteristics and regulatory classification dictate facility infrastructure, crew training, and insurance requirements across freight categories.
- Temperature-Controlled:Pharmaceutical cold-chain and perishable shipments demand active and passive thermal packaging systems, validated container fleets, and continuous data logging that general cargo infrastructure cannot replicate, generating outsized margin contribution.
- General Cargo:Non-specialized freight including consumer goods, textiles, and electronics constitutes volume foundation but faces commoditization pressure as belly capacity abundance compresses yields on major domestic lanes.
- Dangerous Goods:Hazardous materials shipments require IATA-certified handling agents, segregated storage facilities, and specialized aircraft loading protocols that limit carrier participation and sustain pricing premiums.
- Oversized Freight:Project cargo exceeding standard container dimensions necessitates nose-loading freighters, charter arrangements, or cargo-only passenger aircraft with seats removed, constraining capacity availability.
General Cargo anchors volume scale; Temperature-Controlled leads on margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States air freight industry traces its modern scale to the 1973 deregulation of domestic cargo, which unleashed hub-and-spoke network economics across the continental grid. Memphis and Louisville emerged as sorting capitals during this era, anchoring infrastructure investments that still dominate parcel velocity today.
California
Pharmaceutical manufacturing clusters in South San Francisco and San Diego generate temperature-controlled biologics volume requiring validated cold-chain lanes. The state's Air Resources Board enforces emissions standards that accelerate carrier adoption of sustainable aviation fuel at Los Angeles International and Ontario cargo terminals. E-commerce fulfillment density concentrates in the Inland Empire, where Amazon and Walmart distribution centers feed direct freighter routes to Memphis and Louisville.
Texas
Semiconductor fabrication expansion in Austin and Dallas-Fort Worth drives just-in-time component shipments demanding morning delivery certainty. The Texas Department of Transportation coordinates surface connectivity improvements linking Dallas-Fort Worth International cargo terminals to interstate corridors. Houston's Texas Medical Center anchors organ transplant and cell therapy corridors paying premium rates for same-day validated transport.
Tennessee
Memphis anchors the continental express network through FedEx's superhub infrastructure, processing overnight parcel density that justifies dedicated feeder aircraft across the Southeast. The Tennessee Department of Economic and Community Development administers infrastructure grants expanding cargo apron capacity at Memphis International. Nashville's healthcare logistics cluster supports pharmaceutical distribution networks requiring temperature-monitored staging facilities.
Kentucky
Louisville's Worldport anchors UPS air operations with specialized healthcare logistics competing for pharmaceutical contracts against Cincinnati-based rivals. The Kentucky Cabinet for Economic Development funds workforce training programs addressing cargo-rated aviator certification bottlenecks. Northern Kentucky's proximity to Cincinnati/Northern Kentucky International creates cross-state cargo gravity for perishable and temperature-controlled freight.
Ohio
Cincinnati/Northern Kentucky International hosts DHL's Americas hub, specializing in international express and pharmaceutical cold-chain with FDA-audited handling facilities. The Ohio Department of Development supports air cargo infrastructure through JobsOhio incentive programs targeting logistics investment. Cleveland's manufacturing base generates automotive and industrial machinery shipments utilizing belly freight on passenger routes to control transportation spend.
United States Air Freight Market Key Industry Players
The competitive structure tilts toward integrated express carriers with captive superhub infrastructure. Network density advantages concentrate among three operators controlling Memphis, Louisville, and Cincinnati sorting capacity. Strategic archetypes divide between integrated door-to-door providers, freighter capacity lessors, and forwarder-brokerage hybrids. Capacity expansion and sustainable aviation fuel fleet commitments constitute the dominant competitive moves reshaping positioning.
Within the integrated carrier tier, FedEx Corp and United Parcel Service Inc exemplify hub-and-spoke dominance through captive superhub infrastructure. Atlas Air Worldwide Holdings occupies a position as freighter capacity lessor to e-commerce platforms seeking dedicated lift without fleet ownership. DHL Group anchors international express operations with specialized healthcare logistics competing for pharmaceutical cold-chain contracts. These three companies represent the structural fault lines between integrated network control, asset-light capacity provision, and international express specialization.
| Leading Market Players |
|---|
| FedEx Corp |
| United Parcel Service Inc |
| DHL Group |
| Atlas Air Worldwide Holdings |
| Kuehne + Nagel International AG |
| DSV AS |
| Expeditors International |
| C.H. Robinson Worldwide Inc |
| CEVA Logistics |
| Others |
Cost & Logistics Intelligence
Express-same-day bifurcation separates pharmaceutical and semiconductor shippers paying 4-6x premiums from general cargo buyers optimizing cost, with this divergence mapping directly onto dedicated freighter networks versus belly-capacity spot markets and shaping carrier fleet deployment decisions across the California-to-Texas corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with speed guarantees and temperature-validation certification driving price differentiation between pharmaceutical cold-chain contracts and general e-commerce parcel flows. Pricing pressure stems from belly-capacity abundance on transcontinental passenger routes compressing yields in deferred segments. E-commerce retailers exhibit highest price sensitivity, while organ transplant networks and cell therapy distributors demonstrate lowest sensitivity due to life-critical delivery windows.
Supply Chain Analysis
Single-source vulnerability sits with narrow-body freighter conversion facilities concentrated in China and Israel, where feedstock shortages delay dedicated cargo capacity additions. The supply chain draws from airframe manufacturers in the United States and France, jet fuel refineries along the Gulf Coast, and specialized thermal packaging producers in Germany and Switzerland. Tariff exposure on aircraft components and conversion kits constitutes the dominant structural risk. Distribution runs through Memphis, Louisville, and Cincinnati superhubs that anchor hub-and-spoke network economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States air freight market functions as a regulatory compounder where FAA NextGen mandates and EPA sustainable aviation fuel scrutiny under the Inflation Reduction Act continuously reshape carrier capital allocation and fleet renewal timelines.
For Market Incumbents: Acquire freighter conversion slots and SAF-compatible aircraft to lock in capacity ahead of feedstock constraints. Consolidate pharmaceutical cold-chain certifications through FDA-audited facility investments that emerging forwarder-brokerage hybrids cannot replicate. Threat from digital freight matching platforms demands proactive hub automation and predictive maintenance analytics deployment. For New Entrants and Emerging Players: Autonomous cargo drone technology under FAA Part 135 waivers offers entry into 50-150 mile feeder routes from secondary airports underserved by incumbent superhub networks. White-space targets include same-day medical corridors in Houston and Boston, and semiconductor component lanes between Austin and Phoenix. Go-to-market positioning should emphasize validated chain-of-custody systems for FDA DSCSA compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where pilot labor scarcity constrains fleet utilization and specialized healthcare logistics capabilities command scarcity premiums. Long-term viability favors integrated carriers with captive superhub infrastructure over asset-light forwarders vulnerable to margin compression. The signal to watch is freighter fleet commitment announcements tied to SAF procurement agreements as an inflection indicator for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Fleet Renewal | EPA emissions scrutiny under the Inflation Reduction Act accelerates carrier capital reallocation toward sustainable aviation fuel pathways. |
| Superhub Automation Investment | FedEx Memphis and UPS Louisville deployments of autonomous ground handling equipment compress sortation costs per parcel. |
| Pharmaceutical Cold-Chain Certification | FDA-audited handling facilities at Cincinnati and Louisville anchor healthcare logistics contracts with biologics manufacturers. |
| Digital Freight Matching Platform Launch | Disintermediation of traditional forwarder relationships opens spot-market access for non-contract e-commerce volume. |
| Drone Feeder Route Expansion | FAA Part 135 waivers enable 50-150 mile radius autonomous cargo corridors from secondary airports near distribution clusters. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cargo airline network planners, pharmaceutical logistics directors, e-commerce supply chain managers, and FAA regulatory affairs specialists with secondary validation through DOT T-100 traffic data, FAA aircraft registry filings, EPA aviation emissions disclosures, and BTS air freight tonnage statistics. Bottom-up carrier capacity modeling and top-down macroeconomic demand drivers underwent iterative triangulation.
Segment-weighting applied service type, end user vertical, delivery model, and cargo handling complexity dimensions across the projection horizon, with express and same-day velocity tiers receiving distinct growth assumptions based on pharmaceutical cold-chain expansion and e-commerce fulfillment density trends. CAGRs derived from historical tonnage growth patterns, fleet delivery schedules, and regulatory mandate implementation timelines. Jet fuel price volatility scenarios and pilot certification bottleneck durations informed sensitivity bounds.
The model holds under steady FAA modernization progress and stable jet fuel supply; deviation in SAF mandate acceleration or narrow-body conversion facility disruptions would shift capacity availability assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Moving Services (Mover and Packers) Market