
 Military Logistics Market | 2026-2036
Military Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Military Logistics Market Intelligence
The EU Green Deal is decoupling military logistics from carbon-intensive transport modalities across European defense procurement. Lockheed Martin Corporation leverages its satellite-integrated tracking infrastructure to sustain long-haul supply visibility for coalition operations. Kuehne + Nagel International AG anchors commercial-military hybrid networks, competing on multimodal flexibility that defense agencies now require.
Military logistics encompasses the planning, execution, and management of materiel movement, maintenance, and sustainment for armed forces, typically operating across contested environments with redundancy requirements exceeding 99.5% delivery reliability. The discipline coordinates transportation modes, warehousing nodes, and forward distribution points to maintain operational readiness across extended supply lines. Transportation services dominate value capture due to fuel volatility and asset intensity, while GPS and drone technologies represent the fastest-expanding capability layer as autonomous resupply reduces personnel exposure. Army end users command the largest procurement share given ground force scale, though Special Operations segments generate premium margins through rapid-response kitting requirements.
The U.S. Department of Defense issues Federal Acquisition Regulation supplements that mandate cybersecurity-hardened supply chains, while NATO Standardization Agreements enforce interoperable pallet and container specifications across allied logistics networks. The EU AI Act increasingly governs autonomous decision systems in military transport scheduling, creating compliance thresholds for algorithmic route optimization. Stakeholders must weigh sovereign capacity investments against alliance-dependent supply architectures as geopolitical fragmentation intensifies.
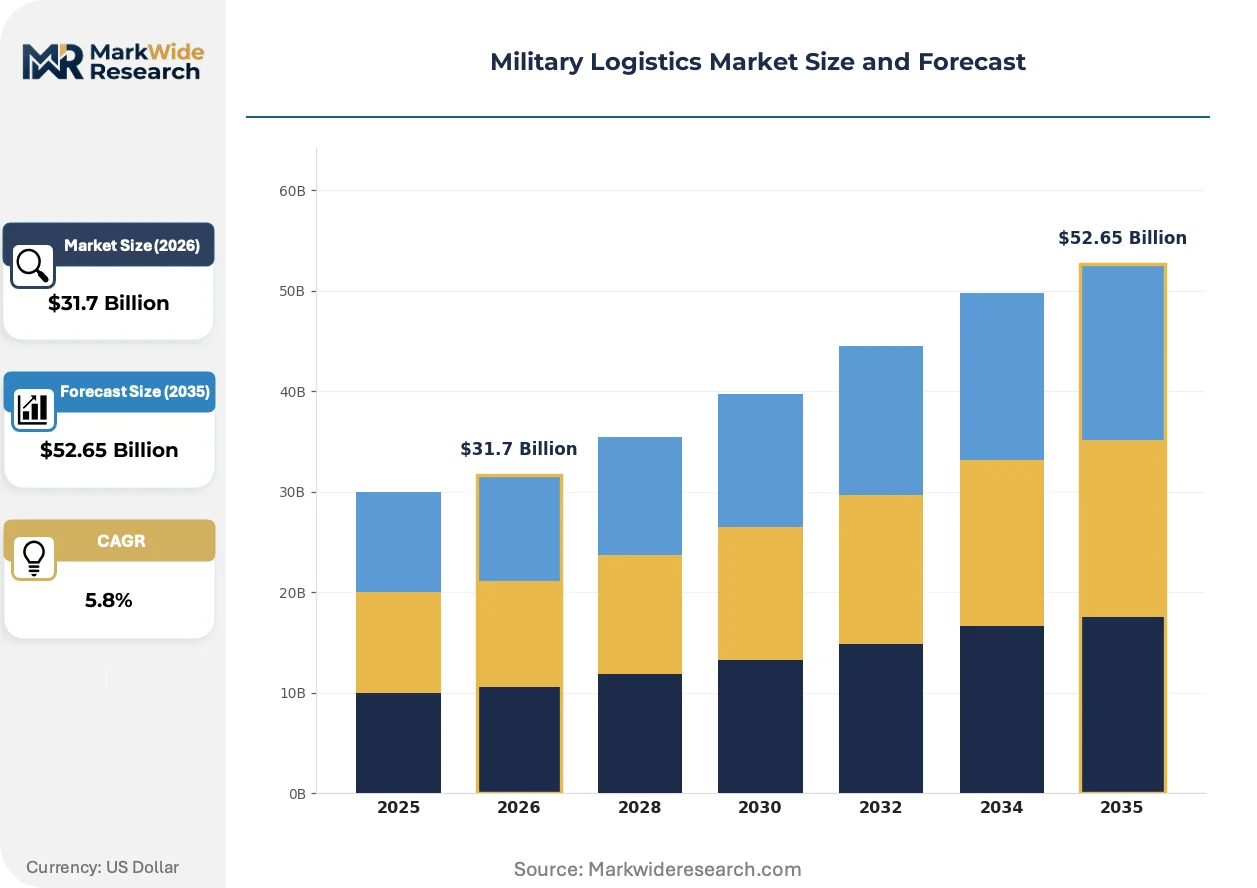
Market Dynamics
NATO's sustainable procurement mandates are forcing defense ministries to restructure fuel-dependent transport networks while autonomous resupply technologies compress delivery timelines for forward-deployed forces.
Growth Catalysts
- EU Green Deal:The European Union's decarbonization framework mandates carbon-neutral military transport modalities across member defense procurement, redirecting investment toward electric and hydrogen-powered distribution assets.
- Autonomous Ground Vehicles:Unmanned ground systems eliminate personnel exposure in contested last-mile delivery scenarios, with Army expeditionary units prioritizing robotic resupply for forward operating bases.
- Australia:The Australian Defence Force's modernization of northern territory logistics infrastructure creates concentrated demand for multimodal distribution hubs supporting Indo-Pacific operations.
Market Restraints
- Jet Fuel Price Volatility:Tactical airlift operations face margin compression from petroleum cost swings, with transport services absorbing the largest cost shock in contested fuel markets.
- Single-Source Dependencies:Specialized military pallet and container manufacturing concentrates in German industrial clusters, creating vulnerability to supply disruption across allied networks.
- EU AI Act Compliance Thresholds:Algorithmic route optimization systems face mandatory explainability requirements that delay deployment of autonomous decision systems in European theater logistics.
Strategic Opportunities
- Drone-Based Resupply:Unmanned aerial systems penetrate denied-access environments where manned transport faces unacceptable risk, opening expeditionary logistics to new operational concepts.
- Commercial-Military Hybrid Networks:Defense agencies now require multimodal flexibility that integrates commercial freight capacity with military-grade security protocols during surge requirements.
- Special Operations Rapid-Response Kitting:SOF units generate premium-margin demand for pre-configured mission-specific equipment packages with sub-24-hour deployment readiness.
Industry Challenges
- Cybersecurity-Hardened Supply Chain Integration:U.S. Federal Acquisition Regulation supplements mandate end-to-end encryption and zero-trust architecture across vendor networks, extending certification timelines for new entrants.
- Interoperable Container Specification Harmonization:NATO Standardization Agreements require unified pallet dimensions and tracking protocols that force legacy warehouse management system overhauls across allied nations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Logistics Market |
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Maintenance Product Type: Vehicles, Ammunition, Medical Supplies, Equipment End User: Army, Navy, Air Force, Special Operations Technology: GPS, RFID, Drones, Robotics |
| Companies Covered | Northrop Grumman Corporation, BAE Systems, Lockheed Martin Corporation, L3Harris Technologies Inc., KBR Inc., RTX Corporation, The Boeing Company, Kuehne + Nagel International AG, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Logistics Market Strategic Shifts & Innovations
Satellite-integrated tracking infrastructure is collapsing visibility gaps across extended supply lines while regulatory pressure on algorithmic decision systems rewrites procurement specifications for autonomous platforms.
AI-driven predictive maintenance platforms is unifying equipment readiness data across distributed vehicle fleets. Army motor pool operators are adopting these systems fastest among ground force segments. The technology is unifying previously siloed maintenance schedules into continuous readiness dashboards that compress downtime windows.
The EU AI Act's risk-based classification system for autonomous transport scheduling is forcing defense contractors to reengineer algorithmic transparency features. Military procurement offices now require documented decision trails for route optimization software. Special Operations logistics units face the steepest compliance burden given their reliance on adaptive real-time planning systems.
Defense agencies are consolidating vendor relationships around integrated logistics service providers capable of end-to-end accountability. Fragmented point-solution contracts are giving way to multi-year performance agreements with penalty clauses for delivery reliability failures. This concentration is most visible in U.S. expeditionary force sustainment contracts, where single-source responsibility for transportation, warehousing, and maintenance is becoming standard.
Military Logistics Market Segmentation
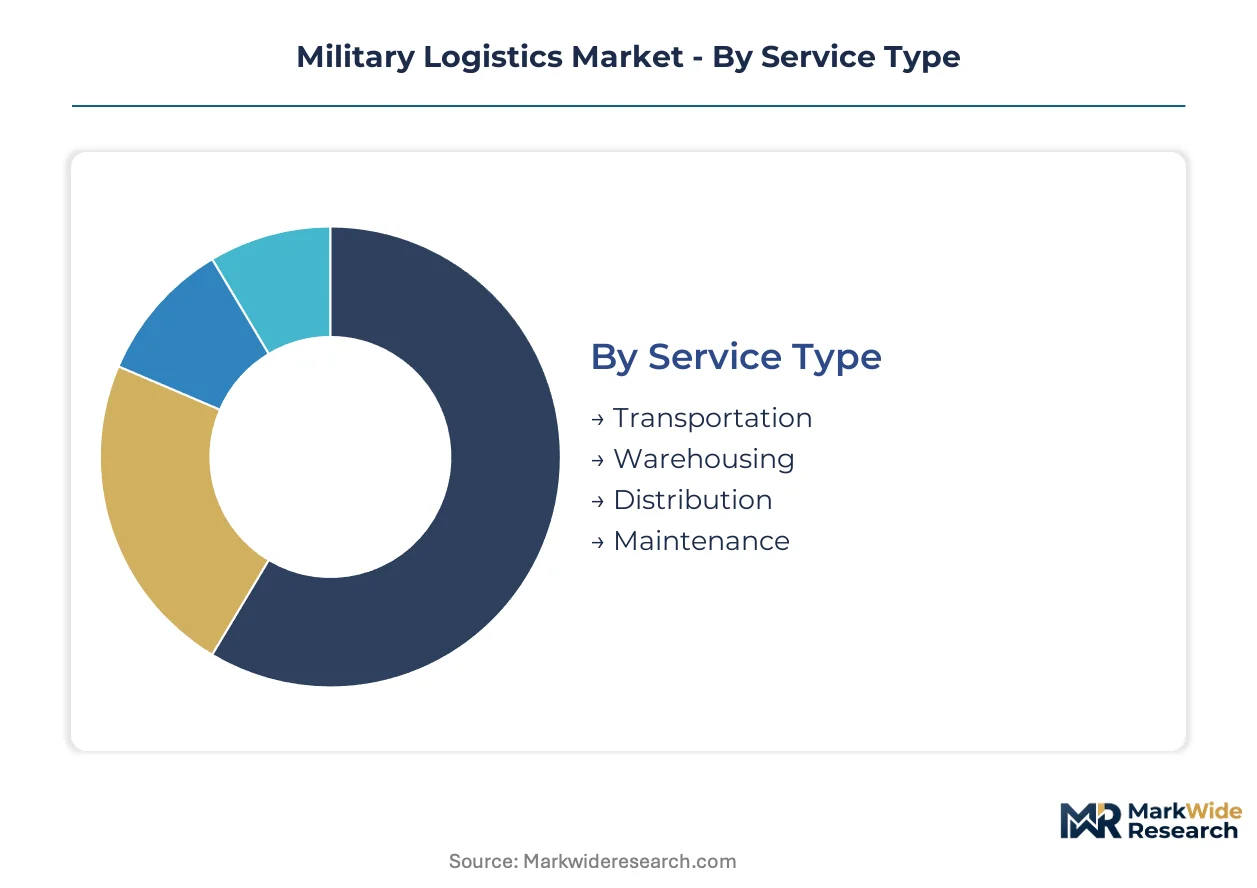
Military logistics segmentation reveals how capital allocates across distinct capability layers. Supply concentration in transportation services and Army procurement shapes competitive positioning, while technology adoption creates divergence in growth trajectories across service lines.
Service Type:
Supply concentration in transportation services captures the largest value share due to fuel intensity and asset requirements across extended supply lines.
- Transportation:Tactical and strategic movement of materiel via air, land, and sea modalities dominates cost structures. Demand concentrates in U.S. expeditionary operations and NATO rapid response forces where contested fuel markets compress margins.
- Warehousing:Forward storage nodes and pre-positioned stockpiles enable operational readiness across dispersed theaters. Australian Defence Force modernization of northern territory hubs drives concentrated investment in climate-hardened distribution infrastructure.
- Distribution:Last-mile delivery coordination bridges strategic airheads to forward operating bases. German industrial clusters anchor specialized pallet manufacturing for interoperable NATO networks.
- Maintenance:Equipment repair and overhaul services sustain fleet availability across rotational deployment cycles. Army motor pools generate the largest procurement volumes for predictive maintenance platform integration.
Today's leader: Transportation. Tomorrow's challenger: Maintenance.
Product Type:
Margin differentiation separates mission-critical ammunition flows from commodity equipment movements across defense procurement tiers.
- Vehicles:Armored and tactical vehicle logistics require specialized heavy-lift capacity and battlefield recovery protocols. U.S. Army expeditionary units prioritize autonomous ground vehicle resupply to eliminate personnel exposure in contested last-mile scenarios.
- Ammunition:Hazardous materiel handling demands certified storage facilities and segregated transport modalities. Special Operations forces generate premium-margin demand for rapid-response ammunition kitting with sub-24-hour deployment readiness.
- Medical Supplies:Temperature-controlled distribution networks sustain pharmaceutical efficacy across climate extremes. Forward surgical teams require continuous cold chain integrity for blood products and biologics.
- Equipment:General-purpose materiel spans individual soldier gear through command-and-control systems. Standardized NATO container specifications force legacy warehouse management system overhauls across allied nations.
Current margin capture centers on Ammunition. Equipment is climbing the fastest as modular force structures expand kit complexity.
End User:
Volume concentration in ground forces contrasts with premium pricing power in specialized units across procurement hierarchies.
- Army:Ground force scale generates the largest absolute procurement volumes across transportation and maintenance services. Expeditionary logistics modernization in the United States, Germany, and Australia concentrates demand for multimodal distribution hubs.
- Navy:Maritime pre-positioning and at-sea replenishment require specialized underway transfer capabilities. Carrier strike groups sustain continuous supply lines across Indo-Pacific operational theaters.
- Air Force:Tactical airlift operations face acute fuel cost volatility that compresses service provider margins. Aerial refueling tanker fleets enable extended range logistics for coalition operations.
- Special Operations:Rapid-response kitting requirements command premium pricing through mission-specific equipment pre-configuration. EU AI Act compliance thresholds impose the steepest burden on adaptive real-time planning systems for SOF logistics units.
Volume dominance belongs to Army. Special Operations offers the steepest expansion trajectory as adaptive mission profiles proliferate.
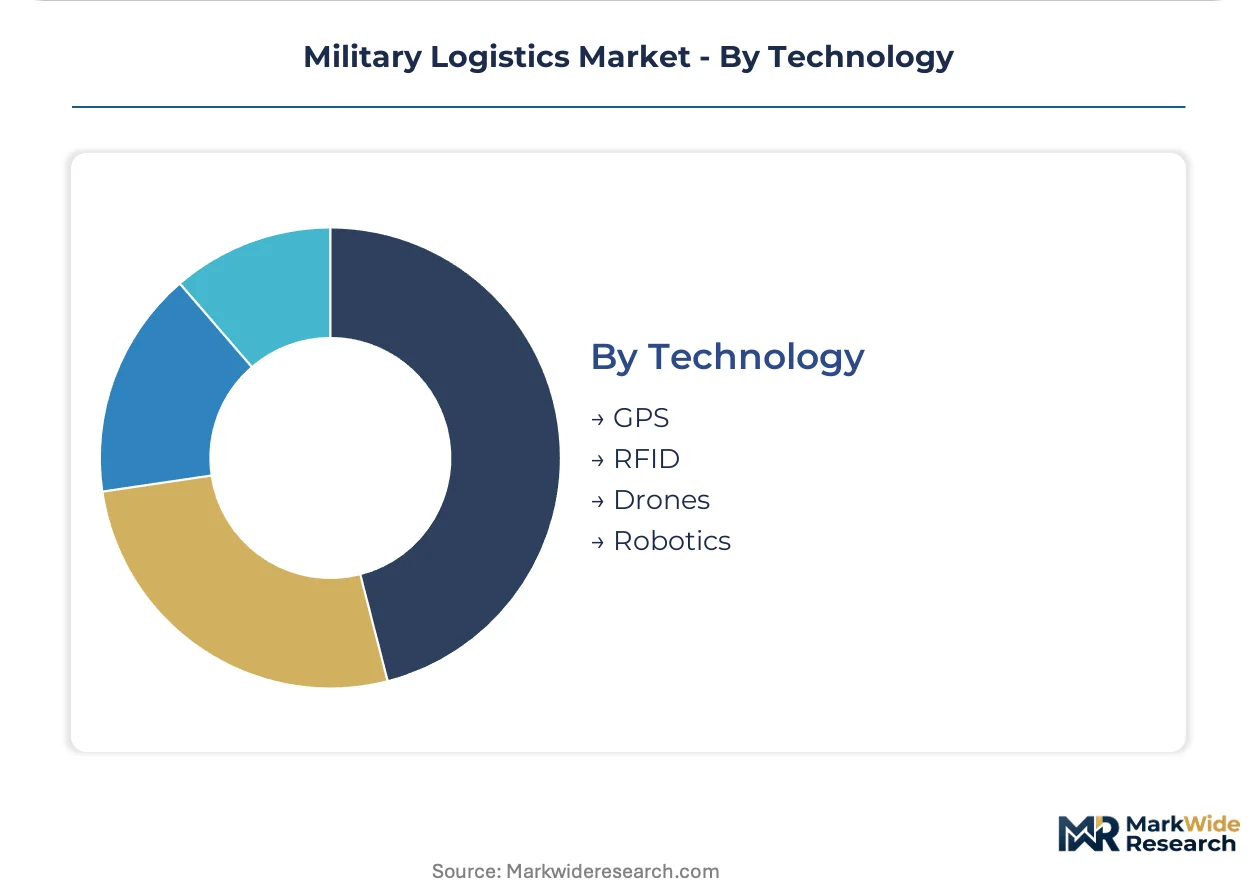
Technology:
Adoption velocity separates established tracking infrastructure from emerging autonomous platforms across capability investment cycles.
- GPS:Satellite-integrated position reporting enables continuous asset visibility across extended supply lines. Coalition operations depend on encrypted military signal resilience against electronic warfare threats.
- RFID:Automated inventory tracking accelerates throughput at distribution nodes and reduces manual reconciliation errors. NATO Standardization Agreements enforce interoperable tag protocols across allied warehouse networks.
- Drones:Unmanned aerial systems penetrate denied-access environments where manned transport faces unacceptable risk. Drone-based resupply redirects capital toward technology-enabled distribution networks for forward-deployed forces.
- Robotics:Autonomous ground vehicles eliminate personnel exposure in contested last-mile delivery scenarios. Army expeditionary units prioritize robotic resupply for forward operating bases under NATO sustainable procurement mandates.
Installed base leadership rests with GPS. Robotics is gaining share fastest as autonomous resupply compresses delivery timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military logistics infrastructure traces its modern architecture to Cold War-era NATO standardization agreements that established interoperable supply networks across Western allied forces. Contemporary demand concentrates in nations modernizing expeditionary capabilities for contested Indo-Pacific and Eastern European theaters.
United States
The U.S. Department of Defense drives the largest procurement volumes through expeditionary force modernization and Indo-Pacific posture realignment. Federal Acquisition Regulation supplements mandate cybersecurity-hardened supply chains with zero-trust architecture requirements. Texas anchors concentrated military logistics infrastructure through Army materiel command facilities and multi-modal distribution hubs supporting global force projection.
Germany
German defense procurement concentrates on sustainable transport modalities under EU Green Deal decarbonization mandates. NATO Standardization Agreements enforce interoperable pallet and container specifications from German industrial clusters. Bavaria hosts specialized military container manufacturing that supplies allied networks across European theater operations.
Australia
The Australian Defence Force modernizes northern territory logistics infrastructure to support expanded Indo-Pacific operational reach. National defense procurement prioritizes climate-hardened distribution nodes capable of sustaining extended supply lines. Darwin and Townsville anchor multimodal hub development connecting continental assets with maritime pre-positioning capabilities.
United Kingdom
UK defense procurement emphasizes rapid-response logistics for coalition expeditionary operations under integrated review force restructuring. Ministry of Defence contracts require commercial-military hybrid network flexibility for surge capacity scenarios. Scotland concentrates naval logistics infrastructure supporting continuous at-sea deterrent and carrier strike group sustainment.
Japan
Japan's defense logistics modernization accelerates under revised national security strategy and counterstrike capability acquisition. METI coordinates dual-use technology transfer frameworks enabling autonomous resupply system development. Nagoya industrial corridors anchor aerospace logistics integration supporting joint operations with allied forces.
Military Logistics Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration depth and sovereign security clearance tiers. The vendor base organizes around three strategic archetypes: integrated defense primes with satellite-enabled tracking infrastructure, commercial-military hybrid logistics operators with multimodal flexibility, and specialized maintenance contractors with predictive platform capabilities. Competitive dynamics favor multi-year performance agreements with penalty clauses over fragmented point-solution contracts, while autonomous system development partnerships reshape capability acquisition patterns.
Within the integrated defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent archetypal positions combining satellite infrastructure with coalition operations visibility. Kuehne + Nagel International AG occupies a distinct hybrid operator position bridging commercial freight scale with military-grade security protocols. These three entities exemplify the competitive segmentation between technology-integrated primes and flexible commercial-military network operators that defense procurement offices now consolidate around for end-to-end accountability.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems |
| Lockheed Martin Corporation |
| L3Harris Technologies Inc. |
| KBR Inc. |
| RTX Corporation |
| The Boeing Company |
| Kuehne + Nagel International AG |
| General Dynamics Corporation |
| Others |
Cost & Logistics Intelligence
Jet fuel cost volatility cascades through transportation service tiers, compressing margins for tactical airlift operators while premium-margin rapid-response kitting absorbs cost shocks through mission-critical pricing power. Defense procurement offices in the United States, Germany, and Australia negotiate multi-year performance agreements that transfer fuel risk to integrated logistics providers.
Pricing Analysis
Contract-based long-term offtake agreements dominate defense procurement, with performance penalties for delivery reliability failures anchoring vendor accountability. Price differentiation separates cybersecurity-hardened supply chains from standard commercial-military hybrid networks, while volume scale discounts concentrate among Army expeditionary logistics contracts. Cost compression in tactical airlift services intensifies as contested fuel markets erode transport margins. Special Operations forces exhibit the least price sensitivity due to mission-critical kitting requirements, whereas commodity equipment movements face the steepest procurement pressure.
Supply Chain Analysis
Freight cost intensity concentrates supply chain investment in German industrial clusters for specialized military pallet manufacturing, in Texas for Army materiel command infrastructure, and in Australia's northern territory for Indo-Pacific distribution hubs. Raw material dependencies center on aerospace-grade aluminum alloys, encrypted GPS chipset supply, and hydrogen fuel cell components for sustainable transport assets. Single-source vulnerability in NATO-standard container specifications creates disruption risk across allied networks. Distribution runs through satellite-integrated tracking infrastructure that sustains coalition operational visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal compounds procurement demand for decarbonized military transport modalities, redirecting capital toward electric and hydrogen-powered distribution assets across European defense ministries.
For Market Incumbents: To counter autonomous resupply technology disruption, Lockheed Martin and Northrop Grumman should deepen satellite-integrated tracking infrastructure investments while securing zero-trust cybersecurity certification for vendor networks under U.S. Federal Acquisition Regulation supplements. Capacity addition in Australian northern territory hubs captures Indo-Pacific posture realignment demand. For New Entrants and Emerging Players: Enter via predictive maintenance platform development for Army motor pool operators, where siloed maintenance schedules create white-space opportunity for continuous readiness dashboard integration. Special Operations rapid-response kitting offers the most penetrable premium-margin segment through mission-specific equipment pre-configuration with sub-24-hour deployment protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented point-solution contracts give way to multi-year performance agreements with penalty clauses. Long-term viability favors integrated logistics service providers capable of end-to-end accountability across transportation, warehousing, and maintenance. Acquisition targets should demonstrate autonomous ground vehicle development partnerships or commercial-military hybrid network scale. The signal to watch is EU AI Act compliance threshold enforcement for algorithmic route optimization systems.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Resupply System Deployment | Eliminates personnel exposure in contested last-mile delivery scenarios for forward operating bases. |
| Satellite-Integrated Tracking Infrastructure | Lockheed Martin leverages encrypted military signal resilience for coalition operational visibility. |
| Commercial-Military Hybrid Network Expansion | Kuehne + Nagel bridges commercial freight scale with military-grade security protocol integration. |
| Predictive Maintenance Platform Integration | Army motor pool operators compress downtime windows through unified equipment readiness dashboards. |
| EU Green Deal Compliance Investment | German defense procurement redirects capital toward hydrogen-powered distribution assets. |
Research Approach
Bottom-up Army end-use modeling reconciled against top-down transportation service tracking forms the analytical core of this study. Primary interviews with defense procurement officers, logistics service provider executives, predictive maintenance platform engineers, and Special Operations kitting specialists were validated against NATO Standardization Agreement documentation, U.S. Federal Acquisition Regulation supplements, EU Green Deal implementation frameworks, and Australian Defence Force modernization procurement disclosures. Secondary sources include customs and trade data for military container flows, SEC 10-K filings from integrated defense primes, and satellite infrastructure deployment records.
Historical trendline analysis of expeditionary logistics modernization cycles informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, product category, end-user branch, and technology adoption velocity alongside regional procurement cluster concentration. CAGRs were derived from expenditure pattern extrapolation and capability investment cycle timing. Forecast inputs incorporate fuel cost volatility scenarios and autonomous platform deployment trajectories.
Inputs from defense ministry procurement disclosures were available through the study window; gaps in classified Special Operations expenditure data introduce uncertainty bands around rapid-response kitting segment projections. Forecasts reflect documented assumptions regarding NATO alliance cohesion and EU regulatory enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market