
 Africa Non-Alcoholic Beverages Market | 2026-2036
Africa Non-Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Non-Alcoholic Beverages Market Intelligence
The Africa non-alcoholic beverages sector is recalibrating around a widening gap between premium functional drinks and commodity soft drinks. Danone leverages its dairy-based beverage expertise to capture health-conscious urban consumers. The Coca-Cola Company sustains extensive distribution networks that dominate rural and peri-urban penetration. PepsiCo differentiates through snack-and-beverage bundling that strengthens convenience store presence.
Non-alcoholic beverages comprise formulated drinks excluding ethanol, typically containing water, sweeteners, acids, flavorings, and functional additives processed through carbonation, pasteurization, or aseptic filling to achieve shelf stability and sensory consistency. Their primary commercial purpose is mass-market hydration, refreshment, and nutritional supplementation across consumer and food service channels. Bottled water and soft drinks represent mature volume pillars with established margin compression, while juice and tea segments attract premiumization through natural positioning and herbal flavor profiles. Distribution through supermarkets and convenience stores still commands structural weight, though online retail gains traction among millennials and health-conscious consumers seeking subscription-based replenishment.
National regulators including Nigeria's National Agency for Food and Drug Administration and Control, South Africa's Department of Health, and Kenya's Bureau of Standards enforce sugar content thresholds, labeling requirements, and additive approvals that reshape formulation strategies. Compliance costs favor scaled manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving front-of-pack warning label mandates and plastic packaging levies that threaten to redistribute competitive advantage toward localized production and biodegradable material adoption.
Market Dynamics
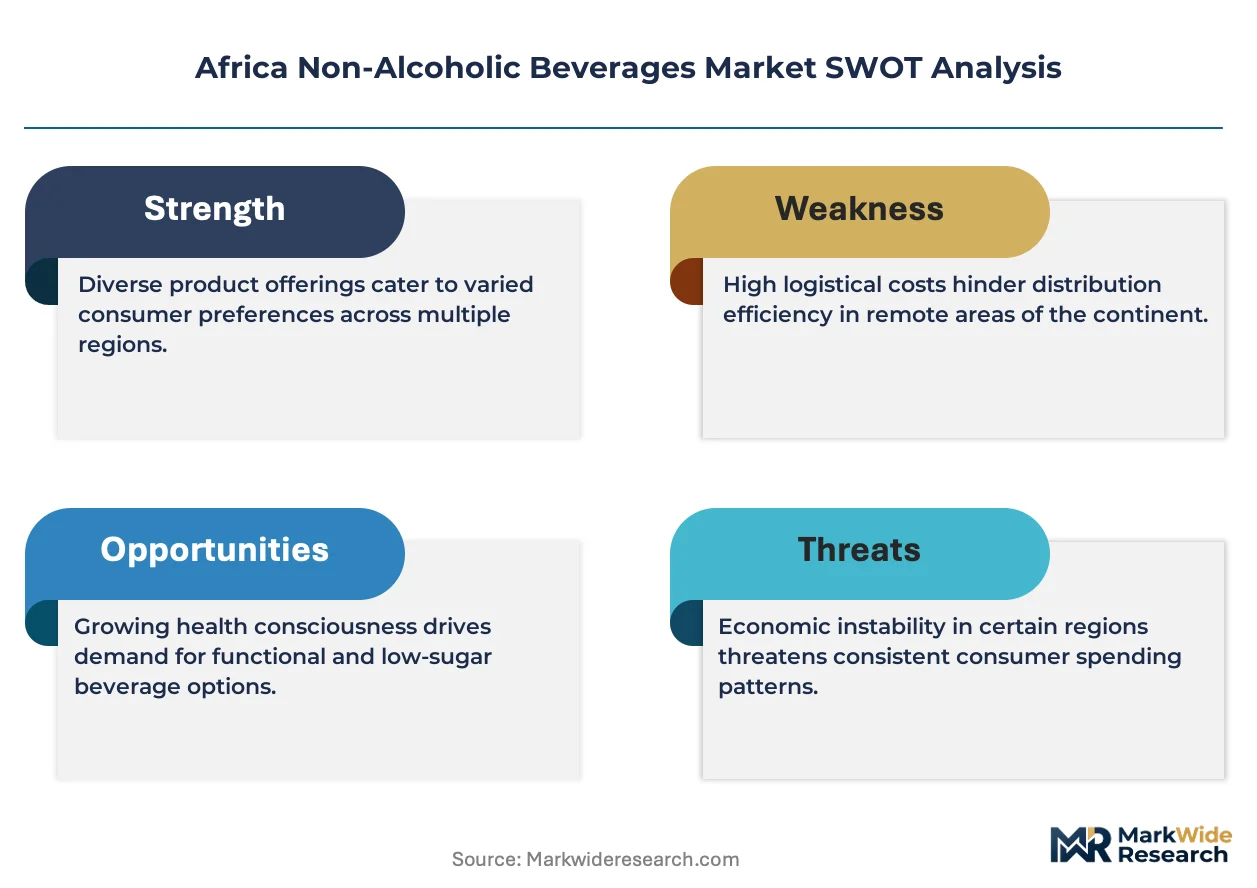
Urban millennials across Lagos, Nairobi, and Accra are compressing demand cycles for functional beverages, forcing manufacturers to accelerate clean-label reformulation and localized sourcing to meet tightened sugar thresholds from Nigeria's NAFDAC and Kenya's Bureau of Standards.
Growth Catalysts
- NAFDAC sugar-content mandates:Nigeria's front-of-pack labeling rules are accelerating reformulation investments among scaled manufacturers with dedicated regulatory affairs capacity.
- Modern trade channel expansion:Supermarket and convenience store penetration in Accra and Lagos is absorbing volume from informal retail, creating shelf-space premiums for branded functional drinks.
- Stevia and monk fruit adoption:Natural sweetener substitution is enabling premium positioning without triggering regulatory penalties across West African markets.
Market Restraints
- Petrochemical input volatility:PET resin and aluminum can costs fluctuate with crude oil benchmarks, compressing margins for producers without backward integration into packaging.
- Concentrated sweetener supply:Stevia extraction capacity clusters in China and Paraguay, exposing African formulators to currency and shipping cost shocks.
- Refrigeration infrastructure gaps:Cold-chain deficits in peri-urban Nigeria and rural Kenya limit distribution reach for temperature-sensitive probiotic and fresh-juice segments.
Strategic Opportunities
- Ethiopia and Tanzania underpenetration:Modern trade density in Addis Ababa and Dar es Salaam remains below Lagos levels, offering first-mover shelf positioning for health-positioned entrants.
- Subscription replenishment models:Direct-to-home delivery platforms in Nairobi and Johannesburg are absorbing repeat-purchase volume from traditional retail, reducing working capital requirements.
- Biodegradable packaging mandates:Kenya's 2020 single-use plastic ban and Nigeria's pending EPR regulations are creating competitive wedges for localized biodegradable material producers.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified compliance professionals capable of navigating NAFDAC, Ghana FDA, and Kenya Bureau of Standards simultaneously command premium compensation in Lagos and Nairobi.
- Legacy distributor integration:Informal wholesaler networks in West Africa resist ERP system adoption, creating data visibility gaps for demand forecasting and inventory optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Non-Alcoholic Beverages Market |
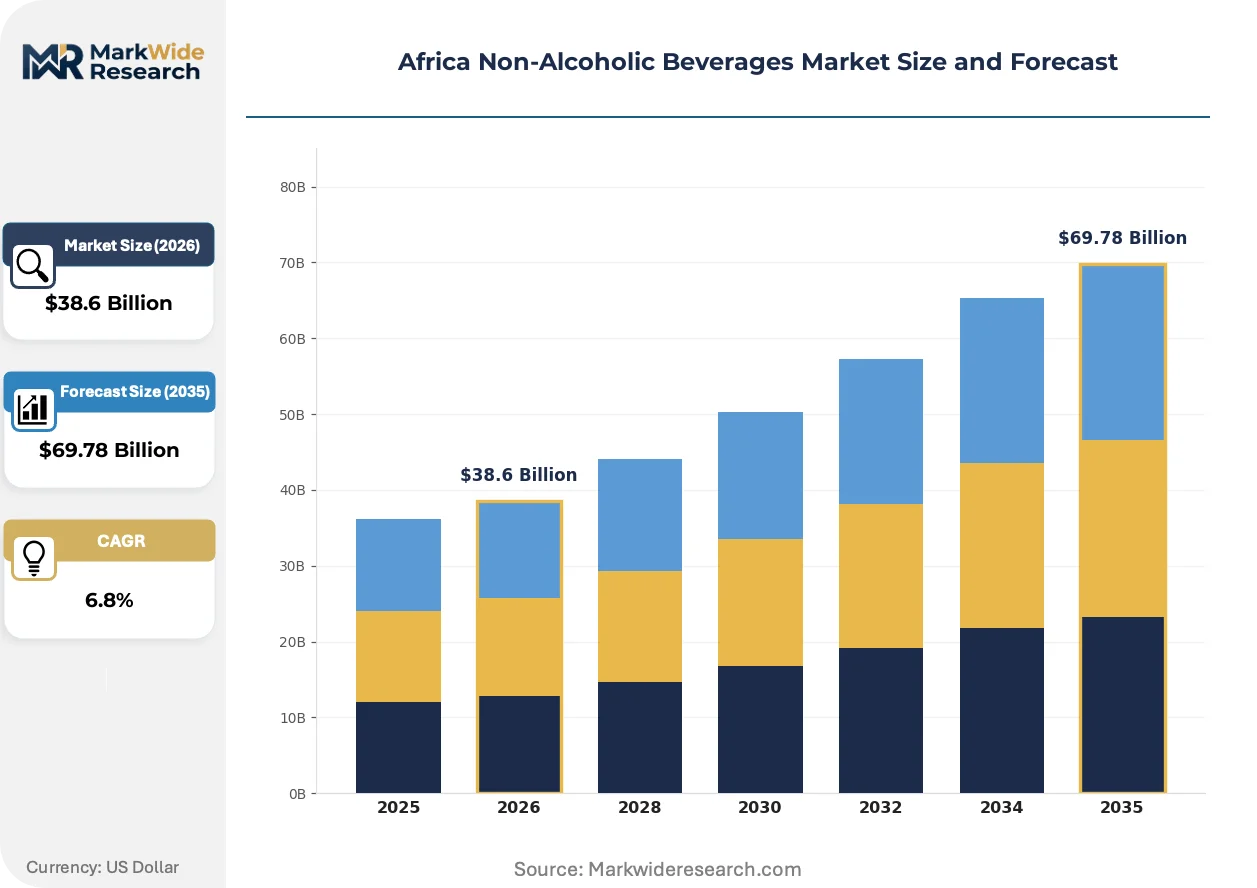
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Juice, Bottled Water, Tea Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Consumer Segment: Health-Conscious Consumers, Millennials, Families, Students Flavor Profile: Citrus, Berry, Herbal, Tropical |
| Companies Covered | Danone, Anheuser-Busch InBev, The Coca-Cola Company, Varun Beverages, Diageo, PepsiCo, Red Bull, Yakult Honsha, Nestlé, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Non-Alcoholic Beverages Market Strategic Shifts & Innovations
Reformulation chemistry and distribution technology are converging to reshape competitive advantage, with natural positioning and cold-chain digitization separating premium aspirants from commodity soft-drink incumbents.
Aseptic filling technology is absorbing capital allocation from carbonation infrastructure across Nigerian and Kenyan manufacturing facilities. Mid-tier producers in Lagos and Nairobi are adopting Tetra Pak and PET aseptic lines to extend shelf life without preservatives, enabling clean-label claims that command retail price premiums. This equipment shift is absorbing technical talent from dairy processors and compressing the viability window for legacy hot-fill operations.
Kenya's Bureau of Standards and Nigeria's NAFDAC are tightening additive approval timelines and mandating front-of-pack warning labels for high-sugar formulations. Manufacturers are responding by accelerating stevia and allulose substitution programs, with compliance costs favoring scaled players over regional bottlers. The juice and dairy-alternative segments face the steepest reformulation burdens, driving consolidation among formulators with in-house analytical laboratories.
Urban millennials in Accra, Lagos, and Nairobi are compressing replenishment cycles through mobile-enabled subscription platforms. Traditional distributor networks are losing share to direct-to-consumer channels that aggregate demand data for predictive inventory positioning. This behavioral shift is most visible in Nairobi's upper-middle suburbs, where quarterly delivery subscriptions for functional waters and kombucha are displacing weekly supermarket stock-up trips.
Africa Non-Alcoholic Beverages Market Segmentation
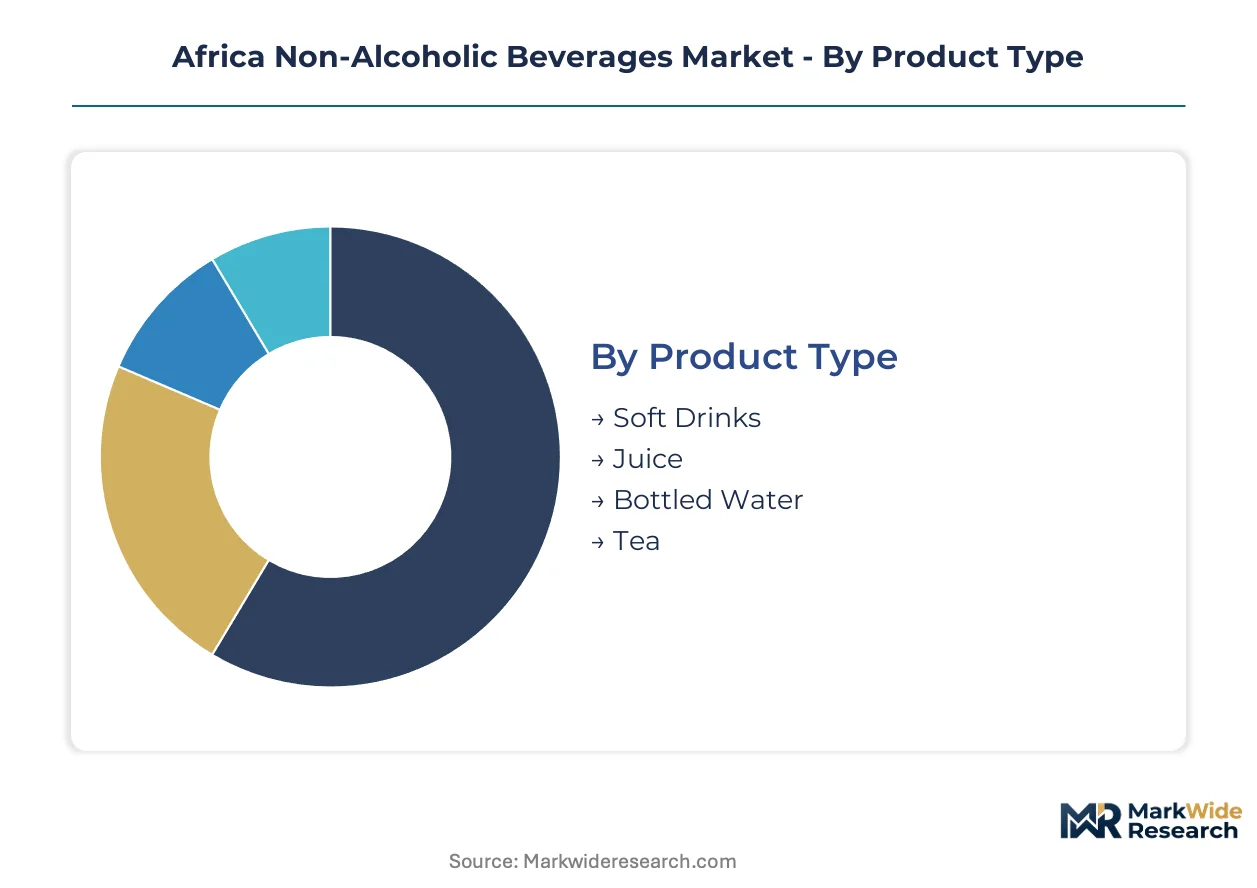
Segmentation in the Africa non-alcoholic beverages market reveals divergent profit pools between commodity hydration and premium functional positioning. Manufacturers must align formulation investment, channel strategy, and packaging specifications to the distinct procurement logic of each buyer cluster.
Product Type:
Purchase frequency and margin structure vary sharply across hydration categories, with urban households splitting weekly budgets between daily staples and occasional premium experimentation.
- Soft Drinks:Carbonated formulations with phosphoric or citric acid bases dominate volume throughput in Lagos and Accra. Reformulation pressure from Nigeria's NAFDAC sugar thresholds is compressing margins for producers without stevia substitution capabilities.
- Juice:Not-from-concentrate and freshly squeezed variants command shelf-space premiums in Nairobi supermarkets. Cold-chain deficits in peri-urban Kenya limit distribution reach for temperature-sensitive pulp formulations.
- Bottled Water:Sachet and PET formats anchor mass-market hydration across West African informal retail. Price per liter has collapsed to commodity levels, forcing producers to differentiate through source certification and mineral content claims.
- Tea:Ready-to-drink formats with rooibos and hibiscus infusions attract health-positioning premiums in South African modern trade. Aseptic filling investments enable clean-label shelf stability without preservative additives.
Volume sits with bottled water; growth tilts toward juice.
Distribution Channel:
Cold-chain requirements and payment terms reshape manufacturer priorities across formal and informal retail infrastructure.
- Supermarkets:Accra and Lagos hypermarkets absorb branded functional drinks through centralized procurement with 30-60 day payment cycles. Shelf-space fees favor scaled manufacturers with dedicated category management teams.
- Convenience Stores:Small-format outlets in Nairobi's upper-middle suburbs stock premium SKUs with higher turnover velocity. Inventory financing constraints limit SKU breadth for independent operators.
- Online Retail:Subscription platforms in Johannesburg aggregate repeat-purchase demand for kombucha and functional waters. Direct-to-consumer channels reduce working capital requirements through prepaid replenishment models.
- Food Service:Hotels and quick-service restaurants in Dar es Salaam specify bulk fountain dispensers and branded glassware. Post-mix syrup contracts lock in multi-year supply relationships with exclusive pouring rights.
Revenue concentrates in supermarkets; expansion accelerates fastest through online retail.
Consumer Segment:
Demographic targeting determines sweetener selection, packaging size, and communication channel allocation across urban Africa.
- Health-Conscious Consumers:Stevia-sweetened and probiotic-positioned formulations attract premium willingness-to-pay in Nairobi's wellness-oriented suburbs. Front-of-pack labeling awareness drives ingredient list scrutiny before purchase.
- Millennials:Mobile-enabled subscription adoption clusters in Lagos and Accra among digitally native professionals. Social media discovery shapes trial behavior for novel flavor launches and limited-edition collaborations.
- Families:Multi-pack formats and value-tier pricing dominate household stock-up trips in Nigerian modern trade. Sugar content concerns increasingly influence brand switching for children's consumption occasions.
- Students:Price-sensitive single-serve purchases concentrate near university campuses in Johannesburg and Nairobi. Sachet and 300ml PET formats match constrained discretionary spending patterns.
Household penetration peaks with families; per-capita spending climbs steepest among health-conscious consumers.
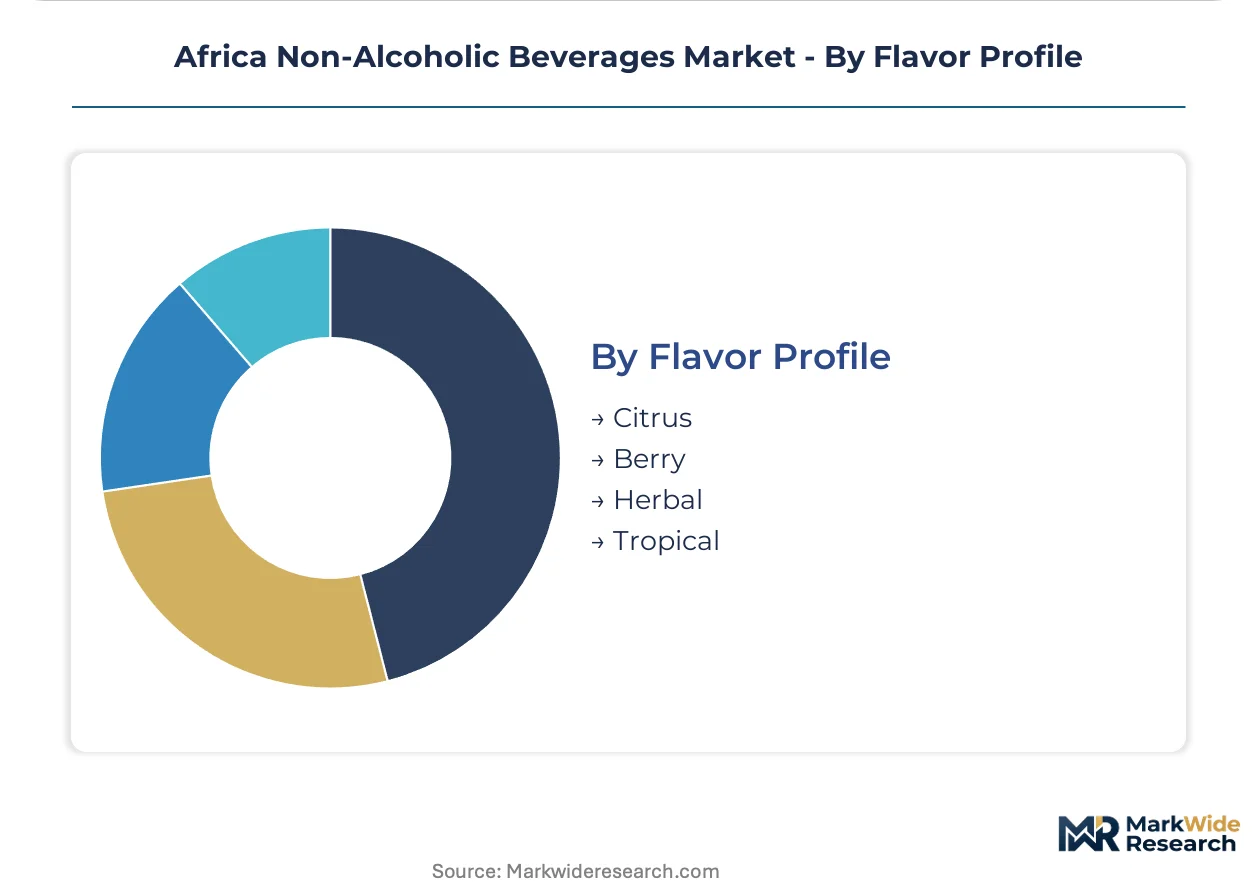
Flavor Profile:
Local ingredient availability and import dependency reshape formulation economics across taste categories.
- Citrus:Orange and lemon formulations leverage established concentrate supply chains from Egyptian and Spanish processors. Mature demand limits differentiation potential beyond vitamin C fortification claims.
- Berry:Cranberry and mixed-berry blends attract premium positioning in South African retail despite imported puree costs. Supply concentration in European and North American processors exposes formulators to currency volatility.
- Herbal:Rooibos, hibiscus, and moringa infusions enable localized sourcing narratives with distinctive African provenance. Kenya's Bureau of Standards and Ghana FDA enforce additive approval timelines for botanical extracts.
- Tropical:Mango, pineapple, and passionfruit formulations dominate West African juice consumption with regional fruit supply integration. Seasonal harvest variability necessitates aseptic storage capacity for year-round production.
Mainstream volume flows through citrus; differentiation concentrates in herbal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors West African beverage consumption through its dense modern trade corridors and millennial-driven demand for functional drinks. Urban clusters in Nigeria, Ghana, Kenya, South Africa, and Ethiopia concentrate distinct regulatory and channel dynamics that reshape manufacturer priorities across the continent.
Nigeria
Lagos and Abuja drive volume through supermarket expansion and convenience store penetration. NAFDAC enforces front-of-pack sugar warning labels that accelerate stevia reformulation timelines. The Lekki Free Trade Zone hosts manufacturing investments targeting export corridors into neighboring Francophone markets.
Ghana
Accra's upper-middle suburbs absorb premium functional beverages through mobile-enabled subscription platforms. The Ghana FDA tightens additive approval timelines for botanical extracts used in herbal infusions. Tema's port infrastructure supports concentrate imports and regional distribution hub operations.
Kenya
Nairobi's wellness-oriented suburbs command price premiums for probiotic-positioned formulations. The Kenya Bureau of Standards enforces sugar content thresholds and single-use plastic bans that reshape packaging specifications. Mombasa's cold-chain infrastructure limits distribution reach for temperature-sensitive fresh-juice segments.
South Africa
Johannesburg aggregates repeat-purchase demand for kombucha and functional waters through direct-to-consumer channels. The Department of Health mandates labeling requirements that favor scaled manufacturers with dedicated regulatory affairs capacity. Cape Town's rooibos supply chain enables localized sourcing narratives for ready-to-drink tea positioning.
Ethiopia
Addis Ababa's modern trade density remains below Lagos levels, offering first-mover shelf positioning for health-positioned entrants. The country's national food safety agency enforces additive approvals that compress formulation viability windows. Hawassa's industrial park attracts aseptic filling investments targeting East African export markets.
Africa Non-Alcoholic Beverages Market Key Industry Players
Capital-heavy producers compete with asset-light brand licensors across a tiered structure where scaled multinationals dominate volume and regional specialists capture premium niches. The market consolidates around three archetypes: dairy-based functional beverage specialists, carbonated soft drink incumbents with extensive rural distribution, and snack-and-beverage bundlers with convenience store dominance. Competitive moves concentrate on clean-label reformulation acceleration and cold-chain digitization investments that separate premium aspirants from commodity players.
Within the multinational tier, Danone and The Coca-Cola Company occupy positions reflecting divergent strategic foundations. Danone exemplifies the dairy-based functional specialist archetype through its health-conscious urban positioning. The Coca-Cola Company anchors the carbonated incumbent model with extensive rural and peri-urban penetration networks. PepsiCo sits within the bundling archetype that strengthens convenience store presence through snack-and-beverage combinations.
| Leading Market Players |
|---|
| Danone |
| Anheuser-Busch InBev |
| The Coca-Cola Company |
| Varun Beverages |
| Diageo |
| PepsiCo |
| Red Bull |
| Yakult Honsha |
| Nestlé |
| Others |
Cost & Logistics Intelligence
Urban millennial households in Lagos and Nairobi concentrate purchasing power for functional beverages, anchoring a value-based pricing model that ties shelf price to clean-label certification and provenance claims rather than commodity input costs.
Pricing Analysis
Outcome-based pricing anchors premium positioning, with stevia-sweetened formulations commanding retail premiums tied to NAFDAC compliance and front-of-pack label absence. Three-tier pricing structure across premium, standard, and economy levels stratifies by sweetener type and packaging format. Price erosion runs through sachet water and carbonated soft drinks as PET resin volatility compresses margins. Students and peri-urban families exhibit highest price sensitivity; health-conscious consumers in Nairobi's wellness suburbs show lowest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from Nigerian and Kenyan bottlers concentrate stevia extract procurement across China and Paraguay, with monk fruit concentrate drawing from Guilin and Hunan provinces. Raw material dependencies center on PET resin, aluminum can sheet, and natural sweetener concentrates. Single-source vulnerability in concentrated sweetener supply exposes formulators to currency and shipping cost shocks. Distribution runs through modern trade channels in Lagos and Accra, with informal wholesaler networks retaining volume in peri-urban Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into aseptic filling technology and captive stevia cultivation is becoming the decisive competitive lever as clean-label mandates harden across West and East Africa.
For Market Incumbents: Anticipate NAFDAC sugar-threshold enforcement by accelerating in-house analytical laboratory investments and locking multi-year stevia supply contracts before price volatility intensifies. Defensive consolidation through distributor ERP integration will close data visibility gaps that emerging subscription platforms exploit.
For New Entrants and Emerging Players: Peri-urban families in Ethiopian and Tanzanian secondary cities represent the most penetrable buyer archetype, with modern trade density in Addis Ababa and Dar es Salaam trailing Lagos benchmarks by substantial margins. Direct-to-home subscription platforms offer the lowest customer acquisition cost entry vector.
For Investors and Strategic Acquirers: The window for entry favors regional bottlers with dedicated regulatory affairs capacity and existing NAFDAC compliance infrastructure. Long-term viability hinges on acquiring formulators with in-house aseptic filling lines and established relationships with Kenya Bureau of Standards. Watch for Kenya's pending biodegradable packaging mandate enforcement as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Investment | Extends shelf life without preservatives, enabling clean-label claims that command retail premiums in Lagos supermarkets. |
| Natural Sweetener Backward Integration | Captive stevia cultivation reduces exposure to China-Paraguay supply concentration and currency volatility. |
| Subscription Platform Launch | Direct-to-consumer channels aggregate demand data for predictive inventory positioning in Nairobi's upper-middle suburbs. |
| Biodegradable Packaging Transition | Kenya's single-use plastic ban and Nigeria's pending EPR regulations create competitive wedges for early movers. |
| Regulatory Affairs Capacity Build | Simultaneous NAFDAC, Ghana FDA, and Kenya Bureau of Standards navigation commands premium compensation and barriers. |
Research Approach
Multi-period observation of NAFDAC enforcement patterns, Kenya Bureau of Standards additive approval timelines, and modern trade channel expansion rates anchored the trend analysis, supplemented by interviews with category buyers at Lagos hypermarkets, regulatory affairs directors at scaled manufacturers, supply planners at PET resin distributors, and brand managers at functional beverage startups. Secondary validation drew from customs import records for concentrate shipments, Nielsen retail audit data for Accra and Nairobi, and SEC filings of multinational parent companies. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting applied product type, distribution channel, consumer archetype, and flavor profile dimensions across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift velocity. Forecast inputs incorporated aseptic filling capacity buildout schedules and stevia substitution program timelines reported by major formulators.
Revisions become necessary when NAFDAC accelerates front-of-pack warning label mandates, Kenya enforces stricter biodegradable packaging requirements, or Ethiopia's national food safety agency tightens additive approval windows beyond current baselines. Deviation in petrochemical input costs or concentrated sweetener supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Ice Tea Market