
 North America Cardiac Rhythm Management Devices Market | 2026-2036
North America Cardiac Rhythm Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cardiac Rhythm Management Devices Market Analytics
US electrophysiology device manufacturing is pivoting toward leadless and MRI-conditional platforms. Medtronic leverages its integrated cath lab ecosystem to sustain catheter and device pull-through across hospital systems. Abbott competes through differentiated mapping and ablation technologies that anchor its position in complex arrhythmia procedures. Boston Scientific Corporation specializes in subcutaneous defibrillator architectures that reduce vascular complications compared with transvenous systems.
Cardiac rhythm management devices encompass implantable and external systems that sense cardiac electrical activity and deliver pacing, defibrillation, or monitoring functions, typically operating at 2.5–3.5 volts with lithium-iodine or lithium-carbon monofluoride batteries lasting 7–15 years depending on therapy burden and device type. These systems primarily restore hemodynamic stability and prevent sudden cardiac death in patients with conduction disorders or tachyarrhythmias. Defibrillators command the dominant share of product type revenue due to premium pricing and expanded indications for primary prevention, while remote monitoring technology grows fastest as cellular and Bluetooth-enabled transmissions reduce in-person clinic visits and enable earlier intervention. Application demand clusters around atrial fibrillation, where ablation volumes and concomitant monitoring create recurring device and service revenue pools.
FDA premarket notification and premarket approval pathways govern device commercialization, while CMS national coverage determinations and local contractor policies directly shape reimbursement access and hospital capital allocation. Health Canada and the FDA coordinate on post-market surveillance through the Medical Device Single Audit Program, streamlining quality system inspections for manufacturers serving both markets. Stakeholders must monitor evolving CMS value-based care metrics that tie reimbursement to procedural outcomes and long-term arrhythmia burden reduction.
Market Dynamics
The migration of cardiac procedures from inpatient to ambulatory surgical centers is compressing device procurement cycles and forcing manufacturers to restructure their hospital sales organizations around outpatient-focused distribution networks.
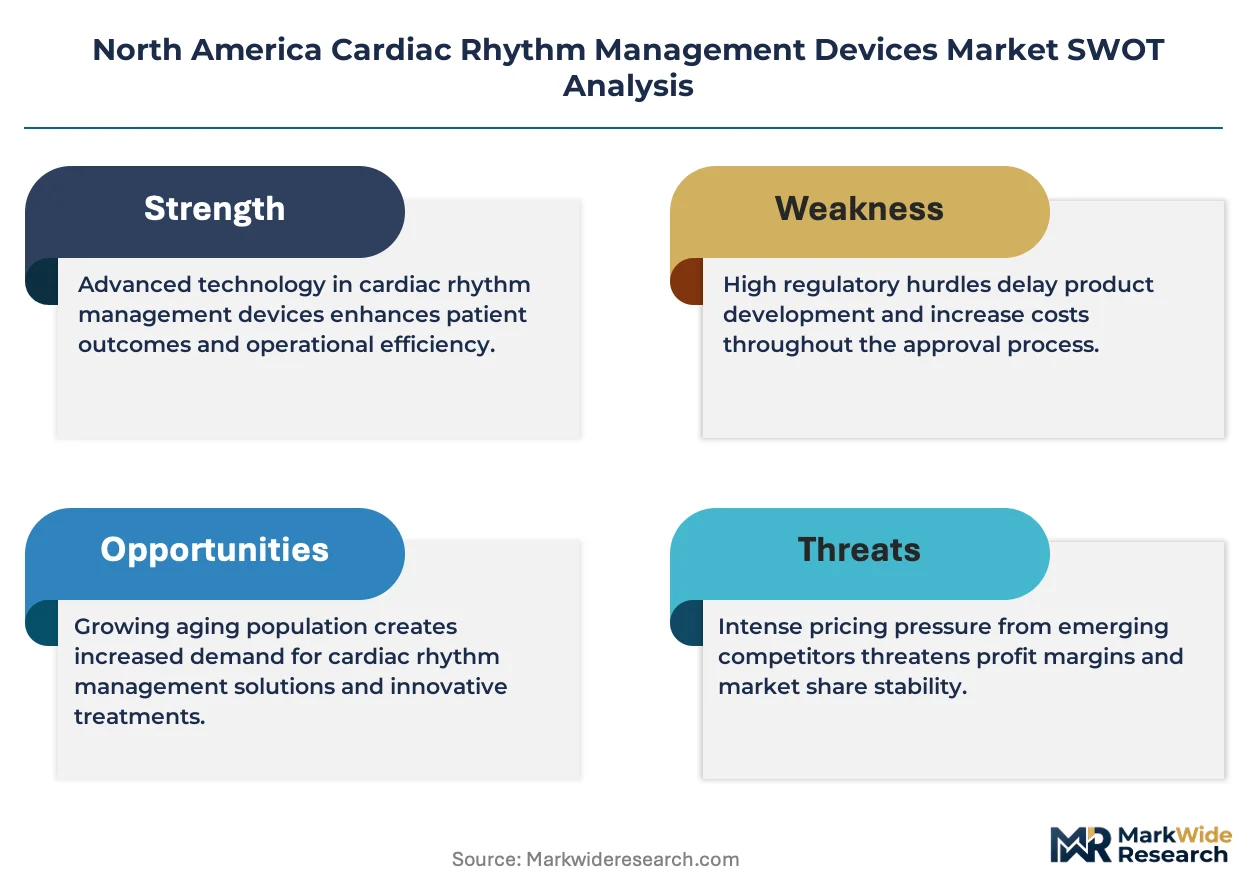
Growth Catalysts
- CMS reimbursement expansion:New reimbursement codes for remote cardiac monitoring incentivize health systems to deploy cellular-enabled implantable devices across their patient populations.
- Ambulatory surgical centers:Outpatient electrophysiology labs in the United States are installing dedicated cath lab equipment to capture shifting procedural volumes from traditional hospitals.
- Leadless pacemaker platforms:Elimination of transvenous leads reduces long-term complication rates and expands eligible patient pools beyond traditional indications.
Market Restraints
- Lithium-iodine battery chemistry:Supply concentration for high-purity lithium compounds creates input cost volatility and limits alternative sourcing strategies for device manufacturers.
- FDA premarket approval timelines:Extended review cycles for novel defibrillator algorithms delay commercialization and compress effective patent life for rhythm detection innovations.
- Transcatheter pacing alternatives:Convergent cardiac resynchronization therapies from structural heart programs threaten traditional pacemaker volumes in heart failure populations.
Strategic Opportunities
- Canada Health Technology Assessment pathways:Streamlined provincial reimbursement reviews for MRI-conditional devices enable faster adoption across Canadian health authorities compared with legacy approval processes.
- Subcutaneous ICD architectures:Elimination of vascular access requirements opens procedural eligibility to patients with venous occlusion or congenital heart defects previously excluded from defibrillator therapy.
- Bluetooth-enabled patient apps:Direct-to-consumer transmission interfaces reduce clinic infrastructure burdens while capturing real-world performance data for post-market surveillance.
Industry Challenges
- Electrophysiology fellowship pipeline:Procedural complexity growth outpaces training program expansion, creating regional bottlenecks for complex ablation and device implantation services.
- Legacy device cybersecurity:Older pacemaker and ICD platforms lack over-the-air update capabilities, forcing costly field interventions to address emerging vulnerability disclosures.
- Multi-vendor cath lab integration:Mapping systems from different manufacturers require proprietary interfaces that complicate workflow standardization across hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cardiac Rhythm Management Devices Market |
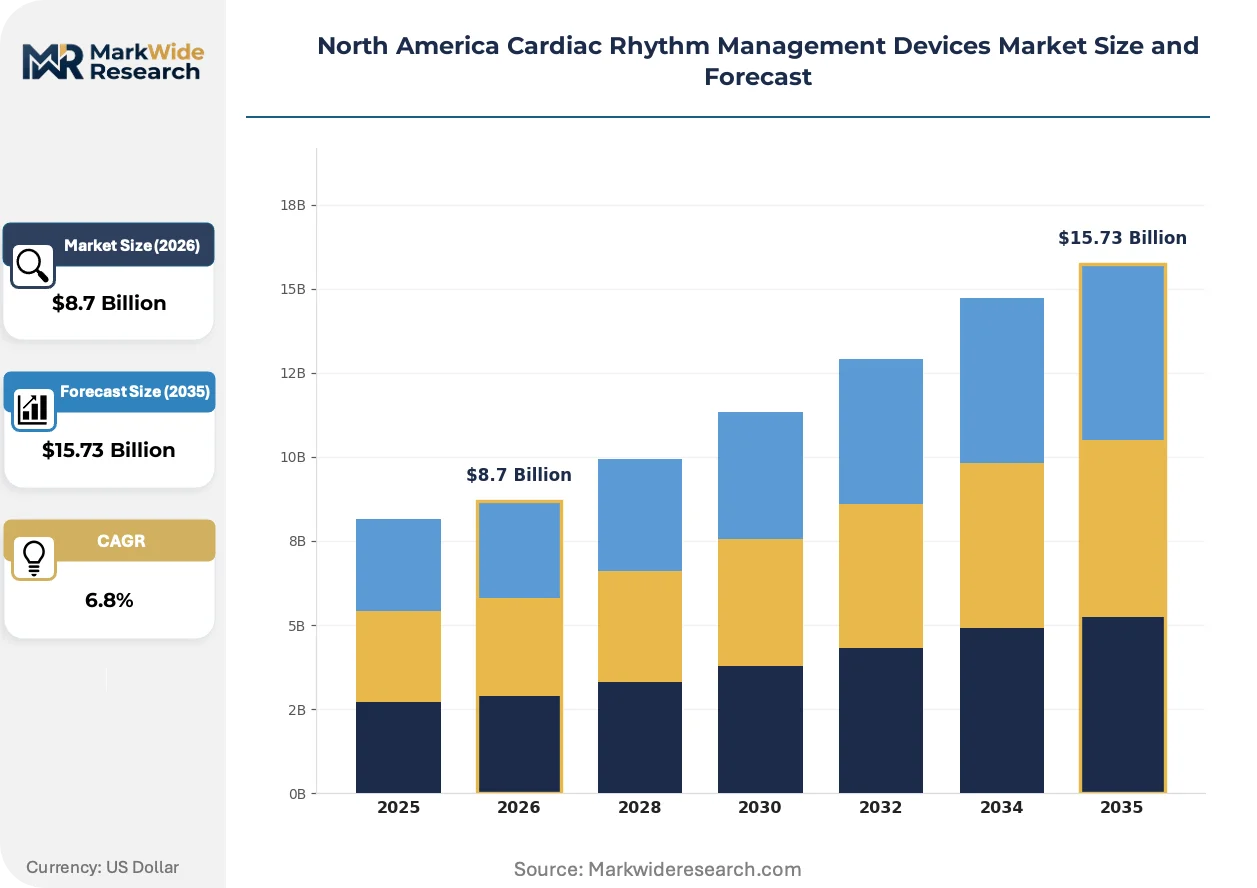
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Defibrillators, Monitoring Devices, Implantable Loop Recorders End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Homecare Technology: Analog, Digital, Wireless, Remote Monitoring Application: Atrial Fibrillation, Heart Failure, Bradycardia, Sudden Cardiac Arrest |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, BIOTRONIK, Koninklijke Philips, Stryker, GE HealthCare, Johnson & Johnson, ZOLL Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cardiac Rhythm Management Devices Market Evolving Landscape
Cardiac rhythm management is converging around platforms that eliminate physical leads while embedding artificial intelligence for automated rhythm classification and predictive intervention.
Leadless pacemaker technology is unifying dual-chamber pacing capability within a single right ventricular implant, eliminating the need for separate atrial hardware. Electrophysiology programs in major United States hospital systems are adopting these platforms for bradyarrhythmia patients with vascular access limitations. This convergence is compressing the traditional pacemaker market structure toward premium-priced, procedure-simplified alternatives that reduce long-term extraction risks.
FDA's evolving cybersecurity premarket guidance for connected medical devices is mandating built-in update capabilities and threat monitoring for new implantable submissions. Device manufacturers are restructuring development pipelines to incorporate software bill of materials and vulnerability disclosure protocols from initial design phases. Implantable cardioverter-defibrillator portfolios face the most immediate compliance pressure, as these devices incorporate the most complex radio-frequency communication stacks.
Health system purchasing consortia are consolidating cardiac device procurement through single-source agreements that bundle devices, catheters, and remote monitoring services into multi-year contracts. Independent electrophysiology practices and smaller hospital systems are losing negotiating leverage as integrated delivery networks capture volume-based pricing discounts. This concentration is most visible across the southeastern United States, where regional health systems have consolidated cath lab purchasing under centralized supply chain governance.
North America Cardiac Rhythm Management Devices Market Segmentation
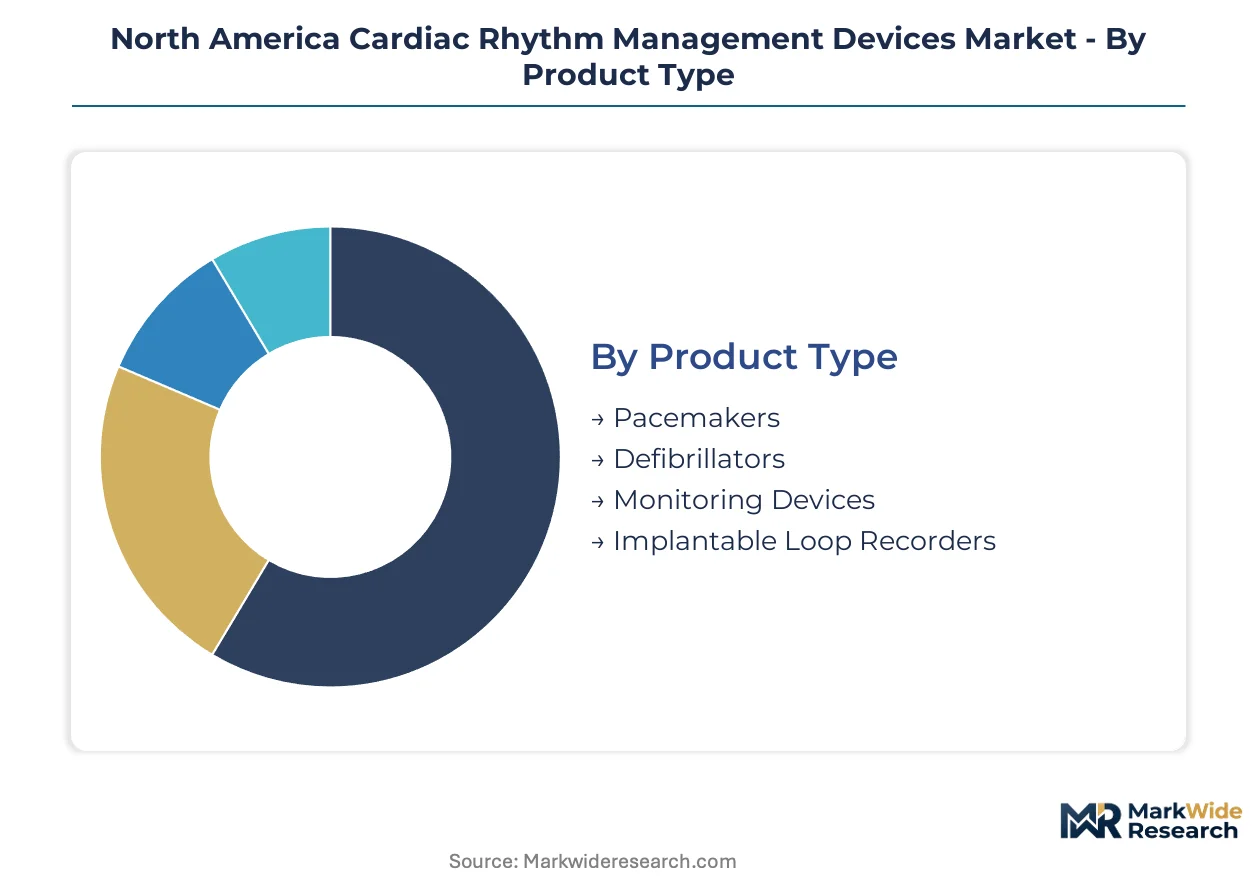
Cardiac rhythm management devices fragment across multiple technical and commercial dimensions, each carrying distinct regulatory pathways and reimbursement profiles that shape manufacturer go-to-market strategies. Understanding how product specifications intersect with end-user purchasing power and clinical workflows enables precise targeting of development resources and sales deployment.
Product Type:
FDA premarket approval timelines vary substantially across this category, with novel defibrillator algorithms facing extended review cycles while incremental pacemaker iterations navigate streamlined notification pathways.
- Defibrillators:These systems deliver high-voltage therapy for ventricular tachyarrhythmias and sudden cardiac death prevention, incorporating sophisticated rhythm detection algorithms and capacitor-based energy delivery. Demand concentrates in United States hospital systems with established electrophysiology fellowship programs, where primary prevention indications expand eligible patient pools beyond traditional secondary prevention cohorts.
- Pacemakers:Devices restore hemodynamic stability in bradyarrhythmia patients through lithium-iodine battery-powered pulse generators connected to transvenous or leadless delivery systems. Canadian provincial health authorities are accelerating MRI-conditional device reimbursement reviews, compressing adoption timelines for next-generation platforms that eliminate magnetic resonance imaging restrictions.
- Monitoring Devices:External telemetry systems capture ambulatory electrocardiographic data for diagnostic workup of syncope and palpitations.
- Implantable Loop Recorders:Subcutaneous devices provide extended arrhythmia surveillance in cryptogenic stroke patients without transvenous hardware.
Defibrillators sit at the top of the volume ranking, with monitoring devices climbing the fastest.
End User:
Procurement authority and capital allocation patterns diverge sharply across this category, influencing contract structures and service bundling requirements.
- Hospitals:Academic medical centers and community hospital systems maintain the deepest electrophysiology program infrastructure, performing complex device implants and generator exchanges under inpatient reimbursement frameworks. United States integrated delivery networks are consolidating cath lab purchasing under centralized supply chain governance, eroding negotiating leverage for independent facilities.
- Ambulatory Surgical Centers:Outpatient electrophysiology labs are installing dedicated catheterization equipment to capture shifting procedural volumes from traditional hospital settings. Southeastern United States health systems have been particularly aggressive in deploying ASC-based device implantation programs, leveraging CMS reimbursement expansion for remote cardiac monitoring to justify capital investment.
- Cardiology Clinics:Physician-owned practices handle device interrogation and programming adjustments without surgical capabilities.
- Homecare:Remote monitoring infrastructure enables direct-to-patient transmission interfaces that reduce clinic infrastructure burdens.
Hospitals retain dominant purchasing volume, though ambulatory surgical centers are gaining share fastest as procedural migration accelerates.
Technology:
Software validation requirements and cybersecurity premarket guidance from FDA create differentiated compliance burdens across this category.
- Remote Monitoring:Cellular and Bluetooth-enabled transmission architectures enable automated device data transmission to centralized monitoring centers, triggering clinical intervention without patient-initiated contact. United States health systems are deploying these platforms across their populations to capture CMS reimbursement codes that incentivize proactive arrhythmia management.
- Digital:Microprocessor-based signal processing delivers enhanced rhythm discrimination and adaptive pacing algorithms compared with legacy analog architectures. Canadian health technology assessment pathways are streamlining provincial reimbursement for digital platforms with embedded artificial intelligence classification capabilities.
- Wireless:Radio-frequency communication stacks eliminate physical telemetry wands during device interrogation.
- Analog:Simplified circuitry persists in cost-sensitive markets and legacy device support obligations.
Remote monitoring commands premium positioning, with digital platforms expanding most quickly as artificial intelligence integration matures.
Application:
Clinical evidence requirements and guideline endorsement status create tiered market access conditions across this category.
- Atrial Fibrillation:The most prevalent sustained arrhythmia drives substantial device and procedural revenue through ablation concomitant monitoring and stroke prevention strategies. United States electrophysiology programs are capturing expanded volumes as catheter ablation gains guideline-directed therapy status for rhythm control beyond antiarrhythmic drug failure.
- Heart Failure:Cardiac resynchronization therapy addresses electromechanical dyssynchrony through biventricular pacing, with indication expansion into milder symptom classes. Transcatheter structural heart alternatives from convergent programs are threatening traditional pacemaker volumes in select heart failure populations.
- Bradycardia:Conduction system disease creates foundational demand for permanent pacing systems.
- Sudden Cardiac Arrest:Secondary prevention indications and primary prevention risk stratification drive defibrillator implantation.
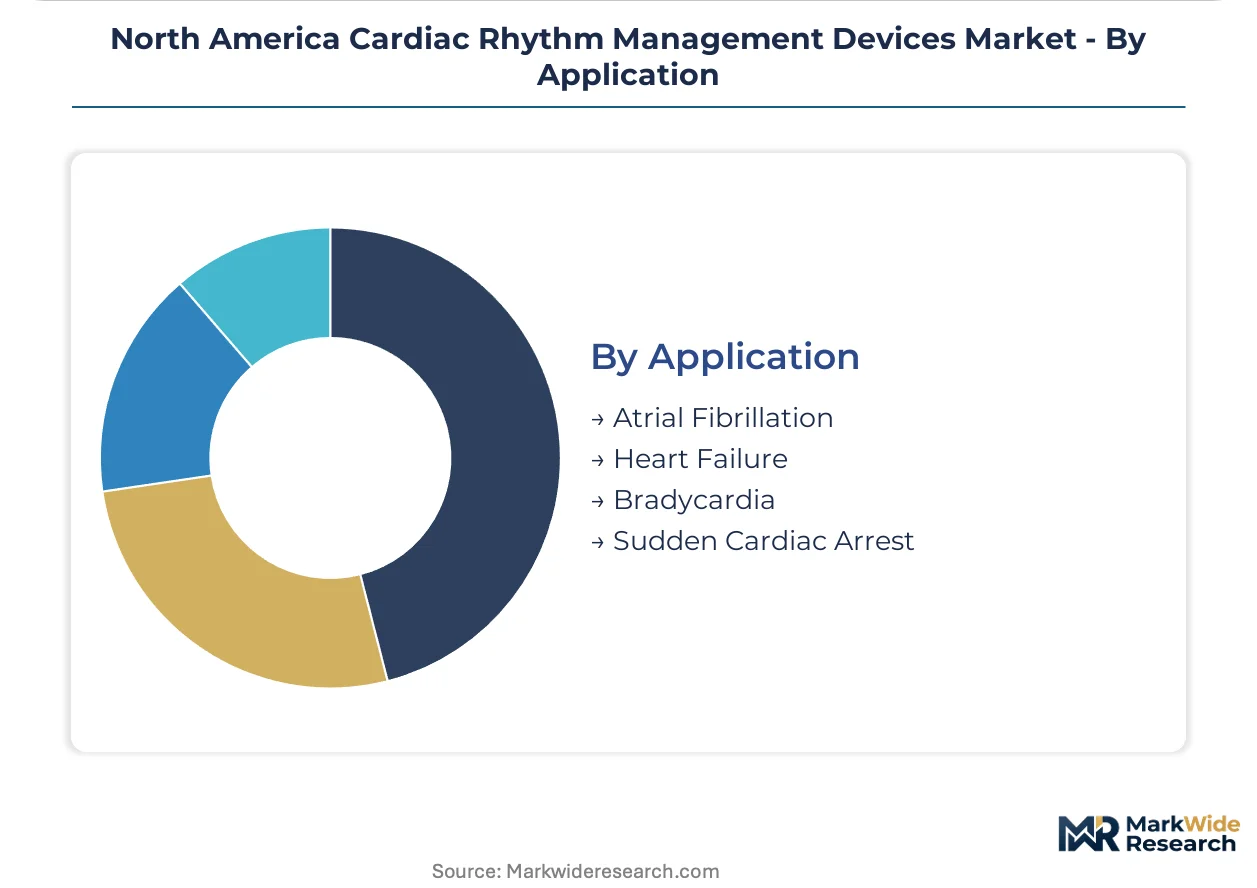
Atrial fibrillation anchors procedure volumes, with heart failure applications showing steepest expansion trajectory as resynchronization indications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger implant volumes than Canada, though Canadian provincial health authorities are compressing approval timelines for MRI-conditional platforms. Mexico's private hospital networks are expanding electrophysiology capacity to capture medical tourism flows from Central America.
United States
FDA premarket approval pathways and CMS reimbursement codes govern commercialization velocity for novel defibrillator algorithms. Integrated delivery networks across the southeastern states have consolidated cath lab purchasing under centralized supply chain governance. Major academic medical centers in Boston and Cleveland anchor complex ablation training pipelines.
Canada
Health Canada coordinates post-market surveillance with FDA through the Medical Device Single Audit Program, streamlining quality inspections for manufacturers. Provincial health technology assessment pathways in Ontario and British Columbia accelerate MRI-conditional device reimbursement compared with legacy processes. Toronto and Vancouver hospital systems deploy leadless pacemaker platforms for bradyarrhythmia patients with vascular access limitations.
Mexico
Private hospital networks in Mexico City and Monterrey are installing dedicated electrophysiology labs to capture regional cardiac procedure volumes. Federal health regulator COFEPRIS maintains alignment with FDA premarket notification standards for imported device clearance. Guadalajara's medical device distribution hub serves expanding ambulatory surgical center networks throughout western Mexico.
North America Cardiac Rhythm Management Devices Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in mapping and ablation technologies. The vendor base concentrates around integrated cath lab ecosystems and subcutaneous defibrillator architectures. Three strategic archetypes dominate: integrated platform providers, specialized ablation technology developers, and cardiac monitoring service bundlers. Competitive moves center on health system purchasing consortia consolidation and remote monitoring infrastructure deployment.
Within the integrated platform tier, Medtronic leverages cath lab ecosystem integration across United States hospital systems. Abbott occupies a differentiated position in complex arrhythmia mapping technologies. Boston Scientific Corporation exemplifies the specialized architecture archetype through its subcutaneous defibrillator focus.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| BIOTRONIK |
| Koninklijke Philips |
| Stryker |
| GE HealthCare |
| Johnson & Johnson |
| ZOLL Medical Corporation |
| Others |
Value Network & Pricing Analysis
Dual-chamber leadless pacemaker premium tiers command threefold pricing multiples over conventional transvenous systems, with that divergence manifesting in concentrated lithium-iodine battery sourcing from Japanese and US chemical suppliers alongside distributed catheter manufacturing across Costa Rican and Malaysian facilities. FDA premarket approval timelines for novel algorithms compress effective patent windows, forcing manufacturers to recover R&D through accelerated premium pricing during abbreviated exclusivity periods.
Pricing Analysis
Distributor margins on implantable defibrillators absorb 18-25 percent of landed hospital cost, with group purchasing organizations extracting volume rebates that compress manufacturer net realization. Three-tier pricing structure across premium MRI-conditional, standard dual-chamber, and economy single-chamber devices stratifies by magnetic resonance compatibility certification and remote monitoring capability. Pricing pressure stems from ambulatory surgical center procurement consortia consolidating purchasing leverage across southeastern United States health systems. Academic medical centers demonstrate lowest price sensitivity due to fellowship training requirements and complex case referral dependencies.
Supply Chain Analysis
Reverse logistics flows for explanted pacemakers and ICDs route through specialized reclamation facilities in Minnesota and Texas, recovering tantalum capacitors and platinum-iridium electrodes for refining. High-purity lithium compound production concentrates in Chile, Argentina, and Australia, with battery cell fabrication anchored in Japan and South Korea. Single-source vulnerability pervades custom integrated circuit fabrication for rhythm detection algorithms, where TSMC and Samsung Foundry capacity allocation determines device launch timing. Distribution runs through dedicated medical device logistics networks with temperature-controlled cold chain requirements for biologic-coated leads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device manufacturers face a geographic-arbitrage opportunity between FDA extended review cycles and Health Canada streamlined provincial assessments, where Canadian MRI-conditional reimbursement acceleration enables 12-18 month earlier market access for equivalent platforms.
For Market Incumbents: Lock in cath lab ecosystem integration through multi-year remote monitoring service bundling that raises switching costs for integrated delivery networks. Defend against leadless pacemaker commoditization by embedding proprietary mapping algorithm dependencies that complicate third-party catheter compatibility.
For New Entrants and Emerging Players: Enter via Bluetooth-enabled patient app development for existing device interrogation, bypassing capital-intensive implantable hardware manufacturing. Target independent electrophysiology practices in Texas and Florida that lack negotiating leverage against consolidated purchasing consortia, offering direct-to-clinic remote monitoring subscriptions without hospital system intermediaries.
For Investors and Strategic Acquirers: Asymmetric upside sits with subcutaneous ICD architecture specialists that eliminate vascular access requirements and expand addressable patient populations beyond traditional transvenous constraints. Long-term viability hinges on cybersecurity update capabilities mandated by evolving FDA premarket guidance. Monitor CMS national coverage determination announcements for remote cardiac monitoring reimbursement expansion as inflection indicators for cellular-enabled device adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Accelerated review timelines for leadless dual-chamber platforms compress competitive windows for first-movers. |
| Hospital System Partnership | Exclusive cath lab equipment agreements with southeastern integrated delivery networks lock out competing catheter vendors. |
| Software Companion Development | Bluetooth-enabled patient apps reduce clinic infrastructure burdens while capturing real-world performance data for post-market surveillance. |
| Reimbursement Strategy | CMS remote monitoring code capture enables ambulatory surgical center capital investment justification for outpatient electrophysiology labs. |
| CE Marking Pathway | European regulatory alignment facilitates Canadian Health Technology Assessment pathway acceleration through established quality system documentation. |
Research Methodology
Multiple input streams — electrophysiology lab directors, hospital purchasing committee administrators, biomedical engineers at major academic medical centers, and GPO contracts managers — were reconciled against FDA 510(k) and PMA filing databases, CMS Medicare claims data, and Health Canada MDALL registration records. Bottom-up implant volume estimates from hospital procurement systems were triangulated with top-down manufacturer revenue disclosures across the analysis window.
Data-stream reconciliation anchored forecast outputs to modeled segmentation across device type, end-user facility category, connectivity technology tier, and clinical application indication. CAGRs were derived from procedure volume trajectories and average selling price evolution assumptions. Forecast inputs incorporated electrophysiology fellowship program expansion rates and ambulatory surgical center certificate-of-need approval timelines.
Inputs from FDA premarket notification databases and CMS national coverage determination records were available through the study window; gaps in proprietary manufacturer pricing disclosures introduce uncertainty bands around net revenue realization estimates. Practitioners should monitor Health Canada provincial reimbursement announcements and FDA cybersecurity guidance updates for early signals of regulatory pathway divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Smart Stairlift Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
IV Poles Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Drainage Catheters Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Catheter Coatings Market