
 Turbocharger Actuators Market | 2026-2036
Turbocharger Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Turbocharger Actuators Market Analytics
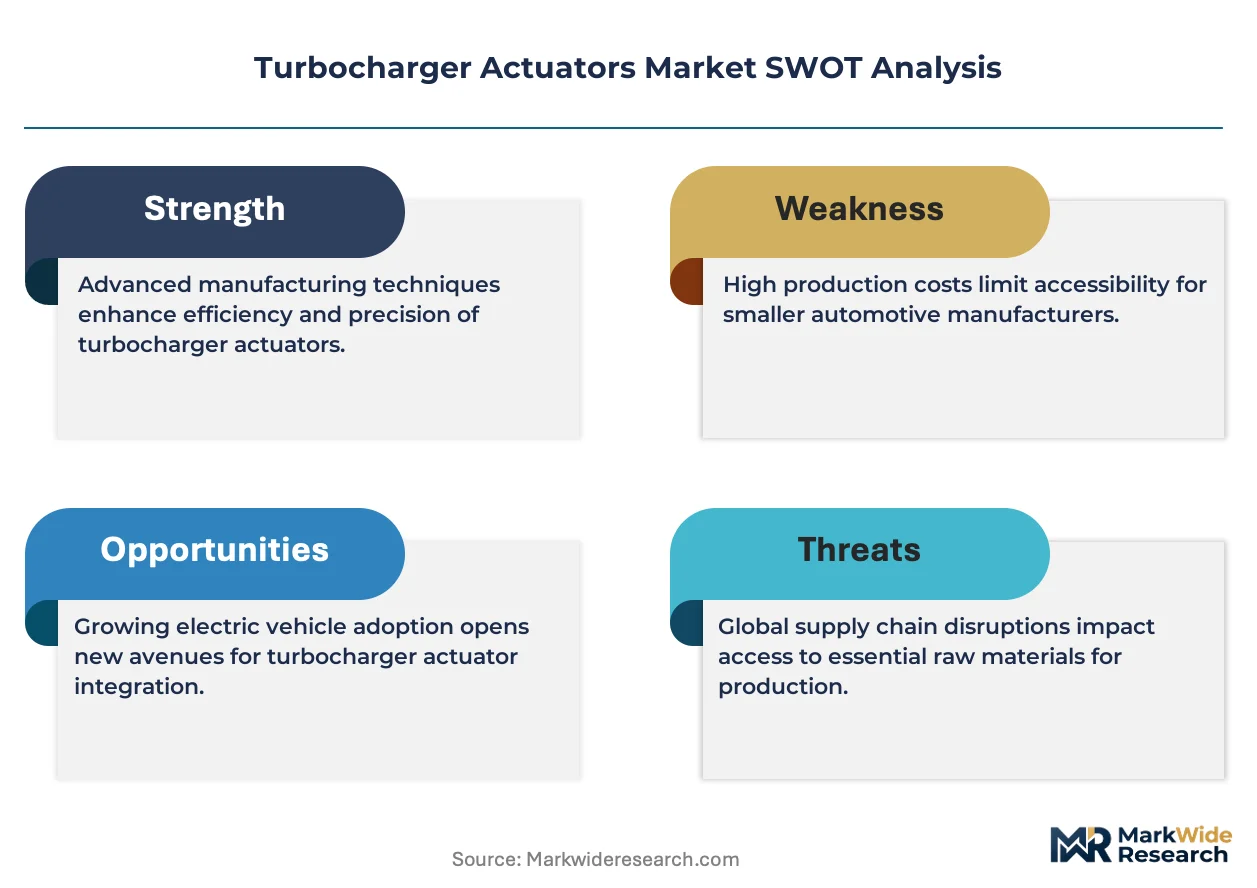
The EU Green Deal is repositioning turbocharger actuator procurement across European automotive supply chains. Continental AG leverages its integrated electronics portfolio to capture factory-installed contracts with premium OEMs. Garrett Motion Inc. anchors its competitive stance through specialized variable geometry actuator designs for light-duty diesel platforms. BorgWarner Inc. dominates aftermarket channels by extending its service network across North American commercial fleet operators.
A turbocharger actuator is an electromechanical or pneumatic device that modulates vane position or wastegate opening to regulate boost pressure, typically operating within temperature ranges exceeding 200°C and response thresholds below 50 milliseconds to maintain optimal air-fuel ratios. Electronic actuators lead the product type landscape due to their compatibility with engine control unit protocols and real-time feedback loops, while pneumatic variants retain cost advantages in retrofitting applications for aging commercial vehicle populations. Variable geometry technology commands the technology segment's margin pool, as dual vane architectures gain traction in hybrid powertrain integrations where transient boost control proves critical.
EPA Phase 3 standards in the United States, Euro 7 proposals under EMA review, and China's GB 18352 emissions enforcement through MEE collectively tighten actuator precision requirements and accelerate OEM validation cycles. These frameworks elevate barrier-to-entry thresholds for aftermarket providers lacking emissions certification capabilities. Stakeholders must monitor how battery-electric vehicle penetration reshapes actuator demand trajectories in long-haul segments versus sustained diesel dependency in emerging market commercial fleets.
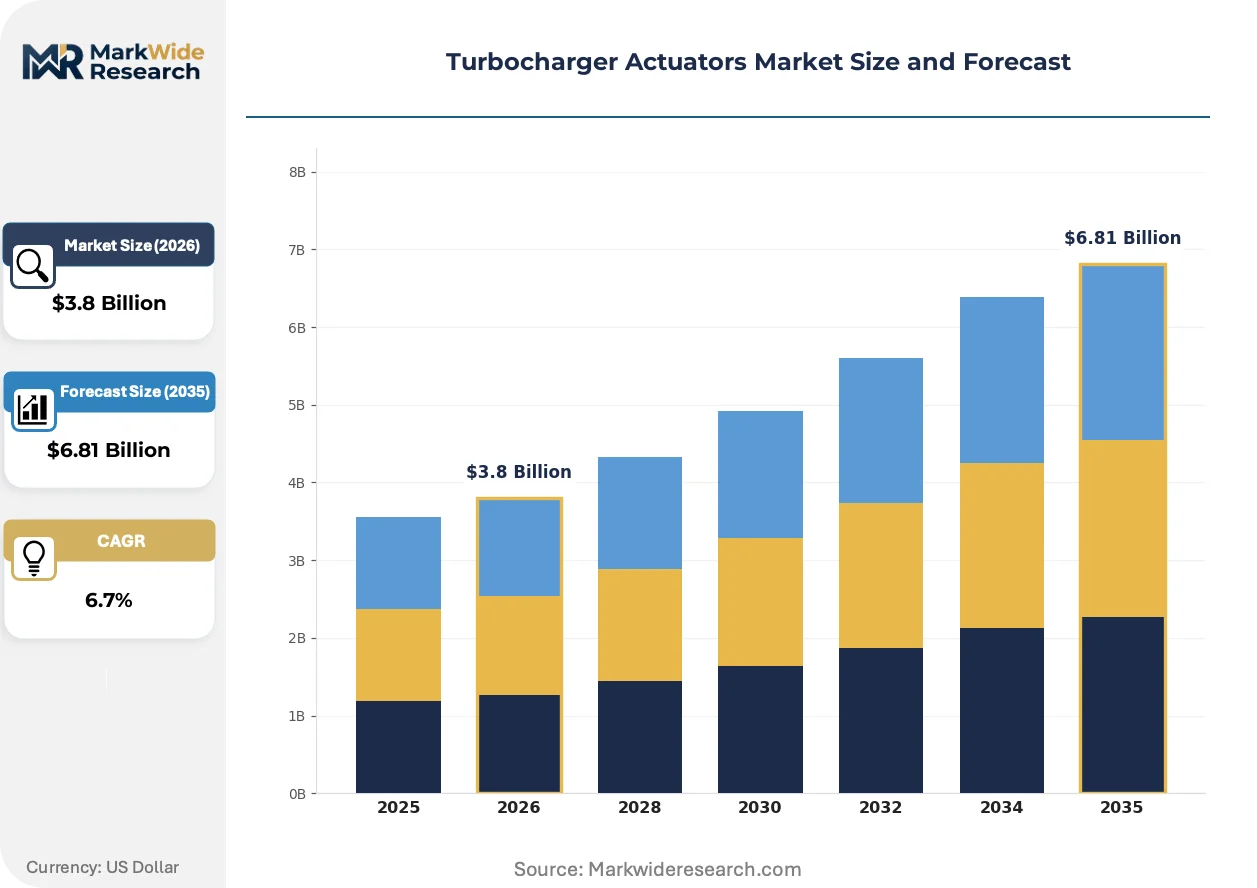
Market Dynamics
Electronic actuator architectures are displacing pneumatic systems as EPA Phase 3 and Euro 7 standards tighten boost-pressure precision thresholds, forcing OEMs to revalidate entire engine control unit integration cycles.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:US commercial fleet operators face mandatory emissions reductions that require precision boost control, accelerating actuator replacement cycles in heavy-duty diesel platforms.
- Hybrid powertrain integration:Dual vane variable geometry architectures enable transient boost response critical for 48V mild-hybrid commercial vehicles, expanding addressable actuator volumes.
- China:GB 18352 emissions enforcement through MEE tightens domestic certification requirements, elevating demand for electronically actuated turbochargers in domestic commercial vehicle production.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies in electronic actuator motors create input cost volatility and geopolitical exposure.
- Thermal durability thresholds:Actuator electronics must sustain continuous operation above 200°C, limiting material substitutions and extending validation timelines.
- Battery-electric substitution:Long-haul trucking electrification trajectories in California and the EU threaten diesel turbocharger actuator demand pools by 2035.
Strategic Opportunities
- India:PLI scheme incentives for commercial vehicle manufacturing attract actuator suppliers to localize production for domestic and export markets.
- Predictive maintenance integration:Sensor-embedded actuators transmitting real-time vane position data enable fleet operators to shift from time-based to condition-based replacement scheduling.
- EU Green Deal:Carbon border adjustment mechanisms favor European-sourced actuators, creating procurement preference tailwinds for regional manufacturers.
Industry Challenges
- Embedded software validation:Functional safety certification to ISO 26262 ASIL-D standards for engine control unit communication protocols extends development cycles and talent requirements.
- Legacy fleet retrofit compatibility:Electronic actuator interfaces require CAN bus infrastructure absent in pre-2010 commercial vehicles, fragmenting aftermarket addressability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbocharger Actuators Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Pneumatic, Hydraulic, Mechanical End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Commercial Fleets Technology: Variable Geometry, Wastegate, Dual Vane, Turbocharger Installation: Factory-installed, Aftermarket, Retrofitting, Custom Solutions |
| Companies Covered | BorgWarner Inc., Continental AG, Garrett Motion Inc., Hitachi Astemo, Ltd., IHI Corporation, Mitsubishi Heavy Industries Ltd., Robert Bosch GmbH, Denso Corporation, Eagle Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbocharger Actuators Market Evolving Landscape
Actuator intelligence is migrating from standalone electromechanical devices to integrated engine management nodes, compressing supplier value chains and redefining competitive differentiation around software-hardware co-design capabilities.
Brushless DC motor technology with integrated position sensing is converging with engine control unit torque-demand mapping algorithms. Tier 1 suppliers are embedding Hall-effect sensors and LIN bus transceivers directly into actuator housings. This convergence is collapsing the historical separation between turbocharger mechanical suppliers and engine electronics specialists.
REACH regulation amendments restricting per- and polyfluoroalkyl substances in high-temperature seals are forcing material transitions to fluorosilicone and perfluoroelastomer alternatives. Seal suppliers must recertify compression set performance across extended thermal cycling regimes. German and Czech turbocharger manufacturers face the steepest compliance cost absorption.
Fleet operators are consolidating actuator procurement under powertrain service agreements rather than component-level purchasing. Independent distributors lose volume to captive dealer networks bundling turbocharger maintenance with engine overhaul contracts. This concentration is most pronounced among North American Class 8 truck operators with centralized maintenance facilities.
Turbocharger Actuators Market Segmentation
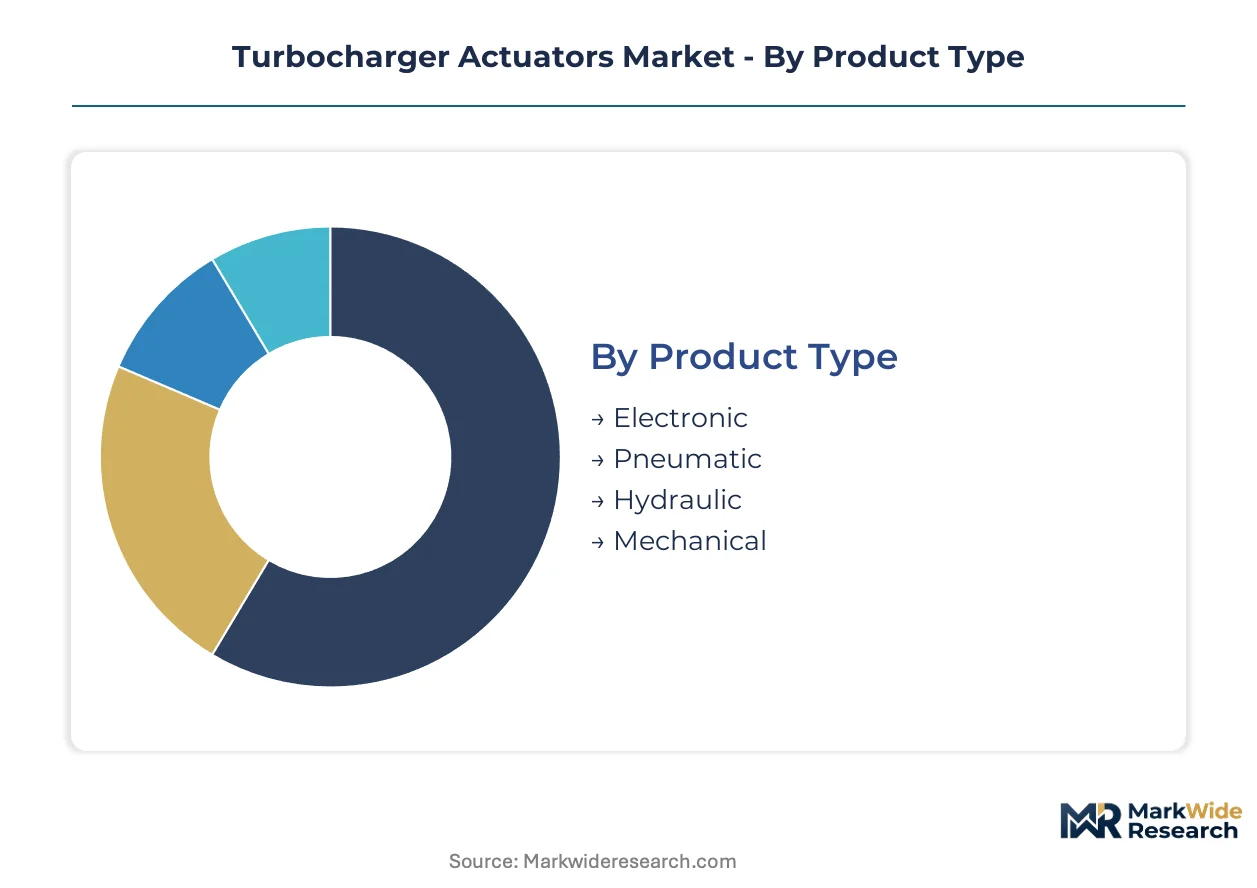
Turbocharger actuator procurement patterns diverge sharply across electronic versus pneumatic architectures, while installation channel preferences separate factory-integrated programs from fragmented aftermarket replacement cycles. Understanding these splits enables suppliers to align validation investments with margin concentration points.
Product Type:
Buyers in this category differentiate primarily by engine control unit compatibility requirements and thermal durability specifications rather than upfront unit cost.
- Electronic:Brushless DC motors with integrated Hall-effect position sensors communicate via LIN bus protocols to engine control units. Demand clusters in German premium OEM supply chains where EPA Phase 3 and Euro 7 precision thresholds mandate real-time feedback loops. Garrett Motion and Continental AG anchor factory-installed contracts through software-hardware co-design capabilities.
- Pneumatic:Vacuum-actuated diaphragm mechanisms modulate wastegate position through pressure differential signals. Commercial fleet operators in North American aftermarket channels favor these units for pre-2010 vehicle retrofits lacking CAN bus infrastructure. Cost advantages persist where emissions certification requirements remain less stringent.
- Hydraulic:Fluid-pressure systems deliver high-force actuation for heavy-duty diesel platforms in mining and construction equipment. Applications concentrate in emerging market commercial vehicle segments where electronic infrastructure penetration lags.
- Mechanical:Direct linkage systems with spring-loaded mechanisms serve legacy vehicle populations and specialized industrial engines. Replacement volumes decline as electronic architectures displace mechanical control across new production.
Volume sits with Electronic actuators; growth tilts toward Pneumatic variants in retrofit-heavy commercial fleet segments.
End User:
Procurement scale and technical specification authority separate stakeholders in this dimension, with OEMs dictating validation protocols that cascade through the supply chain.
- OEMs:Original equipment manufacturers specify actuator performance envelopes during engine platform development, locking suppliers into multi-year supply agreements. IHI Corporation and Robert Bosch GmbH maintain anchored positions in German passenger car and commercial vehicle programs through integrated electronics portfolios.
- Aftermarket Providers:Independent distributors and service networks source replacement units for out-of-warranty vehicles, with procurement consolidating under powertrain service agreements. BorgWarner Inc. extends competitive position through North American service network density.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure actuators as part of complete turbocharger modules rather than discrete components. Sourcing decisions follow engine supplier specifications with limited independent technical authority.
- Commercial Fleets:Centralized maintenance facilities for Class 8 truck operators negotiate volume contracts directly with Tier 1 suppliers, bypassing traditional distribution channels. EPA Phase 3 compliance deadlines accelerate replacement scheduling across US-based fleet operators.
Revenue concentration favors OEMs; margin expansion is steepest among Commercial Fleets consolidating procurement under integrated service agreements.
Technology:
Transient boost response requirements and hybrid powertrain integration complexity drive technology selection in this category.
- Variable Geometry:Dual vane architectures enable continuous vane position adjustment to optimize turbine efficiency across engine speed ranges. Hybrid powertrain applications in 48V mild-hybrid commercial vehicles demand sub-50 millisecond response thresholds that favor electronic actuation.
- Wastegate:Binary or modulated bypass valve configurations divert exhaust flow to control maximum boost pressure. Cost-sensitive light-duty diesel platforms in emerging markets retain wastegate designs where precision requirements permit simpler control strategies.
- Dual Vane:Symmetrical vane arrangements improve flow symmetry and reduce turbine housing thermal stress for high-boost applications. Performance diesel segments in European premium passenger cars specify these architectures for enhanced transient response.
- Turbocharger:Integrated actuator-turbocharger modules where the actuation mechanism is cast into the turbine housing. OEM factory-installed programs favor this approach for assembly line efficiency and warranty consolidation.
Technology margins peak with Variable Geometry; adoption velocity is climbing fastest for Dual Vane configurations in hybrid-integrated powertrains.
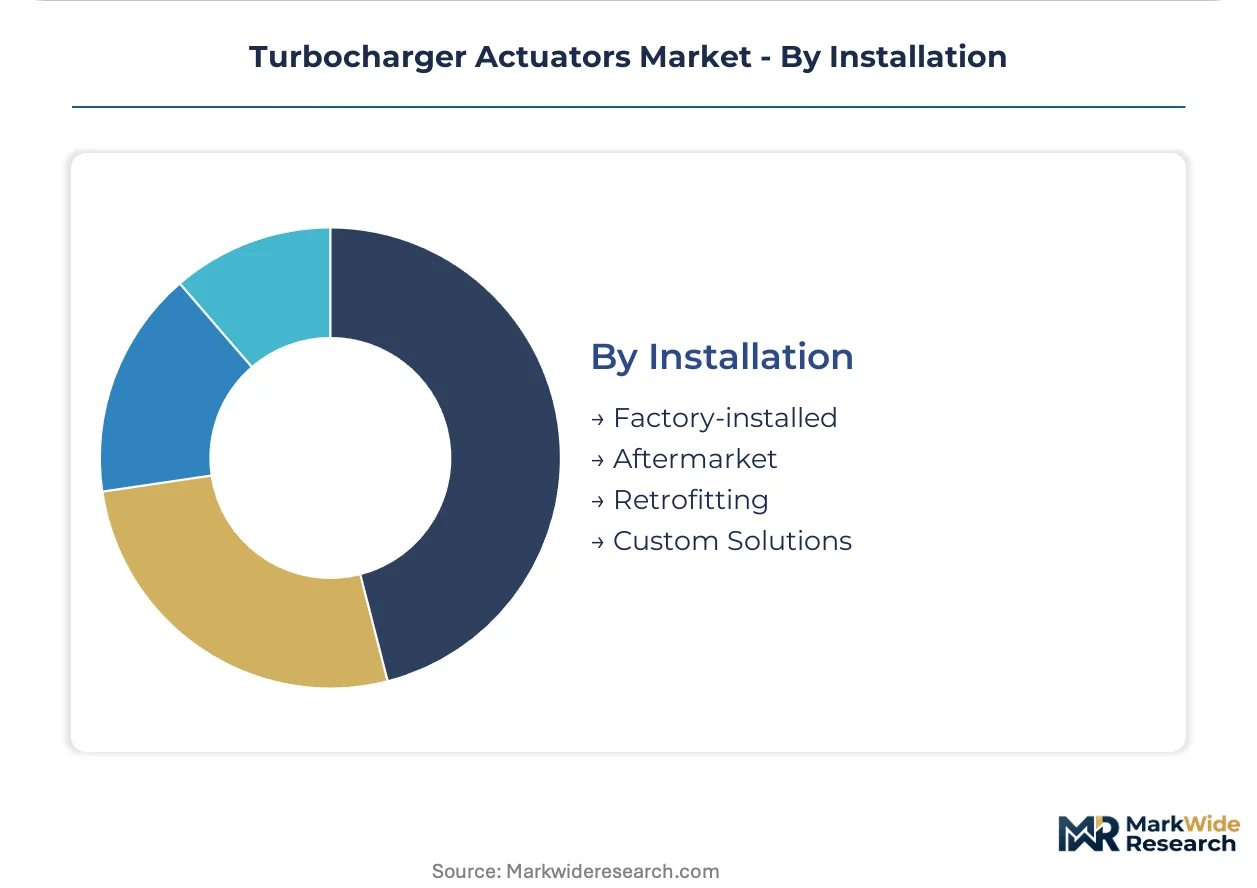
Installation:
Channel economics and technical integration depth separate installation approaches, with factory programs absorbing validation costs that aftermarket channels cannot replicate.
- Factory-installed:Actuators are calibrated to specific engine control unit maps during vehicle assembly, with functional safety certification to ISO 26262 ASIL-D standards. Continental AG and Garrett Motion capture this segment through captive supply relationships with premium OEM platforms.
- Aftermarket:Replacement units must maintain compatibility with original calibration parameters without access to proprietary engine control unit protocols. Independent distributors face margin pressure as fleet operators consolidate procurement under dealer network service agreements.
- Retrofitting:Electronic actuator installation in pre-CAN bus vehicles requires auxiliary control module integration, fragmenting addressable market scope. North American commercial fleets with aging diesel populations drive residual demand for pneumatic-to-electronic conversion kits.
- Custom Solutions:Specialized actuators for racing, marine, and industrial applications operate outside standard automotive validation cycles. Low volumes support premium pricing for suppliers with flexible manufacturing architectures.
Factory-installed channels dominate value capture; Retrofitting applications face structural decline as electronic architecture penetration completes in legacy fleet populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of precision electronic actuators for European OEM supply chains, while the United States consumes the highest volume through commercial fleet replacement cycles. China's domestic commercial vehicle manufacturing absorbs growing actuator volumes under tightened emissions enforcement.
United States
Class 8 truck operators in the Midwest and Southeast are accelerating actuator procurement ahead of EPA Phase 3 compliance deadlines. The EPA mandates precision boost control for heavy-duty diesel platforms starting with model year 2027. Detroit and Columbus anchor concentrated fleet maintenance facilities where powertrain service agreements consolidate component purchasing.
Germany
Premium passenger car OEMs in Baden-Württemberg and Bavaria specify dual vane variable geometry architectures for 48V mild-hybrid integration. The EU Green Deal's carbon border adjustment mechanisms favor regional sourcing for factory-installed programs. Stuttgart and Munich host integrated electronics portfolios where Continental AG and Robert Bosch GmbH maintain anchored supply positions.
China
Domestic commercial vehicle manufacturers in the Yangtze River Delta face GB 18352 emissions enforcement through the MEE. The country's national automotive regulator tightens certification requirements for electronically actuated turbochargers. Shanghai and Wuhan production clusters source actuators for both domestic absorption and export to Belt and Road markets.
Japan
Automotive electronics specialists in the Kanto and Chubu regions supply brushless DC motor architectures to hybrid powertrain programs. METI industrial policy supports precision component manufacturing for next-generation thermal management systems. Toyota City and Nagoya anchor development corridors where Hitachi Astemo and Denso Corporation occupy positions.
India
Commercial vehicle assembly in Maharashtra and Tamil Nadu attracts actuator localization under PLI scheme incentives. The country's national automotive regulator aligns domestic standards with Euro 6-equivalent emissions frameworks. Pune and Chennai manufacturing zones target export markets across Southeast Asia and Africa.
Turbocharger Actuators Market Competitive Landscape
The competitive structure tilts toward integrated electronics conglomerates with captive engine control unit relationships. Tier 1 automotive suppliers dominate factory-installed channels through multi-year platform supply agreements, while specialized turbocharger manufacturers retain aftermarket positioning via service network density. Two strategic archetypes prevail: diversified industrial conglomerates with cross-powertrain electronics portfolios, and dedicated turbocharger system specialists with variable geometry intellectual property. Capacity expansion and software-hardware co-design partnerships represent the dominant competitive moves.
Within the diversified electronics tier, Continental AG and Robert Bosch GmbH represent integrated supplier archetypes with factory-installed positioning, while Garrett Motion Inc. exemplifies the specialized turbocharger system approach. IHI Corporation occupies a position bridging both archetypes through its anchored relationships with German OEMs. BorgWarner Inc. and Denso Corporation sit within distinct geographic supply orbits, with the former extending North American aftermarket presence and the latter anchoring Japanese hybrid powertrain integration.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Continental AG |
| Garrett Motion Inc. |
| Hitachi Astemo, Ltd. |
| IHI Corporation |
| Mitsubishi Heavy Industries Ltd. |
| Robert Bosch GmbH |
| Denso Corporation |
| Eagle Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 26262 ASIL-D validated electronic actuators and uncertified pneumatic alternatives manifests in both pricing power concentration and supply chain tiering. Factory-installed channels command premium positioning through captive engine control unit relationships, while aftermarket distributors absorb margin compression from fleet procurement consolidation.
Pricing Analysis
Cost-down pressure on electronic actuator tiers accelerates because rare earth magnet input volatility and embedded software validation expenses compound manufacturing overhead. Three-tier pricing structure across ASIL-D certified, standard electronic, and pneumatic economy levels stratifies procurement decisions. Price differentiation hinges on functional safety certification grade and volume scale under powertrain service agreements. Commercial fleets exhibit highest price sensitivity in retrofit applications, while German premium OEMs demonstrate lowest sensitivity for factory-integrated programs.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai anchor hub-and-spoke patterns for just-in-time delivery to OEM assembly lines. Manufacturing concentration in Germany, China, and Japan draws from neodymium magnet supplies, fluorosilicone seal compounds, and brushless DC motor subassemblies. Single-source vulnerability in rare earth processing creates exposure to geopolitical disruption. Distribution runs through captive Tier 1 supplier networks rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turbocharger actuator manufacturing is becoming a vertical-integration race as suppliers pursue captive control over brushless DC motor production and engine control unit software co-design capabilities.
For Market Incumbents: Extend software-hardware co-design partnerships with premium OEM platforms to lock in multi-year factory-installed contracts. Deepen backward integration into Hall-effect sensor and LIN bus transceiver production to insulate margins from semiconductor supply volatility. Battery-electric substitution in long-haul segments represents the primary demand threat requiring portfolio diversification.
For New Entrants and Emerging Players: Capture pneumatic-to-electronic conversion kit demand among North American commercial fleets operating pre-2010 vehicle populations lacking CAN bus infrastructure. India's PLI scheme incentives offer the most penetrable geography for localized manufacturing serving Southeast Asian export markets. Pursue predictive maintenance integration as a differentiated go-to-market angle through sensor-embedded actuator development.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized variable geometry actuator specialists given hybrid powertrain integration acceleration across 48V mild-hybrid commercial vehicles. Long-term viability favors suppliers with demonstrated EPA Phase 3 and Euro 7 certification capabilities rather than undifferentiated pneumatic manufacturers. Monitor battery-electric vehicle penetration rates in California and EU long-haul segments as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Hardware Co-Design Partnership | Captures factory-installed contracts with Continental AG and Garrett Motion anchoring premium OEM supply chains. |
| Rare Earth Magnet Supply Agreement | Secures neodymium and dysprosium sourcing from Chinese processors to stabilize electronic actuator motor input costs. |
| Predictive Maintenance Sensor Integration | Enables fleet operators to shift from time-based to condition-based actuator replacement scheduling. |
| India PLI Scheme Localization | Positions manufacturing in Pune and Chennai for domestic absorption and Southeast Asian export markets. |
| EU Green Deal Carbon Border Compliance | Favors European-sourced actuators through carbon adjustment mechanisms creating procurement preference tailwinds. |
Research Methodology
SEC 10-K filings, EPA certification databases, and IHS Markit vehicle production records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and commercial fleet maintenance directors validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation across electronic versus pneumatic actuator shipment data and turbocharger installation rates ensured cross-verification of volume estimates.
Bottom-up modeling aggregated unit economics across product type, technology, and installation channel segments, while top-down analysis cross-checked against regional commercial vehicle production forecasts and emissions regulation implementation timelines. Segmentation dimensions included actuator architecture, end-user procurement authority, variable geometry versus wastegate technology, and factory-installed versus aftermarket channel. CAGRs were derived from regression analysis of historical replacement cycles and regulatory compliance deadline impacts.
The model holds under steady EPA Phase 3 and Euro 7 implementation schedules; deviation in battery-electric vehicle adoption acceleration or rare earth supply disruption would shift demand trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Global Driveline Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Clutch Friction Plate Market
Powertrain
Brazil Automotive Market
Powertrain
Reciprocating Engine Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Engine Rocker Arm Market
Powertrain
Exhaust System Muffler Market
Powertrain
Transmission Oil Filters Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Global Automotive Tappet Market
Powertrain
Automotive Performance Tuning Market