
 Automotive Tuner Market | 2026-2036
Automotive Tuner Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tuner Market Analysis
Skilled ECU calibration engineers is collapsing across the United States and Germany, tightening supply for precision tuning services. Cobb Tuning leverages in-house dyno testing facilities to sustain technology leadership in Subaru and Ford performance platforms. SCT Performance anchors its position through channel control across specialty shops and online retailers serving diesel truck enthusiasts. EcuTek competes by dominating reflashing solutions for Japanese sport compact vehicles.
An automotive tuner is an aftermarket device or software system that modifies engine control unit parameters to increase power output, torque, or fuel efficiency, typically operating within air-fuel ratio tolerances of 12.5:1 to 14.7:1 for gasoline engines. Its primary commercial purpose is enabling vehicle owners and racing professionals to extract performance beyond factory specifications without physical engine rebuilds. Engine management systems command the deepest margin pools due to recurring software update revenue and proprietary map libraries. ECU tuning technology leads volume growth as wireless flash protocols displace bench programming. Performance chips remain a mature segment where price compression limits differentiation.
Federal EPA regulations in the United States restrict tampering with emission control systems, forcing tuners to develop CARB-compliant maps for street-legal sales. KBA type-approval requirements in Germany and equivalent frameworks under Japan's METI shape product standards for European and Asian market access. Stakeholders must monitor enforcement intensity against defeat devices while calibrating R&D investment toward OBD-III readiness and connected-vehicle protocol compatibility.
Market Dynamics
Wireless flash protocols are displacing bench programming as the dominant calibration method, compressing service turnaround times from days to hours while redistributing margin pools from hardware toward software subscriptions and proprietary map libraries.
Growth Catalysts
- EPA emission compliance pathways:CARB-compliant map development enables street-legal sales in the United States, expanding addressable market beyond track-only applications.
- Professional racing procurement:Engine management system purchases by competition teams accelerate as KBA oversight tightens type-approval requirements in Germany.
- Wireless protocol adoption:Over-the-air reflashing technology eliminates physical ECU removal, reducing labor barriers for aftermarket installers.
Market Restraints
- Skilled engineer scarcity:Collapsing supply of ECU calibration specialists in the United States and Germany constrains service expansion.
- Semiconductor input volatility:Engine control module chip sourcing faces concentration risk from limited foundry capacity in Taiwan.
- Defeat device enforcement:EPA and KBA penalties against non-compliant tuning products create liability exposure for distributors.
Strategic Opportunities
- Connected-vehicle protocol integration:OBD-III readiness investments position tuners for factory-authorized calibration partnerships.
- Diesel truck segment channel innovation:Direct-to-consumer platforms bypass traditional specialty shop networks for heavy-duty performance upgrades.
- Japanese sport compact aftermarket:Reflashing solution demand remains underpenetrated relative to United States and European volume.
Industry Challenges
- Dyno facility capex intensity:In-house testing infrastructure requires substantial capital deployment to sustain technology leadership.
- Cross-border certification timelines:KBA type-approval and EPA/CARB dual compliance extend product launch cycles.
- Proprietary map IP protection:Reverse engineering of calibration files threatens recurring revenue from software subscriptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tuner Market |
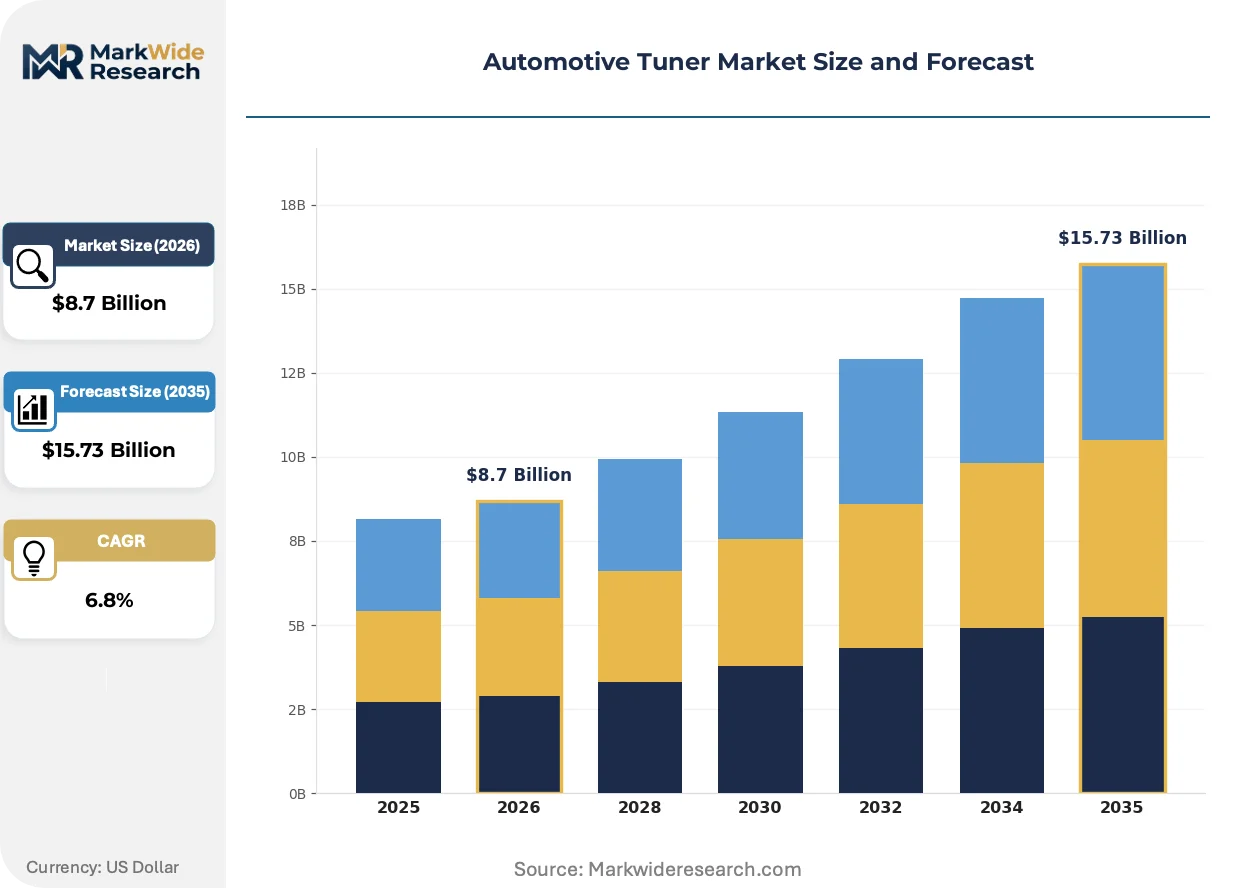
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance Chips, Exhaust Systems, Air Intake Kits, Engine Management Systems End User: Automotive Enthusiasts, Racing Teams, Aftermarket Installers, Vehicle Manufacturers Technology: ECU Tuning, Dyno Testing, Control Modules, Fuel Management Systems Distribution Channel: Online Retailers, Specialty Shops, Automotive Shows, Direct Sales |
| Companies Covered | Superchips, SCT Performance, Cobb Tuning, EFI Live, EcuTek, DiabloSport, Hypertech, Bully Dog, Edge Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tuner Market Emerging Trajectories
Calibration technology is bifurcating between cloud-based map distribution and embedded edge computing, forcing hardware manufacturers to choose between open architecture partnerships and closed ecosystem control.
Cloud-based map repositories are displacing physical storage media as the primary distribution mechanism for performance calibrations. Racing professionals and enthusiast installers now access proprietary tune libraries through subscription portals rather than purchased hardware tokens. This shift compresses upfront hardware margins while extending customer lifetime value through recurring access fees.
EPA enforcement against emission defeat devices is tightening product liability frameworks for aftermarket manufacturers. The regulatory consequence is accelerated investment in compliant calibration architectures that preserve catalytic converter function. Street-legal product lines now command premium positioning over track-only alternatives in United States distribution channels.
Specialty shop consolidation is concentrating procurement authority among fewer, larger installer networks. Independent tuners face disintermediation pressure as SEMA-member chains negotiate direct manufacturer relationships. This channel compression is most visible in United States metropolitan markets where national franchise operations displace single-location service providers.
Automotive Tuner Market Segmentation
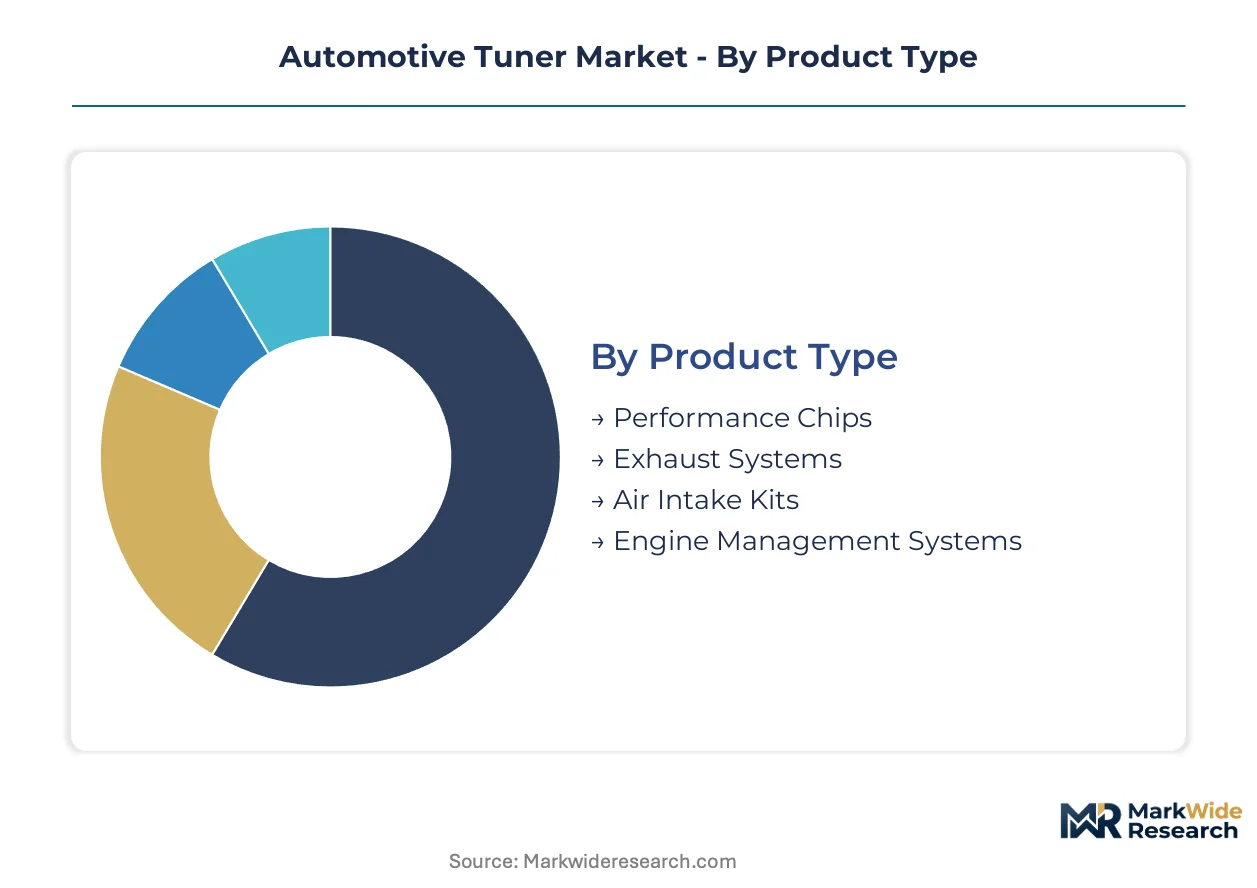
Automotive tuner segmentation reflects divergent compliance burdens and margin architectures across hardware and software categories. Product type and technology dimensions determine exposure to EPA defeat-device enforcement, while end-user and channel splits reveal where wireless flash adoption is compressing service turnaround times.
Product Type:
EPA and KBA emission frameworks create starkly different certification requirements across hardware versus software tuner categories, reshaping R&D allocation and pricing power.
- Engine Management Systems:These integrated control platforms combine processor hardware with proprietary calibration software to manage ignition timing, boost pressure, and fuel delivery across multiple engine maps. Racing teams in Germany under tightening KBA oversight are expanding procurement of these systems as type-approval requirements harden. Recurring revenue from map library subscriptions sustains margin pools unavailable to hardware-only competitors.
- Performance Chips:Plug-in modules intercept factory sensor signals to modify fuel and timing parameters without full ECU replacement. Aftermarket installers in the United States favor these for rapid installation on domestic truck platforms where CARB-compliant variants preserve street-legal distribution. Price compression limits differentiation in this mature segment where Chinese manufacturing has commoditized baseline offerings.
- Exhaust Systems:Cat-back and axle-back configurations reduce backpressure to complement electronic tuning gains. SEMA-member specialty shops bundle these with ECU reflashing to capture install labor revenue.
- Air Intake Kits:Cold-air and short-ram designs increase airflow volume to support richer fuel maps. Enthusiast self-installation dominates volume through online retail channels.
Engine Management Systems handle the majority of throughput; ECU Tuning within technology categories is expanding most quickly on share.
End User:
Customer type determines service intensity, warranty exposure, and compliance documentation requirements across the value chain.
- Aftermarket Installers:SEMA-affiliated service centers and independent shops perform the bulk of professional ECU reflashing and hardware integration. Wireless protocol adoption is eliminating physical ECU removal, reducing labor barriers and compressing service turnaround from days to hours in United States metropolitan markets. Channel consolidation among national franchise operations is concentrating procurement authority and squeezing single-location providers.
- Racing Teams:Professional competition squads demand precision calibration for FIA-sanctioned events and regional series. German KBA oversight on type-approval is accelerating investment in compliant engine management architectures that preserve catalytic function during competition use.
- Automotive Enthusiasts:DIY-oriented owners purchase handheld tuners and smartphone-linked flash tools for garage-based calibration. Direct-to-consumer platforms are bypassing traditional specialty shop networks for heavy-duty diesel upgrades.
- Vehicle Manufacturers:OEM authorized tuning partnerships remain limited but expanding as OBD-III protocols enable factory-sanctioned performance calibrations. Warranty preservation requirements constrain product specifications more tightly than aftermarket alternatives.
Aftermarket Installers dominate volume throughput; Racing Teams are gaining share fastest as compliance investment requirements escalate.
Technology:
Calibration method selection determines capital intensity, intellectual property exposure, and recurring revenue potential.
- ECU Tuning:Software-based parameter modification through OBD-II port access or bench flashing enables power extraction without hardware replacement. Cloud-based map distribution is displacing physical storage media, compressing upfront hardware margins while extending customer lifetime value through subscription portals. Japanese sport compact platforms remain underpenetrated relative to United States and European volume.
- Dyno Testing:Chassis dynamometer validation measures wheel horsepower and torque to verify calibration safety and performance claims. Cobb Tuning and comparable specialists deploy in-house facilities to sustain technology leadership through proprietary test data accumulation.
- Control Modules:Standalone engine controllers bypass factory ECU limitations for heavily modified builds. Semiconductor input volatility from Taiwan foundry concentration constrains module availability during supply disruptions.
- Fuel Management Systems:Auxiliary injector drivers and pump controllers support forced induction applications exceeding factory fuel system capacity. Standalone installations require professional tuning to maintain safe air-fuel ratios.
ECU Tuning commands the deepest margin pools; Dyno Testing carries the steepest expansion trajectory as verification requirements tighten.
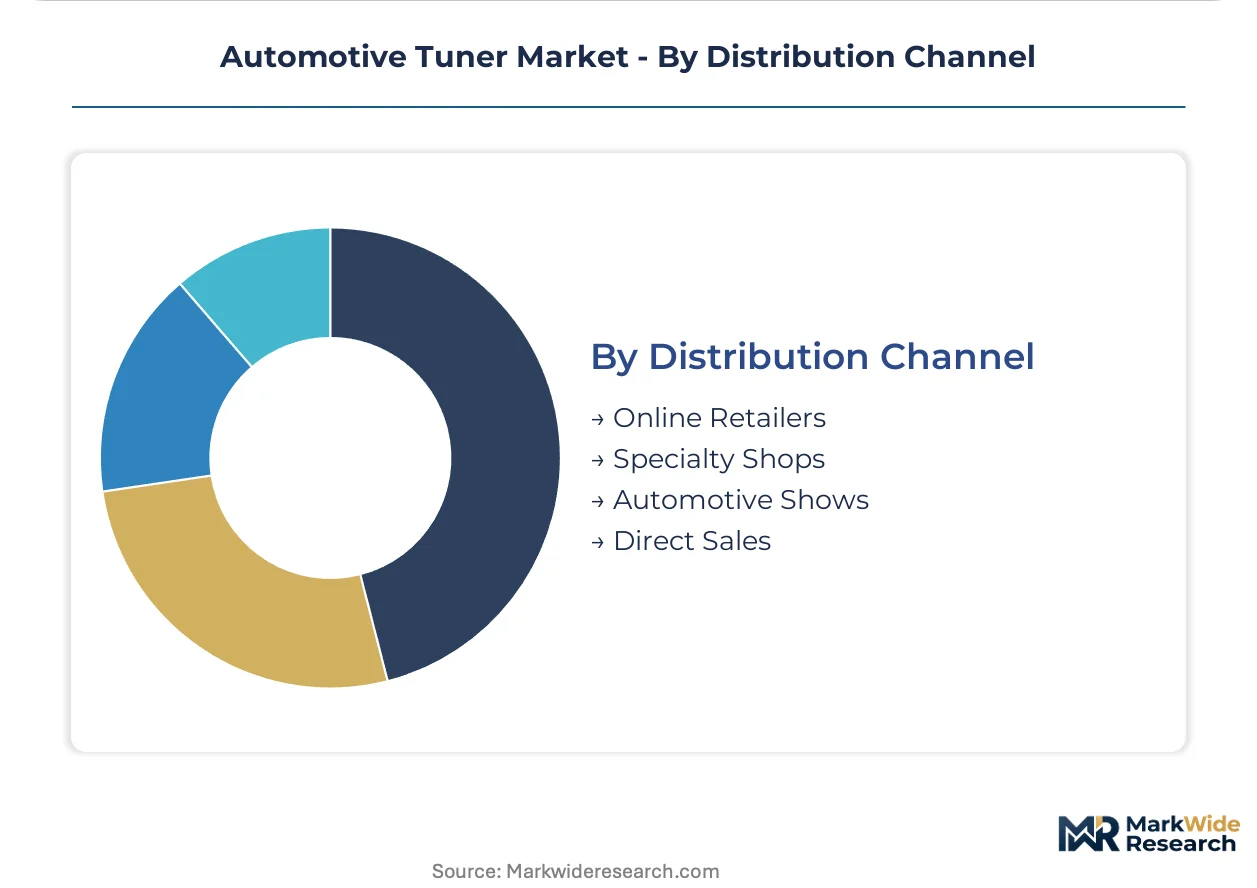
Distribution Channel:
Channel structure determines customer acquisition cost, technical support burden, and exposure to enforcement liability.
- Specialty Shops:Physical service centers provide installation, dyno verification, and warranty support for complex tuning packages. United States metropolitan consolidation is displacing independent single-location operators with national franchise networks that negotiate direct manufacturer relationships.
- Online Retailers:E-commerce platforms serve enthusiast self-installers with handheld tuners and pre-loaded performance modules. SCT Performance anchors market position through channel control across these outlets serving diesel truck segments.
- Automotive Shows:SEMA and regional exhibition events generate concentrated demand spikes for performance upgrades. Seasonal revenue concentration requires inventory pre-positioning.
- Direct Sales:Manufacturer-owned channels bypass distributor margins for proprietary tuning solutions. EcuTek leverages this structure for Japanese sport compact reflashing dominance.
Specialty Shops handle the majority of throughput; Online Retailers are climbing the fastest on share as wireless flash protocols reduce installation complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement frameworks in the United States anchor regulatory intensity for aftermarket calibration products, while KBA type-approval requirements in Germany and METI standards in Japan shape compliance architectures across three distinct demand centers.
United States
SEMA-member specialty shops and national franchise chains drive volume for ECU tuning and performance chip upgrades. CARB-compliant map development enables street-legal sales beyond track-only applications, expanding addressable market scope. California's emission enforcement intensity exceeds federal baselines, pushing manufacturers toward dual-certification strategies for nationwide distribution.
Germany
Professional racing teams are expanding procurement of engine management systems as KBA oversight tightens type-approval requirements for competition use. Stuttgart and Munich industrial clusters concentrate precision engineering capabilities for compliant calibration architectures. The country's automotive supplier density supports rapid prototyping of catalytic-preserving performance maps.
Japan
Japanese sport compact vehicles represent underpenetrated demand relative to United States and European volume for reflashing solutions. METI framework equivalence shapes product standards for Asian market access. Osaka and Nagoya metropolitan areas host specialist calibration workshops serving domestic enthusiast communities and export-oriented tuning houses.
United Kingdom
Aftermarket installers in Greater London and Birmingham metropolitan regions specialize in European performance platform calibration. The country's departure from EU regulatory alignment creates parallel certification requirements for cross-channel product distribution. British racing series procurement sustains niche demand for track-optimized engine management systems.
Australia
Enthusiast self-installation dominates volume through online retail channels serving domestic and Southeast Asian export demand. Melbourne and Sydney tuning communities drive adoption of wireless flash protocols for reduced service turnaround. The country's right-hand-drive vehicle fleet creates specialized calibration requirements distinct from North American and European specifications.
Automotive Tuner Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with dyno facility ownership and proprietary map libraries separating premium positioning from commodity hardware competition. The structure rewards recurring software revenue models over one-time device sales. Strategic archetypes include vertically integrated calibration houses, channel-controlling platform specialists, and regional reflashing experts. Competitive moves concentrate on wireless protocol development and direct-to-consumer platform construction.
Within the integrated calibration tier, Cobb Tuning and SCT Performance exemplify divergent geographic and segment anchoring strategies. Cobb Tuning represents the dyno-intensive technology leadership archetype, while SCT Performance occupies a position defined by channel control across specialty shops and online retailers. EcuTek sits within the regional specialization vector, with its structure indicating Japanese market focus.
| Leading Market Players |
|---|
| Superchips |
| SCT Performance |
| Cobb Tuning |
| EFI Live |
| EcuTek |
| DiabloSport |
| Hypertech |
| Bully Dog |
| Edge Products |
| Others |
Supply Flow & Price Mechanics
Foundry-scale economies in Taiwan concentrate semiconductor supply for engine control modules, compressing hardware margins while elevating software subscription pricing power among calibration houses with proprietary map libraries. Capacity utilization at TSMC and UMC directly determines input cost floors for standalone control modules, forcing tiered pricing stratification across premium CARB-compliant systems, standard OBD-II flash tools, and economy-grade performance chips.
Pricing Analysis
Geographic price spreads between United States and German markets exceed thirty percent for equivalent engine management systems due to KBA type-approval certification costs. Three-tier pricing structure across premium, standard, and economy levels separates CARB-compliant street-legal systems from track-only calibrations and unlicensed gray-market alternatives. Cost compression in economy-grade performance chips is intensifying because Chinese manufacturing has commoditized baseline offerings. DIY automotive enthusiasts exhibit highest price sensitivity, while professional racing teams demonstrate lowest sensitivity due to compliance-driven procurement requirements.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes create working capital intensity for United States-based specialty shop distributors awaiting Taiwanese-sourced control modules. Semiconductor supply concentrates in Taiwan, South Korea, and Japan for ECU processors, flash memory, and power management integrated circuits. Raw material dependencies span silicon wafers, rare-earth magnets for sensor assemblies, and copper for wiring harnesses. Single-source vulnerability from limited foundry capacity in Taiwan presents structural supply chain risk. Distribution runs through SEMA-member specialty shop networks and direct-to-consumer online platforms serving enthusiast self-installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless flash protocol penetration remains below forty percent of installed base, positioning the automotive tuner market for early-cycle expansion as over-the-air calibration displaces bench programming. Japanese sport compact vehicle aftermarket represents the most significant untapped penetration opportunity relative to United States and European volume saturation.
For Market Incumbents: Consolidate procurement authority through exclusive distribution agreements with national franchise chains displacing independent single-location operators. Acquire in-house dyno testing facilities to sustain technology leadership against emerging cloud-based calibration competitors. Channel compression from SEMA-member consolidation presents existential threat to legacy installer relationships; vertical integration into proprietary map library development preserves recurring revenue streams against hardware commoditization. For New Entrants and Emerging Players: Differentiate on Japanese sport compact platform specialization where EcuTek's dominance leaves white-space for Subaru, Mitsubishi, and Mazda calibration solutions. Target diesel truck enthusiast segments through direct-to-consumer platforms bypassing traditional specialty shop networks. Underpenetrated reflashing demand in Osaka and Nagoya metropolitan areas offers geographic white-space with METI-compliant product standards enabling Asian market access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among engine management system providers with proprietary map library subscriptions and cloud-based distribution portals. Long-term viability over the coming decade favors calibration houses with OBD-III readiness investments positioning for factory-authorized partnership opportunities. Acquisition target archetype: vertically integrated specialists combining in-house dyno facilities with wireless flash protocol development capabilities. Signal to watch: EPA enforcement intensity against defeat devices as inflection indicator for compliant product line premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Protocol Development | Over-the-air reflashing eliminates physical ECU removal, compressing service turnaround from days to hours. |
| Proprietary Map Library Expansion | Cloud-based subscription portals extend customer lifetime value beyond one-time hardware sales. |
| CARB-Compliant Certification Investment | Street-legal map development expands addressable market beyond track-only applications under EPA oversight. |
| Direct-to-Consumer Platform Launch | Bypassing specialty shop networks captures diesel truck enthusiast volume through online retail channels. |
| OBD-III Readiness Partnership | Factory-authorized calibration agreements position tuners for connected-vehicle protocol integration. |
Methodological Framework
A spread of perspectives from ECU calibration engineers, SEMA-member specialty shop operators, OEM platform engineers, and aftermarket distributor procurement heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement action databases, KBA type-approval registries, SEMA market research publications, and vehicle registration data from IHS Markit. Bottom-up triangulation across product category shipment estimates and top-down cross-checks against automotive aftermarket expenditure aggregates anchored volume and value outputs.
Segmentation dimensions modeled span product type, end-user archetype, calibration technology, and distribution channel across the projection horizon. Engine management systems, performance chips, exhaust systems, and air intake kits formed product-level splits; aftermarket installers, racing teams, automotive enthusiasts, and vehicle manufacturers defined demand-side segmentation. CAGRs derived from historical shipment trajectories, adoption curve analysis for wireless protocols, and regulatory compliance investment cycles. Forecast inputs incorporated KBA oversight intensity trajectories and semiconductor foundry capacity utilization assumptions.
Material uncertainties — EPA defeat device enforcement escalation, Taiwan foundry supply disruption, and OBD-III protocol standardization timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding wireless flash adoption rates and CARB compliance pathway maturation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Transmission Sales Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Turbocharger Actuators Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Global Automotive Tappet Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Fuel Pumps Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Automotive Driveline Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive Carburetor Market