
 South Africa Data Center Networking Market | 2026-2036
South Africa Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Networking Market Insights
Multi-source procurement of networking hardware is consolidating as South African enterprises reduce vendor fragmentation in their data center refresh cycles. Cisco Systems Inc. dominates the router and switch installed base through its channel partner ecosystem across Johannesburg, Cape Town, and Durban. Huawei Technologies Co. Ltd. competes aggressively on price-performance for hyperscale and government tenders, though supply constraints from US trade restrictions complicate its local positioning. Arista Networks Inc. specializes in high-density Ethernet fabrics for financial services clients requiring low-latency trading infrastructure.
South Africa data center networking encompasses the switching, routing, security, and interconnect hardware that enables traffic flow between servers, storage arrays, and external networks within a contained facility, typically operating at speeds from 1 Gbps edge ports to 400 Gbps spine-layer interfaces with sub-microsecond latency requirements. Its primary commercial purpose is to guarantee application availability, data throughput, and security segmentation for enterprise and cloud workloads. Ethernet technology leads the technology dimension due to its interoperability and declining cost per port, while InfiniBand captures niche demand from research institutions and AI training clusters requiring remote direct memory access capabilities. The hybrid deployment model is expanding fastest as enterprises maintain sensitive workloads on-premise while bursting compute to cloud, whereas colocation providers like Teraco are upgrading their cross-connect fabrics to capture interconnection revenue between tenants.
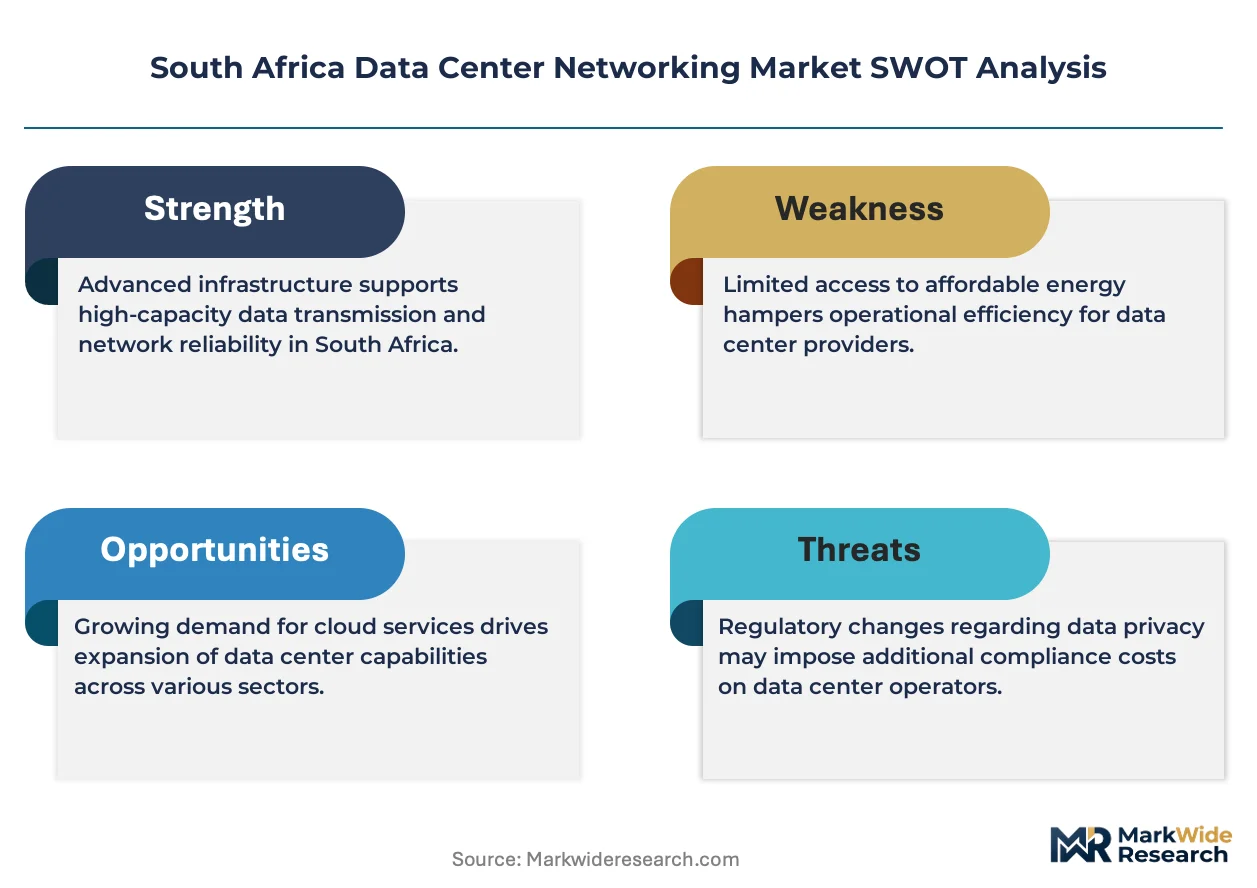
The Independent Communications Authority of South Africa regulates spectrum and telecommunications infrastructure licensing, while the Protection of Personal Information Act mandates data localization controls that drive on-premise and certified colocation networking investment. BIS standards alignment for equipment safety and electromagnetic compatibility shapes import certification timelines for non-SADC networking hardware. The National Treasury's preferential procurement framework for state information technology influences vendor selection in public sector data center projects. Stakeholders must monitor whether ICASA's upcoming spectrum auctions and data center energy efficiency rules reshape facility location decisions and corresponding networking architecture requirements.
Market Dynamics
Teraco's cross-connect fabric expansion at Isando and Bredell campuses is compressing interconnection latency between financial services tenants, forcing rival colocation operators to accelerate spine-layer upgrades or surrender premium tenancy to NAPAfrica's peering exchange.
Growth Catalysts
- Protection of Personal Information Act:Data localization mandates under POPIA compel enterprises to maintain certified on-premise or colocated infrastructure, directly stimulating investment in sovereign-compliant switching and routing hardware.
- Hyperscale cloud bursting:Financial services firms in Johannesburg are deploying hybrid Ethernet fabrics that burst compute workloads to Microsoft Azure and AWS South Africa regions, requiring 100 Gbps+ spine capacity at enterprise edge.
- AI training clusters:Research institutions at Stellenbosch and University of Cape Town are procuring InfiniBand interconnects for GPU-based workloads, creating niche demand for remote direct memory access capabilities.
Market Restraints
- Import certification friction:BIS electromagnetic compatibility testing extends lead times for non-SADC networking equipment by eight to fourteen weeks, constraining refresh cycle velocity for enterprises.
- US trade restriction spillover:Supply constraints on advanced semiconductors complicate procurement of 400 Gbps switch silicon for hyperscale tenders, advantaging vendors with established inventory positions.
- Power infrastructure bottlenecks:Eskom grid instability elevates total cost of ownership for high-density spine switches, as facilities must oversubscribe UPS and generator capacity to maintain sub-microsecond latency guarantees.
Strategic Opportunities
- Western Cape expansion:Cape Town's Atlantic Seaboard subsea cable landings create interconnection arbitrage opportunities for colocation operators building cross-connect fabrics between Equiano and 2Africa cable systems.
- Smart city networking:Tshwane and eThekwini municipal data center consolidation programs mandate IPv6-capable segmentation hardware, opening procurement channels for security-integrated switching platforms.
- Green finance taxonomy alignment:National Treasury's sustainable finance framework creates preferential lending conditions for data center operators deploying energy-efficient spine-layer optics, subsidizing 400G-ZR coherent transceiver adoption.
Industry Challenges
- Certified network engineering scarcity:CCNP- and JNCIE-level talent concentrates in Gauteng, forcing Durban and Port Elizabeth facility operators to pay 35-50% salary premiums or accept longer deployment timelines.
- Multi-vendor orchestration complexity:Enterprises consolidating from three-switch vendor environments to single-stack architectures face six-to-nine month migration windows, delaying ROI realization on 400 Gbps investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Networking Market |
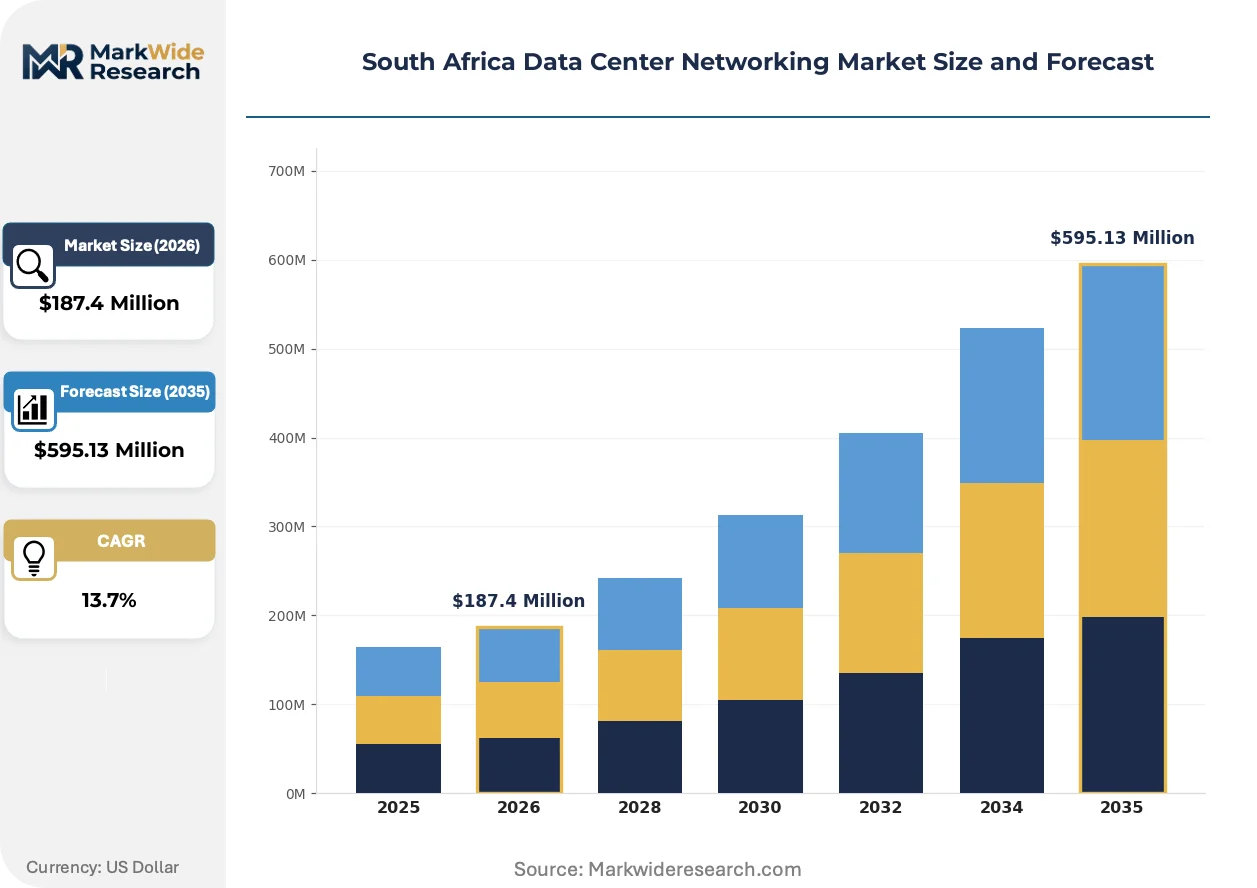
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Access Points Technology: Ethernet, MPLS, Fiber Channel, InfiniBand End User: Telecommunications, BFSI, Retail, Healthcare Deployment Model: On-Premise, Cloud, Hybrid, Colocation |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Huawei Technologies Co. Ltd., H3C Holding Limited, VMware Inc., Arista Networks Inc., Dell Technologies Inc., Hewlett Packard Enterprise, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Networking Market Trends and Innovations
Software-defined networking controllers are displacing manual CLI configuration in South African enterprise data centers, compressing provisioning timelines from weeks to hours while introducing new vendor lock-in risks around API compatibility.
White-box switching hardware is modularizing procurement patterns for Johannesburg-based financial services firms. These organizations now separate bare-metal switch purchases from independent network operating system licensing, compressing capital expenditure by 20-30% versus traditional bundled solutions. The structural consequence is fragmenting Cisco's historical dominance as Arista, Cumulus, and SONiC-based alternatives capture evaluation cycles.
ICASA's pending spectrum auction framework for 6 GHz Wi-Fi and private 5G networks is reshaping edge connectivity architecture. Enterprises must now evaluate whether to extend Ethernet fabrics to remote branch locations or bypass cabling entirely through licensed wireless backhaul. Mining houses in Mpumalanga and Limpopo are most affected, as these operators pilot private 5G for autonomous vehicle telemetry rather than trenching fiber across vast leaseholdings.
Consumption-based networking procurement is displacing traditional capital purchase models among mid-market enterprises. Teraco and Africa Data Centres now offer switch-and-port subscriptions bundled with colocation tenancy, transferring obsolescence risk from tenant to operator. This shift concentrates most visibly in Gauteng province, where CFOs facing Eskom-driven opex volatility prefer predictable monthly networking charges over lumpy refresh capex.
South Africa Data Center Networking Market Segmentation
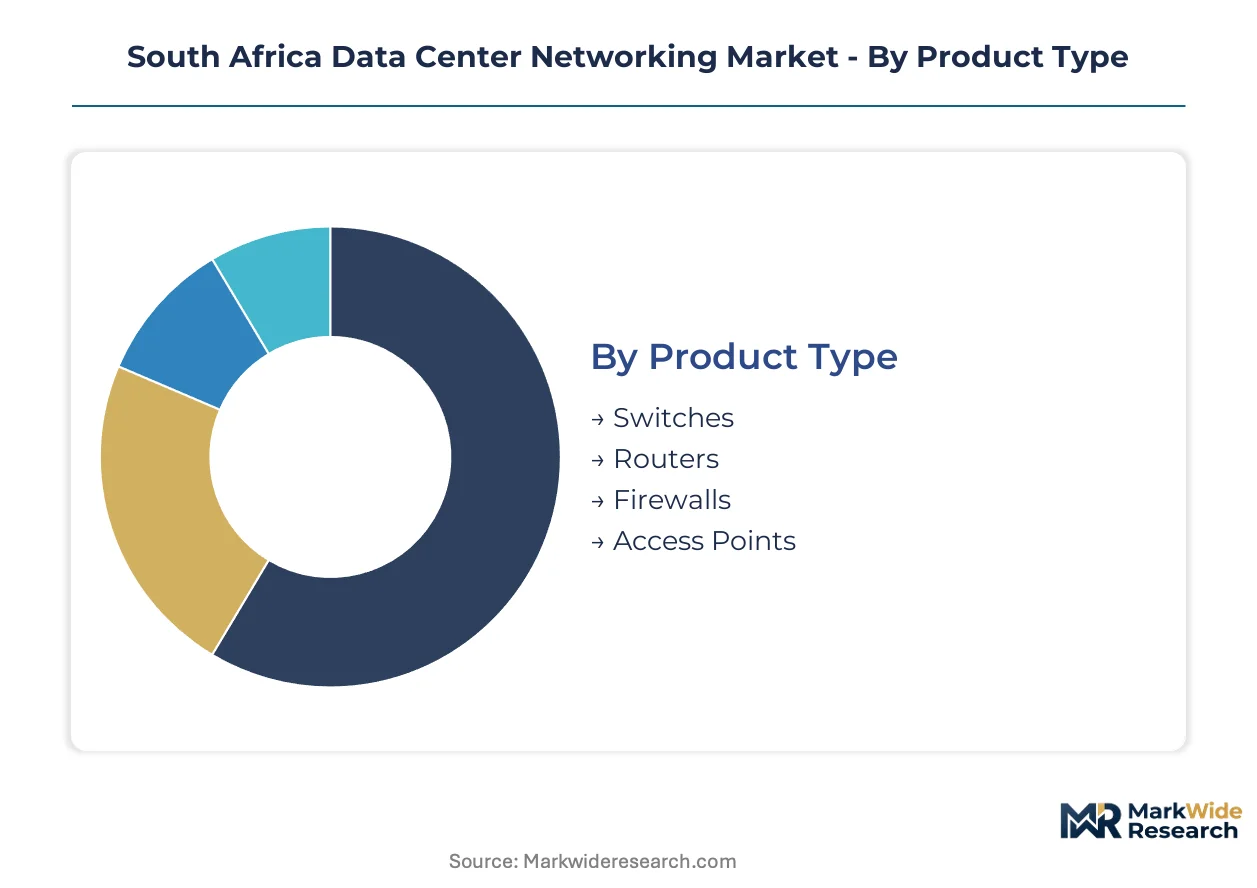
Segmentation in South Africa's data center networking market reveals how POPIA compliance, Eskom-driven opex volatility, and hyperscale cloud adoption reshape procurement priorities across hardware categories and deployment architectures.
Product Type:
Buyers differentiate primarily by port density requirements and refresh cycle urgency, with financial services prioritizing low-latency spine switches while mid-market enterprises favor modular edge hardware.
- Switches:Spine-layer Ethernet switches at 100-400 Gbps dominate Cape Town and Johannesburg financial exchanges where sub-microsecond latency is mandatory. Teraco and NAPAfrica facilities anchor demand for high-density leaf-spine fabrics as colocation tenancy expands.
- Routers:Border gateway routers with BGP-4 capability handle traffic between enterprise edge and subsea cable landings at Melkbosstrand and Mtunzini. BFSI firms in Gauteng prioritize redundant routing hardware to maintain POPIA-mandated data sovereignty.
- Firewalls:Next-generation firewalls with application-layer inspection protect hybrid cloud boundaries.
- Access Points:Wi-Fi 6E and private 5G access points extend fabric connectivity to remote mining operations in Limpopo.
Switches lead volumes today; firewalls are gaining share fastest as POPIA compliance tightens perimeter security requirements.
Technology:
Technology selection tracks workload type, with general-purpose compute favoring interoperability while AI training and high-frequency trading demand specialized interconnect protocols.
- Ethernet:IEEE 802.3 standards-based switching at 25/100/400 Gbps serves as the default for enterprise data centers from Durban to Port Elizabeth. Cisco and Arista channel partners push this technology through certified installation networks concentrated in Gauteng.
- InfiniBand:Remote direct memory access fabrics at 200-400 Gbps connect GPU clusters at Stellenbosch University and UCT for machine learning workloads. Research tenders specify InfiniBand despite limited local engineering expertise.
- MPLS:Multi-protocol label switching remains entrenched in legacy financial WANs.
- Fiber Channel:Storage area networking persists in healthcare and retail mainframe environments.
Ethernet leads volumes today; InfiniBand is climbing the fastest on AI cluster procurement.
End User:
End-user segmentation reflects regulatory exposure and cloud maturity, with POPIA-bound sectors investing in sovereign infrastructure while cloud-native industries favor consumption models.
- BFSI:Banks and insurers in Johannesburg's Sandton district deploy redundant 400 Gbps spine fabrics to support real-time payment clearing and POPIA-compliant data localization. Absa, Standard Bank, and FirstRand drive refresh cycles every 36-48 months.
- Telecommunications:MTN, Vodacom, and Telkom operate carrier-neutral facilities requiring massive scale-out switching for mobile backhaul aggregation.
- Retail:Grocery and fashion chains prioritize cost-optimized edge switching for distribution center automation.
- Healthcare:Hospital groups in Western Cape and KwaZulu-Natal invest in HIPAA-aligned segmentation for electronic health records.
BFSI leads volumes today; healthcare is expanding most quickly on provincial data center consolidation programs.
Deployment Model:
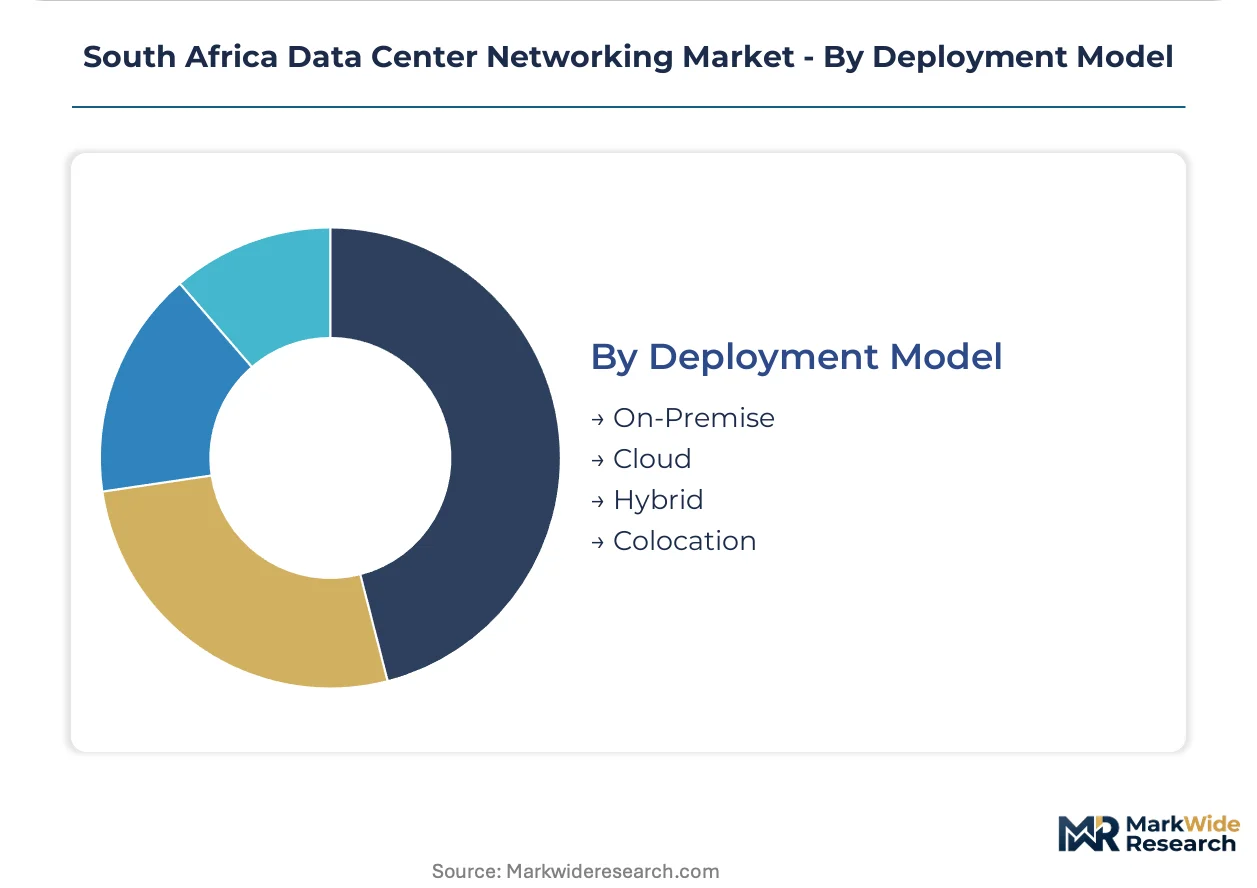
Deployment choice hinges on capital availability and workload sensitivity, with CFOs facing Eskom volatility increasingly preferring opex-heavy colocation over owned infrastructure.
- Colocation:Teraco, Africa Data Centres, and Vantage offer cross-connect fabrics and switch-port subscriptions that transfer obsolescence risk from tenant to operator. This model concentrates in Isando, Bredell, and Century City where submarine cable diversity is highest.
- Hybrid:Financial services firms maintain sensitive transaction processing on-premise while bursting analytics workloads to Microsoft Azure South Africa North and AWS Cape Town regions.
- On-Premise:Government and defense facilities retain fully owned switching infrastructure for classified workloads.
- Cloud:Pure cloud networking abstracts physical hardware entirely through hyperscale virtualized fabrics.
Colocation leads volumes today; hybrid is gaining share fastest as cloud repatriation and sovereignty requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg's Teraco and NAPAfrica facilities anchor interconnection capacity across sub-Saharan Africa, with Gauteng province commanding the dominant share of data center networking investment. Financial services firms in Sandton and Cape Town's Atlantic Seaboard drive demand for low-latency spine fabrics. The government's data sovereignty requirements under POPIA compel local infrastructure deployment.
Gauteng Province
Johannesburg's financial district generates concentrated demand for 400 Gbps spine-layer switches supporting real-time payment clearing. ICASA regulates spectrum licensing for private 5G backhaul extensions to remote mining operations. Teraco's Isando and Bredell campuses anchor cross-connect fabric expansion between banking tenants.
Western Cape
Cape Town's subsea cable landings at Melkbosstrand create interconnection arbitrage opportunities for colocation operators. The Protection of Personal Information Act mandates certified data localization for healthcare and financial records. Stellenbosch University and UCT procure InfiniBand interconnects for GPU-based AI training clusters.
KwaZulu-Natal
Durban's port logistics and manufacturing base drives edge switching demand for distribution center automation. BIS electromagnetic compatibility testing extends lead times for networking hardware imports. eThekwini's municipal data center consolidation mandates IPv6-capable segmentation hardware procurement.
Eastern Cape
Port Elizabeth automotive suppliers invest in modular edge hardware for connected factory deployments. Eskom grid instability elevates total cost of ownership for high-density spine switches. Gqeberha's emerging tech corridor attracts secondary colocation investment from enterprises seeking geographic redundancy.
South Africa Data Center Networking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue white-box and software-defined alternatives. The vendor ecosystem consolidates around three strategic archetypes: bundled hardware-software incumbents, disaggregated white-box specialists, and cloud-native networking vendors. Capacity expansion at Teraco and Africa Data Centres concentrates procurement leverage among hyperscale-tuned suppliers. Strategic partnerships between colocation operators and switch vendors are displacing direct enterprise sales channels.
Among US-based networking vendors, Cisco Systems Inc., Arista Networks Inc., and Juniper Networks Inc. occupy positions across the premium and standard tiers. Cisco exemplifies the bundled hardware-software archetype through its channel partner ecosystem concentrated in Gauteng. Arista represents the high-density Ethernet specialization vector for financial services latency requirements. Juniper sits within the routing-centric tier serving border gateway deployments at subsea cable landing stations.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Huawei Technologies Co. Ltd. |
| H3C Holding Limited |
| VMware Inc. |
| Arista Networks Inc. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
National Treasury's sustainable finance framework gates both qualified supply and premium-tier pricing access for energy-efficient spine-layer optics, as data center operators must demonstrate green certification to unlock subsidized lending for 400G-ZR coherent transceiver procurement. This environmental mandate stratifies vendor participation, separating established suppliers with verified carbon footprints from entrants facing higher capital costs to meet eligibility thresholds.
Pricing Analysis
Input-cost pass-through from advanced semiconductor supply constraints directly compresses margins on 400 Gbps switch silicon, with US trade restriction spillover effects amplifying price volatility for hyperscale tenders. Three-tier pricing structure across premium, standard, and economy levels separates Arista and Cisco's certified low-latency fabrics from white-box alternatives and refurbished legacy hardware. Price differentiation hinges on BIS electromagnetic compatibility certification tier and after-sales engineering support bundled with installation. Cost compression in the standard tier is intensifying because mid-market enterprises facing Eskom-driven opex volatility prioritize predictable subscription models over lumpy capital expenditure. Mining houses in Limpopo and Mpumalanga exhibit highest price sensitivity due to remote logistics costs, while Johannesburg BFSI firms show lowest sensitivity where sub-microsecond latency guarantees justify premium positioning.
Supply Chain Analysis
Workforce-availability constraints in Taiwan, China, and Malaysia semiconductor fabrication facilities limit output of merchant switch silicon and coherent optical components destined for South African hyperscale deployments. Raw material dependencies center on gallium arsenide substrates, advanced packaging substrates, and rare-earth elements for magnetics in power supplies. Single-source vulnerability concentrates in 400 Gbps switch ASIC supply where US export controls restrict foundry access for certain vendors. Distribution runs through Johannesburg-based channel partners with certified CCNP engineering capabilities, extending last-mile configuration and support to Cape Town and Durban facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's data center networking market functions as a geographic-arbitrage play where Cape Town's Atlantic Seaboard subsea cable landings offer interconnection cost advantages 15-20% below Johannesburg's landlocked infrastructure, amplified by Western Cape's more stable municipal power grid reducing UPS oversubscription requirements.
For Market Incumbents: To counter white-box switching displacement from Johannesburg financial services firms, Cisco and Arista must deepen captive supply of merchant silicon through backward integration into ASIC design partnerships, while simultaneously expanding certified channel engineering capacity in Durban and Port Elizabeth to defend against 35-50% salary premiums eroding deployment timelines.
For New Entrants and Emerging Players: Begin with eThekwini and Tshwane municipal data center consolidation programs as the most penetrable public-sector entry point, where IPv6-capable security-integrated switching platforms face limited incumbent certification and procurement cycles favor specialized vendors over bundled hardware-software stacks.
For Investors and Strategic Acquirers: Roll-up economics work for regional colocation operators with cross-connect fabric assets because Teraco's Isando and Bredell campus expansions have validated tenant willingness to pay premium interconnection fees, creating scalable revenue pools for consolidation. Acquisition targets should demonstrate existing NAPAfrica peering exchange adjacency or private 5G spectrum licenses for mining vertical extension. The signal to watch is ICASA's 6 GHz Wi-Fi and private 5G auction timing, which would accelerate edge connectivity architecture shifts and revalue licensed versus unlicensed backhaul assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Spectrum Acquisition | ICASA licensing enables mining house telemetry deployments across Mpumalanga and Limpopo leaseholdings. |
| Cross-Connect Fabric Expansion | Teraco's Bredell campus upgrades capture interconnection arbitrage between Equiano and 2Africa cable systems. |
| White-Box Switching Migration | SONiC-based alternatives fragment Cisco's historical dominance in Johannesburg financial services refresh cycles. |
| Green Finance Certification | National Treasury taxonomy alignment unlocks preferential lending for 400G-ZR coherent transceiver deployment. |
| InfiniBand Cluster Deployment | Stellenbosch and UCT research tenders create niche demand for GPU-based AI training interconnects. |
Research Methodology
Multiple input streams — primary interviews with data center facility managers, network engineering directors at BFSI firms, and procurement leads at colocation operators, combined with secondary validation against ICASA regulatory filings, BIS electromagnetic compatibility certification databases, and National Treasury preferential procurement frameworks — were reconciled through bottom-up and top-down triangulation. Field perspectives from Teraco, Africa Data Centres, and Vantage operations teams anchored volume assumptions, while hyperscaler capex disclosures and subsea cable landing data provided external benchmarks.
Data-stream reconciliation across product type, technology protocol, end-user vertical, and deployment model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by current revenue contribution, with POPIA compliance timelines and Eskom grid stability indices serving as industry-specific forecast inputs to model infrastructure investment pacing.
Several conditions sit outside the modeled scope, including potential ICASA spectrum auction delays, unforeseen BIS certification timeline extensions, and acute Eskom load-shedding escalation beyond historical volatility bands. Forecasts reflect assumptions around continued US trade restriction enforcement and stable SADC preferential tariff treatment. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Network Connectivity Tester Market