
 Japan Data Center Market | 2026-2036
Japan Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Market Outlook
Project finance partnerships with institutional investors is reconfiguring competitive entry barriers for new facility developments. NTT Global Data Centers leverages its domestic fiber backbone to anchor hyperscale connectivity in Tokyo and Osaka. Equinix competes through interconnection density at its carrier-neutral campuses. KDDI Corporation differentiates via integrated telecommunications-to-data-center service bundles.
A data center comprises purpose-built facilities housing servers, storage systems, and networking equipment within controlled environments maintaining temperatures between 18°C and 27°C and humidity at 40-60% relative humidity, designed to deliver continuous compute, storage, and connectivity services for enterprise and consumer digital workloads. Colocation services dominate current revenue as enterprises shed owned assets, while edge computing deployments represent the fastest-expanding technology segment driven by latency-sensitive applications in manufacturing and autonomous systems. Cloud services within hybrid deployment models concentrate margin pools where vendors orchestrate workloads across on-premise and multi-cloud environments.
METI enforces energy efficiency standards under the Act on Rationalizing Energy Use, while the Ministry of the Environment implements carbon reporting rules that shape facility design and cooling technology selection. JIS standards govern electrical and fire safety compliance for mission-critical infrastructure. Facility operators must monitor evolving grid interconnection rules and renewable energy procurement frameworks as stakeholder decisions on power sourcing increasingly determine site viability and long-term operating economics.
Market Dynamics
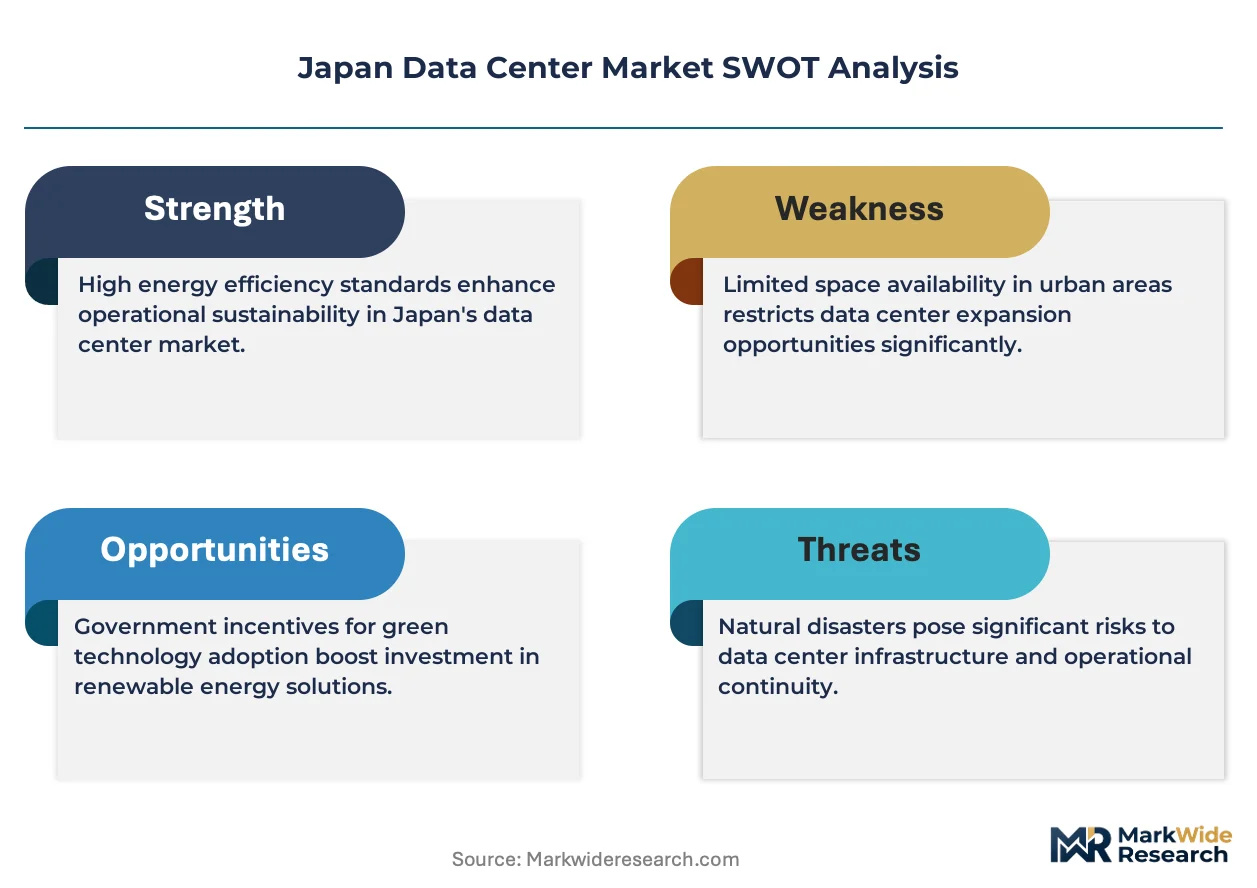
Hyperscale cloud operators are compressing deployment timelines across Greater Tokyo and Osaka, forcing facility developers to secure power interconnection agreements before land acquisition closes. METI's tightening carbon intensity standards under the Green Transformation initiative now determine site viability ahead of construction financing.
Growth Catalysts
- Green Transformation mandates:METI's carbon reporting rules compel facility operators to source renewable energy, accelerating procurement of grid-scale solar and offshore wind contracts.
- Edge computing for manufacturing:Latency-sensitive autonomous systems in automotive and precision electronics plants are pulling distributed compute capacity into Osaka's industrial corridor.
- Osaka secondary market expansion:Land scarcity and power constraints in Tokyo are redirecting hyperscale investment toward western Japan's emerging data center cluster.
Market Restraints
- Grid interconnection queues:Tokyo Electric Power's application backlog stretches 18-24 months for facilities above 50MW, freezing development pipelines.
- Liquid cooling infrastructure:Domestic supply chains for immersion cooling fluids and precision delivery systems remain concentrated among three specialized vendors.
- Seismic construction codes:JIS-compliant base isolation systems add 15-20% to structural capex versus conventional designs.
Strategic Opportunities
- Fukuoka-Kyushu corridor:Submarine cable landings and geothermal power access position the island for low-carbon hyperscale campuses serving Asian markets.
- AI training workloads:Dense GPU clusters for generative model development favor facilities with direct liquid cooling and high-voltage substations.
- Corporate renewable energy procurement:METI's non-fossil certificate trading scheme enables data center operators to monetize clean power attributes.
Industry Challenges
- Critical facilities engineering talent:Japan produces fewer than 200 certified data center design engineers annually, constraining project execution capacity.
- Legacy building retrofit integration:Converting 1980s industrial warehouses to tier-III facilities requires complete electrical and mechanical replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Market |
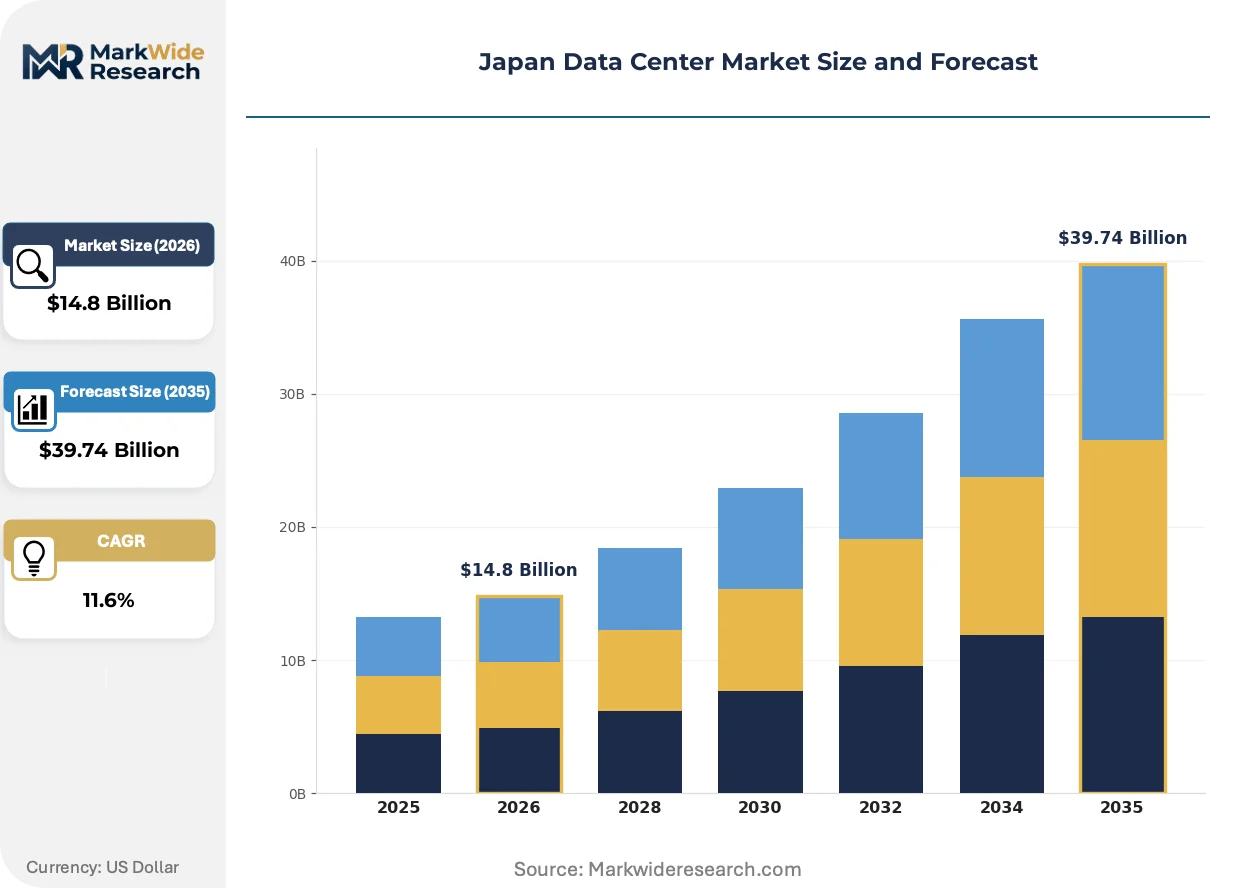
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Services, Cloud Services, Dedicated Hosting End User: IT Services, BFSI, Telecommunications, Retail Technology: Hyperconverged Infrastructure, Open Compute, Virtualization, Edge Computing Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud |
| Companies Covered | NTT Global Data Centers, Equinix, Digital Realty, KDDI Corporation, Fujitsu, IDC Frontier, SoftBank Corp., AT TOKYO, AirTrunk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Market Strategic Shifts
Cooling architecture and power delivery systems are converging around sustainability metrics that now dominate site selection decisions ahead of traditional latency or connectivity criteria. Facility operators are engineering for thermal efficiency and grid flexibility as primary design inputs.
Liquid cooling technology is hybridizing air-cooled and direct-to-chip architectures into unified thermal management platforms. Semiconductor foundries and AI research laboratories are adopting two-phase immersion systems at pilot scale. This convergence is compressing the performance gap between traditional hyperscale designs and high-density GPU clusters.
METI's Act on Rationalizing Energy Use now mandates annual energy efficiency reporting for facilities exceeding 1,500 kilowatts of IT load. Operators must document power usage effectiveness ratios and implement continuous monitoring systems. Western Japan's emerging developments are responding with geothermal heat rejection and waste heat district heating partnerships.
Enterprise buyers are consolidating vendor relationships around integrated telecommunications-to-data-center service bundles. Manufacturing and financial services verticals favor single-contract accountability for network connectivity, security, and compute capacity. Kansai region procurement teams are accelerating this consolidation to simplify vendor management overhead.
Japan Data Center Market Segmentation
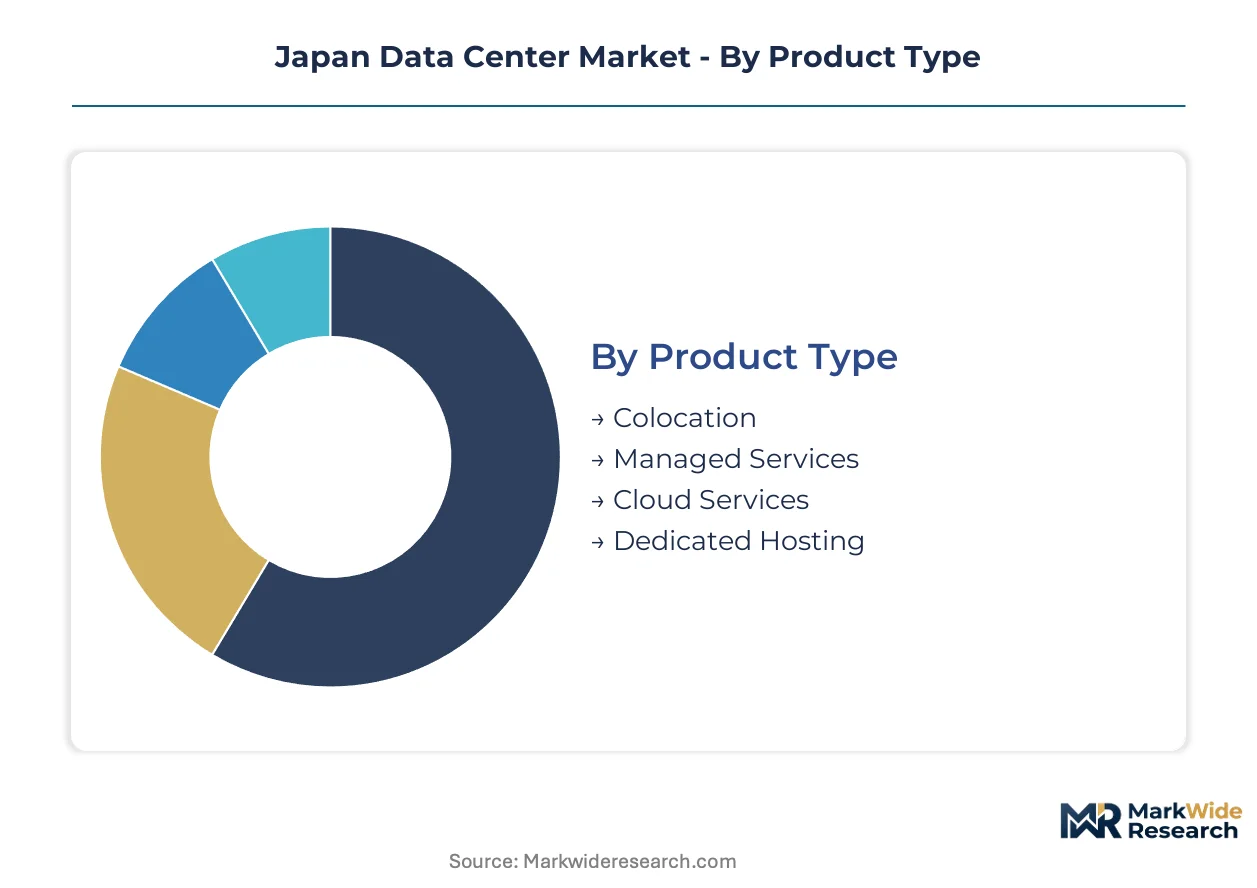
Segmentation in Japan's data center market reveals how regulatory pressure and workload density are splitting procurement patterns. METI's carbon reporting rules and hyperscale expansion timelines are forcing buyers into distinct technology and deployment configurations that reshape vendor positioning.
Product Type:
Mature revenue streams anchor the base while emerging service layers capture margin expansion from AI and edge workloads.
- Colocation:Wholesale and retail rack space leasing within third-party facilities with redundant power and cooling infrastructure. Enterprises in Tokyo and Osaka are shedding owned assets under METI efficiency mandates, concentrating demand in carrier-neutral campuses with direct cloud on-ramps.
- Managed Services:Outsourced infrastructure operations covering server administration, backup management, and security monitoring under SLA contracts. Financial services and pharmaceutical firms in the Kansai region favor single-contract accountability for compliance-sensitive workloads.
- Cloud Services:Public and private cloud resource provisioning with consumption-based billing.
- Dedicated Hosting:Single-tenant server deployment with guaranteed resource allocation.
Colocation handles the majority of throughput; Managed Services is climbing the fastest on share as compliance complexity deepens.
End User:
Vertical specialization determines facility selection criteria across cooling density, latency tolerance, and data sovereignty requirements.
- IT Services:Software vendors and systems integrators consuming compute for development, testing, and SaaS delivery. Hyperscale cloud operators in Greater Tokyo are compressing deployment timelines, forcing developers toward hybrid architectures with local edge nodes.
- BFSI:Banks, insurers, and securities firms with stringent availability and audit requirements. The Financial Services Agency's operational resilience guidelines are mandating geographic separation of primary and disaster recovery sites across Japan's eastern and western grids.
- Telecommunications:Mobile and fixed-line carriers hosting network functions and content delivery infrastructure.
- Retail:Omnichannel merchants processing transactions and inventory analytics.
IT Services commands the largest capacity allocation; BFSI is expanding most quickly as regulatory separation rules multiply.
Technology:
Infrastructure architecture choices increasingly hinge on thermal management capabilities and GPU density requirements.
- Hyperconverged Infrastructure:Integrated compute, storage, and networking software-defined platforms. Manufacturing firms in Osaka's industrial corridor are deploying HCI for shop-floor analytics under latency constraints that disqualify centralized cloud.
- Edge Computing:Distributed micro-data centers positioned within 10 milliseconds of end devices. Autonomous systems and precision electronics plants are pulling compute capacity into secondary markets as METI's carbon rules make long-haul data transit economically punitive.
- Open Compute:Disaggregated hardware designs optimized for hyperscale efficiency.
- Virtualization:Abstracted compute resources enabling multi-tenant server utilization.
Hyperconverged Infrastructure anchors current deployment volumes; Edge Computing is gaining share fastest as manufacturing automation accelerates.
Deployment:
Workload placement strategy now balances sovereignty, latency, and carbon accounting across four distinct models.
- Hybrid:Orchestrated workloads spanning on-premise infrastructure and public cloud resources. Enterprise procurement teams in western Japan are consolidating vendor relationships around integrated telecommunications-to-data-center bundles that simplify multi-environment management.
- Multi-Cloud:Deliberate distribution across two or more hyperscale providers to mitigate concentration risk. Financial institutions facing FSA operational resilience requirements are mandating cloud-agnostic architectures with automated failover between AWS, Azure, and domestic platforms.
- On-Premise:Customer-owned facilities with captive infrastructure operations.
- Cloud-Based:Fully outsourced public cloud resource consumption.
Hybrid deployments absorb the greatest capacity investment; Multi-Cloud is expanding most quickly as regulatory risk diversification hardens into procurement policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's Green Transformation initiative is redirecting hyperscale investment across Japan's archipelago as carbon intensity standards now determine site viability ahead of construction financing. Power interconnection queues and renewable energy access are fragmenting deployment timelines between eastern and western grids.
Kanto/Tokyo
Hyperscale cloud operators are compressing deployment timelines across Greater Tokyo despite land scarcity and grid constraints. Tokyo Electric Power's 18-24 month interconnection backlog for facilities above 50MW is freezing development pipelines. NTT Global Data Centers leverages its domestic fiber backbone to anchor hyperscale connectivity in the capital region.
Kansai/Osaka
Land scarcity and power constraints in Tokyo are redirecting hyperscale investment toward western Japan's emerging data center cluster. METI's carbon reporting rules compel facility operators to source renewable energy, accelerating procurement of grid-scale solar contracts in the Kansai industrial corridor. Manufacturing firms in Osaka's industrial corridor are deploying hyperconverged infrastructure for shop-floor analytics under latency constraints.
Chubu/Nagoya
Precision electronics plants are pulling distributed compute capacity into the Chubu region as METI's carbon rules make long-haul data transit economically punitive. The Act on Rationalizing Energy Use mandates annual energy efficiency reporting for facilities exceeding 1,500 kilowatts of IT load. Automotive and precision manufacturing clusters in Aichi Prefecture are driving edge computing deployment for autonomous systems.
Kyushu
Submarine cable landings and geothermal power access position the island for low-carbon hyperscale campuses serving Asian markets. Western Japan's emerging developments are responding with geothermal heat rejection and waste heat district heating partnerships. Fukuoka's emerging corridor benefits from direct fiber connectivity to continental Asia and abundant renewable baseload.
Japan Data Center Market Competitive Environment
On the supply side, the industry is consolidating around telecommunications incumbents with captive fiber infrastructure and global colocation specialists with carrier-neutral positioning. Three strategic archetypes dominate: domestic telecom-integrated operators leveraging network assets, pure-play colocation providers emphasizing interconnection density, and hyperscale cloud builders with captive facility requirements. Capacity expansion and strategic partnerships with institutional investors constitute the dominant competitive moves as project finance reconfigures entry barriers.
Among Japan-based telecommunications operators, NTT Global Data Centers, KDDI Corporation, and SoftBank Corp. exemplify the integrated infrastructure archetype. These entities anchor hyperscale connectivity through domestic fiber backbone control and bundled telecommunications-to-data-center service offerings. Within the carrier-neutral tier, Equinix occupies a position emphasizing interconnection density at metropolitan campuses. The competitive dynamic pits fiber-rich domestic incumbents against global specialists with standardized facility designs and institutional capital partnerships.
| Leading Market Players |
|---|
| NTT Global Data Centers |
| Equinix |
| Digital Realty |
| KDDI Corporation |
| Fujitsu |
| IDC Frontier |
| SoftBank Corp. |
| AT TOKYO |
| AirTrunk |
| Others |
Value Chain & Pricing Dynamics
Domestic supply chains for immersion cooling fluids and precision delivery systems remain concentrated among three specialized vendors, anchoring margin capture in the thermal management tier and compressing pricing flexibility for facility operators scaling liquid-cooled deployments. This upstream concentration feeds downstream into how hyperscale cloud operators negotiate power interconnection agreements before land acquisition closes.
Pricing Analysis
Certification level under JIS standards creates the primary spread between mission-critical tier-III facilities and lower-grade industrial conversions. Wholesale colocation contracts dominate revenue structures, with pricing stratifying across premium carrier-neutral campuses, standard telecom-integrated bundles, and economy remote facilities. Cost compression in the economy tier is intensifying because METI's carbon reporting rules disqualify older mechanical designs from enterprise procurement shortlists. Financial services buyers demonstrate the least price sensitivity due to FSA operational resilience mandates, while retail omnichannel merchants pressure vendors on per-rack economics.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk planning for electrical switchgear and precision cooling components. Manufacturing concentration rests on Japan, China, and South Korea for critical infrastructure inputs including high-voltage transformers, immersion cooling fluids, and seismic isolation bearings. Raw material dependencies center on copper busbar, fluorinated coolants, and reinforced concrete additives. Single-source vulnerability persists for direct-to-chip cold plates. Distribution runs through domestic EPC contractors with METI certification holding inventory risk until grid interconnection closes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified data center design engineers number fewer than 200 annually from Japanese universities, creating a structural bottleneck that determines which developers can execute complex liquid-cooled hyperscale projects. This talent scarcity reconfigures competitive entry barriers around in-house engineering depth rather than capital access alone.
For Market Incumbents: Harden project execution capacity through captive training pipelines for liquid cooling specialists before grid interconnection queues lengthen further. Deepen backward integration into geothermal heat rejection partnerships to deflect METI carbon intensity penalties. Defend against emerging pure-play colocation specialists by leveraging fiber backbone control for latency-sensitive financial services workloads. For New Entrants and Emerging Players: Establish a beachhead in Fukuoka-Kyushu's submarine cable corridor where geothermal power access and Asian connectivity demand outstrip incumbent presence. Target corporate renewable energy procurement advisory as a service wedge, monetizing METI's non-fossil certificate trading scheme for data center operators. Lead with direct liquid cooling expertise to capture AI training workload migrations from air-cooled legacy facilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional developers holding pre-grid-interconnection land positions in Osaka's emerging corridor. Long-term viability hinges on renewable energy contracting discipline and JIS certification maintenance through seismic code evolution. Watch for TEPCO queue clearance announcements as the inflection signal for development pipeline reactivation.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Power Partnership | Kyushu facilities secure baseload renewable supply under METI carbon reporting rules. |
| Liquid Cooling Specialist Acquisition | Hyperscale operators capture scarce engineering talent for dense GPU cluster deployments. |
| Submarine Cable Landing Rights | Fukuoka campuses gain direct Asian connectivity bypassing Tokyo congestion. |
| Non-Fossil Certificate Trading | Operators monetize clean power attributes through METI's emerging marketplace mechanism. |
| Seismic Base Isolation Retrofit | Legacy facilities achieve JIS tier-III compliance for financial services tenancy. |
Study Parameters
A spread of perspectives from data center facility operators, TEPCO grid interconnection planners, METI energy efficiency auditors, and hyperscale cloud procurement leads converged on the working assumptions. Primary interviews with EPC contractors and cooling system vendors were cross-referenced against secondary sources including METI energy use reports, JIS standard documentation, and TEPCO interconnection queue disclosures. Bottom-up project pipeline tracking and top-down capacity absorption modeling were triangulated to validate investment flow estimates.
Demand-supply balance across the analysis window was assessed through hyperscale cloud operator facility announcements, renewable energy procurement filings, and manufacturing automation capex trends. Segmentation dimensions modeled include service type, end-user vertical, cooling technology architecture, and deployment configuration. CAGRs were derived from capacity absorption curves and power interconnection timelines rather than simple trend extrapolation. Forecast inputs incorporated METI carbon intensity trajectory assumptions and TEPCO grid expansion plans.
Stress conditions across grid interconnection delays, geothermal project completion rates, and liquid cooling supply bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and hyperscale operator entry timing. Material shifts in METI carbon reporting thresholds or TEPCO transmission expansion schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market