
 Japan Data Center Construction Market | 2026-2036
Japan Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Construction Market Insights
Multi-source contracting for mechanical and electrical systems is pivoting away from traditional single-source arrangements as operators seek resilience against supply disruptions. Shimizu Corporation leverages its integrated design-build capability to capture turnkey hyperscale contracts. Takenaka Corporation anchors its position through advanced seismic isolation engineering tailored to Japan's tectonic profile. Kajima Corporation differentiates via proprietary modular construction methods that compress deployment timelines.
Japan data center construction encompasses the planning, engineering, and physical build-out of facilities housing servers, storage, and networking equipment, typically requiring power densities exceeding 15 kW per rack and precision cooling within plus-or-minus 1 degree Celsius tolerances. These structures serve as the physical backbone for cloud computing, enterprise IT, and telecommunications infrastructure. Hyperscale facilities command the largest capital allocation as international cloud operators expand domestic presence, while edge deployments represent the fastest-expanding construction category driven by latency-sensitive applications. Colocation construction maintains stable demand from enterprises outsourcing infrastructure ownership, though margin pools increasingly favor operators offering hybrid-ready power architectures.
METI enforces stringent energy efficiency standards under the Act on Rationalizing Energy Use, compelling operators to integrate liquid cooling and waste heat recovery systems into new builds. JIS standards for seismic performance and fire resistance shape structural engineering specifications, while local prefectural ordinances on noise and land use constrain site selection in dense urban zones. Stakeholders must monitor evolving grid interconnection rules and carbon accounting requirements as these will determine which projects secure development permits and long-term power purchase agreements.
Market Dynamics
METI's energy efficiency mandates under the Act on Rationalizing Energy Use are forcing wholesale redesigns of cooling architectures and power distribution systems across new facility builds.
Growth Catalysts
- Cloud Provider Expansion:International hyperscale operators are committing capital to domestic facilities to serve latency-sensitive AI inference workloads and enterprise cloud migration.
- Edge Computing Demand:5G network densification and autonomous vehicle testing corridors are pulling distributed compute infrastructure into secondary metropolitan zones.
- Liquid Cooling Mandates:METI's thermal efficiency thresholds are compelling adoption of direct-to-chip and immersion cooling technologies that reduce PUE ratios below 1.2.
Market Restraints
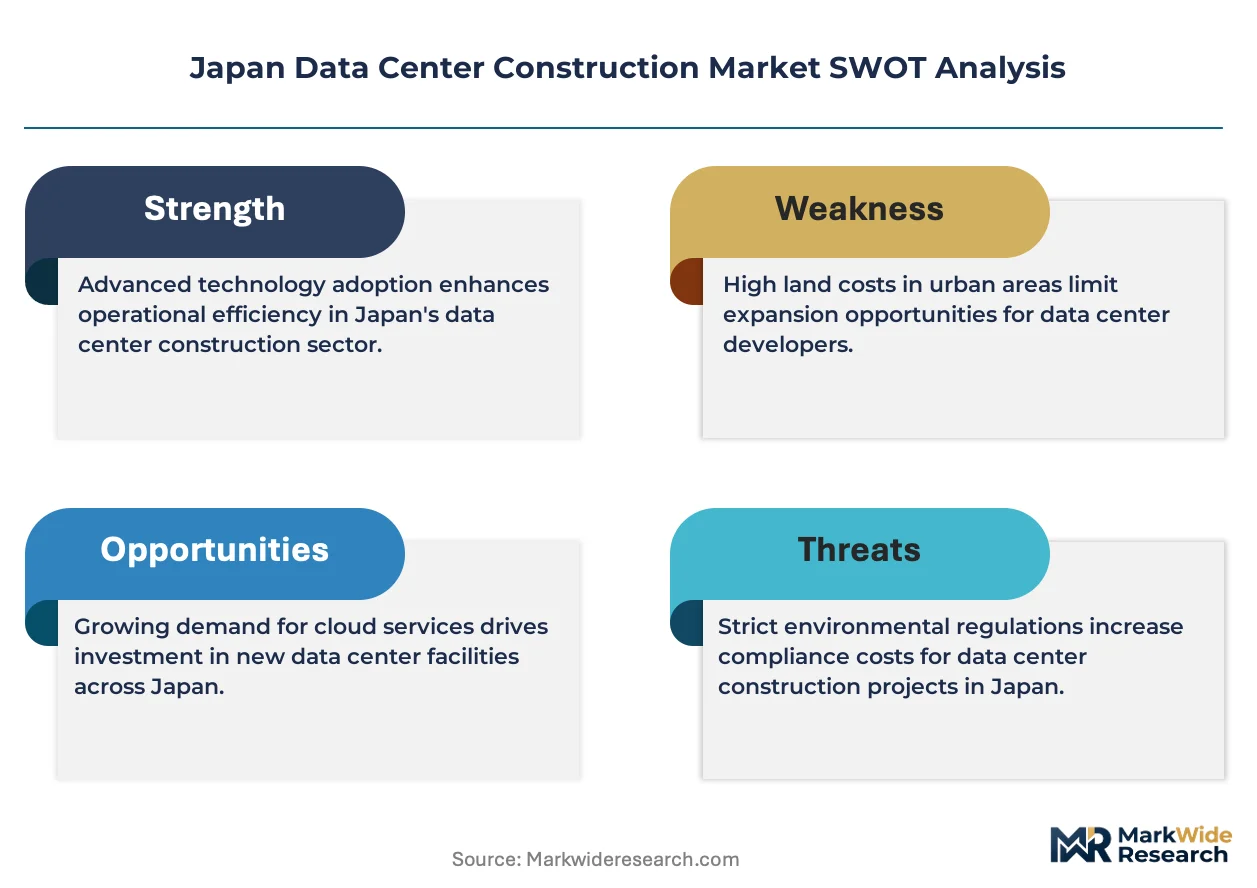
- Land Scarcity in Core Markets:Tokyo and Osaka prefectures face acute industrial land constraints that inflate site acquisition costs and extend zoning approval timelines.
- Seismic Engineering Premium:JIS-compliant base isolation and damping systems add 15-25% to structural capital costs versus conventional builds in seismically stable geographies.
- Grid Interconnection Queues:Regional utilities impose multi-year waits for substation upgrades and dedicated high-voltage feeds above 50 MW capacity.
Strategic Opportunities
- Hokkaido Renewable Power:Abundant geothermal and wind resources offer carbon-neutral electricity sourcing for operators targeting Scope 2 neutrality commitments.
- Waste Heat Recovery:District heating integration with municipal networks creates secondary revenue streams and accelerates permitting in urban jurisdictions.
- Modular Factory Prefabrication:Off-site assembly of power and cooling modules compresses on-site construction windows and reduces labor dependency.
Industry Challenges
- Specialized Mechanical Talent:Shortages of technicians certified in refrigerant handling and precision HVAC commissioning extend commissioning schedules.
- Legacy System Integration:Brownfield expansions must reconcile new liquid cooling loops with existing air-cooled rack architectures without full facility shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Construction Market |
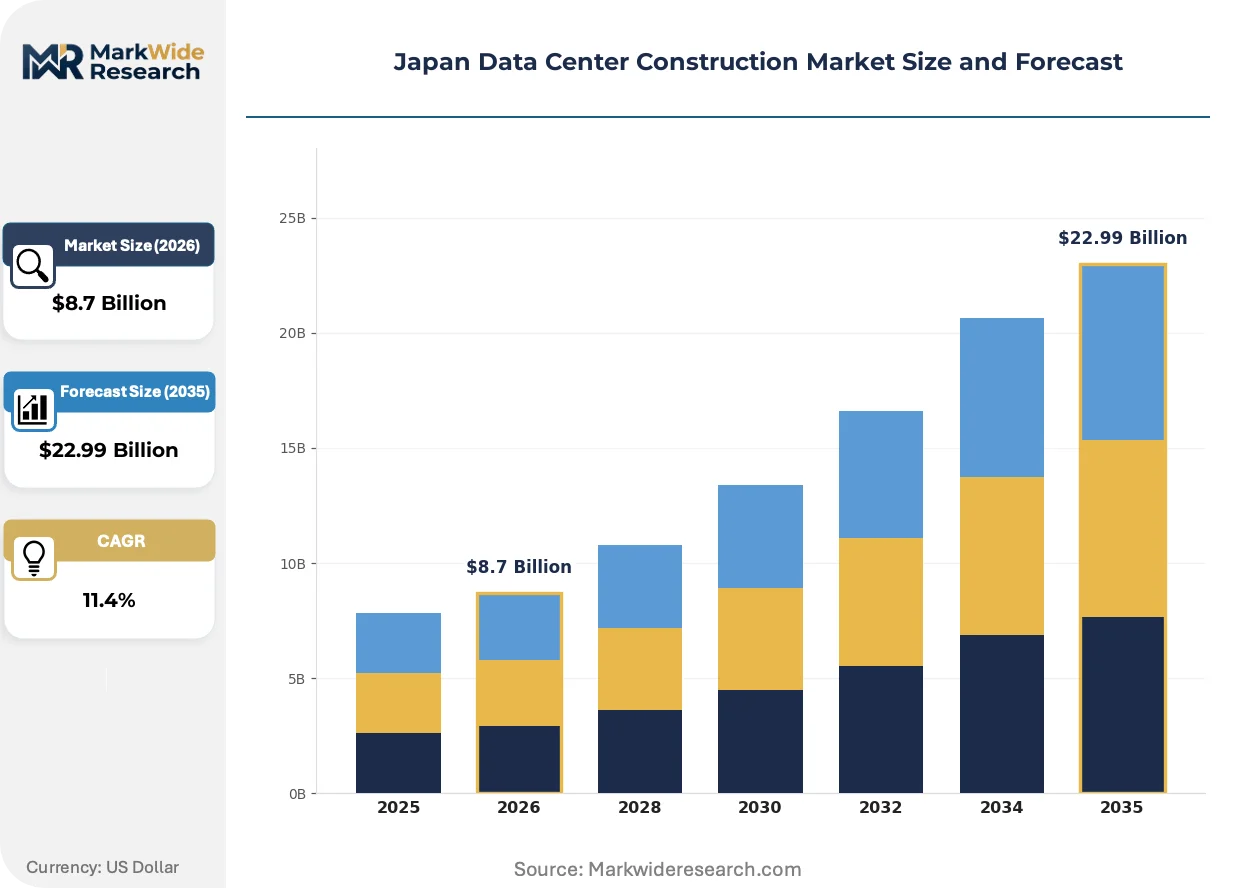
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Hyperscale, Colocation, Edge, Modular Power Source: Renewable, Grid, Diesel, Hybrid Construction Type: New Build, Retrofit, Expansion, Pre-fabricated End User: IT Companies, Cloud Providers, Telecommunications, Enterprises |
| Companies Covered | Shimizu Corporation, Daiwa House Industry Co., Ltd., Obayashi Corporation, Fuji Furukawa Engineering and Construction, Hibiya Engineering Ltd, Kajima Corporation, Takenaka Corporation, Tokyu Construction, Taisei Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Construction Market Trends and Innovations
Facility engineering is pivoting from static capacity planning to dynamic, software-defined infrastructure that adapts to workload volatility in real time.
Artificial intelligence-driven building management software is automating predictive maintenance scheduling and energy load balancing across mechanical systems. Hyperscale operators are deploying these platforms at greenfield sites in Greater Tokyo. The technology is automating fault detection and response protocols that previously required 24/7 on-site engineering presence.
METI's 2024 amendments to the Act on Rationalizing Energy Use introduced mandatory carbon disclosure thresholds for facilities above 1,500 kW contracted demand. Operators must now install sub-metering and report granular PUE metrics to prefectural authorities. Colocation providers in Osaka and Fukuoka are accelerating LEDC and ISO 50001 certifications to preempt compliance gaps.
Enterprise buyers are consolidating vendor relationships around single-source design-build contracts that transfer completion risk to contractors. Financial services and gaming sectors in Tokyo are driving this consolidation to compress time-to-operation. The shift is most pronounced among domestic enterprises that previously self-managed multi-contractor builds.
Japan Data Center Construction Market Segmentation
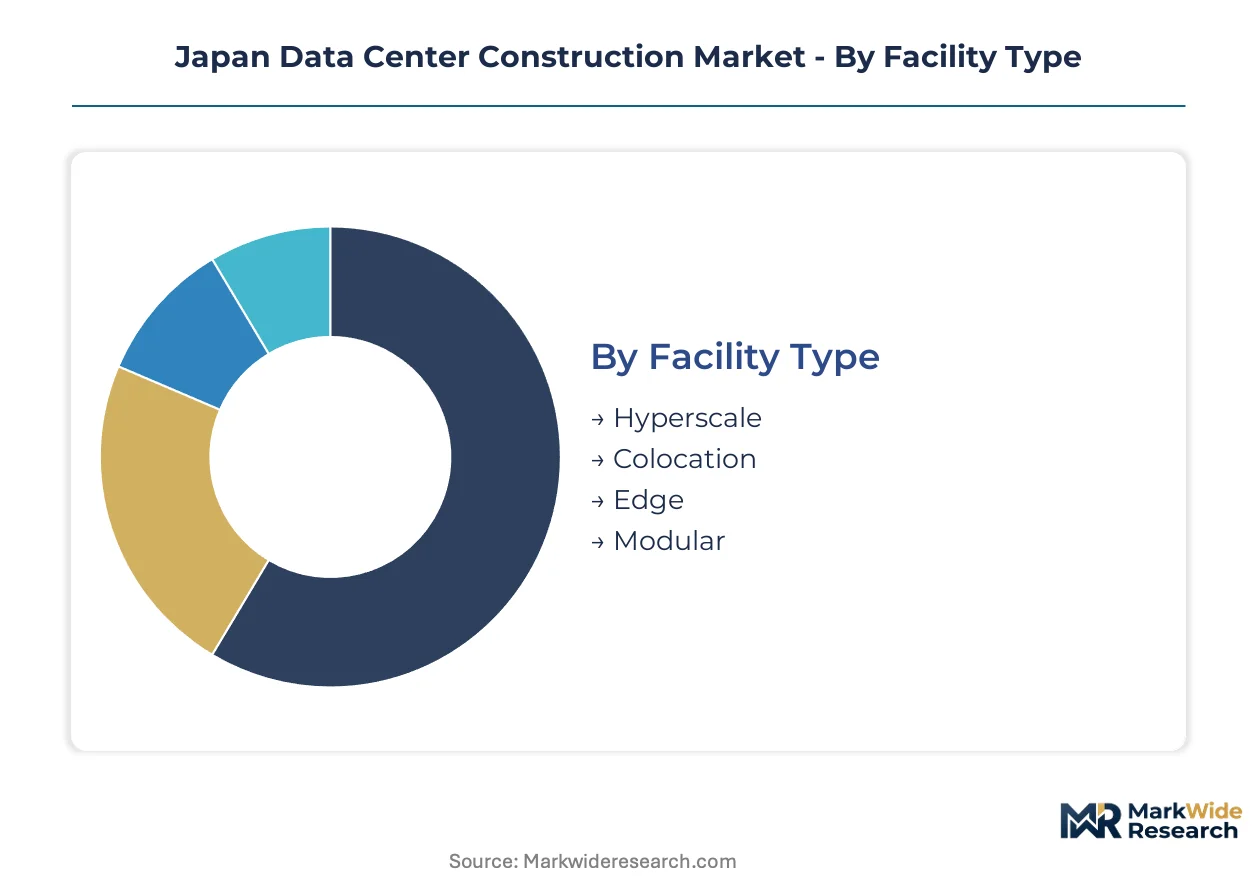
Segmentation in Japan's data center construction market reveals how capital allocation splits across facility scales, energy strategies, and deployment velocities. Understanding these divides exposes where METI regulations bite hardest and where modular methods compress delivery timelines.
Facility Type:
Customization intensity varies sharply across this category, from bespoke hyperscale campuses to standardized edge nodes.
- Hyperscale:Facilities exceeding 50 MW designed for single-tenant cloud operators with 15+ kW rack densities and liquid cooling integration. Demand concentrates in Greater Tokyo and Osaka as international cloud providers secure land for AI training clusters, constrained by METI energy disclosure mandates above 1,500 kW.
- Colocation:Multi-tenant facilities with standardized power and cooling modules serving enterprises outsourcing infrastructure ownership. Osaka and Fukuoka operators are accelerating LEDC certifications to preempt METI compliance gaps while maintaining hybrid-ready architectures.
- Edge:Distributed sub-5 MW deployments positioned for 5G densification and autonomous vehicle corridors.
- Modular:Factory-prefabricated power and cooling skids compressing on-site construction windows.
Most installed capacity flows through Hyperscale. Expansion is steepest in Edge.
Power Source:
Cost tier differentiation separates premium renewable sourcing from baseline grid dependency across this category.
- Renewable:Geothermal from Hokkaido and wind power purchase agreements enabling Scope 2 neutrality commitments. Hokkaido operators leverage abundant geothermal and wind resources to attract hyperscale tenants with carbon-neutral electricity sourcing.
- Grid:Conventional utility supply from regional operators with multi-year interconnection queues for substation upgrades above 50 MW capacity.
- Diesel:Backup generation systems meeting JIS fire resistance standards for seismic zones.
- Hybrid:Blended renewable-grid configurations with battery storage smoothing intermittency.
Grid connections dominate current capacity. Renewable sourcing is climbing fastest.
Construction Type:
Maturity gradients separate legacy retrofit approaches from emerging prefabrication methods in this category.
- New Build:Greenfield developments incorporating direct-to-chip liquid cooling and seismic base isolation from foundation stage. Greater Tokyo greenfield sites are deploying AI-driven building management software automating predictive maintenance and energy load balancing.
- Retrofit:Brownfield liquid cooling integration reconciling new loops with existing air-cooled architectures without full facility shutdowns.
- Expansion:Phased capacity additions to operating facilities requiring live-environment mechanical work.
- Pre-fabricated:Off-site assembly of power modules and cooling skids reducing labor dependency and on-site construction windows.
New Build absorbs the largest capital share. Pre-fabricated methods are gaining share fastest.
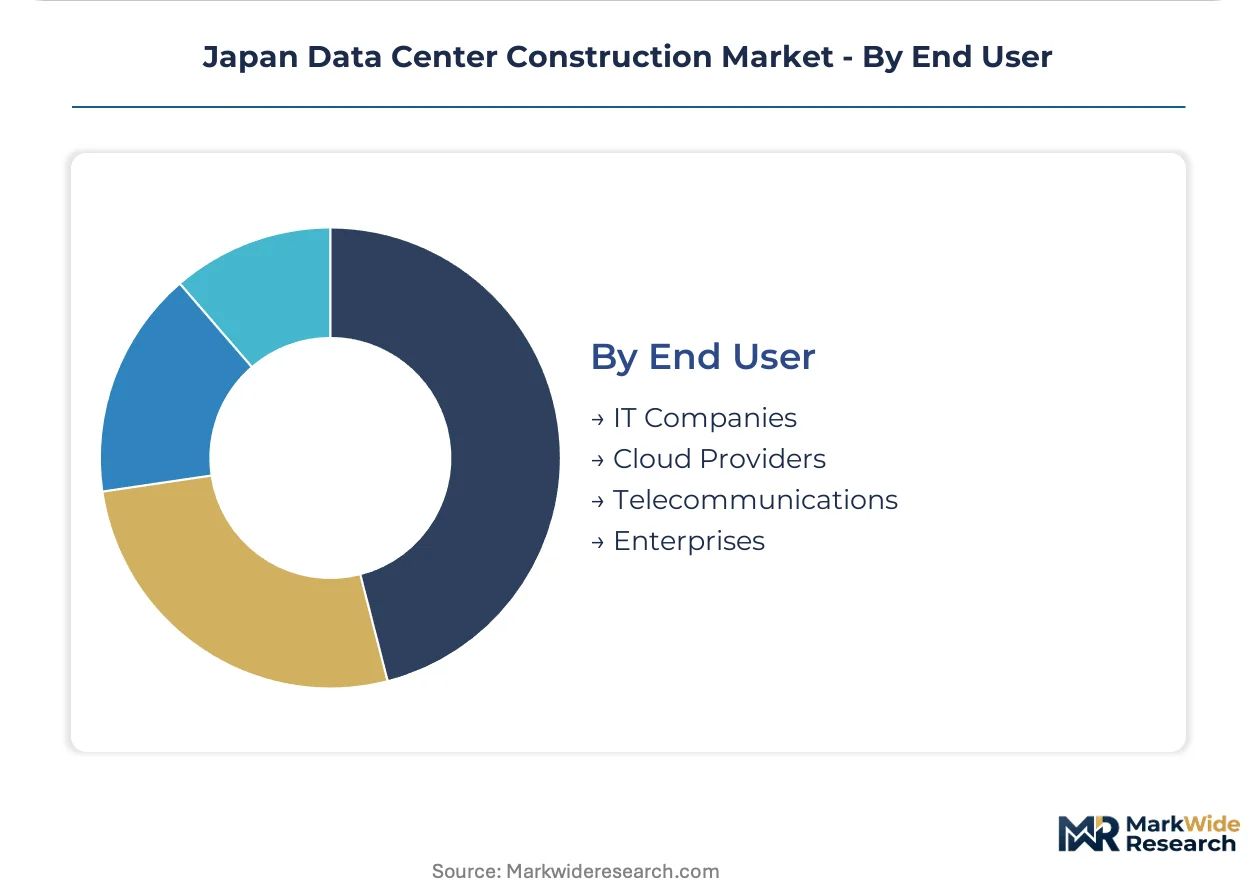
End User:
Customer type fragmentation splits this category between latency-sensitive operators and cost-optimizing enterprises.
- IT Companies:Domestic technology firms consolidating vendor relationships around single-source design-build contracts transferring completion risk to contractors. Tokyo financial services and gaming sectors are driving this consolidation to compress time-to-operation.
- Cloud Providers:International hyperscale operators committing capital to domestic facilities for AI inference workloads and enterprise cloud migration.
- Telecommunications:5G network operators pulling distributed compute into secondary metropolitan zones for densification.
- Enterprises:Traditional corporations outsourcing infrastructure ownership to colocation providers while maintaining compliance control.
Cloud Providers command the largest facility footprints. IT Companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Tokyo anchors facility development as international cloud operators secure land for AI training clusters. Osaka and Fukuoka corridors attract secondary investments driven by enterprise colocation demand. METI's energy disclosure mandates above 1,500 kW reshape site selection calculus across all prefectures.
Kanto/Tokyo
Hyperscale operators commit capital to AI inference workloads and enterprise cloud migration. METI enforces mandatory carbon disclosure thresholds for facilities exceeding contracted demand limits. Saitama and Chiba prefectures absorb overflow development as Tokyo proper faces acute industrial land constraints.
Kansai/Osaka
Colocation providers accelerate LEDC certifications to preempt compliance gaps under revised energy regulations. Osaka prefectural ordinances on noise and land use constrain site selection in dense urban zones. Sakai and Kyoto satellite zones emerge as alternative locations for modular edge deployments.
Chubu/Nagoya
Automotive and manufacturing enterprises outsource infrastructure ownership to hybrid-ready colocation facilities. JIS standards for seismic performance shape structural engineering specifications across new builds. Toyota City and Nagoya metropolitan clusters concentrate demand from latency-sensitive industrial IoT applications.
Hokkaido
Abundant geothermal and wind resources attract hyperscale tenants with carbon-neutral electricity sourcing commitments. Regional utilities impose shorter grid interconnection timelines compared to Honshu counterparts. Tomakomai and Sapporo zones develop as renewable-powered alternatives to mainland capacity constraints.
Kyushu
Submarine cable landing stations pull distributed compute infrastructure into Fukuoka for Asia-Pacific connectivity. Local prefectural authorities streamline permitting for facilities integrating waste heat recovery with municipal district heating. Kitakyushu industrial zones repurpose legacy manufacturing sites for edge computing nodes.
Japan Data Center Construction Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular prefabrication and liquid cooling specialization. The vendor base clusters around three strategic archetypes: integrated design-build contractors, seismic engineering specialists, and modular construction innovators. Competitive positioning hinges on completion risk transfer capabilities and METI compliance acceleration. Market participants execute capacity expansion in renewable-rich prefectures while forming technology licensing partnerships for direct-to-chip cooling systems.
Among integrated design-build contractors, Shimizu Corporation and Takenaka Corporation exemplify the turnkey hyperscale archetype. Kajima Corporation occupies a position within the modular construction tier, representing factory-prefabrication approaches that compress deployment timelines. These three anchors demonstrate how domestic contractors leverage seismic isolation expertise and METI regulatory fluency to differentiate against international entrants lacking Japan-specific engineering credentials.
| Leading Market Players |
|---|
| Shimizu Corporation |
| Daiwa House Industry Co., Ltd. |
| Obayashi Corporation |
| Fuji Furukawa Engineering and Construction |
| Hibiya Engineering Ltd |
| Kajima Corporation |
| Takenaka Corporation |
| Tokyu Construction |
| Taisei Corporation |
| Others |
Pricing and Supply Chain Analysis
METI's carbon disclosure mandates for facilities above 1,500 kW contracted demand gate both qualified mechanical contractor networks and premium-tier project pricing. Contractors possessing LEDC certification and ISO 50001 credentials command 20-30% construction cost premiums over uncertified competitors, while non-compliant bidders face automatic disqualification from hyperscale and enterprise colocation tenders.
Pricing Analysis
Input-cost pass-through from seismic base isolation systems and liquid cooling infrastructure drives project-based contract structures with escalation clauses tied to steel and copper commodity indices. Price differentiation centers on JIS seismic certification tier and integrated design-build capability versus fragmented multi-contractor arrangements. Cost compression in standard-tier colocation builds is intensifying as domestic enterprises consolidate vendor relationships. Cloud providers demonstrate lowest price sensitivity, prioritizing completion risk transfer and METI compliance acceleration over capital expenditure minimization.
Supply Chain Analysis
Direct-to-hyperscale channels handle international cloud operator demand, while tier-2 integrators serve domestic enterprise colocation projects. Manufacturing concentration for precision HVAC equipment and seismic isolation bearings rests on Japan, Germany, and South Korea. Critical dependencies include copper busbar assemblies, refrigerant-grade steel piping, and AI-driven building management software controllers. Single-source vulnerability in liquid cooling componentry exposes projects to 12-18 month lead time volatility. Distribution runs through integrated design-build contractors for 70% of hyperscale capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in modular prefabrication and renewable-powered greenfield development, where factory assembly methods compress labor costs and Hokkaido's geothermal access enables premium carbon-neutral positioning.
For Market Incumbents: Acquire specialized liquid cooling engineering teams to preempt capability gaps as METI thermal efficiency thresholds tighten. Integrate proprietary modular construction IP through technology licensing partnerships with direct-to-chip cooling specialists. Defend against emerging factory-prefabrication entrants by embedding AI-driven building management software into standard design-build offerings, transferring operational efficiency risk to contractor balance sheets. For New Entrants and Emerging Players: Direct-to-chip cooling specialization offers entry into hyperscale vendor lists currently dominated by seismic engineering generalists. Target Hokkaido and Kyushu greenfield developments where renewable power access and streamlined permitting create first-mover positioning. Pursue joint development agreements with regional utilities to bypass grid interconnection queues that constrain incumbent expansion timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale modular construction specialists because METI compliance complexity is driving enterprise buyers toward single-source accountability. Five-to-ten year viability favors contractors with captive factory-prefabrication capacity and established relationships with international cloud operators. Monitor hyperscaler capital commitment announcements as inflection indicators for construction backlog visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Factory Prefabrication | Off-site assembly compresses on-site construction windows and reduces labor dependency in Greater Tokyo. |
| Liquid Cooling Technology Licensing | Direct-to-chip and immersion cooling partnerships enable METI PUE compliance below 1.2 thresholds. |
| Hokkaido Renewable Power Integration | Geothermal and wind PPAs attract hyperscale tenants with Scope 2 neutrality commitments. |
| AI-Driven Building Management Deployment | Predictive maintenance automation reduces 24/7 on-site engineering presence requirements. |
| Waste Heat Recovery Partnerships | District heating integration with municipal networks accelerates urban permitting and creates secondary revenue. |
Research Methodology
Direct dialogue with data center construction executives, METI regulatory affairs specialists, mechanical engineering contractors, and hyperscale facility operators grounded qualitative insights. Secondary validation drew from METI energy disclosure filings, JIS standards documentation, regional utility interconnection queue data, and prefectural zoning ordinance records. Bottom-up project pipeline aggregation and top-down capital expenditure triangulation converged on market sizing estimates.
Segment-level value outputs emerged from facility type, power source, construction method, and end-user demand modeling across the projection horizon. CAGRs derived from regression analysis against cloud provider capex disclosures, 5G network densification timelines, and METI regulatory phase-in schedules. Forecast inputs incorporated seismic engineering cost premiums, liquid cooling adoption curves, and modular prefabrication penetration rates.
The model holds under steady METI enforcement intensity and sustained hyperscaler land acquisition; deviation in grid interconnection timeline acceleration or renewable PPA pricing volatility would shift capacity deployment geography. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Dedicated Server Hosting Market