
 India Data Center Server Market | 2026-2036
India Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Server Market Insights
Project finance tied to green bond issuances is reconfiguring competitive entry in India's data center server landscape. Hewlett Packard Enterprise leverages its local manufacturing partnerships to anchor supply commitments for hyperscale deployments. Dell Technologies sustains channel control through direct enterprise relationships and distributor networks across tier-1 and tier-2 cities. Netweb Technologies India specializes in indigenously designed servers that compete on cost-adjusted performance for government and PSU tenders.
Data center servers are purpose-built computing systems engineered with multi-core processors, redundant power supplies, and hot-swappable components to deliver continuous uptime for enterprise workloads. These systems process transactional data, host virtualized environments, and manage storage arrays across cloud and on-premise installations. Rack servers dominate volume deployment across Indian colocation facilities due to standardization and density optimization. Edge Computing represents the fastest-growing technology segment as latency-sensitive applications from manufacturing and retail push compute closer to source data generation. Blade servers occupy concentrated margin pools in financial services where space constraints and centralized management justify premium configurations.
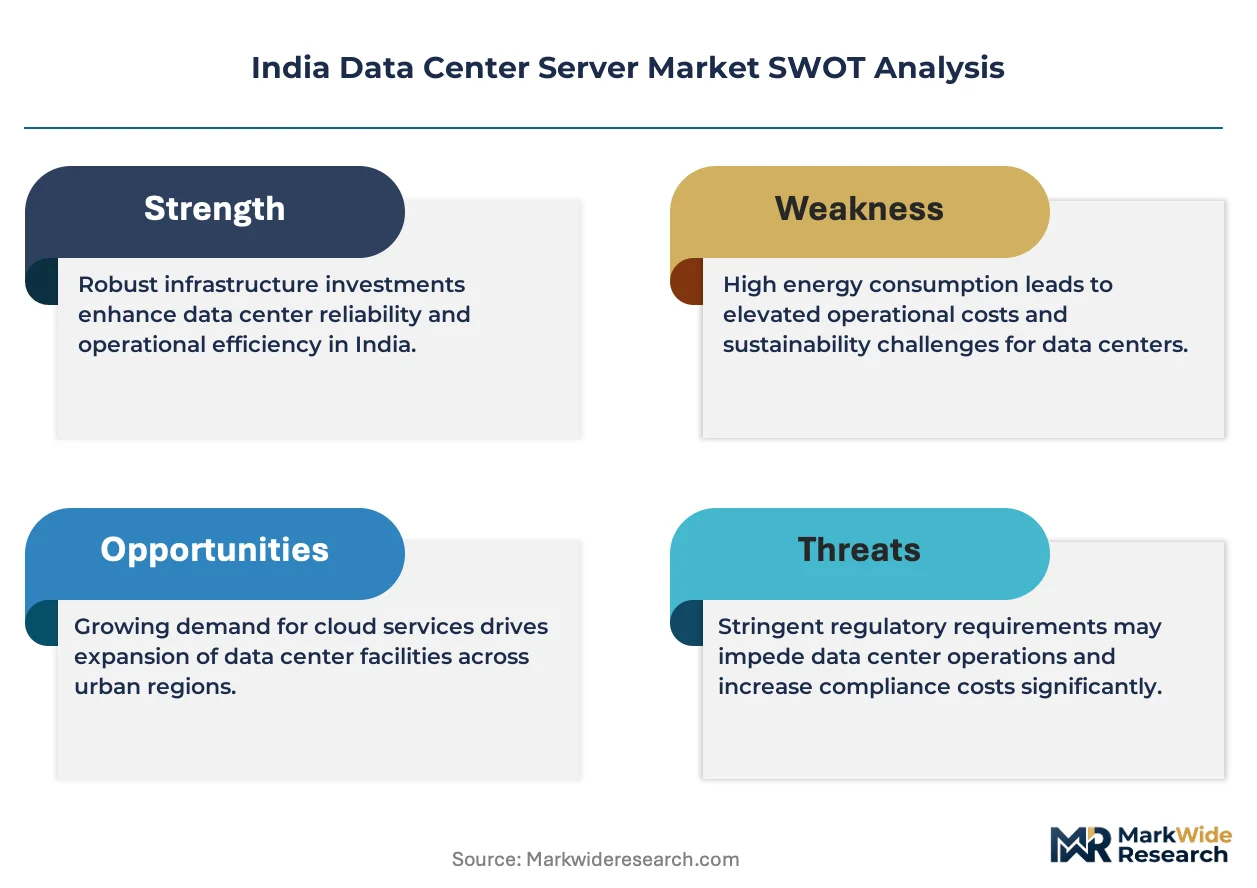
MeitY's Data Centre Policy and BIS certification requirements for IT hardware are tightening product standards and channeling procurement toward domestically assembled units. The PLI scheme for IT hardware and state-level data center policies in Maharashtra and Telangana are reshaping where manufacturing capacity and demand co-locate. Stakeholders must monitor how evolving CEA power-usage norms and state electricity tariff structures alter total cost of ownership calculations for server fleet operators.
Market Dynamics
Hyperscale cloud operators are consolidating server procurement around green bond-financed facilities, compressing vendor selection cycles and privileging suppliers with verified domestic assembly lines under BIS certification.
Growth Catalysts
- PLI scheme for IT hardware:Production-linked incentives are accelerating domestic manufacturing capacity for data center equipment, reducing import dependency for rack and blade server assemblies.
- Edge Computing deployments:Latency-sensitive manufacturing and retail applications are pushing compute infrastructure toward tier-2 cities, expanding addressable server demand beyond traditional metro clusters.
- Maharashtra and Telangana data center policies:State-level infrastructure zones with streamlined clearances and subsidized power tariffs are concentrating hyperscale investment in these corridors.
Market Restraints
- GPU and advanced processor import concentration:Supply of AI-optimized server components remains concentrated with Taiwan and US-based foundries, exposing procurement to export control volatility.
- CEA power-usage norms:Tightening efficiency standards under Central Electricity Authority regulations are raising compliance costs for legacy server fleet operators.
- Liquid cooling infrastructure gap:High-density rack deployments face technical limitation from inadequate chilled water distribution and heat rejection capacity in existing facilities.
Strategic Opportunities
- Indigenous server design:Government and PSU tenders are creating procurement preference for domestically engineered systems that compete on cost-adjusted performance metrics.
- Green hydrogen power purchase agreements:Renewable energy mandates under state electricity regulations are enabling tariff arbitrage for operators securing long-term clean power contracts.
- Micro-edge installations:5G network densification is opening server deployment opportunities at cellular base stations and industrial IoT aggregation points.
Industry Challenges
- Server hardware certification timelines:BIS testing protocols and MeitY security compliance are extending product validation cycles, delaying revenue recognition for new platform introductions.
- Legacy virtualization stack integration:Enterprise migrations from on-premise VMware estates to cloud-native Kubernetes environments require complex workload refactoring and downtime orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Server Market |
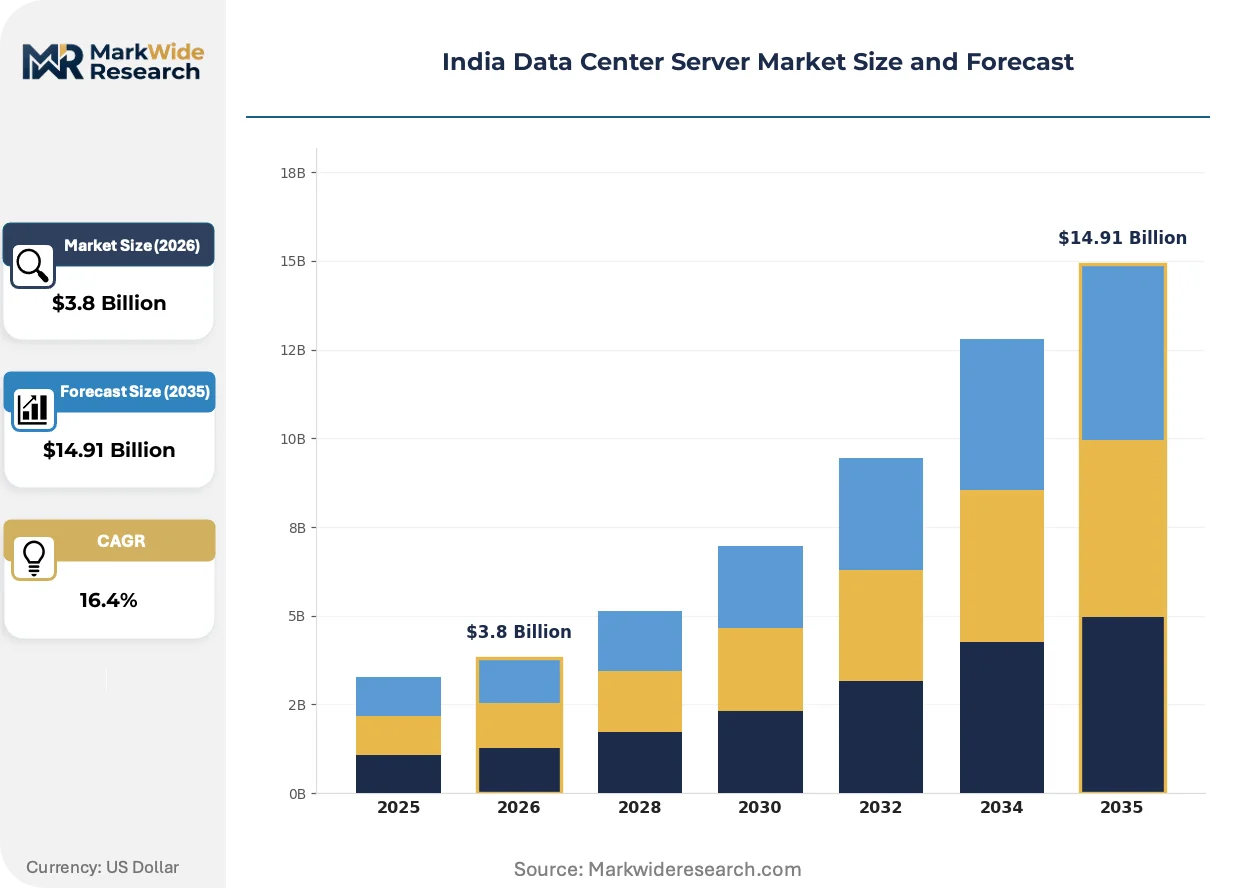
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Mainframe Servers End User: Telecommunications, BFSI, Healthcare, Government Technology: Virtualization, Hyperconverged Infrastructure, Edge Computing, Cloud Computing Application: Data Processing, Backup & Recovery, Server Hosting, Cloud Storage |
| Companies Covered | Hewlett Packard Enterprise, Broadcom, Netweb Technologies India, NetForChoice, Arista Networks, E2E Networks, Cisco Systems, Aurionpro Solutions, Dell Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Server Market Trends and Innovations
Server architecture is fragmenting across thermal design, processing topology, and financing structures as workload diversity outpaces homogeneous infrastructure economics.
Arm-based processors are hybridizing the x86-dominated server landscape by offering performance-per-watt advantages for cloud-native and containerized workloads. Hyperscale operators in Hyderabad and Noida are piloting these architectures for non-critical compute tiers. The technology is hybridizing procurement specifications, forcing incumbent vendors to dual-source silicon strategies.
MeitY's Data Centre Policy mandates minimum power usage effectiveness thresholds and renewable energy share commitments for new facility approvals. Operators must now integrate carbon accounting into capex planning and secure green certification from the Bureau of Energy Efficiency. Maharashtra-based facilities face the tightest compliance windows as the state advances its net-zero electricity grid commitments.
Enterprise buyers are consolidating server procurement through managed infrastructure contracts that bundle hardware, maintenance, and colocation into single-vendor relationships. Traditional distributor networks in tier-2 cities are losing volume to direct manufacturer engagements with large enterprises. Banking and financial services in Mumbai exhibit the strongest concentration, with CIOs favoring outcome-guaranteed uptime contracts over capital purchase models.
India Data Center Server Market Segmentation
Server procurement patterns in India fragment sharply across deployment topology, workload sensitivity, and regulatory compliance requirements. Understanding these segment boundaries reveals where vendor margins concentrate and which technology transitions will reshape competitive positioning over the forecast window.
Product Type:
After-sales service intensity varies dramatically across form factors, with rack deployments demanding routine thermal maintenance and blade systems requiring specialized technician callouts for mid-plane failures.
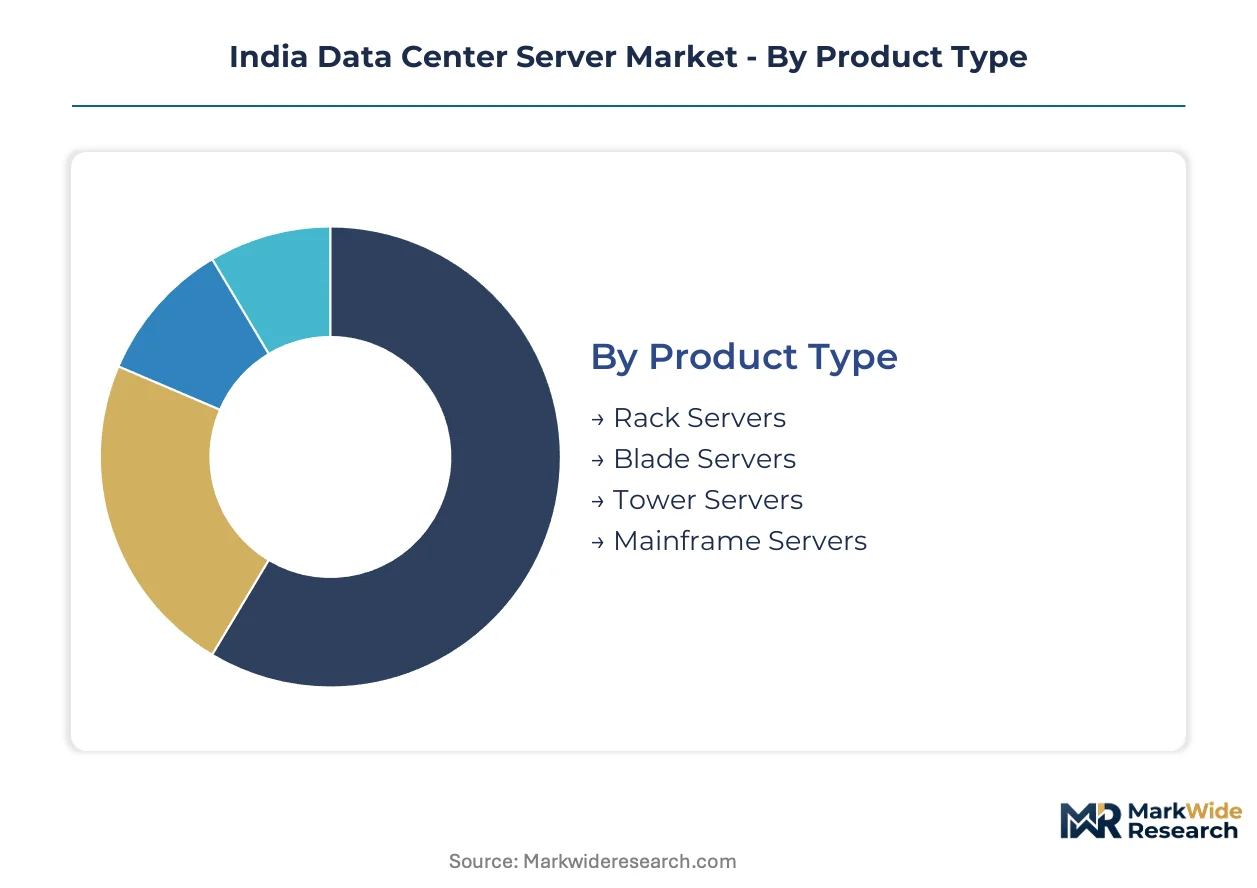
- Rack Servers:Standardized 1U to 4U enclosures housing independent compute nodes with redundant power and hot-swappable storage. Demand concentrates in Maharashtra colocation corridors where density-optimized footprints align with CEA power-usage compliance requirements for new facility approvals.
- Blade Servers:Modular chassis-based systems sharing power, cooling, and network infrastructure across multiple server blades. Banking headquarters in Mumbai drive procurement where floor space constraints and centralized management justify premium configurations and integrated service contracts.
- Tower Servers:Standalone vertical enclosures suited for branch office deployments and small-scale on-premise workloads. Regional PSU data centers in tier-2 cities favor these for standalone reliability without rack infrastructure investment.
- Mainframe Servers:High-availability centralized systems processing massive transactional volumes with hardware-level redundancy. Core banking modernization at SBI and other public sector banks sustains this segment despite cloud migration pressure.
By volume, Rack Servers lead. By growth pace, Blade Servers are ahead.
End User:
Customer procurement sophistication spans from outcome-based managed infrastructure contracts to rigid tender-driven capital purchases.
- Telecommunications:5G core network functions and subscriber data management drive high-availability server demand. Jio and Airtel hyperscale deployments in Hyderabad and Noida anchor volume, with edge node expansion into tier-2 cities climbing fastest.
- BFSI:Risk analytics, real-time payments infrastructure, and regulatory reporting workloads dominate specifications. Private sector banks in Mumbai consolidate procurement through direct manufacturer engagements with uptime-guaranteed service level agreements.
- Healthcare:Hospital information systems and medical imaging archives require compliance with CDSCO data localization guidelines. Diagnostic chains in Delhi-NCR and Bengaluru represent the primary demand concentration.
- Government:MeitY-mandated domestic procurement preferences and BIS certification requirements channel tenders toward indigenously assembled systems. State data center projects under Digital India sustain predictable though elongated sales cycles.
Telecommunications captures the largest installed base. Government contracts are expanding most quickly under PLI-accelerated localization mandates.
Technology:
Architecture choices determine whether infrastructure spend flows to incumbent virtualization vendors or cloud-native platform providers.
- Virtualization:VMware and Hyper-V environments remain entrenched in legacy enterprise estates. Financial services in Mumbai exhibit the strongest concentration, though Kubernetes migration pressure is compressing new license growth.
- Hyperconverged Infrastructure:Software-defined compute-storage-network integration simplifies branch office and remote site deployments. Mid-market enterprises across Pune and Chennai favor these for rapid provisioning without specialized storage administration.
- Edge Computing:Distributed micro-data centers processing latency-sensitive workloads at source. Manufacturing automation in Gujarat and Tamil Nadu, plus retail POS analytics, are climbing fastest as 5G backhaul densifies.
- Cloud Computing:Public cloud infrastructure-as-a-service and private cloud platforms built on OpenStack or proprietary stacks. Hyperscale operator expansion in Hyderabad and Noida concentrates procurement volume for multi-tenant server farms.
Cloud Computing dominates current infrastructure investment. Edge Computing is gaining share fastest as latency requirements harden across industrial IoT deployments.
Application:
Workload criticality determines redundancy specifications, disaster recovery architecture, and acceptable maintenance windows.
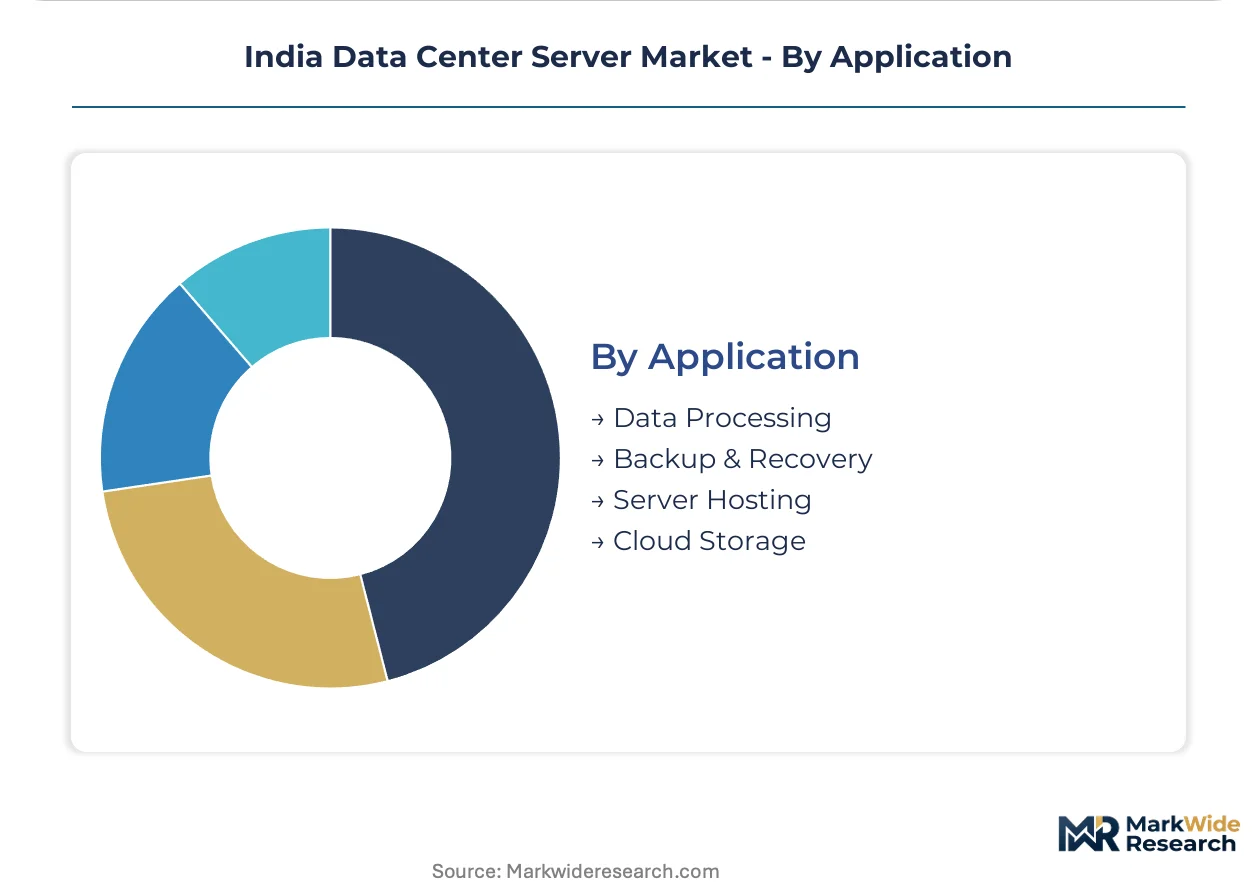
- Data Processing:Transaction processing, analytics, and artificial intelligence training workloads. BFSI real-time payments and securities trading in Mumbai drive highest-specification configurations with liquid cooling readiness.
- Backup & Recovery:Secondary site replication, archival storage, and ransomware recovery infrastructure. Regulatory mandates from RBI and SEBI for business continuity are expanding dedicated recovery site server procurement.
- Server Hosting:Multi-tenant colocation and managed dedicated server offerings. Mumbai and Noida facilities lead volume, with Chennai emerging under Tamil Nadu data center policy incentives.
- Cloud Storage:Object storage, file services, and block storage backends for SaaS and enterprise workloads. Domestic cloud providers competing with AWS, Azure, and GCP anchor demand for scale-out storage-optimized servers.
Data Processing commands the highest average selling prices. Cloud Storage is climbing fastest as domestic SaaS expansion and data localization requirements deepen local infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level data center policies and subsidized power tariffs are redistributing server demand across Indian sub-regions. Maharashtra and Telangana anchor hyperscale investment through specialized infrastructure zones.
Maharashtra
Mumbai's financial services sector drives premium blade server procurement for risk analytics and real-time payments. The state's data center policy offers streamlined clearances and reduced electricity tariffs for facilities meeting green energy thresholds. Navi Mumbai and Pune corridors concentrate colocation capacity expansion.
Telangana
Hyderabad's hyperscale cloud operator presence generates volume demand for rack-optimized server configurations. The Telangana State Industrial Project Approval and Self-Certification System accelerates facility commissioning timelines. Hardware assembly partnerships under PLI scheme incentives cluster in the city's electronics manufacturing zone.
Karnataka
Bengaluru's software-as-a-service ecosystem sustains steady server refresh cycles for private cloud infrastructure. The state's EV and energy storage policies indirectly support grid-stabilization for data center power requirements. Whitefield and Electronic City sub-regions host domestic cloud provider server farms.
Tamil Nadu
Chennai's submarine cable landing stations attract submarine cable-linked server hosting demand. The Tamil Nadu Data Centre Policy provides capital subsidies and stamp duty exemptions for new facility investments. Sriperumbudur electronics corridor emerges as an assembly location for domestically manufactured server components.
Delhi-NCR
Government and PSU data localization mandates channel server procurement toward Noida and Greater Noida facilities. MeitY's Data Centre Policy compliance requirements favor BIS-certified hardware assemblies for public sector tenders. The region's concentration of central government ministries sustains predictable though elongated sales cycles.
India Data Center Server Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market exhibits moderate consolidation with three distinct competitive layers. Global technology conglomerates with established distributor networks occupy the premium enterprise segment. Domestic system integrators and indigenously focused manufacturers capture government and mid-market opportunities. Hyperscale cloud operators increasingly negotiate direct supply agreements, compressing traditional channel margins.
Among global technology providers, Hewlett Packard Enterprise and Dell Technologies anchor the premium enterprise tier through direct manufacturer relationships and established service networks. Netweb Technologies India occupies a specialist position serving government tenders and PSU procurement with domestically engineered configurations. These three represent the dominant archetypes: global full-service providers with local manufacturing partnerships, and indigenous design specialists competing on cost-adjusted performance for regulated procurement channels.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Broadcom |
| Netweb Technologies India |
| NetForChoice |
| Arista Networks |
| E2E Networks |
| Cisco Systems |
| Aurionpro Solutions |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
Sriperumbudur's electronics manufacturing corridor concentrates server assembly capacity under PLI scheme incentives, translating upstream component access into pricing leverage for domestic vendors competing against import-dependent rivals. This geographic concentration of BIS-certified assembly lines compresses procurement timelines for hyperscale operators while pressuring margins on non-compliant hardware.
Pricing Analysis
Certification level (BIS/CE/ISO-grade) creates the primary spread between premium and economy server tiers. Three-tier pricing structure across premium, standard, and economy levels dominates enterprise procurement, with hyperscale cloud operators extracting volume discounts through direct manufacturer engagements. Cost compression in the standard tier is intensifying because PLI-accelerated domestic assembly expands supply. Government and PSU tenders exhibit highest price sensitivity due to rigid tender-driven capital purchase mandates, while private sector banks in Mumbai show lowest sensitivity when uptime-guaranteed service level agreements bundle hardware and maintenance.
Supply Chain Analysis
Extended payment terms from hyperscale cloud operators restructure working capital requirements for assembly partners. Taiwan, South Korea, and the United States concentrate GPU and advanced processor supply, exposing procurement to export control volatility. Server manufacturing draws from imported silicon, domestic chassis assembly, and locally sourced power supply units. Single-source vulnerability in AI-optimized components presents the dominant structural risk. Distribution runs through direct manufacturer relationships with large enterprises, compressing traditional distributor networks in tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's data center server market operates as a defensive-moat story where regulatory entrenchment through BIS certification and MeitY procurement mandates creates durable competitive barriers for compliant domestic assemblers.
For Market Incumbents: Insulate market position by deepening backward integration into chassis and power supply manufacturing under PLI scheme incentives. Anchor supply commitments for hyperscale deployments through verified domestic assembly lines. Certification investment represents the priority lever against emerging indigenous design specialists competing on cost-adjusted performance for government tenders.
For New Entrants and Emerging Players: Pursue white-space opportunities in edge computing deployments across tier-2 manufacturing corridors in Gujarat and Tamil Nadu. Micro-edge installations at cellular base stations and industrial IoT aggregation points represent the most penetrable segment. Go-to-market execution should target direct engagements with state data center projects under Digital India, bypassing hyperscale procurement concentration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors indigenous server design specialists with established BIS certification pathways and state-level policy relationships. Long-term viability hinges on PLI scheme extension and renewable energy mandate enforcement. Acquisition target archetype: domestic system integrators with proven government tender execution. Watch liquid cooling infrastructure buildout as the signal for high-density rack deployment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Supply Manufacturing | PLI scheme incentives reward domestic component sourcing, reducing import dependency for rack assemblies. |
| BIS Certification Fast-Track Program | Accelerated product validation compresses revenue recognition timelines for new platform introductions. |
| Green Hydrogen Power Purchase Agreement | Long-term clean power contracts enable tariff arbitrage under Maharashtra and Telangana electricity regulations. |
| Edge Computing Partnership with 5G Infrastructure Providers | Micro-edge server deployment at cellular base stations captures latency-sensitive manufacturing workloads. |
| Liquid Cooling Infrastructure Joint Venture | Chilled water distribution capacity unlocks high-density rack deployments for AI training workloads in Mumbai. |
Research Methodology
Initial hypotheses were tested against primary input from data center facility operators, server procurement officers at hyperscale cloud providers, PLI scheme manufacturing partners, and state IT department officials, and refined through secondary validation. Primary research combined structured interviews with secondary triangulation against BIS certification databases, MeitY policy circulars, CEA power-usage filings, and state electricity regulatory commission tariff orders. Bottom-up server deployment estimates from colocation facilities were cross-checked against top-down hyperscale capex disclosures.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions included product type (rack, blade, tower, mainframe), end user (telecommunications, BFSI, healthcare, government), technology (virtualization, hyperconverged infrastructure, edge computing, cloud computing), and application (data processing, backup and recovery, server hosting, cloud storage). CAGRs were derived from installed base refresh cycles, hyperscale expansion timelines, and PLI scheme capacity buildout trajectories. Forecast inputs incorporated state-level data center policy implementation pace and renewable energy mandate compliance thresholds.
Sensitivities concentrate around PLI scheme extension decisions, CEA power-usage norm enforcement intensity, and GPU export control volatility. Forecasts reflect assumptions about continued hyperscale investment concentration in Maharashtra and Telangana, BIS certification pathway efficiency, and state electricity tariff structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
Chile Data Center Server Market