
 Asia-Pacific Ammonium Nitrate Market | 2026-2036
Asia-Pacific Ammonium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ammonium Nitrate Market Insights
Multi-source procurement of ammonia feedstock is restructuring supply economics across the Asia-Pacific ammonium nitrate sector. Orica Limited leverages its integrated blasting services model to anchor downstream demand in Australian iron ore belts. Incitec Pivot Limited competes through manufacturing scale at its Queensland and Newcastle plants. Deepak Fertilisers and Petrochemicals Corporation Ltd specializes in technical-grade ammonium nitrate for explosives markets across South Asia.
Ammonium nitrate is a hygroscopic crystalline salt with the chemical formula NH₄NO₃, typically manufactured through the neutralization of nitric acid with anhydrous ammonia under controlled temperature and pressure conditions. It serves as both a high-nitrogen fertilizer delivering 34% nitrogen content and as the principal oxidizer in industrial explosives formulated as ammonium nitrate fuel oil. Prilled product dominates volume flows across mining corridors where bulk handling infrastructure favors free-flowing spherical particles. Agricultural fertilization applications sustain the widest geographic footprint, with field crops in India's Indo-Gangetic Plain absorbing substantial tonnage through government procurement channels. Solutions and liquid blends are gaining traction among plantation operators in Indonesia and Malaysia seeking precision application compatibility.
China's MEE enforces emission caps on nitric acid plants, forcing capacity consolidation at larger facilities. Australia's AS 4326 and state-level dangerous goods regulators mandate stringent storage and transport protocols for ammonium nitrate classified as a security-sensitive substance. India's CEA and Petroleum and Explosives Safety Organisation jointly oversee licensing for explosives-grade production, creating dual-track compliance requirements for manufacturers serving both fertilizer and blasting sectors. Stakeholders must track how Indonesia's emerging mining provinces balance infrastructure build-out against evolving environmental permit conditions for new nitrate plants.
Market Dynamics
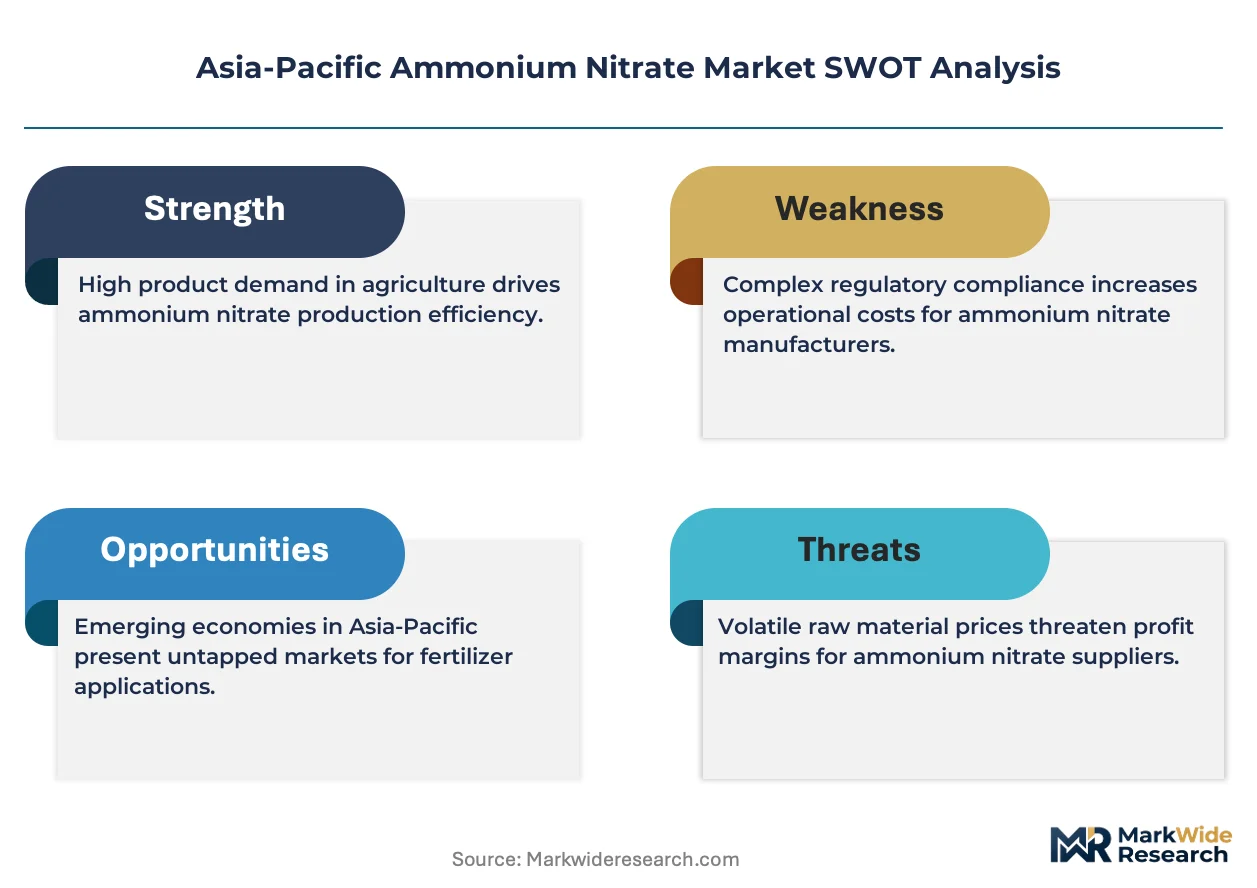
China's dual carbon goals are forcing nitric acid plant consolidation across the Asia-Pacific ammonium nitrate sector, restructuring feedstock procurement economics and concentrating production capacity at larger coastal facilities.
Growth Catalysts
- Australian iron ore expansion:Mining operations in Western Australia's Pilbara region are consuming bulk explosives at accelerating rates, pulling prilled ammonium nitrate through established supply corridors.
- India's subsidized fertilizer distribution:The government's nutrient-based subsidy scheme channels low-cost ammonium nitrate to smallholder farmers across Uttar Pradesh and Punjab, sustaining baseline agricultural demand.
- Indonesian nickel mining boom:Sulawesi and Halmahera operations require increasing volumes of bulk blasting agents, creating new demand nodes outside traditional consumption centers.
Market Restraints
- Natural gas price volatility:Ammonia synthesis depends on natural gas feedstock, exposing margins to LNG spot market swings across Southeast Asian import terminals.
- Chinese supply concentration:Over half of regional nitric acid capacity sits in Shandong and Jiangsu provinces, creating single-point failure risks for downstream ammonium nitrate producers.
- Emulsion explosive substitution:Water-gel and emulsion formulations are displacing ANFO in sensitive blasting applications, compressing technical-grade ammonium nitrate growth in Australian surface mining.
Strategic Opportunities
- Vietnam's underdeveloped mining sector:Bauxite and rare earth projects in the Central Highlands lack established explosives supply chains, opening first-mover positioning for technical-grade producers.
- Precision agriculture adoption:Liquid ammonium nitrate blends are penetrating Indonesian palm oil plantations, displacing conventional solid fertilizers through fertigation compatibility.
- Australia's security-sensitive substance protocols:AS 4326 compliance requirements create regulatory moats favoring domestic manufacturers with established dangerous goods infrastructure.
Industry Challenges
- Explosives licensing complexity:India's Petroleum and Explosives Safety Organisation imposes dual-track approvals for manufacturers serving both fertilizer and blasting sectors, extending product launch timelines.
- Nitrous oxide abatement capex:China's MEE emission caps require catalytic decomposition units at nitric acid plants, forcing capital allocation toward environmental compliance rather than capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ammonium Nitrate Market |
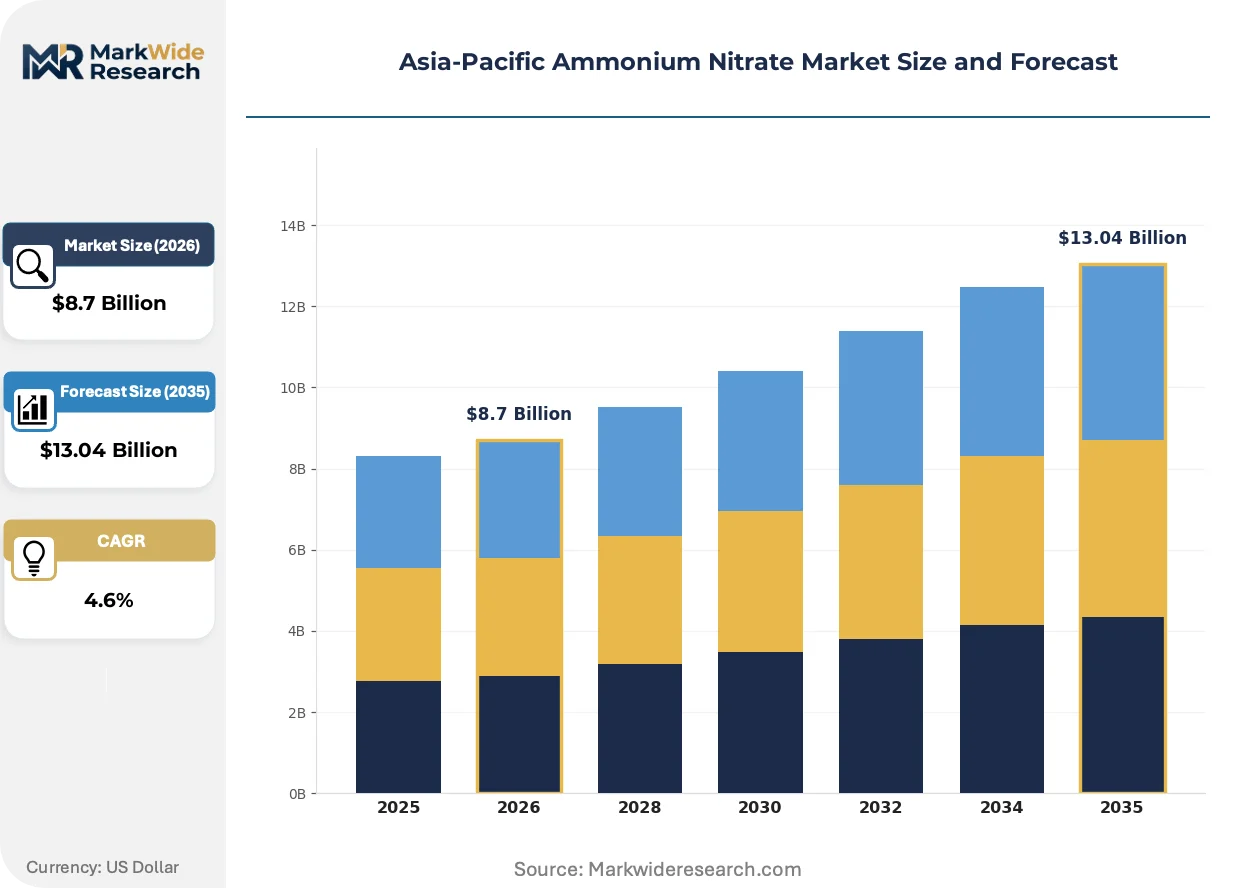
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Prilled, Solutions, Mixed End User: Agriculture, Mining, Explosives, Fertilizers Application: Field Crops, Ore Extraction, Controlled Blasting, Agricultural Fertilization Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Yara International ASA, Orica Limited, Incitec Pivot Limited, CF Industries Holdings Inc., EuroChem Group, San Corporation, Deepak Fertilisers and Petrochemicals Corporation Ltd, Rashtriya Chemicals and Fertilizers Ltd, Sumitomo Chemical Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ammonium Nitrate Market Trends and Innovations
Digital blasting systems and low-carbon ammonia pathways are restructuring how ammonium nitrate moves from chemical plant to blast hole across Asia-Pacific mining and agriculture corridors.
Carbon capture integration at ammonia production facilities is converging with green hydrogen pilot projects, enabling fossil-free ammonium nitrate for European export markets. Japanese trading houses are underwriting these investments to secure offtake agreements with Australian mining contractors facing Scope 3 disclosure requirements. The technology is compressing the carbon intensity gap between regional producers and Middle Eastern competitors.
China's MEE has tightened nitrous oxide emission limits for nitric acid plants, forcing capacity closures at smaller facilities in Hebei and Henan provinces. Surviving producers must install tertiary abatement systems, raising marginal production costs by 8-12 percent. Technical-grade ammonium nitrate destined for Australian explosives markets faces the steepest cost pass-through, as these buyers lack alternative supply sources with equivalent product specifications.
Consolidated procurement by Australian iron ore majors is displacing fragmented distributor networks across the Pilbara and Hunter Valley. Rio Tinto and BHP now contract directly with Orica and Incitec Pivot for integrated blasting services, bundling ammonium nitrate supply with drill-and-blast execution. This pattern concentrates volume at fewer chemical producers while squeezing independent explosives distributors out of core mining relationships.
Asia-Pacific Ammonium Nitrate Market Segmentation
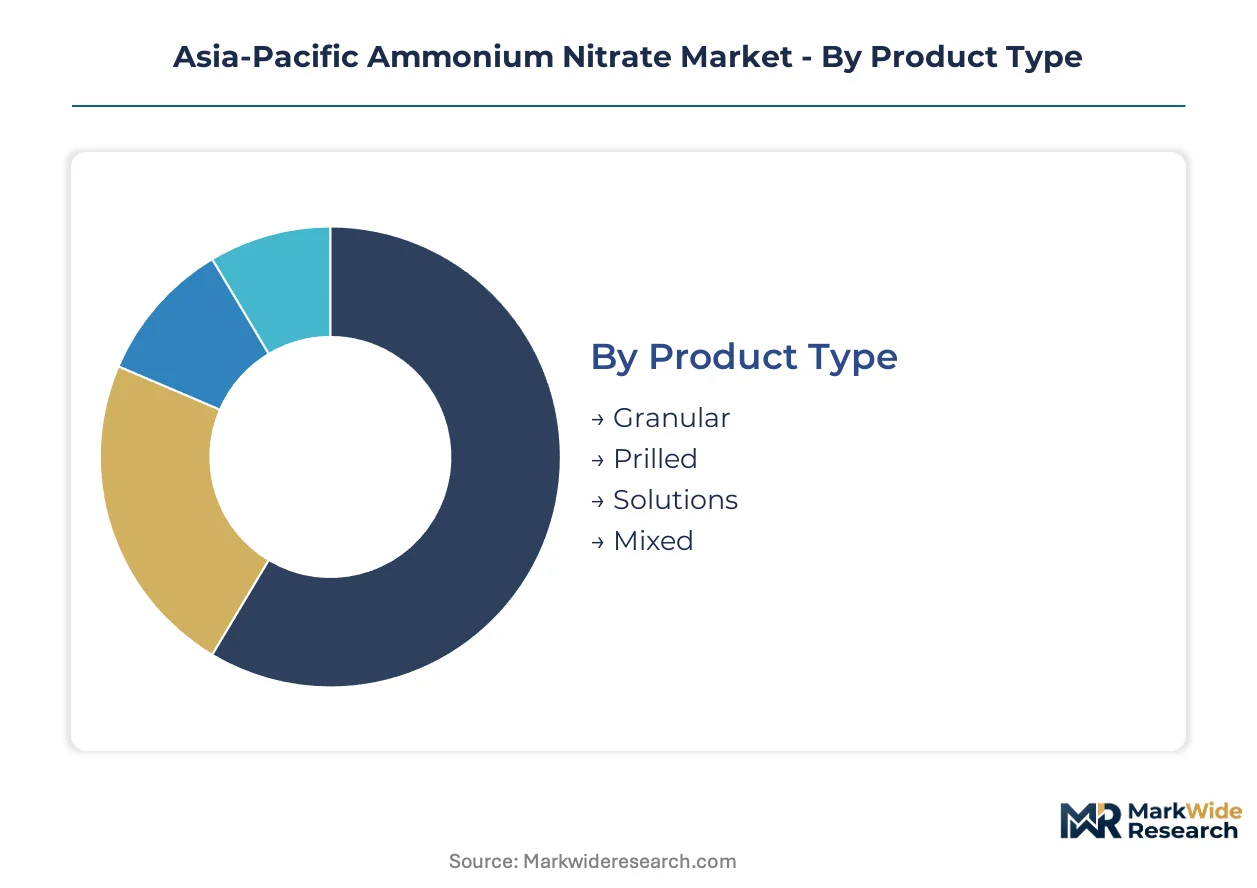
Segmentation across the Asia-Pacific ammonium nitrate market reveals how product specifications and procurement channels align with distinct buyer economics. Mining contractors prioritize handling characteristics and security compliance, while agricultural users optimize for nitrogen delivery cost per hectare.
Product Type:
Buyers differentiate primarily by bulk handling requirements and application equipment compatibility.
- Prilled:Spherical particles engineered for free-flowing behavior through pneumatic conveyors and bulk storage silos. Western Australia's Pilbara iron ore operations absorb substantial volumes through dedicated supply corridors serving Orica and Incitec Pivot blasting contracts.
- Solutions:Liquid ammonium nitrate concentrates blended with urea or micronutrients for fertigation systems. Indonesian palm oil plantations in Sumatra are converting from solid applications to precision delivery through drip irrigation networks.
- Granular:Dense crystalline form favored by Indian state fertilizer depots for mechanical spreading compatibility with smallholder equipment.
- Mixed:Compound formulations incorporating phosphate or potash for balanced NPK delivery in Vietnam's Mekong Delta rice cultivation.
Prilled product leads volumes today; solutions are gaining share fastest.
End User:
Procurement scale and regulatory exposure separate these buyer categories.
- Mining:Bulk explosives manufacturers and mine operators purchasing technical-grade material under dangerous goods protocols. Australia's AS 4326 compliance requirements restrict supplier pools to established domestic producers with security-sensitive substance infrastructure.
- Agriculture:Government procurement agencies and cooperative societies channeling subsidized fertilizer to smallholder farmers. India's nutrient-based subsidy scheme fixes maximum retail prices, compressing margins for manufacturers serving Uttar Pradesh and Punjab distribution networks.
- Explosives:Specialized industrial blasting contractors formulating ANFO and emulsion products for civil engineering and quarrying applications.
- Fertilizers:Blending facilities producing compound fertilizers for plantation and estate agriculture across Malaysia and Indonesia.
Mining dominates revenue concentration; agriculture sustains the widest geographic footprint.
Application:
Performance requirements and environmental sensitivity determine formulation selection.
- Ore Extraction:High-volume bulk blasting in open-pit operations demanding consistent oxidizer density and fuel oil absorption rates. Rio Tinto and BHP direct procurement contracts specify prilled ammonium nitrate with tight particle size distribution for Pilbara iron ore benches.
- Field Crops:Seasonal nitrogen top-dressing for wheat and rice in India's Indo-Gangetic Plain, with application timing tied to monsoon patterns and government procurement windows.
- Controlled Blasting:Precision fragmentation for infrastructure projects and urban quarrying, increasingly served by emulsion formulations displacing ANFO in noise-sensitive environments.
- Agricultural Fertilization:Basal and top-dressing applications across diverse cropping systems, with solution blends penetrating plantation sectors for fertigation compatibility.
Ore extraction commands premium pricing; controlled blasting faces substitution pressure from alternative formulations.
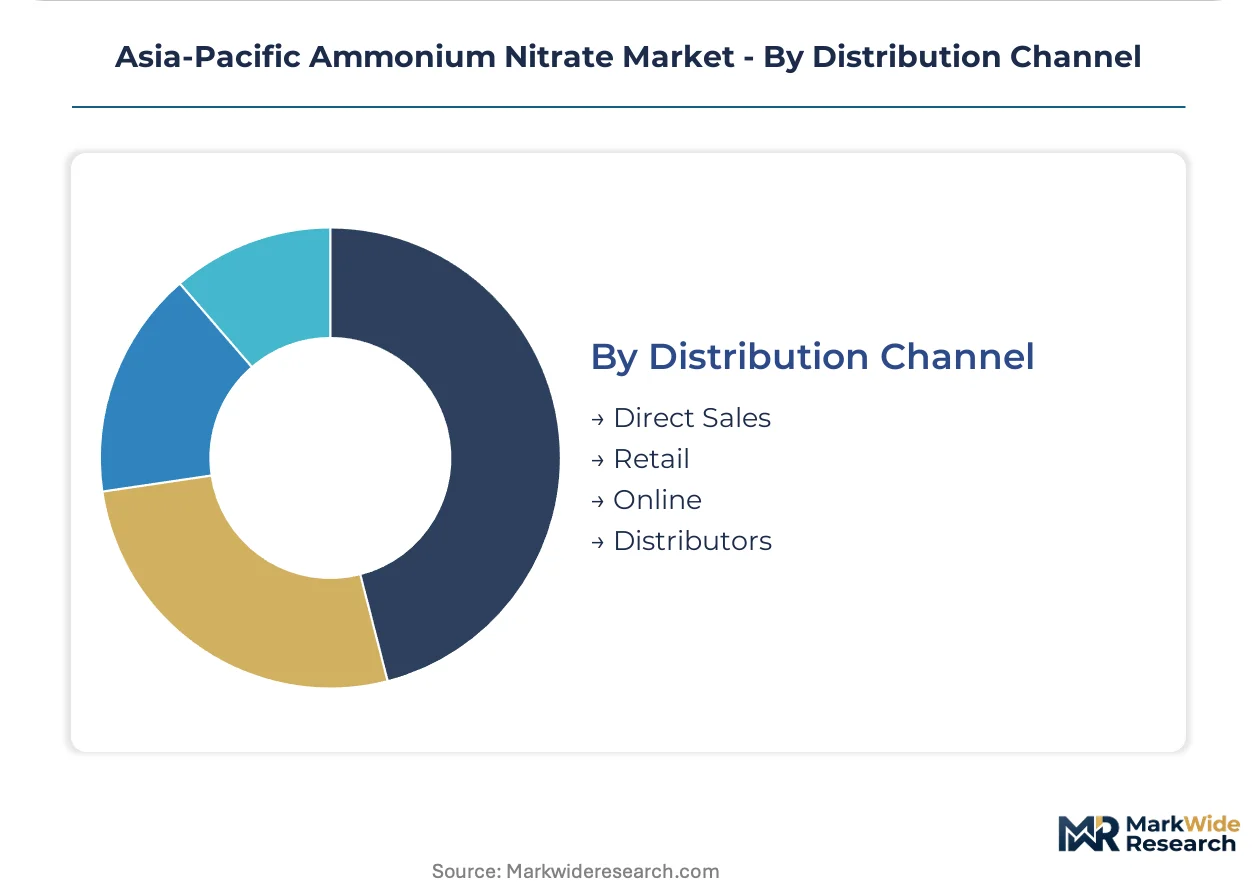
Distribution Channel:
Volume scale and technical service requirements shape channel selection.
- Direct Sales:Integrated supply agreements between manufacturers and mining majors, bundling ammonium nitrate with blasting services and technical support. Consolidated procurement by Australian iron ore operators has displaced fragmented distributor networks.
- Distributors:Regional stockists managing inventory and credit for agricultural markets, particularly in India's state-level fertilizer distribution systems.
- Retail:Cooperative societies and input dealers serving smallholder farmers with bagged product in last-mile rural networks.
- Online:Emerging digital platforms for agricultural inputs, currently limited by hazardous materials shipping restrictions and subsidy documentation requirements.
Direct sales capture the highest volume concentration; distributor networks retain critical importance in subsidized agricultural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions with lower compliance costs as China's MEE tightens emission caps, creating arbitrage opportunities for manufacturers in Australia and Southeast Asia willing to absorb displaced volume.
Australia
Western Australia's Pilbara iron ore belt consumes prilled ammonium nitrate through dedicated supply corridors serving integrated blasting contracts. The country's AS 4326 dangerous goods protocols restrict supplier pools to domestic producers with security-sensitive substance infrastructure. Queensland and New South Wales host manufacturing clusters where Orica and Incitec Pivot maintain coastal plants for export flexibility.
China
Shandong and Jiangsu provinces concentrate over half of regional nitric acid capacity, though MEE emission caps are forcing consolidation at larger coastal facilities. Smaller plants in Hebei and Henan face closure mandates, raising marginal production costs for technical-grade material. Surviving producers must install tertiary abatement systems, compressing margins on explosives-grade exports to Australian markets.
India
Uttar Pradesh and Punjab absorb subsidized fertilizer through the government's nutrient-based subsidy scheme, sustaining baseline agricultural demand. The CEA and Petroleum and Explosives Safety Organisation impose dual-track licensing for manufacturers serving both fertilizer and blasting sectors. Deepak Fertilisers anchors technical-grade production in Maharashtra for South Asian explosives markets.
Indonesia
Sulawesi and Halmahera nickel mining operations require increasing volumes of bulk blasting agents, creating demand nodes outside traditional consumption centers. Plantation operators in Sumatra are converting to liquid ammonium nitrate blends for fertigation compatibility. Emerging mining provinces face evolving environmental permit conditions for new nitrate plant approvals.
Vietnam
Bauxite and rare earth projects in the Central Highlands lack established explosives supply chains, opening first-mover positioning for technical-grade producers. The Mekong Delta rice cultivation absorbs mixed compound formulations through state procurement channels. Infrastructure build-out in northern mining districts lags behind mineral resource development timelines.
Asia-Pacific Ammonium Nitrate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision agriculture and carbon-capture differentiation to escape commodity pricing pressure. The market structures around three archetypes: integrated blasting service providers bundling chemical supply with drill-and-blast execution, standalone fertilizer manufacturers serving subsidized agricultural procurement channels, and technical-grade specialists supplying explosives formulators under dangerous goods protocols. Dominant competitive moves include direct procurement consolidation by Australian mining majors displacing distributor networks, and capacity relocation toward Southeast Asian jurisdictions with lighter emission compliance burdens.
Among Asia-Pacific-based operators, Orica Limited and Incitec Pivot exemplify the integrated blasting services archetype, while Deepak Fertilisers and Petrochemicals Corporation Ltd occupies a position within the technical-grade specialization tier. Yara International ASA represents the multinational fertilizer-major model with regional manufacturing footprints. These entities anchor distinct competitive vectors: Orica and Incitec Pivot through Australian dangerous goods infrastructure and mining relationships, Deepak Fertilisers through South Asian explosives licensing expertise, and Yara through global ammonia sourcing networks feeding regional nitrate production.
| Leading Market Players |
|---|
| Yara International ASA |
| Orica Limited |
| Incitec Pivot Limited |
| CF Industries Holdings Inc. |
| EuroChem Group |
| San Corporation |
| Deepak Fertilisers and Petrochemicals Corporation Ltd |
| Rashtriya Chemicals and Fertilizers Ltd |
| Sumitomo Chemical Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Skilled nitric acid plant operators concentrated in China's Shandong and Jiangsu provinces command wage premiums that widen pricing spreads between technical-grade explosives material and standard agricultural grades. Labor-cost differentials between coastal chemical clusters and inland fertilizer blending facilities translate into tiered product economics across the Asia-Pacific ammonium nitrate sector.
Pricing Analysis
Distributor margins on bagged agricultural product in India's Uttar Pradesh and Punjab distribution networks absorb the steepest channel economics, while direct-to-mine contracts for Pilbara iron ore operators bypass intermediary markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates AS 4326-compliant technical-grade material from subsidized fertilizer and unbranded commodity grades. Cost compression in standard agricultural tiers is intensifying because India's nutrient-based subsidy scheme fixes maximum retail prices regardless of input cost swings. Smallholder farmers in state procurement channels exhibit highest price sensitivity; Australian mining majors purchasing integrated blasting services show lowest.
Supply Chain Analysis
Empty bulk explosive containers and spent packaging from Australian mining sites flow back to Queensland and Newcastle plants for refurbishment and reuse under dangerous goods protocols. Nitric acid capacity concentrates in China, Australia, and India, with ammonia feedstock drawing from Middle Eastern and Southeast Asian LNG terminals. Natural gas price volatility at Singapore and Japanese import hubs creates margin instability for ammonia synthesis operations. Distribution runs through dedicated supply corridors for mining contracts and state depot networks for subsidized agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ammonium nitrate market functions as a regulatory compounder where China's MEE emission caps on nitric acid plants are restructuring production economics and forcing capacity consolidation that favors compliant manufacturers.
For Market Incumbents: Lock in AS 4326-compliant infrastructure advantages across Australian manufacturing assets before emerging Southeast Asian producers achieve dangerous goods certification parity. Prioritize backward integration into ammonia supply through long-term offtake agreements with Middle Eastern producers to hedge against LNG spot volatility threatening margin stability. Emulsion explosive substitution in Australian surface mining represents the most immediate demand threat requiring formulation diversification responses. For New Entrants and Emerging Players: The price-point gap between premium technical-grade explosives material and economy agricultural fertilizer creates entry space for mid-tier producers targeting Vietnam's Central Highlands bauxite projects. Vietnamese mining districts lack established explosives supply chains, making this geography the most penetrable white-space target. Pursue joint venture structures with Indonesian nickel operators in Sulawesi to secure anchor demand before domestic capacity expansion saturates regional supply. For Investors and Strategic Acquirers: Integrated blasting service providers are the most active acquirer in this space, consolidating chemical manufacturing with drill-and-blast execution capabilities to capture Scope 3 disclosure premiums from Australian mining contractors. Five-to-ten year viability hinges on carbon intensity positioning as European export markets impose embodied emissions standards. Target acquisition archetype: technical-grade specialists with explosives licensing expertise in underserved South Asian markets. Monitor green hydrogen ammonia pilot project announcements as the critical inflection signal for fossil-free production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Supply | Captive feedstock sourcing from Qatari or Saudi producers hedges against LNG spot volatility at Singapore terminals. |
| Carbon Capture Integration | Japanese trading house offtake agreements enable fossil-free ammonium nitrate premiums for European export markets. |
| Direct Procurement Consolidation | Rio Tinto and BHP bundling contracts displace fragmented distributor networks across Pilbara supply corridors. |
| Emulsion Formulation Diversification | Water-gel product lines defend against ANFO displacement in Australian noise-sensitive blasting applications. |
| Security-Sensitive Infrastructure Expansion | AS 4326 compliance investments create regulatory moats favoring established domestic Australian producers. |
Research Methodology
Coverage spans Australia, China, India, Indonesia, and Vietnam, with primary inputs from each market gathered through structured interviews with plant operations managers, procurement leads at iron ore majors, explosives licensing officials, and agricultural cooperative distributors. Secondary validation draws from MEE emission filings, Australian Dangerous Goods Code amendments, Indian Fertilizer Ministry subsidy notifications, and customs trade data on ammonia feedstock flows. Bottom-up volume modeling triangulates against top-down capacity assessments across regional nitric acid facilities.
Rate-of-change decomposition separates volume drivers by product grade tier, end-use industry concentration, and regional regulatory cluster intensity across the projection horizon. Segmentation dimensions modeled include prilled versus solution versus granular form factors, mining versus agriculture versus explosives end-use splits, and direct sales versus distributor versus retail channel economics. CAGRs derive from historical demand elasticity analysis applied to announced capacity additions and regulatory compliance timelines. Forecast inputs incorporate LNG price scenario modeling and MEE enforcement intensity assumptions for Chinese production clusters.
Caveats apply where MEE emission cap enforcement delays, Indonesian mining permit moratoriums, or Indian subsidy scheme revisions could materially shift the outlook beyond modeled parameters. Practitioners should monitor green hydrogen ammonia project commissioning announcements and Australian iron ore production guidance downgrades for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Ground Calcium Carbonate Market