
 Sintered Silencer Market | 2026-2036
Sintered Silencer Market Size, Share, and Industry Trends Forecast 2026-2036
Sintered Silencer Market Insights
China is rewriting capacity dynamics for porous metal components as domestic powder-metallurgy infrastructure scales to serve regional automotive and heavy-machinery supply chains. Boegger Industech Limited leverages in-house sintering capabilities to anchor European demand for high-temperature exhaust applications. Donaldson Company, Inc. competes through filtration-adjacent acoustic expertise, while Parker Hannifin Corporation extends its fluid-power distribution network into integrated silencer systems for off-highway OEMs.
A sintered silencer is a porous-metal acoustic attenuation device produced through powder compaction and high-temperature bonding, typically achieving pore sizes from 5 to 100 microns for controlled gas flow and noise reduction. Its primary purpose is to dissipate sound energy in pneumatic exhaust, engine blow-by, and compressed-air systems while maintaining minimal back-pressure. Stainless-steel engine silencers dominate current volume owing to thermal durability and corrosion resistance in automotive underhood environments. Exhaust silencers for heavy machinery represent the fastest-expanding application segment as construction-equipment OEMs pursue modular emission-and-noise packages. Aluminum acoustic silencers for aerospace occupy a concentrated margin pool where weight-critical specifications command premium positioning.
EPA noise-emission standards for stationary and mobile sources, Euro 7 regulatory frameworks under ECHA and EU-type approval bodies, and China's GB standards for environmental noise limit permissible sound levels and shape product certification requirements across major supply destinations. REACH compliance in Europe and evolving MEE enforcement in China are tightening material-traceability obligations for powder suppliers and finished-component exporters. Stakeholders must monitor regulatory divergence between emission-centric and noise-centric compliance pathways as dual-certification costs reshape sourcing decisions for cross-border OEM contracts.
Market Dynamics
Stainless-steel powder metallurgy is displacing conventional perforated-tube designs as Euro 7 and EPA mandates harden acoustic-attenuation requirements for elevated-temperature exhaust streams. Tier-1 automotive suppliers now specify sintered architectures that survive 800°C continuous operation.
Growth Catalysts
- Euro 7 noise-emission frameworks:ECHA and EU-type approval bodies are tightening permissible sound levels for passenger vehicles and heavy machinery, forcing OEMs toward porous-metal solutions with predictable acoustic impedance.
- Heavy-machinery modular packaging:Construction-equipment manufacturers in Germany and China are bundling emission-and-noise systems, creating specification pull for integrated sintered exhaust components.
- Stainless-steel powder compaction:Advances in high-temperature bonding are yielding pore-size distributions from 5 to 100 microns with minimal back-pressure penalty.
Market Restraints
- Nickel and chromium price volatility:Stainless-steel feedstock costs swing with LME trading patterns, compressing margin predictability for powder-metallurgy converters.
- German precision-manufacturing concentration:Critical sintering furnace capacity clusters in Baden-Württemberg and Bavaria, creating geographic supply risk for cross-border OEM contracts.
- Ceramic-fiber substitute threat:High-temperature insulation composites from aerospace suppliers are capturing niche applications where weight reduction outweighs thermal mass tolerance.
Strategic Opportunities
- India automotive expansion:BIS certification pathways and PLI scheme incentives for component manufacturing are opening specification windows for domestic powder-metallurgy entrants.
- Compressed-air system digitization:Industrial automation OEMs are integrating acoustic sensors with sintered silencers for predictive maintenance, creating hardware-software bundling potential.
- REACH material-traceability mandates:European powder suppliers with documented supply chains can capture premium positioning as ECHA enforcement tightens on heavy-metal content declarations.
Industry Challenges
- Sintering furnace operator scarcity:Specialized technicians capable of maintaining hydrogen-atmosphere integrity across 24-hour production cycles command wage premiums that inflate fixed costs.
- Dual-certification timeline compression:OEMs requiring simultaneous EPA and Euro 7 validation face extended prototype iterations that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sintered Silencer Market |
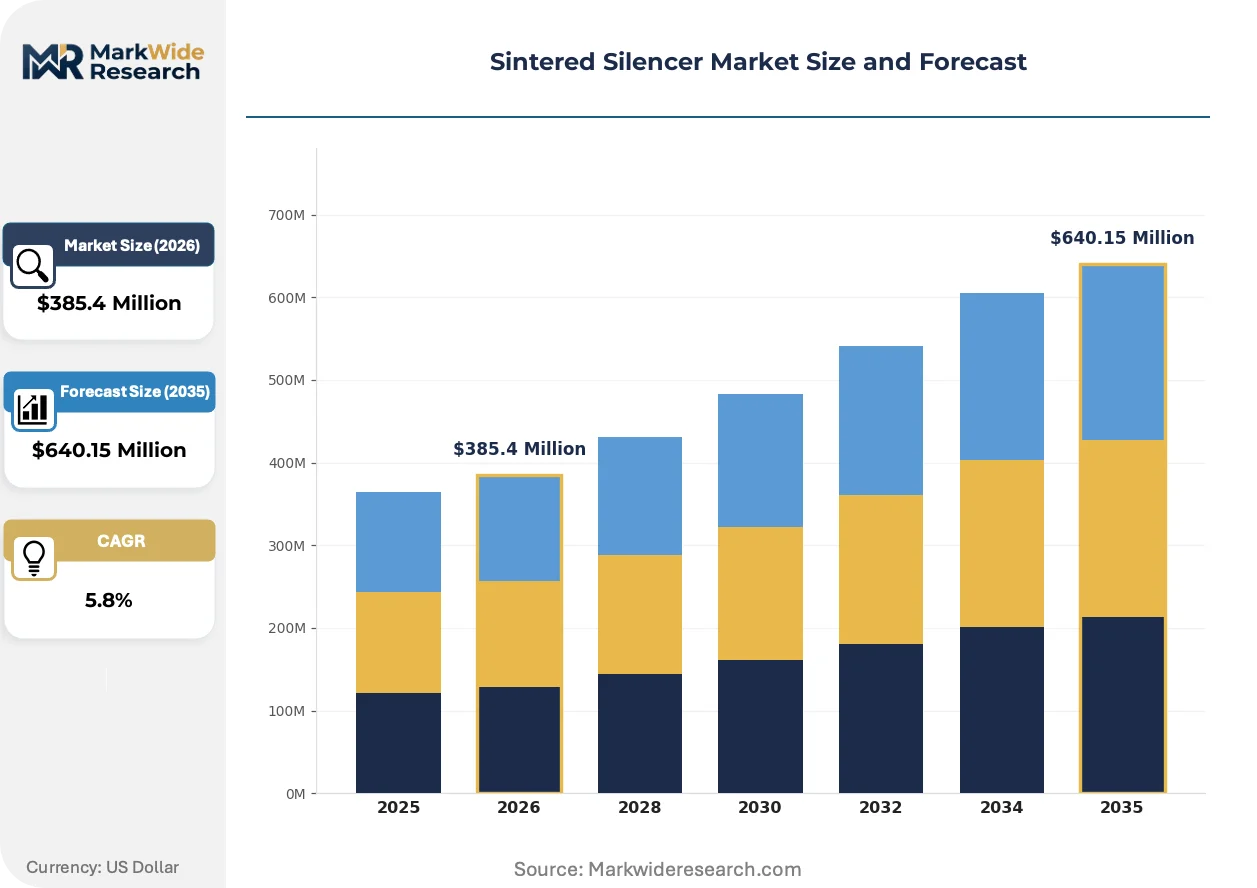
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Silencers, Exhaust Silencers, Industrial Silencers, Acoustic Silencers Material: Stainless Steel, Aluminum, Carbon Fiber, Composite Materials Application: Automotive, Aerospace, Heavy Machinery, Marine End User: Manufacturers, OEMs, Aftermarket Providers, Construction |
| Companies Covered | Boegger Industech Limited, Porvair Filtration Group, Royal Fluid Power Inc., Metallfilter AB, HENGKO Technology Co., Ltd., BLUE Sintered Filters, Donaldson Company, Inc., Parker Hannifin Corporation, Universal Silencer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sintered Silencer Market Trends and Innovations
Acoustic-performance modeling is migrating from empirical testing to simulation-driven design, compressing development cycles and enabling pore-architecture optimization before physical prototyping.
Additive-manufacturing integration is digitizing sintered silencer development. Binder-jet systems now produce complex internal geometries impossible with conventional die compaction. Aerospace OEMs in the United States are piloting topology-optimized acoustic channels that reduce weight by 30% versus pressed-powder equivalents. This capability is digitizing the boundary between prototype and production tooling.
REACH Annex XVII restrictions on nickel release are tightening material specifications for exhaust components sold into European markets. Powder suppliers must now document leach-test compliance across batch records. Stainless-steel grades with reduced nickel content are gaining share in passenger-vehicle applications where corrosion exposure is moderate.
Specification consolidation among construction-equipment OEMs is compressing supplier diversity. Buyers in China and Germany are reducing approved-vendor lists from twelve to four, demanding integrated acoustic-thermal packages rather than discrete silencer procurement. This pattern is visible most acutely in crawler-excavator and wheel-loader segments where modular subsystem sourcing dominates.
Sintered Silencer Market Segmentation
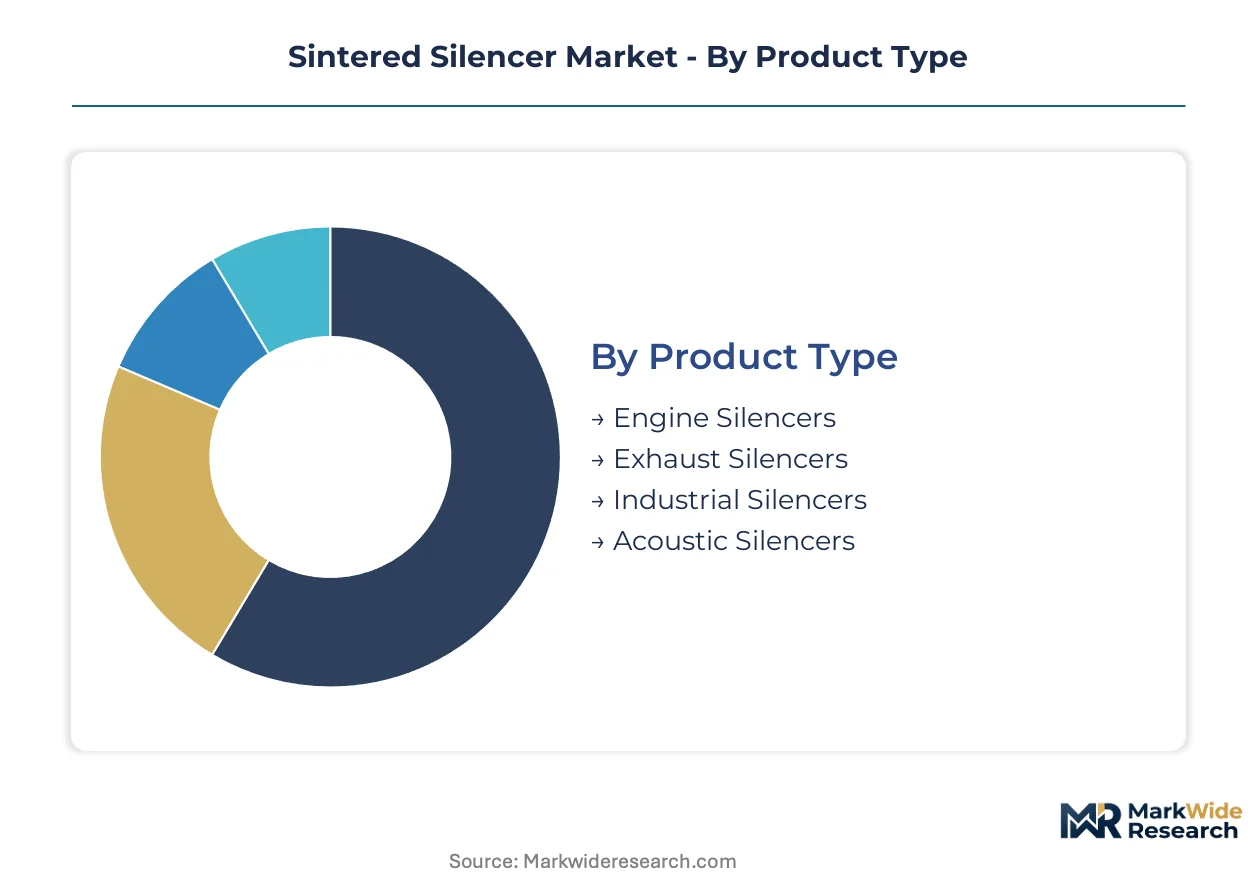
Sintered silencer architectures vary dramatically across thermal load, acoustic specification, and integration depth. Powder-metallurgy converters must align pore-size distribution and material grade with distinct certification pathways and end-use durability requirements.
Product Type:
The use-case spectrum spans underhood thermal management to open-environment exhaust routing, with each configuration demanding different sintering protocols and back-pressure tolerances.
- Engine Silencers:Stainless-steel powder compacts with 5–50 micron pore architectures manage blow-by gases and crankcase ventilation in passenger-vehicle powertrains. Demand concentrates in Germany and the United States where Euro 7 and EPA mandates enforce 800°C continuous-operation specifications.
- Exhaust Silencers:High-temperature sintered elements attenuate post-turbine noise in heavy-machinery and on-highway diesel systems. Construction-equipment OEMs in China are bundling these with aftertreatment modules, creating specification pull for integrated thermal-acoustic packages.
- Industrial Silencers:Compressed-air and pneumatic exhaust applications utilize coarser pore distributions for minimal flow restriction.
- Acoustic Silencers:Precision-tuned porosity serves aerospace cabin ventilation and medical gas systems where weight and frequency targeting dominate.
Established volume favors engine silencers; emerging adoption favors exhaust silencers as modular emission-and-noise packaging expands.
Material:
Cost tier and thermal ceiling dictate material selection, with nickel-content grades commanding premium positioning under tightening traceability mandates.
- Stainless Steel:Austenitic and ferritic grades dominate automotive underhood and exhaust-stream applications. REACH Annex XVII nickel-release restrictions are forcing formulation adjustments in European-bound components, with reduced-nickel grades gaining share in moderate-corrosion environments.
- Aluminum:Sintered aluminum offers 60% weight reduction versus steel equivalents for aerospace acoustic management. United States-based OEMs are piloting topology-optimized aluminum channels through binder-jet additive processes.
- Carbon Fiber:Ceramic-matrix composites capture niche thermal-insulation roles where mass reduction outweighs sintered-metal durability.
- Composite Materials:Hybrid ceramic-metal laminates serve specialized marine exhaust applications.
Stainless steel retains the broadest specification footprint; aluminum is climbing the fastest in aerospace procurement.
Application:
Customer type and certification intensity separate segments, with mobile-source regulations driving tighter integration than stationary equipment.
- Automotive:Passenger-vehicle and commercial-truck exhaust systems specify sintered architectures for predictable acoustic impedance under EPA and Euro 7 noise-emission ceilings.
- Aerospace:Weight-critical cabin and environmental control systems utilize aluminum sintered elements with documented batch-traceability for FAA certification.
- Heavy Machinery:Crawler excavators and wheel loaders in Germany and China are consolidating supplier lists around integrated acoustic-thermal subsystems.
- Marine:IMO noise guidelines and port-state emission controls shape specification for vessel engine-room silencers.
Automotive generates the highest unit volumes; heavy machinery shows the steepest expansion trajectory as construction-equipment modularization accelerates.
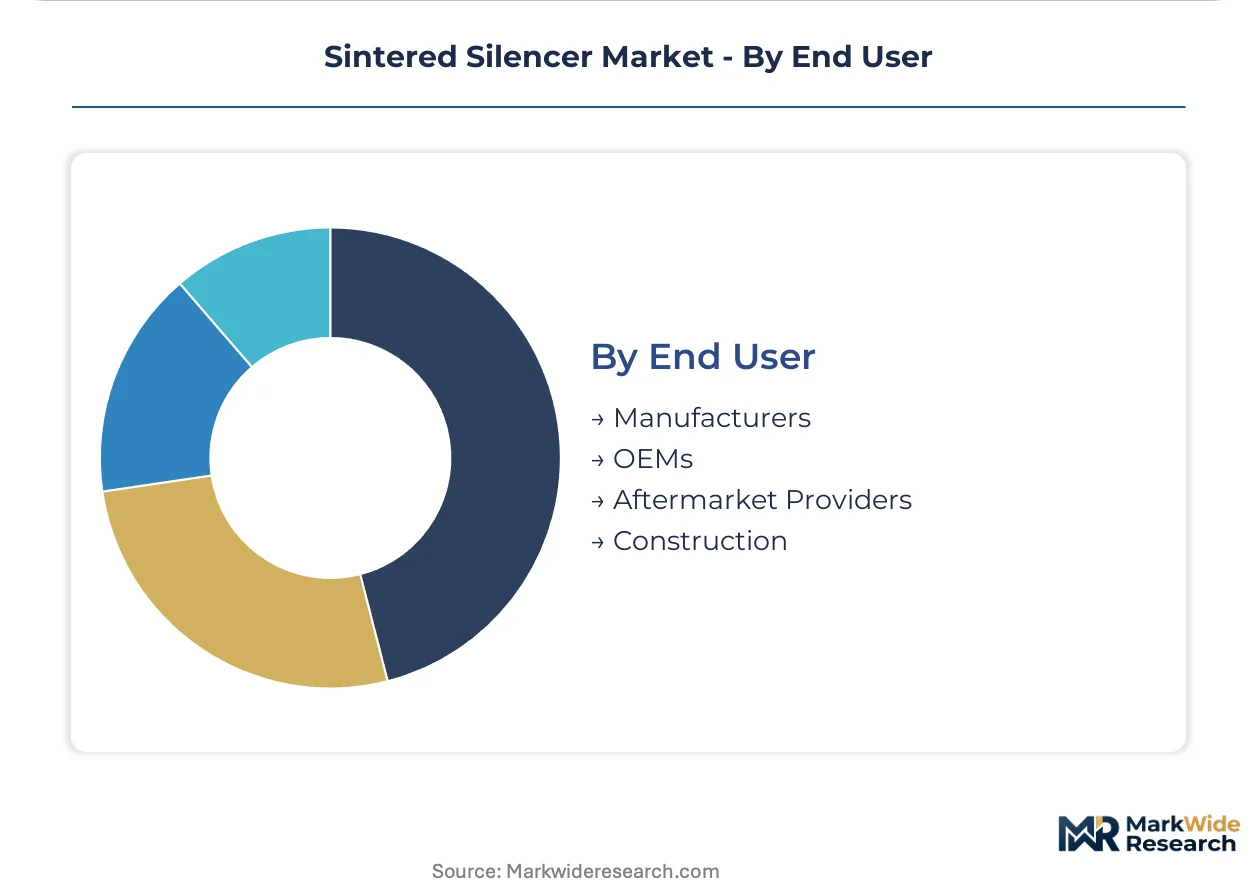
End User:
Procurement authority and design-integration depth determine margin structure, with captive manufacturing favoring long-term furnace contracts over spot purchasing.
- Manufacturers:Tier-1 powder-metallurgy specialists with in-house sintering capacity serve as specification gatekeepers for major OEM programs.
- OEMs:Integrated automotive and heavy-machinery builders are reducing approved-vendor lists from twelve to four, demanding subsystem-level acoustic-thermal packages rather than discrete silencer procurement.
- Aftermarket Providers:Replacement and retrofit channels serve aging equipment fleets with shorter lead-time tolerance.
- Construction:Project-based procurement of noise-attenuation packages for temporary equipment deployments.
OEM direct sourcing commands the deepest integration requirements; aftermarket providers offer the most price-sensitive demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sintered silencer manufacturing clusters in Baden-Württemberg and Bavaria dominate European capacity, while Chinese powder-metallurgy infrastructure scales rapidly to serve regional automotive supply chains. German precision-engineering centers and U.S. aerospace corridors anchor premium-tier demand.
Germany
Automotive exhaust-system mandates from KBA and Euro 7 frameworks drive specification pull for 800°C-rated stainless-steel components. ECHA enforcement on REACH Annex XVII nickel-release restrictions forces formulation adjustments in European-bound production. Stuttgart and Munich industrial corridors concentrate Tier-1 supplier relationships for integrated acoustic-thermal packages.
China
Domestic construction-equipment OEMs bundle emission-and-noise systems, creating demand for modular sintered exhaust architectures. GB standards for environmental noise and MEE enforcement tighten material-traceability obligations for powder suppliers. Yangtze River Delta manufacturing hubs scale in-house sintering capacity to serve regional heavy-machinery supply chains.
United States
EPA noise-emission standards for stationary and mobile sources shape certification requirements for automotive and industrial applications. FAA documentation protocols govern aerospace procurement of aluminum sintered elements for cabin ventilation systems. Michigan and Ohio automotive corridors anchor Tier-1 supplier relationships for underhood thermal management.
India
BIS certification pathways and PLI scheme incentives for component manufacturing open specification windows for domestic powder-metallurgy entrants. Automotive exhaust-system localization pressures create pull for regional stainless-steel silencer production. Maharashtra and Gujarat industrial clusters attract capacity investments from multinational Tier-1 suppliers.
Japan
METI industrial standards and JIS specifications govern precision porosity requirements for pneumatic and compressed-air applications. Automotive OEMs specify sintered architectures for predictable acoustic impedance in hybrid powertrain blow-by systems. Aichi Prefecture manufacturing corridors concentrate powder-metallurgy expertise for domestic and export supply.
Sintered Silencer Market Competitive Landscape
Integrated filtration conglomerates and specialized powder-metallurgy fabricators split the market along capability-depth lines. Tier-1 automotive programs favor suppliers with captive sintering furnace capacity and documented REACH batch-traceability, while industrial pneumatic applications tolerate shorter-lead-time spot purchasing. Three archetypes dominate: precision-engineering specialists with in-house high-temperature bonding, diversified filtration players leveraging acoustic-adjacent expertise, and regional powder-metallurgy converters serving construction-equipment modular packaging. Competitive dynamics center on geographic capacity expansion and strategic partnerships for dual-certification EPA-Euro 7 validation.
Among diversified filtration conglomerates, Donaldson Company, Inc. and Parker Hannifin Corporation exemplify archetypes extending adjacent acoustic expertise into integrated silencer systems. Boegger Industech Limited anchors European demand representation for high-temperature exhaust applications. These three occupy distinct positioning vectors: filtration-conglomerate scale, fluid-power distribution reach, and regional precision-engineering depth.
| Leading Market Players |
|---|
| Boegger Industech Limited |
| Porvair Filtration Group |
| Royal Fluid Power Inc. |
| Metallfilter AB |
| HENGKO Technology Co., Ltd. |
| BLUE Sintered Filters |
| Donaldson Company, Inc. |
| Parker Hannifin Corporation |
| Universal Silencer |
| Others |
Pricing and Supply Chain Analysis
Nickel and chromium price volatility on the London Metal Exchange determines both the spread between premium and standard-grade stainless-steel silencer tiers and the geographic clustering of sintering furnace capacity. Buyers facing feedstock cost swings compress procurement timelines, while suppliers with captive powder-metallurgy operations capture margin stability unavailable to spot-market converters.
Pricing Analysis
Euro 7 and EPA noise-emission mandates dictate the pricing tier structure across the sintered silencer market. Certification-grade differentiation separates REACH-compliant stainless-steel formulations for European-bound production from standard grades serving less regulated markets. Pricing pressure stems from construction-equipment OEMs consolidating approved-vendor lists and demanding integrated acoustic-thermal subsystems at bundled rates. Aftermarket providers exhibit the highest price sensitivity due to shorter lead-time tolerance and spot purchasing patterns, while aerospace procurement shows the least sensitivity given weight-critical specifications and documented batch-traceability requirements.
Supply Chain Analysis
Contract-manufacturing concentration rests with specialized powder-metallurgy converters in Germany, China, and the United States that maintain captive hydrogen-atmosphere sintering furnaces. Raw material dependencies center on austenitic and ferritic stainless-steel powders, nickel and chromium alloying elements, and aluminum feedstocks for aerospace applications. Single-source vulnerability characterizes the German precision-manufacturing corridor where Baden-Württemberg and Bavaria host critical furnace capacity. Distribution runs through Tier-1 automotive supplier networks and direct OEM procurement channels for integrated subsystem sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification pathways and application-specific thermal requirements creates niche positioning opportunities for specialists with documented compliance capabilities. Modular emission-and-noise packaging in heavy machinery is splitting demand pools that formerly consolidated around generalist suppliers.
For Market Incumbents: Insulate margin stability through backward integration into stainless-steel powder production and captive sintering furnace capacity additions in the Yangtze River Delta to serve Chinese construction-equipment OEMs. Ceramic-fiber substitutes from aerospace suppliers threaten niche high-temperature applications; counter by deepening REACH batch-traceability documentation and Euro 7 pre-certification investments that emerging competitors cannot replicate quickly. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified automotive exhaust segment where PLI scheme incentives and localization pressures create specification windows for domestic powder-metallurgy entrants. Compressed-air system digitization for predictive maintenance integration offers a hardware-software bundling angle with lower certification barriers than automotive exhaust applications. Target Tier-2 construction-equipment suppliers in Germany seeking alternatives to consolidated approved-vendor lists. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors precision-engineering specialists with in-house high-temperature bonding capabilities over diversified filtration conglomerates. Long-term viability across the next decade hinges on dual-certification EPA-Euro 7 validation capacity and documented supply chain traceability. Watch for inflection signals in nickel price volatility patterns and construction-equipment OEM modular packaging adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Investment | Simultaneous EPA and Euro 7 validation shortens OEM prototype cycles and deepens supplier relationships. |
| Backward Integration into Powder Production | In-house stainless-steel powder supply insulates margins from LME nickel and chromium price swings. |
| Additive Manufacturing Pilot Programs | Binder-jet topology optimization for aerospace aluminum channels reduces weight by thirty percent versus pressed equivalents. |
| REACH Traceability Documentation | Documented batch records for nickel-release compliance capture premium positioning as ECHA enforcement tightens. |
| Compressed-Air Sensor Integration | Acoustic sensor bundling with sintered silencers creates predictive maintenance revenue streams for industrial automation OEMs. |
Research Methodology
Cross-validation between primary interviews with powder-metallurgy plant managers, Tier-1 automotive procurement teams, aftermarket service heads, and ECHA regulatory affairs specialists anchors the qualitative findings. Secondary sources include customs and trade data for stainless-steel powder movements, SEC filings from diversified filtration conglomerates, KBA type-approval databases, and REACH Annex XVII restriction updates. Bottom-up demand modeling across engine, exhaust, industrial, and acoustic silencer segments triangulates against top-down macroeconomic indicators for automotive and heavy-machinery production.
Calibration against historical capacity utilization rates in German and Chinese sintering corridors validates the projection framework across the analysis window. Segmentation dimensions include product type, material grade, application vertical, and end-user procurement authority. CAGRs derive from regression analysis of regulatory mandate implementation timelines and OEM specification adoption curves. Industry-specific forecast inputs incorporate Euro 7 phase-in schedules and construction-equipment modular packaging adoption patterns.
Stress conditions across nickel price volatility bands, sintering furnace operator wage inflation, and dual-certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM supplier consolidation rates. Quarterly review of LME stainless-steel alloy pricing, KBA type-approval volumes, and Chinese construction-equipment production data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Tappet Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market