
 Global Floor Coatings Market | 2026-2036
Global Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Floor Coatings Market Foresight
Aftermarket maintenance revenue is rewriting profit distribution across the floor coatings value chain. PPG Industries Inc. leverages its architectural coatings network to capture recurring refurbishment contracts in North American commercial real estate. Sika AG anchors its position through captive supply of polyurethane resin systems and applicator training programs. AkzoNobel N.V. competes on decorative self-leveling platforms for European retail and hospitality interiors.
Global floor coatings encompass resin-based protective layers formulated from epoxy, polyurethane, or acrylic binders with film thickness typically ranging from 2 to 10 mils, designed to resist abrasion, chemical attack, and moisture ingress in high-traffic industrial and commercial substrates. Epoxy formulations dominate warehouse and laboratory installations where chemical resistance and load-bearing durability are paramount. Polyurethane segments lead decorative and anti-slip applications across sports facilities and exhibition halls due to superior UV stability and aesthetic flexibility. Water-based technologies are gaining formulation share in educational institutions and retail outlets as VOC regulations tighten across multiple jurisdictions.
REACH in Europe and EPA regulations in the United States mandate progressive reductions in solvent-based coating emissions, redirecting R&D investment toward water-based and cementitious alternatives. China's MEE enforces GB standards for industrial facility VOC discharge, shaping product registration requirements for imported coating systems. ISO 4624 and ASTM D7234 test protocols define adhesion and pull-off performance benchmarks that determine specification eligibility in commercial and government tenders. Stakeholders must monitor regulatory divergence between jurisdictions to align formulation portfolios with evolving compliance thresholds.
Market Dynamics
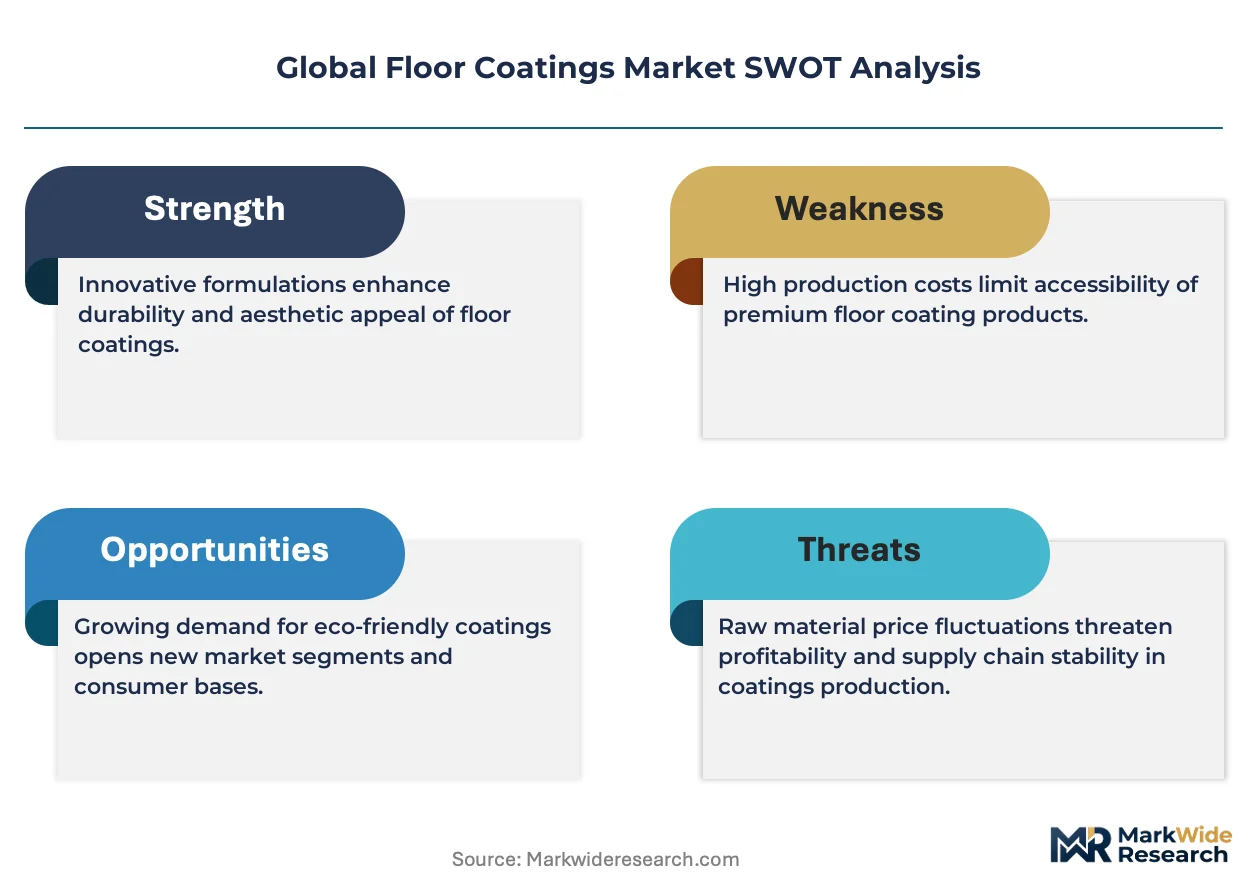
REACH-compliant low-VOC mandates are compressing solvent-based formulation margins while redirecting R&D budgets toward water-based and cementitious alternatives across European industrial warehousing.
Growth Catalysts
- Epoxy resin systems:Chemical resistance and load-bearing durability specifications in warehouse and laboratory installations are pulling demand toward high-performance epoxy formulations.
- REACH Phase 2 VOC limits:European regulatory pressure is accelerating formulation transitions that create first-mover advantages for compliant suppliers.
- Brazil:Manufacturing facility construction across Latin America is concentrating demand growth for polyurethane and acrylic floor protection systems.
Market Restraints
- Bisphenol A price volatility:Epoxy resin feedstock costs fluctuate with petrochemical supply disruptions, squeezing margin predictability for coating manufacturers.
- Chinese MEE enforcement:GB standards for industrial VOC discharge create product registration barriers that delay market entry for imported systems.
- Cementitious overlays:Lower-cost moisture-mitigation alternatives threaten specification share in light-traffic commercial applications.
Strategic Opportunities
- India:Manufacturing facility construction is outpacing domestic coating capacity, opening import and local production partnerships for polyurethane systems.
- Applicator certification networks:Captive training programs tied to resin supply create switching costs and recurring specification capture.
- UV-stable polyurethane:Sports facilities and exhibition halls are demanding aesthetic flexibility that epoxy cannot match, expanding addressable market scope.
Industry Challenges
- ISO 4624 adhesion testing:Certification timelines for pull-off performance benchmarks delay tender eligibility and compress project windows.
- Skilled applicator shortage:Self-leveling and decorative system installation requires specialized training that outpaces workforce development in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Floor Coatings Market |
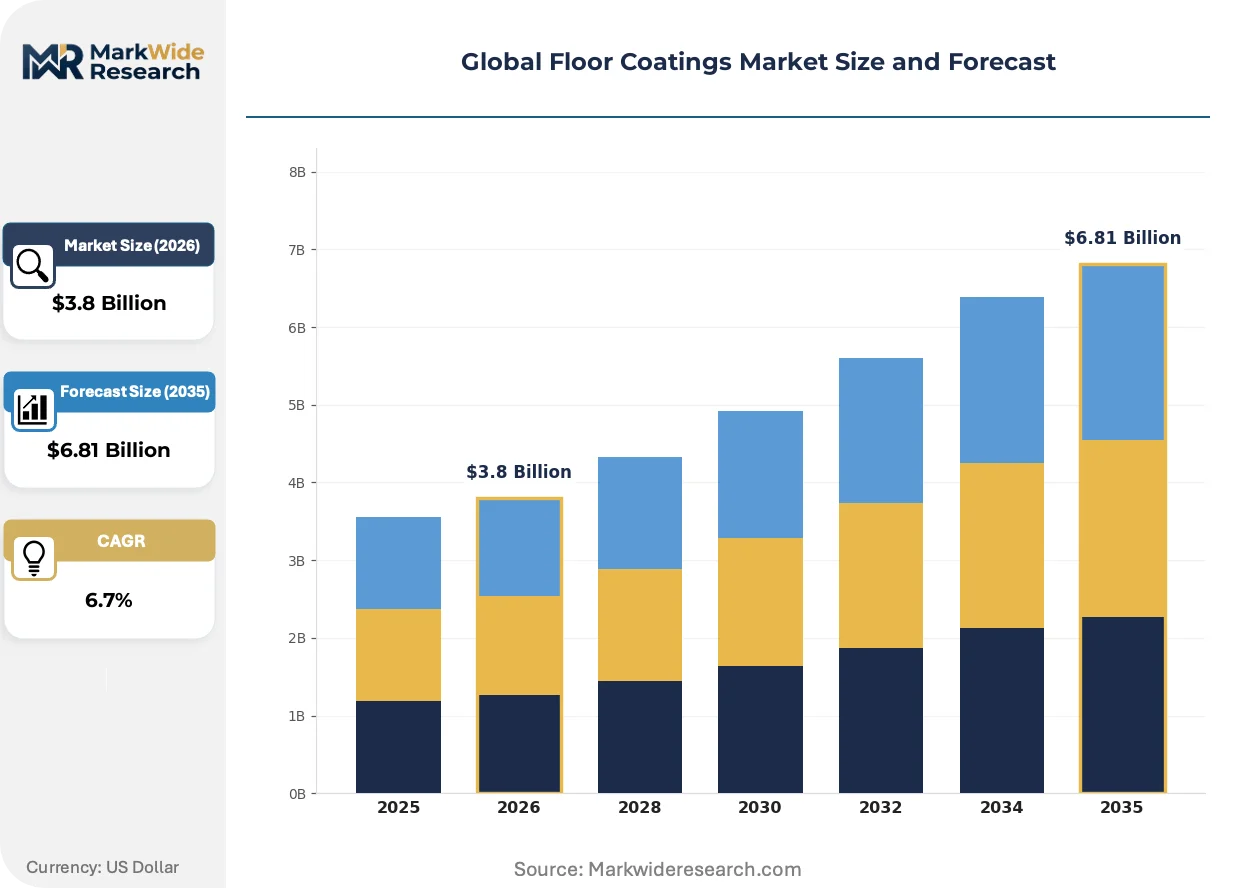
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Water-based, Solvent-based, Cementitious Application: Commercial Buildings, Warehouses, Sports Facilities, Exhibition Halls, Laboratories, Educational Institutions End User: Contractors, Facility Managers, Retail Outlets, Government Entities, Educational Facilities, Hospitality Providers Technology: Self-leveling, Decorative, Moisture Barrier, Anti-slip, Chemical Resistant, UV Resistant |
| Companies Covered | PPG Industries Inc., BASF SE, The Sherwin-Williams Company, RPM International Inc., AkzoNobel N.V., Sika AG, Asian Paints Limited, Jotun Group, Nippon Paint Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Floor Coatings Market Shifts & Advancements
Water-based formulation chemistry is overtaking solvent-borne systems as the dominant R&D trajectory, with regulatory compliance and worker safety converging to reset competitive positioning.
Polyaspartic aliphatic polyurea technology delivers rapid return-to-service cure times under four hours. Food processing and cold-storage facilities are adopting these systems to minimize operational downtime. Fast-cure chemistry is rendering obsolete traditional epoxy schedules that demand 72-hour cure windows.
EPA VOC emission standards for architectural coatings are tightening permissible solvent content in industrial maintenance categories. Coatings manufacturers are reformulating high-solids and water-reducible systems to maintain specification eligibility. Warehouse and logistics operators in the United States face compliance-driven product substitution pressures.
Facility managers are consolidating procurement through single-source maintenance contracts that bundle installation with scheduled refurbishment. Distributor-applicator relationships are displacing traditional material-only transactions. North American commercial real estate portfolios are pioneering this bundled service model.
Global Floor Coatings Market Segmentation
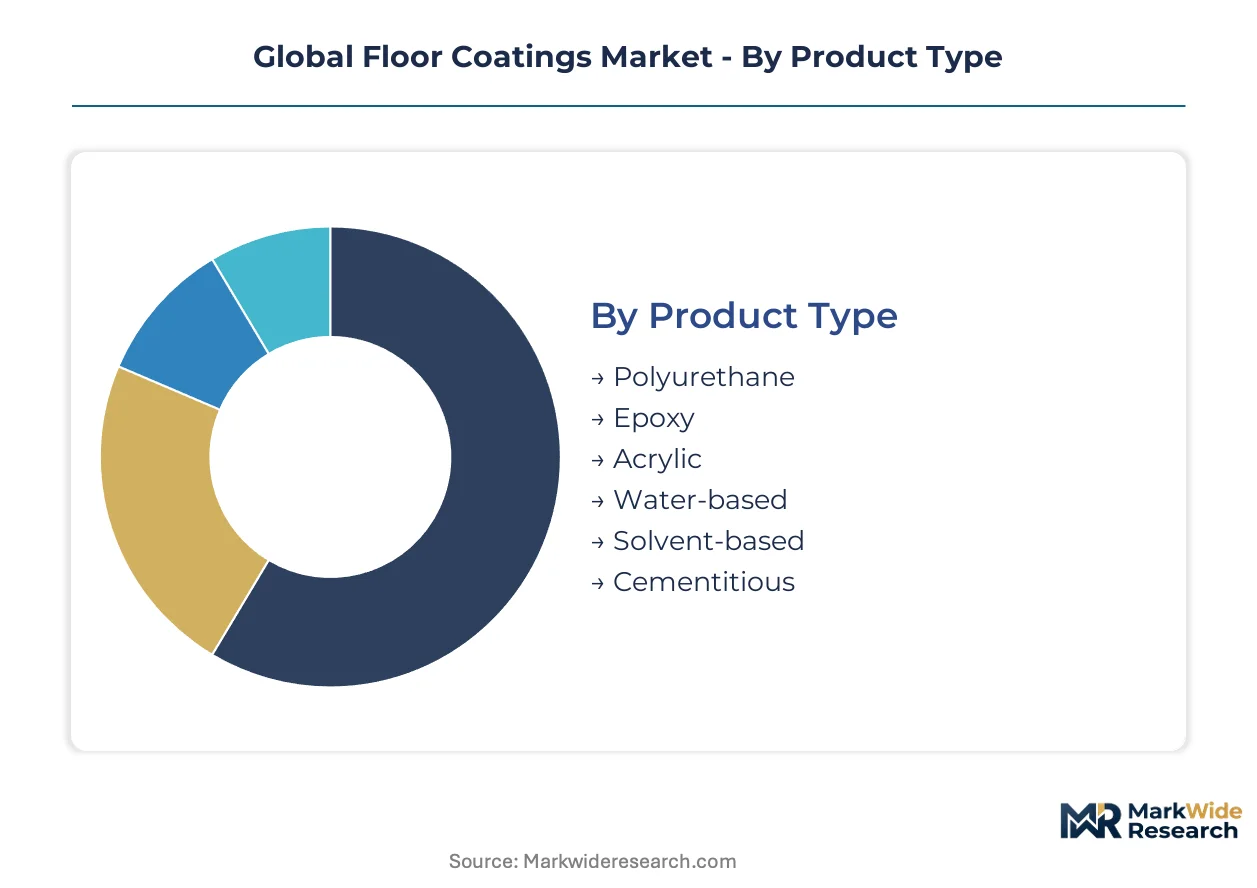
Floor coatings segmentation reveals how formulation chemistry, installation context, and buyer type reshape procurement patterns. Each dimension carries distinct margin profiles and specification barriers that determine competitive positioning across industrial and commercial substrates.
Product Type:
Mature epoxy and polyurethane formulations dominate specification sheets, while emerging water-based and cementitious alternatives capture regulatory-driven substitution.
- Epoxy:Thermosetting polymer systems built from bisphenol A and epichlorohydrin precursors deliver chemical resistance and compressive strength above 10,000 psi. German industrial warehousing under REACH Phase 2 mandates is pulling demand toward low-VOC epoxy variants as facility operators face compliance deadlines.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems offer superior UV stability and elongation properties for dynamic substrates. Sports facilities and exhibition halls in Brazil specify polyurethane for aesthetic flexibility and rapid return-to-service requirements.
- Acrylic:Thermoplastic resin systems provide cost-effective decorative finishes with moderate durability for light-traffic environments.
- Water-based:Emulsion polymer technology reduces VOC emissions below 50 g/L for educational institutions and retail outlets facing indoor air quality mandates.
- Solvent-based:High-solids alkyd and epoxy formulations retain specification in heavy industrial applications where cure speed and chemical resistance outweigh regulatory pressure.
- Cementitious:Polymer-modified Portland cement overlays deliver moisture mitigation and substrate repair at lower installed cost than resin systems.
Epoxy handles the majority of throughput; water-based is expanding most quickly on share as regulatory pressure intensifies.
Application:
Cost tier separation runs from premium laboratory specifications through economy-grade educational installations, with performance requirements determining formulation selection.
- Commercial Buildings:Mixed-traffic environments demand decorative self-leveling systems with abrasion resistance and aesthetic customization. North American commercial real estate portfolios are consolidating procurement through bundled installation and maintenance contracts.
- Warehouses:High-load industrial floors require epoxy or polyurethane systems with defined film thickness and compressive strength for forklift and pallet racking operations. China and India manufacturing facility construction is accelerating specification volume for chemical-resistant formulations.
- Sports Facilities:Polyurethane and acrylic systems provide shock absorption, ball rebound, and line-marking durability for multipurpose athletic surfaces.
- Exhibition Halls:Decorative metallic and flake broadcast systems prioritize visual impact and rapid installation turnover for temporary event programming.
- Laboratories:Chemical-resistant epoxy formulations with coved bases and integral drainage meet contamination control protocols.
- Educational Institutions:Water-based acrylic and epoxy systems balance durability, cost, and VOC compliance for classroom and corridor environments.
Warehouses command the largest installed base; sports facilities are climbing the fastest as leisure infrastructure investment expands.
End User:
Customer type determines procurement sophistication, from specification-engineered government tenders through price-sensitive retail direct purchasing.
- Contractors:Professional applicators source resin systems through distributor networks with bundled technical support and warranty backing. Applicator certification programs tied to polyurethane resin supply create switching costs and recurring specification capture.
- Facility Managers:Building operators prioritize lifecycle cost and scheduled refurbishment over initial installed price. North American commercial real estate portfolios are pioneering single-source maintenance contracts that bundle installation with refurbishment.
- Retail Outlets:Brand-conscious operators specify decorative self-leveling platforms for customer-facing environments with high visual impact requirements.
- Government Entities:Public procurement mandates ISO 4624 adhesion testing and ASTM D7234 pull-off performance benchmarks that delay tender eligibility.
- Educational Facilities:School districts and universities face budget constraints and indoor air quality regulations that favor water-based technologies.
- Hospitality Providers:Hotels and restaurants demand rapid-cure polyaspartic systems to minimize operational downtime during renovation cycles.
Contractors handle the majority of throughput; facility managers are gaining share fastest as bundled service models displace material-only transactions.
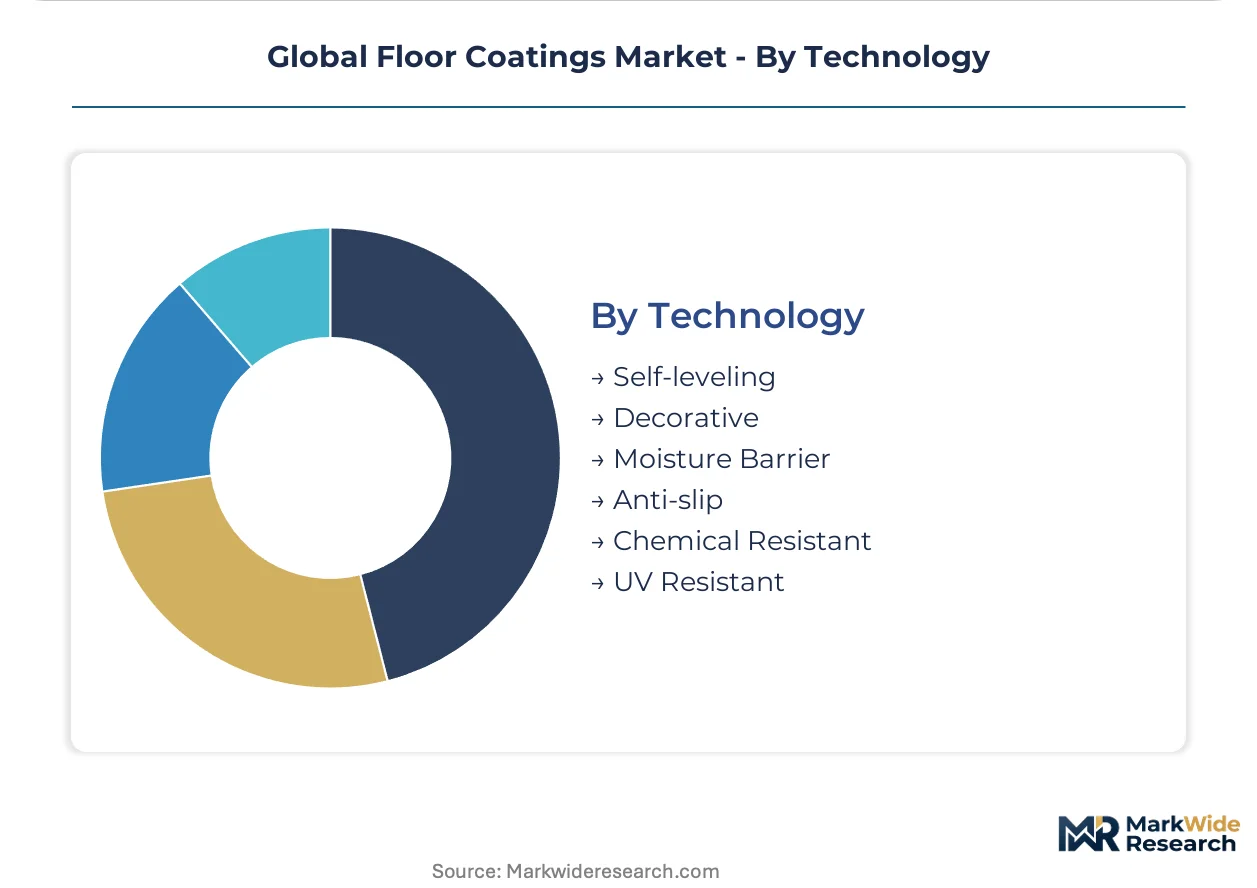
Technology:
Volume concentration sits with functional moisture and chemical barriers, while margin expansion follows decorative and UV-stable premium tiers.
- Self-leveling:Flow-applied epoxy and polyurethane systems create flat, seamless surfaces without trowel marks for aesthetic-critical environments. Skilled applicator shortage for self-leveling installation outpaces workforce development in emerging markets.
- Decorative:Metallic pigments, color quartz, and vinyl flake broadcast systems deliver branded visual environments for retail and hospitality.
- Moisture Barrier:Cementitious and epoxy-based vapor emission control systems protect flooring from alkaline salt damage and adhesive failure.
- Anti-slip:Aggregate broadcast and textured finish technologies reduce slip resistance values for wet environments in food processing and commercial kitchens.
- Chemical Resistant:High-crosslink density epoxy formulations withstand acids, alkalis, and solvents in laboratory and manufacturing settings.
- UV Resistant:Aliphatic polyurethane and polyaspartic chemistry prevents yellowing and chalking in daylight-exposed atriums and entrance areas.
Self-leveling commands the largest installation volume; UV-resistant is gaining share fastest as daylighting design expands in commercial architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial warehousing consumes epoxy formulations for chemical resistance, while Brazilian manufacturing facilities specify polyurethane for rapid return-to-service requirements. This consumption-mix differential reflects divergent facility priorities across geographies.
Germany
Industrial warehousing operators in North Rhine-Westphalia and Bavaria are expanding epoxy installations under ECHA REACH Phase 2 VOC limits. German regulators mandate progressive solvent reductions, redirecting procurement toward water-based and cementitious alternatives. The Ruhr industrial cluster sees facility operators facing compliance deadlines for low-VOC warehouse flooring specifications.
United States
Commercial real estate portfolios across the Southeast and Midwest are consolidating procurement through bundled installation and maintenance contracts. EPA emission standards for architectural coatings tighten permissible solvent content in industrial maintenance categories. Dallas-Fort Worth logistics hubs drive specification volume for high-solids epoxy systems in distribution center construction.
China
Manufacturing facility construction in the Yangtze River Delta and Pearl River Delta accelerates demand for chemical-resistant polyurethane systems. China's MEE enforces GB standards for industrial VOC discharge, shaping product registration requirements for imported coating systems. Shanghai industrial parks specify epoxy formulations for electronics manufacturing cleanroom environments.
Brazil
Manufacturing facility construction across São Paulo and Minas Gerais concentrates demand growth for polyurethane and acrylic floor protection systems. ANVISA regulations align with international chemical safety protocols for industrial facility coatings. The Campinas industrial corridor sees sports facilities and exhibition halls specifying UV-stable polyurethane for aesthetic flexibility requirements.
India
Manufacturing facility construction in Maharashtra and Gujarat outpaces domestic coating capacity, opening import partnerships for polyurethane systems. BIS certification requirements create specification barriers for foreign suppliers entering government tenders. The Pune-Chakan automotive belt demands rapid-cure epoxy systems for assembly plant flooring installations.
Global Floor Coatings Market Competitive Landscape
Capability concentration sits with resin system specialists possessing captive polyurethane chemistry and applicator training infrastructure; scale advantage sits with diversified coatings conglomerates leveraging architectural distribution networks. The vendor base organizes around three strategic archetypes: integrated resin-coating manufacturers, regional formulation specialists, and distributor-applicator networks. Dominant competitive moves include backward integration into resin supply chains and geographic expansion through local production partnerships.
Within the diversified coatings tier, PPG Industries Inc. and AkzoNobel N.V. occupy positions defined by architectural coatings network leverage and decorative platform development. Sika AG exemplifies the resin-integrated specialist archetype through captive polyurethane systems and applicator certification programs. These three entities represent distinct competitive vectors: network scale, formulation integration, and technical service capture.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| BASF SE |
| The Sherwin-Williams Company |
| RPM International Inc. |
| AkzoNobel N.V. |
| Sika AG |
| Asian Paints Limited |
| Jotun Group |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp chemical corridor freight costs cascade through bisphenol A and isocyanate supply chains, compressing margins for epoxy and polyurethane formulators while amplifying price spreads between REACH-compliant European production and import-dependent Asian markets.
Pricing Analysis
Long-term offtake agreements dominate procurement for industrial warehousing operators, while project-based spot purchasing serves exhibition hall and retail renovation cycles. Three-tier pricing structure across premium, standard, and economy levels separates ISO 4624-certified systems from basic moisture-barrier formulations. Pricing pressure stems from cementitious overlay substitution in light-traffic commercial segments. Facility managers show lowest price sensitivity due to lifecycle cost framing, while educational institutions face acute budget constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize distributor relationships with applicator networks, particularly for decorative self-leveling systems. Germany, China, and the United States anchor resin production concentration. Epoxy formulations draw from bisphenol A and epichlorohydrin feedstocks; polyurethane systems rest on MDI and polyol precursors. Single-source vulnerability runs through specialty aliphatic isocyanates for UV-stable grades. Distribution runs through certified applicator networks with captive training programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled applicator scarcity for self-leveling and decorative system installation outpaces workforce development, constraining capacity expansion and fragmenting service quality across emerging markets.
For Market Incumbents: Entrench specification capture through captive applicator certification programs tied to polyurethane resin supply. Deepen backward integration into MDI and polyol production to insulate margins from petrochemical volatility. Cementitious overlay encroachment in light-traffic commercial applications demands defensive R&D into hybrid cementitious-epoxy systems.
For New Entrants and Emerging Players: Pursue import partnerships and local production joint ventures in Maharashtra and Gujarat, where manufacturing facility construction outpaces domestic coating capacity. Water-based formulation gaps in educational institutions and retail outlets present the most penetrable white space. Lead with MEE pre-registration and BIS certification to accelerate tender eligibility.
For Investors and Strategic Acquirers: Resin-integrated specialists with captive polyurethane chemistry and applicator training infrastructure represent the most defensible acquisition archetype. Long-term viability hinges on regulatory compliance agility across REACH, EPA, and GB standard convergence. Watch for polyaspartic aliphatic polyurea adoption inflection in food processing and cold-storage facilities as rapid-cure technology displaces traditional epoxy schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive MDI and polyol production insulates margins from bisphenol A price volatility. |
| Applicator Certification Network Expansion | Sika AG's training programs create switching costs and recurring specification capture across European warehousing. |
| Water-Based Formulation Transition | REACH Phase 2 and EPA emission standards redirect R&D toward sub-50 g/L VOC alternatives. |
| Polyaspartic Technology Licensing | Sub-four-hour cure times render 72-hour epoxy schedules obsolete in food processing facilities. |
| Local Production Partnership in India | Maharashtra and Gujarat manufacturing construction outpaces domestic coating capacity. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at industrial warehousing operators, procurement leads at commercial real estate portfolios, technical R&D directors at resin manufacturers, and certified applicator network heads, then refined through secondary validation against ECHA REACH compliance databases, EPA emission standard filings, Chinese MEE GB standard registrations, and customs trade data for bisphenol A and isocyanate flows. Bottom-up volume triangulation across formulation chemistry segments was cross-checked against top-down market sizing from architectural coatings distribution networks.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeling across epoxy, polyurethane, acrylic, water-based, and cementitious chemistry tiers; warehouse, commercial building, sports facility, and laboratory application contexts; and contractor, facility manager, and government entity end-user archetypes. CAGRs were derived from installed base growth, refurbishment cycle frequency, and regulatory substitution elasticity. Forecast inputs incorporated REACH Phase 2 compliance deadlines and MEE enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in industrial construction investment, petrochemical feedstock costs, or currency volatility in Brazil and India would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and applicator workforce development rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Protective Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
E-Coat Market
Coatings
Coatings Raw Materials Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Yacht Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Gelcoat Market
Coatings
Clear Coatings Market
Coatings
Polyester Coatings Market
Coatings
Glass Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Fluoropolymer Coating Market