
 Asia-Pacific Light and Very Light Jets Market | 2026-2036
Asia-Pacific Light and Very Light Jets Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Light and Very Light Jets Market Outlook
Aftermarket service revenue is tilting toward engine overhaul and avionics retrofit centers as fleet ages across the region. Embraer SA leverages its established Phenom service network to capture recurring maintenance streams. Honda Aircraft Company differentiates through its HA-420 HondaJet's over-the-wing engine mount design, which sustains competitive operating economics on thin routes. Textron Inc. dominates the light-twin segment with Cessna CitationJet variants that anchor charter operator procurement cycles.
Asia-Pacific light and very light jets encompass fixed-wing aircraft with maximum takeoff weights below roughly 10,000 kilograms, typically seating four to eight passengers and employing turbofan or turboprop propulsion for missions of 1,500 to 3,000 nautical miles. These platforms serve point-to-point business mobility, medical evacuation, and owner-flown transportation where scheduled airline frequency remains inadequate. Light Jets command the largest installed base among aircraft type segments, while Very Light Jets represent the fastest-growing category as owner-pilot regulations relax in Indonesia and Malaysia. Charter Operators lead end user demand, though Corporate Clients are shifting toward managed fleet structures rather than outright ownership.
Civil Aviation Safety Authority Australia, India's Directorate General of Civil Aviation, and Civil Aviation Authority of New Zealand enforce type certification and operational standards that dictate avionics equipage timelines and pilot qualification thresholds. These frameworks compress market access for uncertified platforms while accelerating retrofit demand for ADS-B Out and performance-based navigation compliance. Stakeholders must monitor regulatory divergence between ASEAN member states as bilateral recognition agreements mature or fragment.
Market Dynamics
Fractional ownership programs are compressing capital deployment cycles for corporate flight departments across Southeast Asia and Australia, while India's DGCA certification reforms accelerate type-approval velocity for imported platforms.
Growth Catalysts
- Regulatory Streamlining:India's DGCA reforms compress type-approval timelines for imported aircraft, reducing market entry friction for foreign OEMs.
- Fractional Ownership Expansion:Corporate flight departments in Australia and Southeast Asia deploy capital-light fleet access models that expand addressable demand beyond traditional full-ownership buyers.
- Owner-Pilot Liberalization:Relaxed regulations in Indonesia and Malaysia enable single-pilot operations for very light jets, unlocking owner-flown transportation segments.
Market Restraints
- Aviation Fuel Price Volatility:Jet A-1 cost fluctuations strain operating economics for thin-route operators across the region's archipelagic geographies.
- Pilot Qualification Thresholds:Civil Aviation Safety Authority Australia mandates instrument rating upgrades that extend crew training timelines and elevate labor costs.
- Airport Infrastructure Gaps:Limited FBO capacity at secondary airfields in the Philippines and Vietnam constrains point-to-point mission feasibility.
Strategic Opportunities
- Medical Evacuation Expansion:Australia's remote mining corridors and Indonesia's island chains generate underpenetrated demand for rapid patient transport configurations.
- ADS-B Out Retrofit Mandates:Performance-based navigation compliance deadlines across ASEAN states create aftermarket avionics upgrade revenue streams.
- Charter Operator Consolidation:Managed fleet structures displace outright ownership among corporate clients, opening recurring revenue models for fleet management providers.
Industry Challenges
- Certification Timeline Compression:Bilateral recognition agreements between ASEAN regulators fragment type-approval reciprocity, forcing redundant documentation for cross-border operations.
- Maintenance Technician Scarcity:Turbofan engine overhaul specialization concentrates in Singapore and Australia, creating service access bottlenecks for dispersed Pacific island operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Light and Very Light Jets Market |
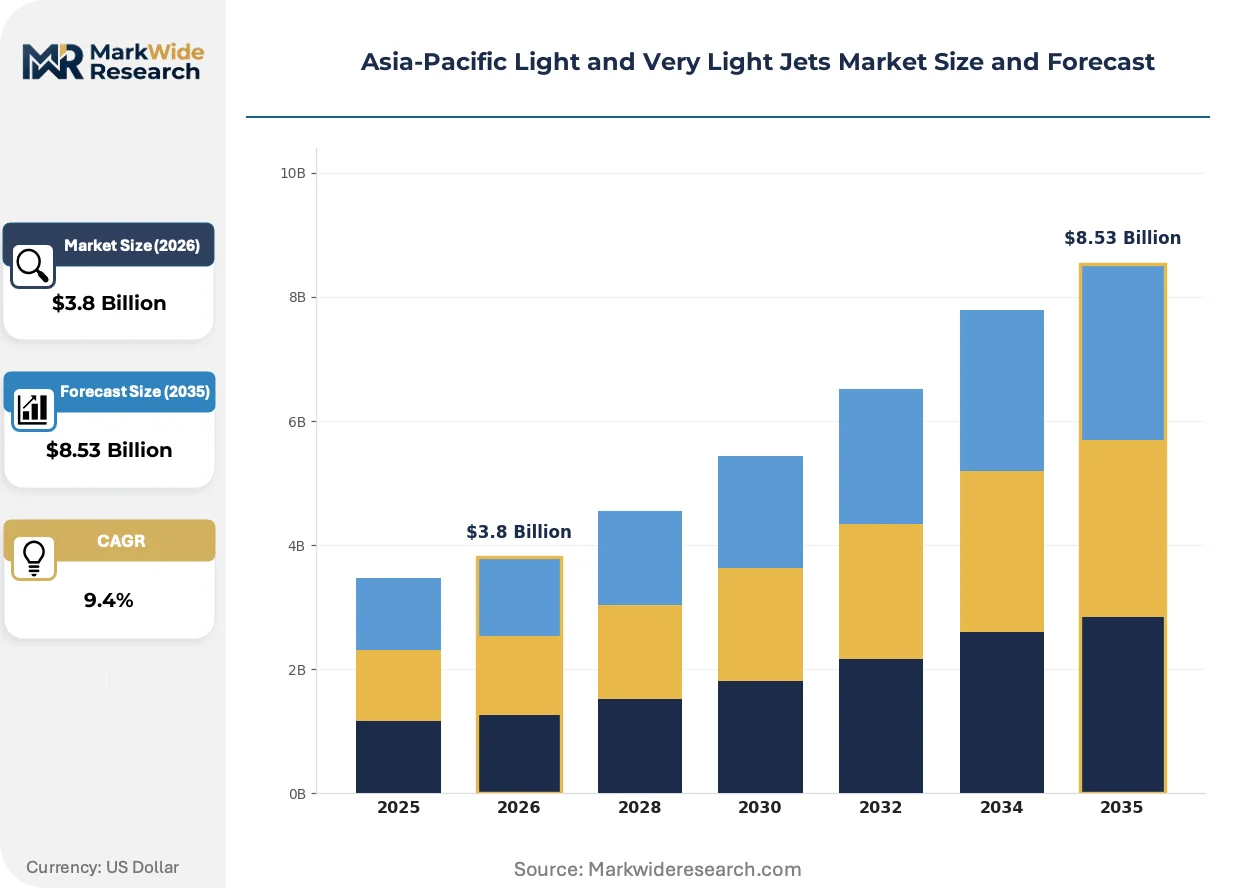
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Very Light Jets, Twin Engine Jets, Single Engine Jets End User: Private Owners, Charter Operators, Corporate Clients, Government Agencies Application: Business Travel, Air Ambulance, Cargo Transport, Recreational Use Operational Range: Short Range, Medium Range, Ultra Short Range, Long Range |
| Companies Covered | Embraer SA, Honda Aircraft Company, Textron Inc., Pilatus Aircraft Ltd, Bombardier Inc., Cirrus Design Corporation, Diamond Aircraft Industries, Daher, Piper Aircraft, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Light and Very Light Jets Market Strategic Shifts
Digital avionics architectures and sustainable aviation fuel pathways are restructuring fleet economics and operational compliance frameworks across Asia-Pacific business aviation networks.
Integrated flight deck systems with synthetic vision and touchscreen interfaces are collapsing pilot workload requirements for single-pilot certified platforms. Charter operators in Australia's Gold Coast-to-Sydney corridor adopt these configurations fastest, compressing training costs and expanding the addressable pilot labor pool for thin-route missions.
Performance-based navigation mandates from Civil Aviation Authority of New Zealand and Australia's CASA are accelerating avionics retrofit cycles across legacy light jet fleets. Operators must equip for ADS-B Out and RNP approaches by specified deadlines or face airspace access restrictions, channeling maintenance expenditure toward digital cockpit upgrades rather than airframe heavy maintenance.
Corporate flight departments now favor managed access agreements over outright airframe ownership, unbundling capital commitment from utilization rights. This behavioral pivot concentrates fleet purchasing power with specialized management companies in India's Delhi-Mumbai triangle, displacing traditional owner-operator procurement patterns and compressing sales cycles for OEM direct channels.
Asia-Pacific Light and Very Light Jets Market Segmentation
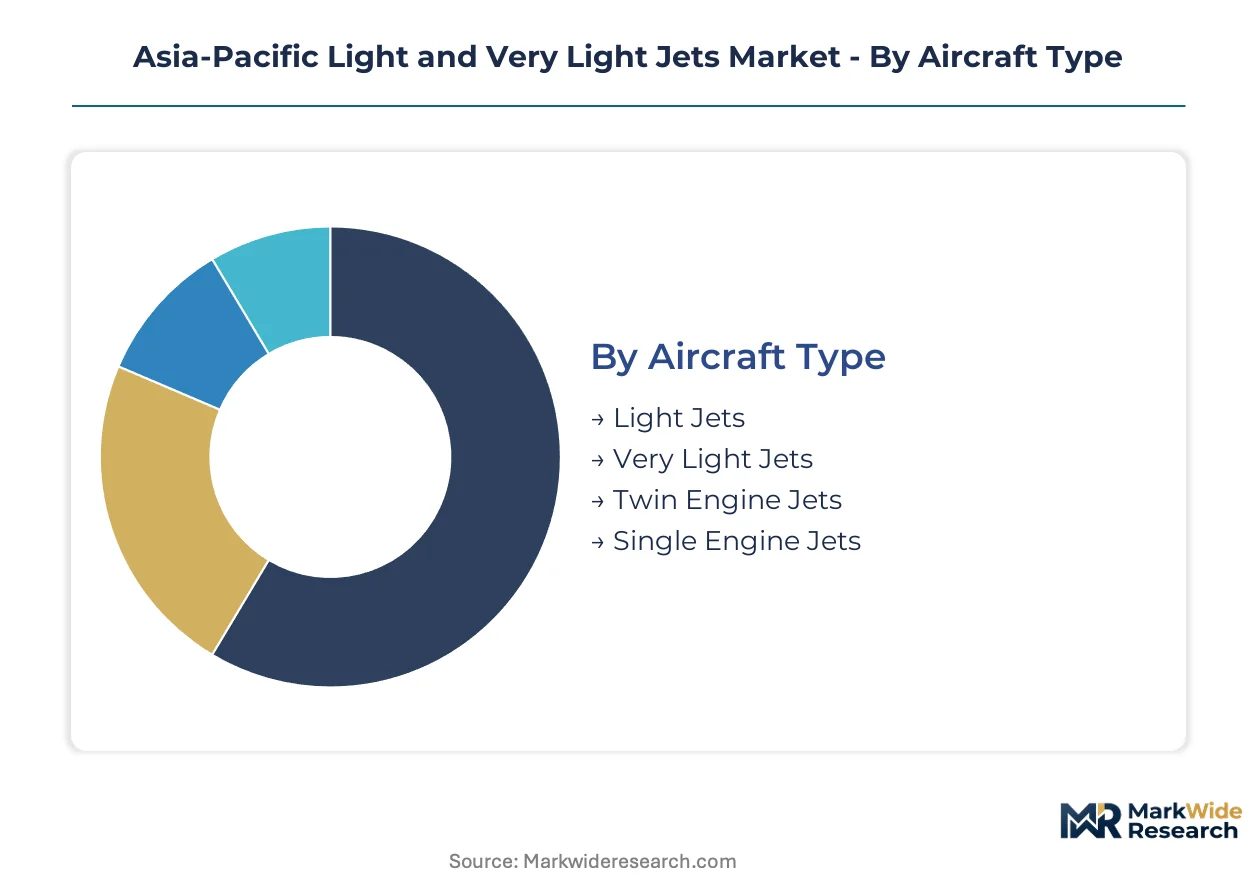
Segmentation in Asia-Pacific light and very light jets reveals distinct procurement cycles and utilization patterns across aircraft configurations and mission profiles. Fleet turnover velocity varies dramatically between owner-flown platforms and high-utilization charter assets, shaping aftermarket revenue concentration and OEM direct sales strategies.
Aircraft Type:
Replacement cycles diverge sharply across this category, with high-cycle charter platforms turning over in under eight years while owner-flown assets often exceed fifteen-year service lives.
- Light Jets:These platforms carry maximum takeoff weights between roughly 10,000 and 12,500 pounds, typically seating six to eight passengers with ranges extending to 2,000 nautical miles. Australia's Gold Coast-to-Sydney corridor operators favor these aircraft for their payload flexibility on thin business routes, though India's DGCA certification timelines for imported units create procurement bottlenecks.
- Very Light Jets:Maximum takeoff weights below approximately 10,000 pounds define this segment, with four-to-six passenger configurations and single-pilot operational capability. Indonesia's relaxed owner-pilot regulations and Malaysia's liberalized single-pilot certification are accelerating fleet expansion for personal transportation missions across Southeast Asian archipelagos.
- Twin Engine Jets:Redundant propulsion systems command premium positioning for over-water operations and mountainous terrain penetration.
- Single Engine Jets:Simplified maintenance profiles and lower direct operating costs attract cost-sensitive owner-operators in emerging Southeast Asian markets.
Light Jets anchor the volume base while Very Light Jets gain share at the steepest rate.
End User:
Capital deployment intensity separates these segments, with corporate clients committing multi-airframe orders while private owners concentrate purchasing power in single-unit transactions.
- Private Owners:Individual purchasers seeking point-to-point mobility autonomy dominate Australia's recreational aviation clusters and New Zealand's owner-flown networks. India's emerging high-net-worth demographic in Delhi and Mumbai is expanding this segment fastest, though hangar scarcity at secondary airfields constrains fleet growth.
- Charter Operators:Fleet-based service providers across Australia's mining corridors and Indonesia's island chains generate the highest airframe utilization rates. These operators prioritize dispatch reliability and rapid turnaround capability, compressing procurement cycles toward younger vintage aircraft with integrated avionics suites.
- Corporate Clients:Flight departments and managed fleet structures now favor access agreements over balance-sheet ownership.
- Government Agencies:Civil aviation authorities and emergency services procure specialized configurations for surveillance and medical evacuation missions.
Charter Operators concentrate the highest airframe throughput while Corporate Clients are pivoting most aggressively toward managed-access structures.
Application:
Mission-specific equipage requirements create divergent specification pathways, with air ambulance configurations demanding dedicated medical installations that extend delivery timelines.
- Business Travel:Point-to-point executive mobility dominates procurement volume across Australia's intercity corridors and India's Delhi-Mumbai triangle. Charter operators in these corridors specify premium cabin configurations and connectivity suites that elevate capital costs but sustain yield premiums on thin routes.
- Air Ambulance:Medical evacuation missions across Australia's remote mining regions and Indonesia's dispersed island chains require dedicated stretcher installations, oxygen systems, and electrical capacity for life-support equipment. Civil Aviation Safety Authority Australia's stringent equipment certification extends modification timelines for these specialized configurations.
- Cargo Transport:Quick-change interior systems enable dual-use flexibility for small-package logistics.
- Recreational Use:Owner-flown leisure travel concentrates in New Zealand's tourism corridors and Australia's coastal regions.
Business Travel commands the dominant revenue share while Air Ambulance climbs fastest as mining and island healthcare access gaps widen.
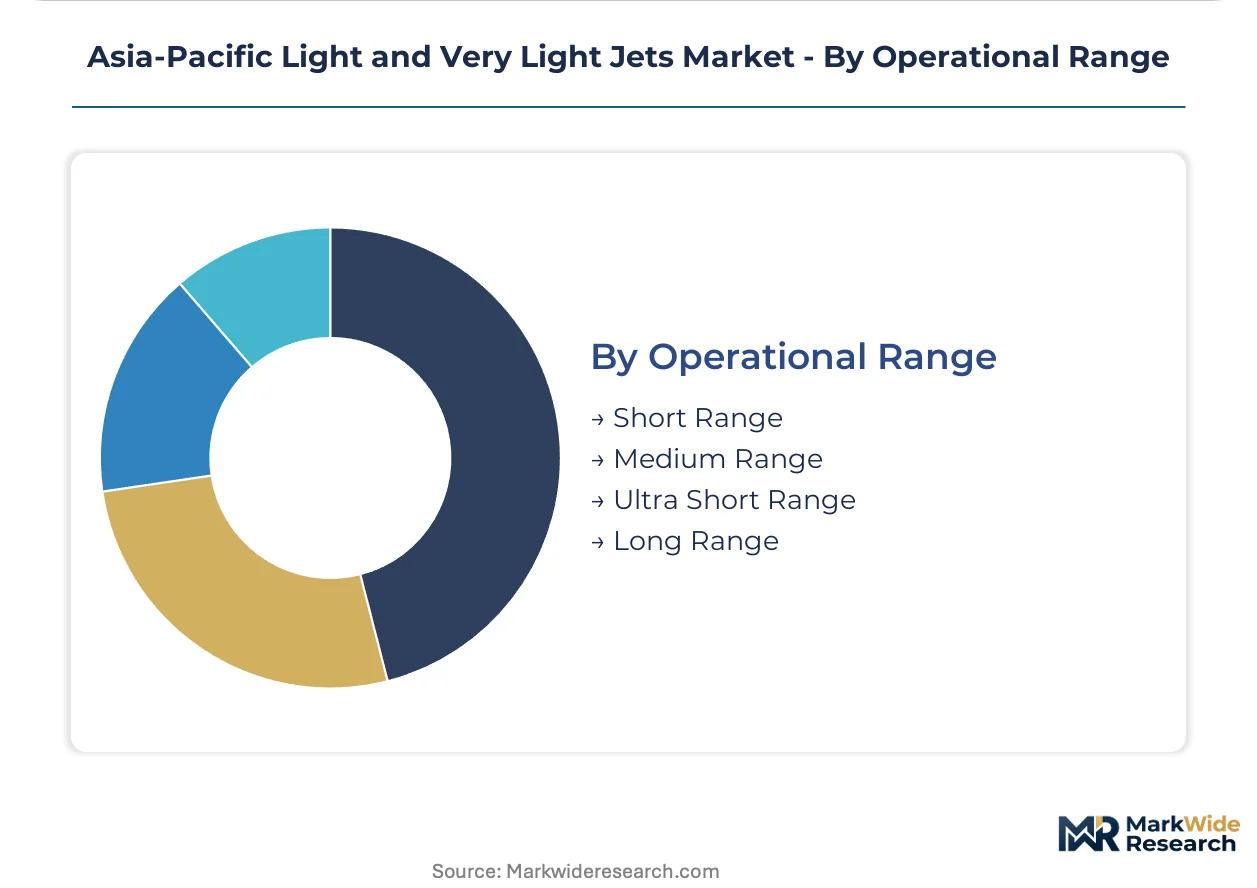
Operational Range:
Route network topology dictates range specification, with archipelagic geographies penalizing short-range assets and continental corridors enabling lighter configurations.
- Medium Range:Platforms covering 1,500 to 3,000 nautical miles dominate intercity business missions across Australia's east coast and India's north-south axis. These aircraft penetrate the largest addressable route set without the weight penalties of long-range fuel capacity, optimizing payload economics for typical regional sector lengths.
- Short Range:Missions under 1,500 nautical miles serve dense metropolitan pairings and island-hopping routes. Indonesia's intra-archipelago operators and Philippines charter fleets favor these configurations for their lower acquisition costs and reduced fuel burn on sub-two-hour sectors.
- Ultra Short Range:Sub-500-nautical-mile capability targets specialized shuttle missions.
- Long Range:Extended reach configurations penetrate transcontinental and transoceanic corridors.
Medium Range captures the broadest route applicability while Short Range expands most quickly as intra-ASEAN connectivity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific light and very light jets landscape. Australia's corporate buyers show the least sensitivity to acquisition cost, while Indonesia's owner-pilot segment operates at the threshold of affordability.
Australia
Corporate flight departments and mining sector operators drive demand for medium-range light jets across the Gold Coast-to-Sydney corridor. Civil Aviation Safety Australia mandates instrument rating upgrades that extend crew training timelines. Perth anchors Western Australia's resource extraction aviation cluster, where air ambulance configurations serve remote mine sites.
India
Delhi-Mumbai business aviation triangle concentrates high-net-worth individual purchases and managed fleet structures. Directorate General of Civil Aviation certification reforms compress type-approval timelines for imported aircraft. Bangalore's emerging technology executive demographic is expanding fractional ownership program enrollment.
Indonesia
Relaxed owner-pilot regulations unlock single-pilot very light jet operations across the archipelago's island-hopping routes. The country's civil aviation authority liberalized private pilot certification thresholds for aircraft below 10,000 pounds maximum takeoff weight. Jakarta-Surabaya corridor operators favor short-range platforms for sub-two-hour intercity missions.
Malaysia
Single-pilot certification liberalization accelerates personal transportation segment growth among Southeast Asian high-net-worth individuals. The national aviation regulator streamlined type rating requirements for very light jet platforms. Kuala Lumpur's corporate aviation infrastructure supports expanding charter operator consolidation activity.
Singapore
Turbofan engine overhaul specialization and MRO capability concentration serve dispersed Pacific island operator demand. The Civil Aviation Authority of Singapore enforces stringent maintenance technician qualification standards. Seletar Aerospace Park anchors the region's technical service access point for legacy fleet avionics retrofits.
Asia-Pacific Light and Very Light Jets Market Competitive Environment
Capability concentration sits with established full-service airframers; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: integrated aerospace groups with complete product families, specialized business aviation pure-plays, and diversified industrial manufacturers with aviation divisions. Consolidation pressure intensifies as charter operator procurement cycles compress and aftermarket service revenue pools attract non-traditional entrants. Geographic expansion and strategic partnerships dominate competitive maneuvering.
Within the established airframer tier, Embraer SA and Honda Aircraft Company exemplify divergent technical philosophies. Embraer SA anchors recurring maintenance streams through established service network density. Honda Aircraft Company occupies a position defined by aerodynamic innovation in propulsion integration. Textron Inc. represents scale-driven manufacturing efficiency across multiple jet families. These three entities collectively illustrate the competitive tension between service-network depth, technical differentiation, and production economies.
| Leading Market Players |
|---|
| Embraer SA |
| Honda Aircraft Company |
| Textron Inc. |
| Pilatus Aircraft Ltd |
| Bombardier Inc. |
| Cirrus Design Corporation |
| Diamond Aircraft Industries |
| Daher |
| Piper Aircraft |
| Others |
Value Chain & Pricing Dynamics
Singapore's Seletar Aerospace Park concentrates turbofan engine overhaul capacity and avionics retrofit specialization, creating regional pricing power for aftermarket services that cascades downstream through Australia's charter operator networks and Indonesia's dispersed island fleets.
Pricing Analysis
Engine overhaul and avionics service contracts generate lifetime value exceeding initial airframe acquisition costs across the regional fleet. Three-tier pricing structure across premium OEM-authorized, standard independent MRO, and economy third-party maintenance levels segments buyer access by certification requirements and dispatch reliability needs. Pricing pressure stems from charter operator consolidation compressing procurement cycles toward younger aircraft with integrated warranties. Indonesia's owner-pilot segment exhibits highest price sensitivity, while Australia's mining sector flight departments prioritize dispatch reliability over acquisition cost.
Supply Chain Analysis
Contract manufacturing for avionics suites and engine components concentrates in Singapore, Australia, and the United States. Supply chains draw from specialized titanium alloys, composite prepregs, and turbofan engine cores. Single-source vulnerability persists for certain avionics chipsets subject to export control restrictions. Distribution runs through OEM-direct channels for new aircraft sales and authorized service networks for aftermarket parts, with independent brokers filling gaps for legacy fleet support across secondary Southeast Asian airfields.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation intensifies as corporate flight departments abandon outright ownership for managed access structures, creating service-provider niches distinct from traditional OEM sales channels.
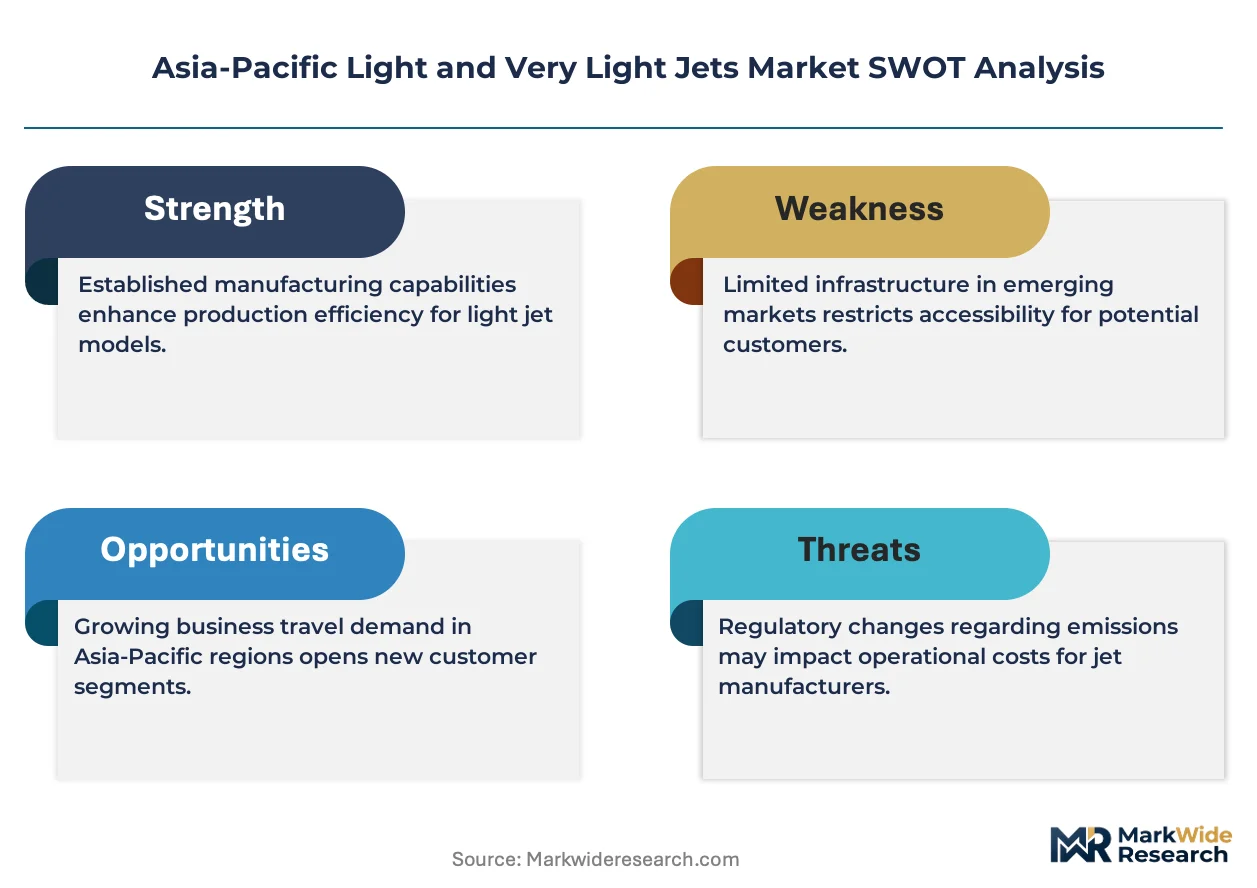
For Market Incumbents: Build regulatory certification moats by accelerating bilateral recognition agreements with India's DGCA and Indonesia's civil aviation authority. Secure exclusive MRO partnerships with Singapore's Seletar cluster to lock in aftermarket revenue streams. Counter emerging threats from fractional ownership platforms by embedding long-term service contracts into managed fleet agreements. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's owner-pilot very light jet segment where single-pilot certification liberalization outpaces incumbent service network expansion. Target Australia's remote mining corridor air ambulance configurations underserved by existing charter operators. Deploy direct-to-operator digital sales channels bypassing traditional broker networks concentrated in Sydney and Melbourne. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors avionics retrofit specialists with ADS-B Out and performance-based navigation compliance capabilities. Long-term viability rests on capturing recurring maintenance revenue from aging light jet fleets rather than cyclical new aircraft sales. Monitor India's DGCA certification reform velocity as inflection indicator for import market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Expansion | Embraer SA's Phenom maintenance density captures recurring overhaul revenue from Australia's charter operators. |
| Regulatory Certification Investment | Honda Aircraft Company's HA-420 type-approval velocity accelerates market entry across ASEAN liberalization windows. |
| Fractional Ownership Platform Launch | Managed fleet structures displace outright ownership in India's Delhi-Mumbai business aviation triangle. |
| Avionics Retrofit Capability Buildout | ADS-B Out mandates channel maintenance expenditure toward digital cockpit upgrades across legacy fleets. |
| Air Ambulance Configuration Specialization | Australia's remote mining corridors generate underpenetrated demand for rapid patient transport installations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with charter operator fleet managers, corporate flight department directors, MRO facility technical leads, and civil aviation authority certification officials. Secondary validation incorporated DGCA regulatory filings, CASA operational directives, customs import records for aircraft components, and OEM delivery disclosures. Bottom-up airframe deployment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Calibration against historical fleet turnover rates and regulatory implementation timelines anchored projection reliability. Segmentation dimensions modeled include aircraft type, end-user category, mission application, and operational range tier. CAGRs were derived from fitted growth curves applied to base-year installed base estimates. Industry-specific forecast inputs incorporated pilot certification liberalization schedules and ADS-B Out mandate compliance deadlines across ASEAN member states.
Stress conditions across aviation fuel price volatility, regulatory timeline delays, and maintenance technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fractional ownership adoption curves and bilateral certification reciprocity progression. Quarterly review of DGCA import approval velocity and CASA instrument rating mandate implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
United States Aerospace and Defense Market
Aircraft
South Korea Aviation Market
Aircraft
Amphibious Aircraft Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Aerospace Winglet System Market
Aircraft
Global Business Jets Market
Aircraft
Latin America Business Jet Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Aircraft Jack Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Regional Jet Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Aircraft Oxygen System Market