
 Australia Aviation Market | 2026-2036
Australia Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Aviation Market Analysis
Operating lease prevalence is tilting competitive dynamics toward asset-light carriers and specialized lessors in Australian aviation. The Boeing Company leverages its established widebody support network to sustain aftermarket revenue across Qantas and Virgin Australia fleets. Airbus SE anchors narrowbody procurement pipelines through A320neo family positioning with domestic low-cost operators. Lockheed Martin Corporation specializes in defense-adjacent sustainment contracts tied to RAAF platforms, occupying a distinct procurement channel from commercial rivals.
Australian aviation encompasses all fixed-wing and rotary-wing aircraft operations, maintenance ecosystems, and air traffic management infrastructure serving domestic and international routes across the continent's vast distances, where sector lengths often exceed 2,500 nautical miles. Commercial aircraft dominate fleet value as international capacity restoration drives widebody reactivation, while unmanned aerial vehicles represent the fastest-growing product category as CASA-certified beyond-visual-line-of-sight operations expand into mining survey and agricultural monitoring. Flight training services command premium pricing due to instructor scarcity and simulator slot constraints, whereas ground handling margins face pressure from airport consolidation of service contracts.
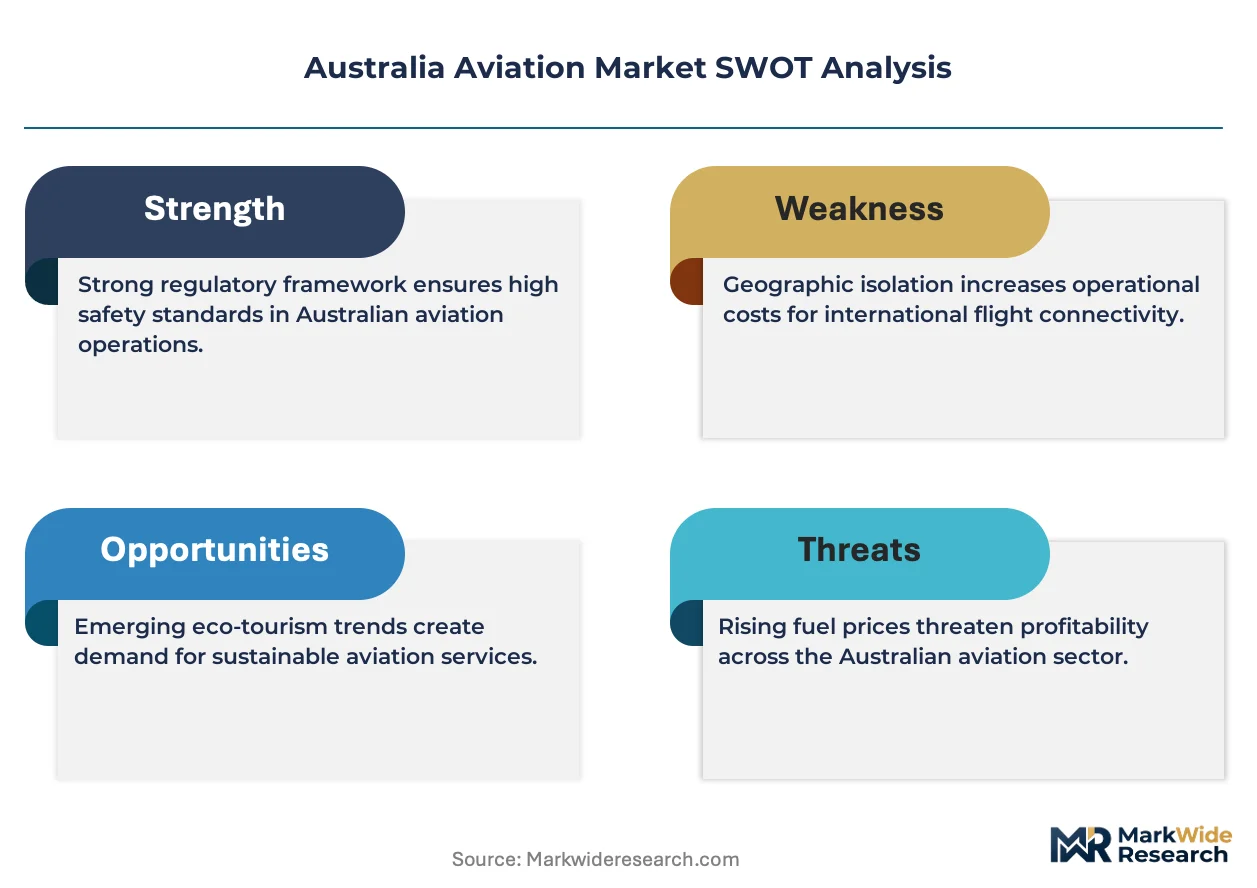
CASA's airworthiness directives and the Civil Aviation Act govern operational standards, while TGA-adjacent medical certification protocols shape pilot workforce availability through stringent health screening requirements. The Australian government's Jet Zero Council framework and sustainable aviation fuel mandates are redirecting procurement criteria toward emissions-reduction credentials. Stakeholders must monitor CASA's regulatory technology roadmap for unmanned systems integration, as drone traffic management protocols will determine infrastructure investment priorities and new entrant market access conditions.
Market Dynamics
CASA's updated Part 61 flight training regulations are compressing instructor supply timelines while FIFO mining traffic and international gateway services concentrate demand along Queensland's coastal aviation corridor.
Growth Catalysts
- Jet Zero Council framework:Australia's sustainable aviation fuel mandates redirect procurement criteria toward emissions-reduction credentials across domestic carrier fleets.
- Queensland coastal corridor:Overlapping FIFO mining traffic and international gateway services concentrate demand for regional fleet expansion.
- Beyond-visual-line-of-sight operations:CASA-certified drone traffic management protocols unlock mining survey and agricultural monitoring applications.
Market Restraints
- Simulator slot scarcity:Flight training infrastructure constraints limit pilot certification throughput despite elevated demand from regional operators.
- Jet fuel price volatility:Input cost exposure compresses margin buffers for domestic carriers operating thin-route networks.
- TGA-adjacent medical certification:Stringent health screening protocols reduce qualified pilot pool availability through elevated disqualification rates.
Strategic Opportunities
- Western Australia FIFO routes:Underpenetrated remote site connectivity presents white space for specialized regional operators.
- Drone traffic management infrastructure:CASA's regulatory technology roadmap creates first-mover advantage in unmanned systems integration.
- Sustainable aviation fuel supply chains:Domestic biofuel production incentives align procurement with federal decarbonization targets.
Industry Challenges
- Certified flight instructor scarcity:Part 61 pathway compression extends training timelines while demand for commercial pilots accelerates.
- Airport service contract consolidation:Ground handling margin pressure intensifies as major gateways centralize vendor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Aviation Market |
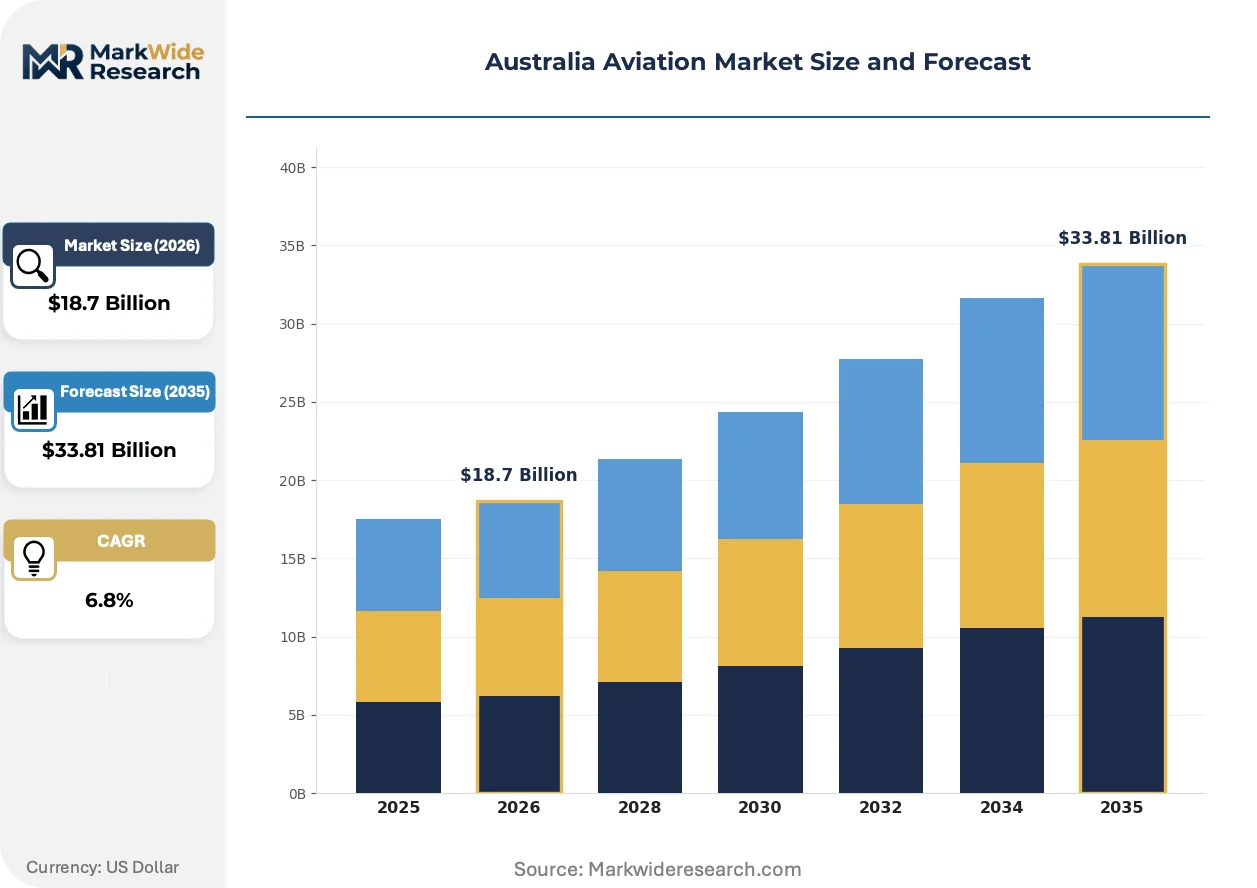
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Cargo Aircraft, Military Aircraft, Unmanned Aerial Vehicles Service Type: Maintenance, Repair, and Overhaul, Flight Training, Ground Handling, In-Flight Services End User: Airlines, Government, Cargo Operators, Private Owners Technology: Avionics, Aerodynamics, Propulsion Systems, Flight Control Systems |
| Companies Covered | General Dynamics Corporation, Embraer, The Boeing Company, Leonardo S.p.A, Textron Inc., Airbus SE, Bombardier Inc., Pilatus Aircraft Ltd, Lockheed Martin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Aviation Market Emerging Trajectories
Aviation training and operational technologies are converging around virtualization, regulatory adaptation to unmanned systems, and compressed procurement cycles for fleet assets.
Extended reality (XR) simulation platforms are virtualizing cockpit procedural training and emergency scenario rehearsal. Regional operators and flight schools adopt these systems to bypass physical simulator slot constraints. This technology is virtualizing traditional instructor-led hours while CASA evaluates certification credit eligibility for virtual environment completion.
CASA's regulatory technology roadmap for unmanned aerial systems integration mandates standardized detect-and-avoid protocols and remote identification requirements. Commercial drone operators must retrofit existing fleets or acquire certified platforms to maintain operational authorization. Mining survey contractors in Western Australia and Queensland agricultural monitoring services face accelerated compliance timelines as enforcement phases begin.
Operating lease structures displace direct aircraft ownership among domestic low-cost carriers and regional tourism operators. Specialized lessors capture margin through sale-leaseback arrangements and residual value risk assumption. This financing rotation concentrates most visibly in narrowbody fleet renewals serving Sydney-Melbourne-Brisbane triangle routes.
Australia Aviation Market Segmentation
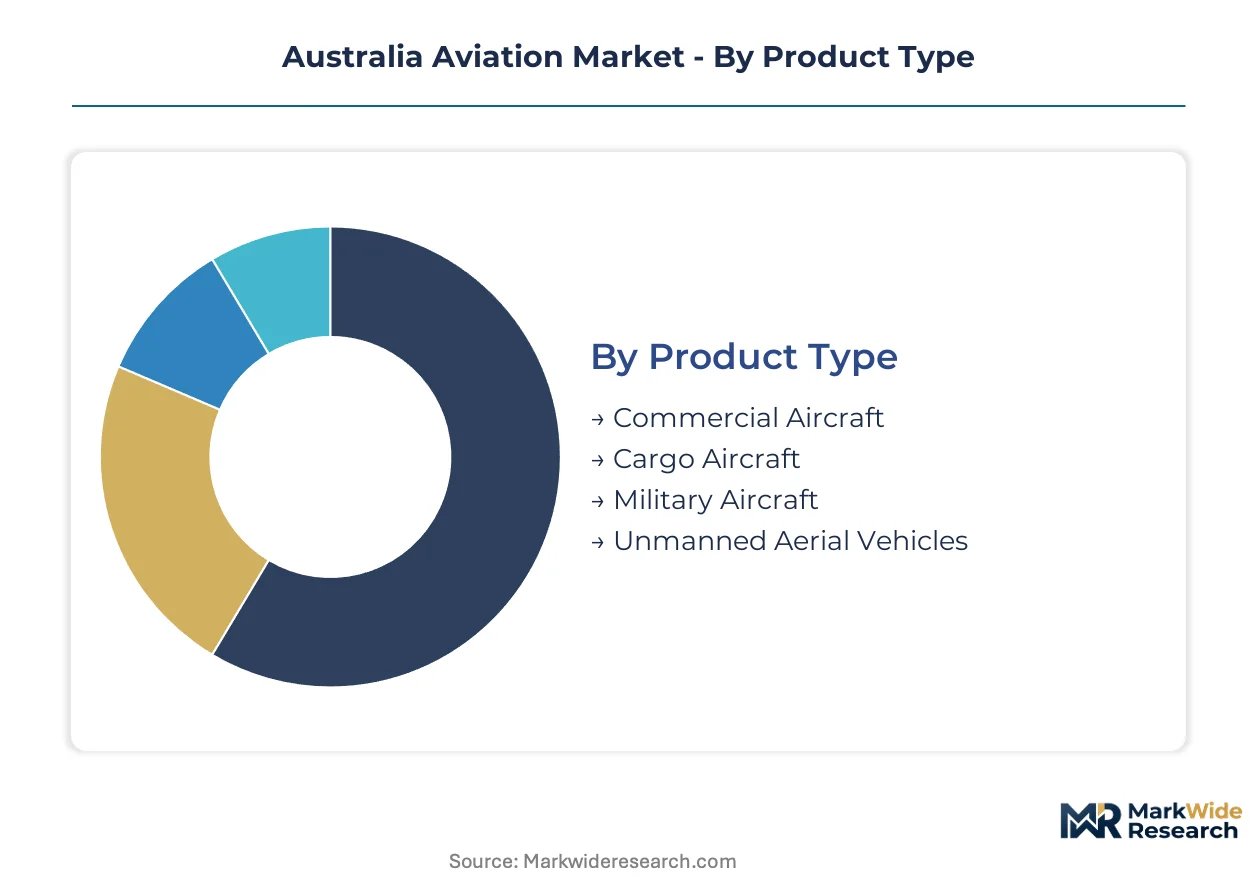
Segmentation reveals how after-sales service intensity varies dramatically across aviation product categories, with widebody platforms demanding specialized MRO infrastructure and narrowbody fleets driving volume-based training economics. Understanding these structural differences illuminates where procurement budgets concentrate and which supplier capabilities command premium positioning.
Product Type:
After-sales service intensity peaks with commercial aircraft platforms, where engine overhaul cycles and airframe heavy checks create recurring revenue streams that outlast initial delivery margins by decades.
- Commercial Aircraft:Twin-aisle and single-aisle platforms dominate fleet value, with international capacity restoration driving widebody reactivation across Qantas and Virgin Australia networks. Queensland's coastal aviation corridor concentrates demand where FIFO mining traffic and international gateway services overlap, creating mixed-fleet complexity for MRO providers.
- Unmanned Aerial Vehicles:Fixed-wing and multirotor systems certified for beyond-visual-line-of-sight operations represent the steepest expansion trajectory, with CASA-mandated detect-and-avoid protocols forcing fleet retrofit investments. Mining survey contractors in Western Australia and agricultural monitoring services in Queensland absorb platform costs to capture operational authorization.
- Cargo Aircraft:Freighter conversions and dedicated cargo fleets serve time-sensitive supply chains, with dedicated MRO networks supporting overnight express operations.
- Military Aircraft:RAAF platforms operate through defense-adjacent sustainment contracts, with Lockheed Martin and domestic primes occupying procurement channels distinct from commercial aviation.
By volume, Commercial Aircraft leads. By growth pace, Unmanned Aerial Vehicles is climbing the fastest.
Service Type:
Margin structures diverge sharply across service categories, with flight training capturing premium pricing from instructor scarcity while ground handling faces airport-driven consolidation pressure.
- Flight Training:CASA's Part 61 regulations compress instructor supply timelines while extended reality platforms virtualize cockpit procedural training. Simulator slot constraints limit certification throughput despite regional operator demand acceleration.
- Maintenance, Repair, and Overhaul:Engine overhaul cycles and airframe heavy checks anchor aftermarket revenue, with Boeing's established widebody support network sustaining relationships across Australian carrier fleets.
- Ground Handling:Airport service contract consolidation intensifies margin pressure as major gateways centralize vendor relationships and standardize equipment specifications.
- In-Flight Services:Catering and cabin provisioning adapt to carrier cost structures, with low-cost operators minimizing spend while full-service networks differentiate through premium offerings.
By revenue concentration, Maintenance, Repair, and Overhaul dominates. By pricing power expansion, Flight Training is gaining share fastest.
End User:
Procurement sophistication varies by operator scale, with airlines driving fleet-wide standardization while government buyers navigate defense procurement protocols.
- Airlines:Qantas and Virgin Australia anchor narrowbody and widebody demand, with operating lease structures displacing direct ownership and concentrating supplier relationships with specialized lessors.
- Government:RAAF and federal agencies sustain defense-adjacent platforms through long-term sustainment contracts with distinct certification and security requirements.
- Cargo Operators:Dedicated freighter fleets and converted passenger aircraft serve domestic overnight networks, with MRO scheduling optimized around utilization patterns.
- Private Owners:Business aviation and general aviation operators access fragmented service networks, with CASA medical certification protocols shaping pilot availability.
By fleet value, Airlines leads. By contract duration stability, Government is expanding most quickly.
Technology:
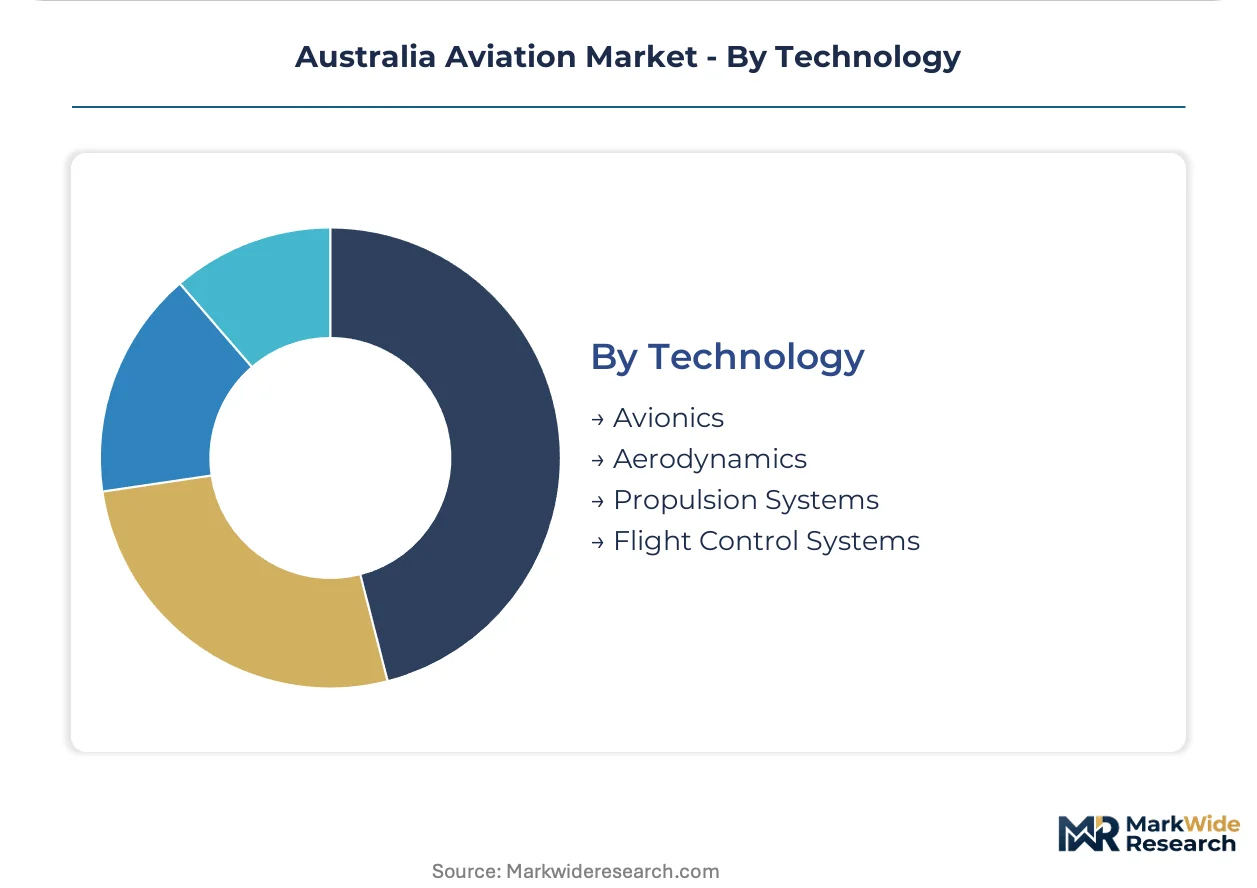
Technology segmentation tracks where R&D investment concentrates and which subsystems drive upgrade cycles across Australian operator fleets.
- Avionics:Cockpit display systems and communication suites undergo continuous refresh cycles, with CASA mandates driving ADS-B and satellite navigation adoption.
- Propulsion Systems:Engine efficiency improvements and sustainable aviation fuel compatibility dominate procurement criteria under the Jet Zero Council framework.
- Flight Control Systems:Fly-by-wire architectures and automated flight guidance reduce pilot workload on long-haul sector lengths exceeding 2,500 nautical miles.
- Aerodynamics:Winglet retrofits and drag reduction modifications extend existing fleet economic life against new aircraft capital costs.
By replacement frequency, Avionics leads. By regulatory momentum, Propulsion Systems is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's aviation sector operates with a structural trade deficit in aircraft imports against service export revenues from international education and tourism. The analysis window reveals divergent growth trajectories across state-level aviation corridors shaped by mining logistics, gateway capacity, and regulatory enforcement zones.
New South Wales
Sydney Airport anchors international gateway traffic with Qantas and Virgin Australia maintaining dual-hub operations for transpacific routes. CASA's airworthiness directives enforce stringent maintenance protocols on widebody fleets operating from Kingsford Smith. The Greater Sydney region concentrates MRO infrastructure investment as engine overhaul cycles align with post-recovery capacity restoration.
Victoria
Melbourne Airport sustains the second-highest international passenger throughput with low-cost carrier competition intensifying on Southeast Asian routes. The state's flight training sector faces simulator slot scarcity as Part 61 regulations compress instructor certification timelines. Avalon Airport hosts dedicated freighter operations serving time-sensitive supply chains across the Bass Strait.
Queensland
The coastal aviation corridor concentrates overlapping FIFO mining traffic and international tourism gateway services, creating mixed-fleet complexity for regional operators. Brisbane Airport anchors narrowbody procurement pipelines as Jet Zero Council mandates redirect carrier procurement toward emissions-reduction credentials. Cairns and Townsville absorb expanded fleet orders from tourism operators targeting post-recovery passenger volumes.
Western Australia
Perth Airport serves as the primary FIFO mining logistics hub with underpenetrated remote site connectivity presenting white space for specialized regional operators. The state's unmanned aerial vehicle sector leads CASA-certified beyond-visual-line-of-sight operations for mining survey contractors. Domestic biofuel production incentives align with federal decarbonization targets for sustainable aviation fuel supply chain development.
South Australia
Adelaide Airport maintains defense-adjacent sustainment contracts tied to RAAF platforms through Edinburgh airbase proximity. The state's agricultural monitoring services absorb CASA-mandated detect-and-avoid protocol retrofits for commercial drone operators. Regional tourism operators expand fleet connectivity to Kangaroo Island and remote outback destinations.
Australia Aviation Market Vendor Landscape
On the supply side, the industry is bifurcated between full-service aerospace conglomerates and specialized platform manufacturers serving distinct procurement channels. The vendor base stratifies across defense-adjacent sustainment providers, commercial aircraft lessors, and unmanned systems integrators. Three archetypes dominate: established widebody support networks, narrowbody procurement pipeline anchors, and drone traffic management specialists. Competitive moves center on operating lease structure expansion and sustainable aviation fuel certification partnerships.
Within the defense-adjacent tier, Lockheed Martin Corporation and General Dynamics Corporation occupy positions distinct from commercial rivals through long-term RAAF sustainment contracting. The Boeing Company and Airbus SE anchor the commercial aircraft vector, with the former exemplifying established widebody support economics and the latter representing narrowbody fleet renewal positioning. Leonardo S.p.A sits within the specialized rotary-wing and unmanned systems segment.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Embraer |
| The Boeing Company |
| Leonardo S.p.A |
| Textron Inc. |
| Airbus SE |
| Bombardier Inc. |
| Pilatus Aircraft Ltd |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Jet fuel price volatility determines both margin compression across domestic carrier fleets and the geographic concentration of MRO infrastructure investment. This commodity exposure feeds back into supply chain decisions as operators prioritize lease structures over ownership to transfer residual value risk to specialized lessors.
Pricing Analysis
Airlines anchor pricing structures around operating lease rates and power-by-the-hour maintenance contracts rather than capital acquisition. Price differentiation stems from aircraft generation tier and CASA certification compliance status, with newer narrowbody platforms commanding premiums for fuel efficiency credentials. Cost compression in regional turboprop services is intensifying because mining contractors consolidate vendor panels for FIFO routes. Charter operators exhibit highest price sensitivity due to discretionary demand exposure, while government sustainment contracts demonstrate lowest sensitivity through multi-year obligation structures.
Supply Chain Analysis
Extended payment terms from Australian carriers to MRO providers are compressing working capital cycles throughout the aftermarket ecosystem. Component manufacturing concentrates in the United States, France, and Germany, with engine assemblies and avionics suites drawing from these hubs. Supply chain vulnerability rests on single-source dependencies for specific engine overhaul capabilities and specialized simulator hardware. Distribution runs through Sydney and Melbourne as consolidated gateway nodes, with secondary flows reaching Brisbane and Perth through scheduled air freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's aviation market fragments across distinct procurement channels—defense sustainment, commercial operating leases, and emerging unmanned systems—creating specialized niches for targeted positioning. The convergence of FIFO mining logistics and international tourism recovery is generating overlapping demand patterns that reward focused service providers.
For Market Incumbents: Build regulatory compliance moats through early CASA drone certification investment and sustainable aviation fuel infrastructure partnerships. Qantas and Virgin Australia fleet standardization programs threaten independent MRO providers with volume exclusion, necessitating backward integration into specialized component repair capabilities or exclusive regional operator relationships. For New Entrants and Emerging Players: Pursue underpenetrated Western Australia FIFO routes where incumbent coverage gaps persist in remote site connectivity. Agricultural monitoring services in Queensland present the most penetrable unmanned systems segment due to fragmented operator landscape and accelerating CASA compliance deadlines. Go-to-market positioning should emphasize detect-and-avoid retrofit bundling with operational authorization consulting. For Investors and Strategic Acquirers: CASA's unmanned systems regulatory technology roadmap reshapes the acquisition landscape toward drone traffic management infrastructure and certified pilot training platforms. Long-term viability favors asset-light lessors with narrowbody exposure and specialized regional operators with FIFO contract visibility. Monitor Jet Zero Council biofuel procurement mandates as the signal indicating which carrier fleets will face accelerated fleet renewal capital demands.| Strategic Initiative | Industry Significance |
|---|---|
| Operating Lease Structure Expansion | Specialized lessors capture margin through sale-leaseback arrangements with Qantas and Virgin Australia narrowbody renewals. |
| Sustainable Aviation Fuel Certification Partnership | Domestic biofuel production incentives align procurement with Jet Zero Council emissions-reduction mandates. |
| Drone Traffic Management Infrastructure Investment | CASA-mandated detect-and-avoid protocols create first-mover advantage in unmanned systems integration. |
| Extended Reality Training Platform Deployment | Virtual cockpit simulation bypasses physical simulator slot constraints constraining Part 61 certification throughput. |
| Western Australia FIFO Route Specialization | Remote mining site connectivity gaps present white space for dedicated regional operator market entry. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of CASA regulatory filings, airline fleet planning disclosures, and mining contractor procurement databases. Primary interviews incorporated airline fleet managers, MRO facility directors, flight school operators, and mining logistics procurement leads. Secondary validation drew from Civil Aviation Act amendments, Jet Zero Council policy documents, and customs trade data on aircraft component imports. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the Australian aviation ecosystem.
Forecast inputs incorporate aircraft delivery schedules, pilot certification throughput constraints, and sustainable aviation fuel supply chain development timelines. Segmentation modeling spans product type, service category, end-user archetype, and technology subsystem across the projection horizon. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and fleet renewal cycles. Industry-specific inputs include CASA Part 61 implementation pace and FIFO mining contract renewal patterns.
The forecast holds incumbent behavior within observed patterns; aggressive fleet standardization moves by Qantas or Virgin Australia would shift MRO provider competitive outcomes. Macroeconomic deviation in commodity export revenues, regulatory acceleration in unmanned systems integration, or technological breakthrough in sustainable aviation fuel production would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Southeast Asia Aviation Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Middle-East Aviation Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Afterburner Market
Aircraft
Military Fixed-Wing Aircraft Market
Aircraft
Docking System Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Global LW Sport Aircraft Market