
 Aircraft Leasing and Rental Market | 2026-2036
Aircraft Leasing and Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Leasing and Rental Market Analysis
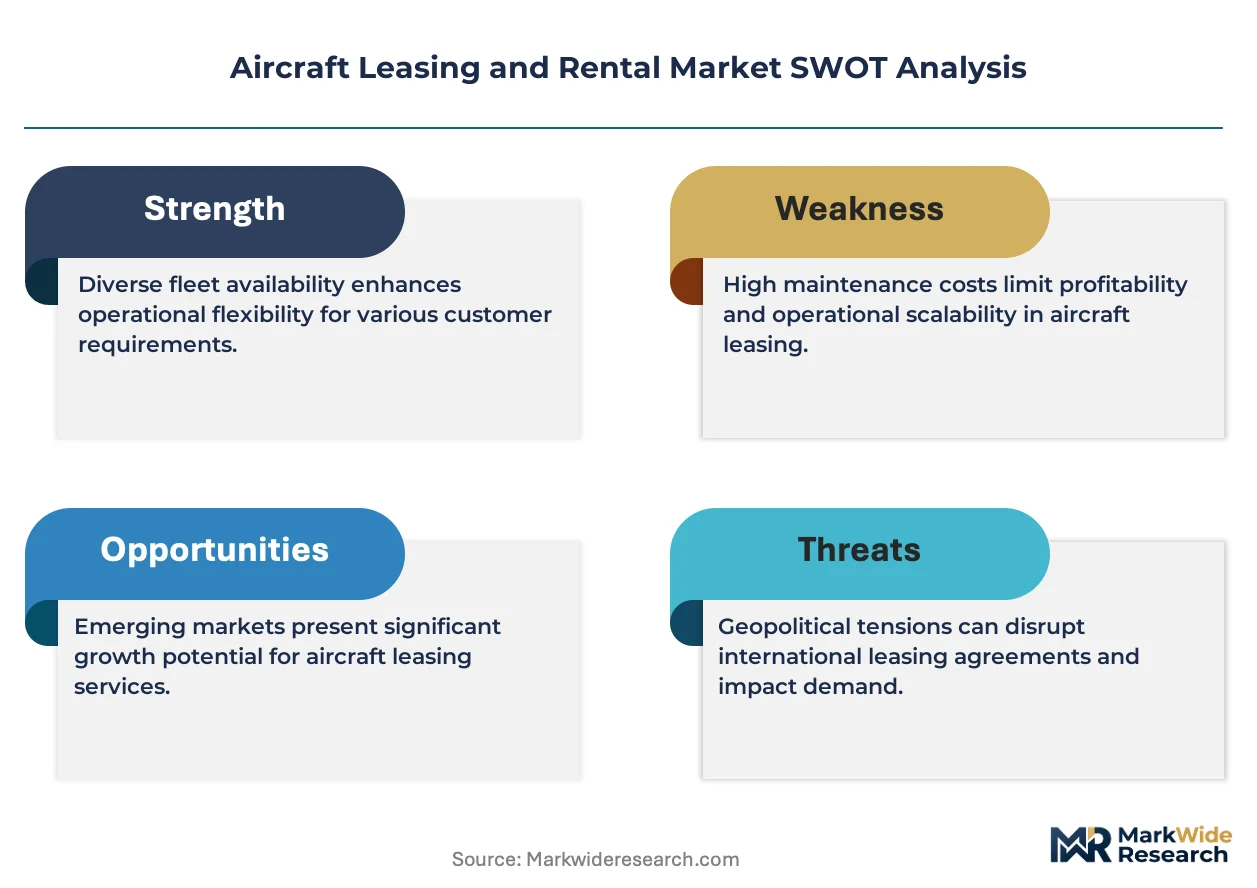
Buyer concentration among low-cost carriers is hardening across emerging aviation corridors. AerCap Holdings N.V. leverages its scale to dominate wide-body placements with major network carriers. SMBC Aviation Capital anchors its competitive position through deep relationships with Asia-Pacific operators. BOC Aviation naviges regulatory complexity across multiple jurisdictions to sustain portfolio diversification.
Aircraft leasing and rental denotes the commercial practice of providing airframes to operators under contractual arrangements that transfer use rights without full ownership transfer, typically governed by lease factors tied to asset residual values and maintenance reserve structures. The primary purpose is to enable airlines to manage fleet flexibility, preserve balance sheet capacity, and access modern fuel-efficient technology without capital-intensive direct purchases. Narrow-body assets command the largest share of transaction volume given their deployment versatility on short-haul and medium-haul routes. Operating lease structures attract the majority of new capital commitments as carriers prioritize off-balance-sheet treatment and return conditions. Wet lease arrangements serve seasonal demand peaks and crew-scarce markets where operational control transfers amplify lessor revenue per airframe.
FAA airworthiness directives and EASA type certification requirements shape lessor fleet composition decisions by determining which aircraft generations qualify for cross-border operations. The EU ETS and ICAO CORSIA framework impose carbon accountability on leased asset deployment, pushing lessors toward newer-engine technology to preserve residual values. Stakeholders must monitor how evolving emissions standards interact with lease rate factors and end-of-term remarketing exposure across jurisdictions.
Market Dynamics
The ICAO CORSIA framework is compressing lease rate factors for older-generation aircraft while accelerating lessor portfolio turnover toward next-engine technology. This regulatory pressure is restructuring capital deployment timelines across the entire lessor base.
Growth Catalysts
- India's airport infrastructure expansion:Greenfield terminals in Delhi, Mumbai, and Bengaluru are unlocking slot capacity for leased narrow-body deployments. Domestic carriers are tripling monthly lease commitments to capture this route growth.
- EU ETS carbon pricing:The emissions trading scheme is penalizing pre-2020 aircraft generations, creating artificial demand pull for lessor portfolios holding A320neo and 737 MAX assets.
- Wet lease operational control:Seasonal crew shortages in Southeast Asian markets are expanding lessor revenue per airframe through full operational package arrangements.
Market Restraints
- Titanium and composite input cost volatility:OEM production backlogs are extending new aircraft delivery timelines, trapping lessor capital in speculative forward positions.
- US FAA airworthiness directive uncertainty:Pending safety mandates on certain engine types are freezing secondary market liquidity for affected airframes.
- Banking sector concentration:Aircraft ABS issuance depends on a narrow pool of European and Japanese institutional investors, amplifying refinancing risk during rate cycles.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Low-cost carrier fleet plans in these markets remain 40% below regional peers, offering first-mover placement advantages for lessors with established Asia-Pacific relationships.
- Sustainable aviation fuel mandates:The EU Green Deal's blending requirements are creating lease rate premiums for aircraft with SAF-compatible engine certifications.
- Digital lease administration platforms:Blockchain-based maintenance reserve tracking is compressing transaction friction and expanding direct airline-lessor contracting outside traditional broker channels.
Industry Challenges
- Technical records digitization:Legacy paper-based maintenance documentation is delaying end-of-lease transitions and inflaming dispute resolution costs between lessors and operators.
- Cross-jurisdiction repossession complexity:Divergent enforcement frameworks across India, Indonesia, and the Philippines are extending aircraft recovery timelines during lessee defaults.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Leasing and Rental Market |
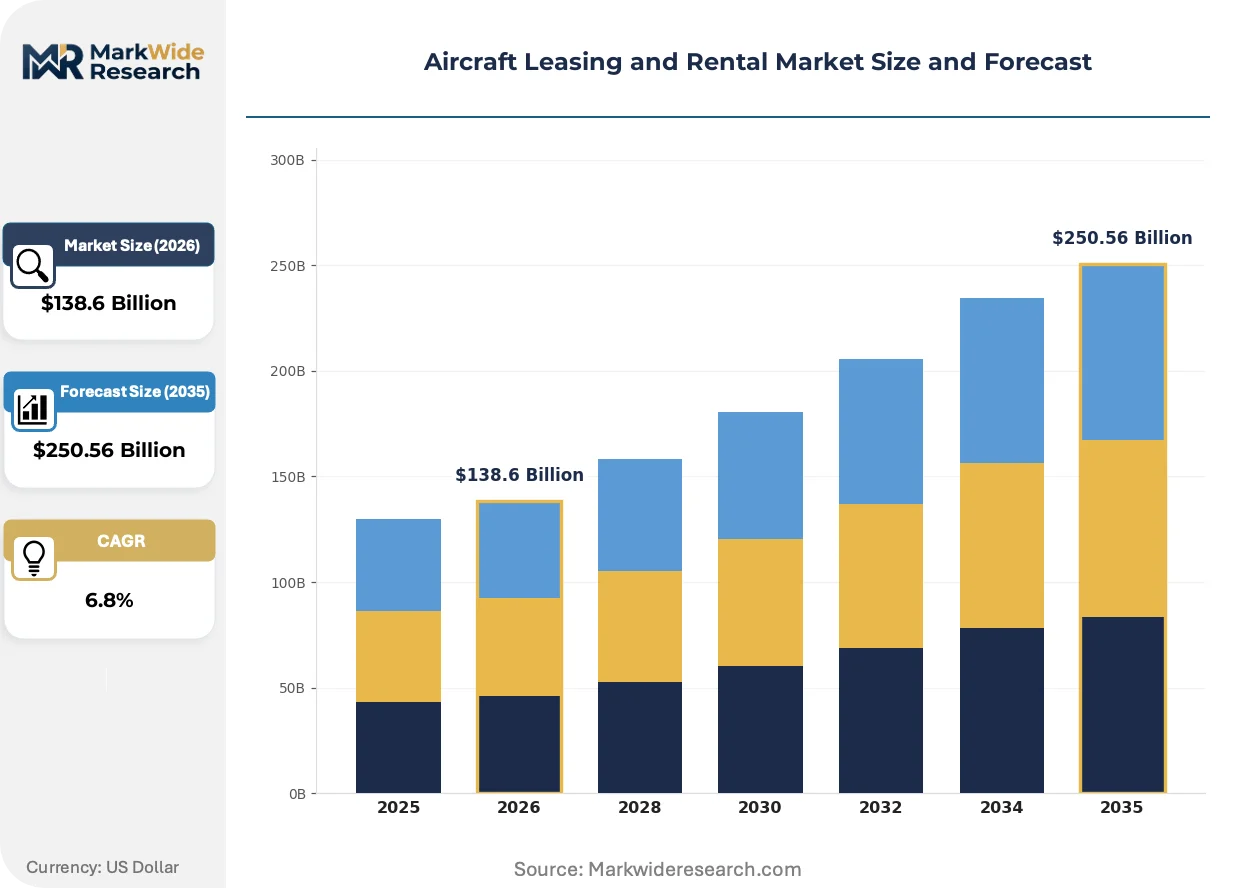
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Narrow-Body, Wide-Body, Very Large Aircraft, Regional Jets Lease Type: Operating Lease, Financial Lease, Wet Lease, Dry Lease Customer Type: Commercial Airlines, Cargo Carriers, Charter Services, Private Operators Contract Duration: Short-Term, Medium-Term, Long-Term, Flexible |
| Companies Covered | Avolon, BBAM Aircraft Leasing & Management, AerCap Holdings N.V., Dubai Aerospace Enterprise, Aviation Capital Group, SMBC Aviation Capital, BOC Aviation, Nordic Aviation Capital, Air Lease Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Leasing and Rental Market Emerging Trajectories
Digital twins and predictive maintenance systems are compressing aircraft downtime economics while reshaping how lessors price residual value risk into lease structures.
Artificial intelligence-driven predictive maintenance is expanding into lessor asset management workflows. Airlines operating leased fleets are adopting these systems to minimize unscheduled downtime and avoid penalty clauses. The technology is expanding into lease rate negotiations by enabling real-time residual value forecasting that compresses pricing spreads between lessor and operator.
The EU's CSRD sustainability reporting mandate is forcing lessors to disclose Scope 3 emissions from leased asset operations. This regulatory pressure is restructuring portfolio composition toward younger aircraft with verified carbon intensity data. European lessors are responding by accelerating sale-leaseback arrangements with carriers holding new-generation fleets.
Airlines are unbundling maintenance reserve management from traditional lessor relationships. Third-party technical asset managers are capturing these functions through standalone contracts that displace bundled lease provisions. This pattern is most visible among Southeast Asian low-cost carriers seeking operational flexibility without balance sheet commitment.
Aircraft Leasing and Rental Market Segmentation
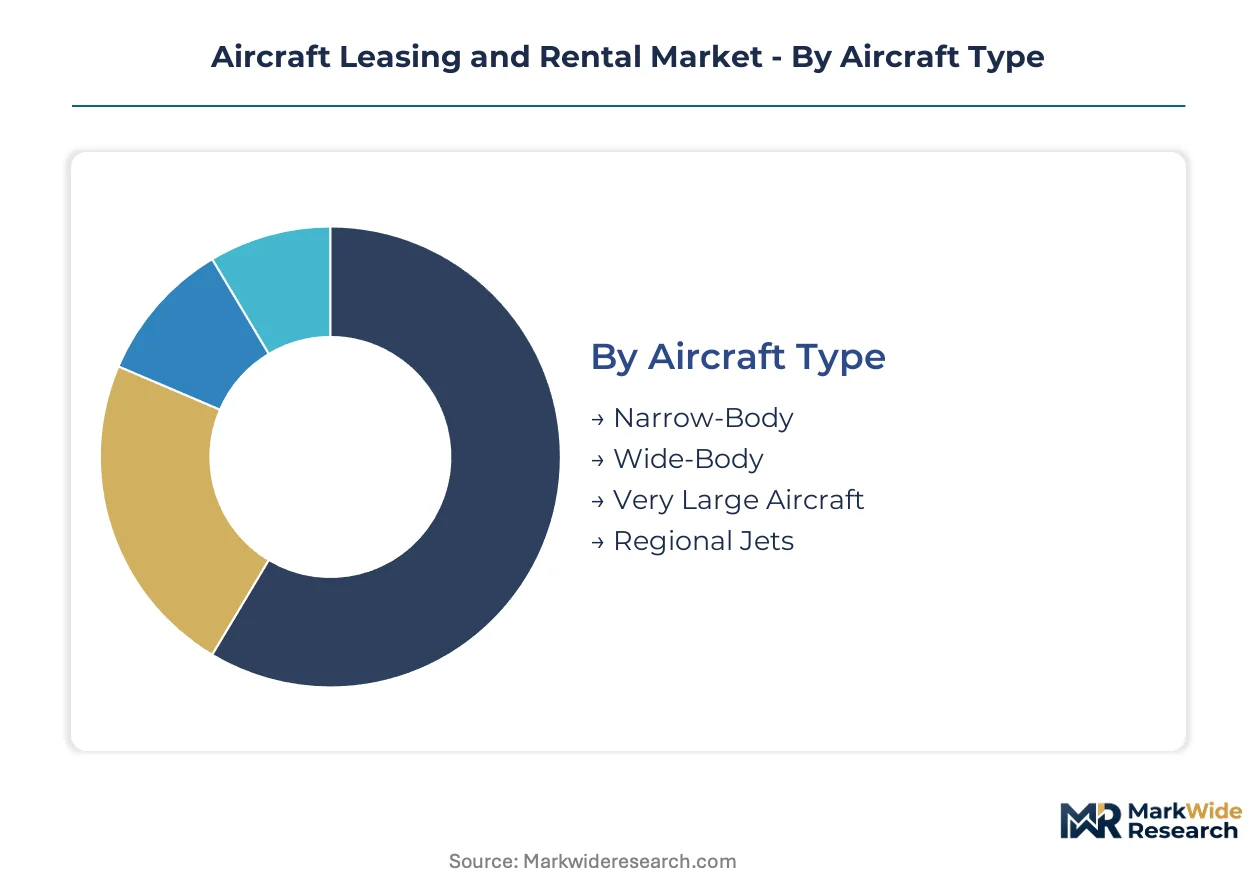
Segmentation in aircraft leasing and rental reveals how capital deployment, risk allocation, and operational control distribute across distinct contractual and asset configurations. Lessors structure portfolios around aircraft generation, lease mechanism, and customer credit profile to optimize residual value capture and remarketing flexibility.
Aircraft Type:
Standalone deployment dominates narrow-body and regional jet segments, while wide-body and very large aircraft function as embedded capacity within network carrier hub systems.
- Narrow-Body:Single-aisle configurations from A320 and 737 families command the highest transaction velocity. India's domestic carriers are tripling monthly lease commitments for these assets to capture slot expansion at Delhi, Mumbai, and Bengaluru airports.
- Wide-Body:Twin-aisle aircraft serve long-haul trunk routes with higher lease rate factors tied to residual value uncertainty. EU ETS carbon pricing is penalizing pre-2020 generations and accelerating demand pull for lessor portfolios holding A350 and 787 assets.
- Very Large Aircraft:A380 and 747-8 configurations occupy niche deployment scenarios with concentrated operator bases. Gulf network carriers anchor demand through fleet commonality requirements.
- Regional Jets:Sub-100 seat turbofans and turboprops feed spoke connectivity into major hubs. Southeast Asian low-cost carriers deploy these on thin routes where slot constraints limit narrow-body economics.
Narrow-body assets lead volumes today; wide-body placements are gaining share fastest as long-haul capacity rebuilds.
Lease Type:
Cost tier differentiation separates capital-light operating structures from balance-sheet-intensive financial arrangements, with wet lease commanding premium pricing for operational control transfer.
- Operating Lease:Off-balance-sheet treatment preserves carrier borrowing capacity while transferring residual risk to lessors. SMBC Aviation Capital and BOC Aviation anchor competitive positions through deep relationships with Asia-Pacific operators seeking this structure.
- Financial Lease:Capital lease accounting treats the asset as owned, with depreciation and interest expense recognition. Indian carriers favor this mechanism to access depreciation shields under domestic tax frameworks.
- Wet Lease:Full operational package including crew, maintenance, and insurance commands revenue premiums per airframe. Seasonal crew shortages in Southeast Asian markets are expanding lessor yield through these arrangements.
- Dry Lease:Aircraft-only provision requires operator technical capability and regulatory certification. FAA airworthiness directive uncertainty on certain engine types is freezing secondary market liquidity for dry-leased airframes affected by pending mandates.
Operating lease structures dominate capital commitments today; wet lease revenue is climbing the fastest as crew scarcity intensifies.
Customer Type:
Application concentration varies sharply, with commercial airlines driving standardized fleet economics while cargo and charter segments demand specialized configuration flexibility.
- Commercial Airlines:Scheduled passenger carriers generate predictable lease rate streams through network density and frequency requirements. Low-cost carriers across Southeast Asia are expanding leased fleets faster than owned assets.
- Cargo Carriers:Dedicated freighter operators and converted passenger-to-freighter lessors serve e-commerce logistics networks. AerCap Holdings N.V. leverages scale to dominate wide-body placements with integrators and postal operators.
- Charter Services:Ad-hoc and ACMI providers absorb seasonal demand volatility through short-term lease structures. Wet lease arrangements serve peak periods where operational control transfers amplify lessor revenue.
- Private Operators:Corporate flight departments and ultra-high-net-worth individuals demand bespoke cabin configurations. This segment accepts higher lease factors for customization flexibility and rapid deployment.
Commercial airlines anchor lessor portfolios today; cargo carrier lease commitments are expanding most quickly on e-commerce logistics growth.
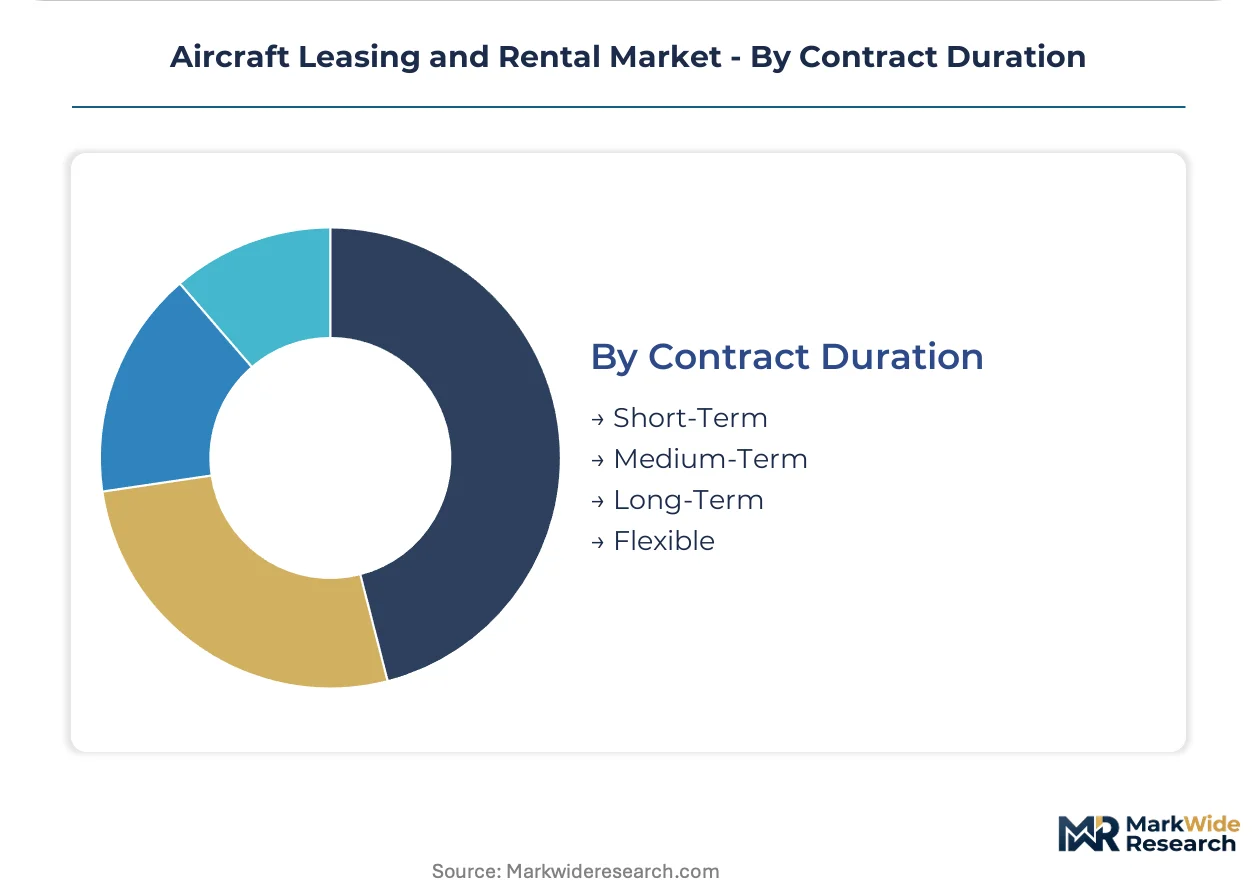
Contract Duration:
Maturity profiles segment the market into speculative forward positions, committed yield streams, and adaptive structures responding to demand volatility.
- Short-Term:Contracts under 12 months serve seasonal peaks, maintenance bridging, and new market entry testing. Wet lease dominates this duration band.
- Medium-Term:2-5 year structures balance commitment security with remarketing optionality. Vietnam and Philippines low-cost carriers favor this band as fleet plans remain 40% below regional peers.
- Long-Term:10-12 year commitments lock in lease rate factors and residual value assumptions. Network carriers anchor lessor portfolios through these arrangements.
- Flexible:Extension options, early return clauses, and purchase rights embed contingent decision points. ICAO CORSIA framework is compressing lease rate factors for older-generation aircraft and accelerating portfolio turnover toward next-engine technology.
Long-term contracts secure the largest capital deployment today; flexible structures are gaining traction fastest as regulatory uncertainty reshapes fleet planning horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's domestic aviation capacity doubles while Indonesia's low-cost carriers expand leased fleets faster than owned assets, revealing divergent growth trajectories across emerging aviation corridors.
India
Domestic carriers triple monthly lease commitments for narrow-body aircraft to capture slot expansion at Delhi, Mumbai, and Bengaluru greenfield terminals. The country's PLI scheme for aircraft maintenance, repair and overhaul infrastructure accelerates lessor confidence in local technical capability. The Delhi-Mumbai Industrial Corridor anchors logistics connectivity supporting aviation supply chain clustering.
Indonesia
Low-cost carriers across the archipelago expand leased fleets faster than owned assets as route networks penetrate secondary cities. DGFT regulations governing cross-border aircraft registration create compliance complexity that BOC Aviation navigates through established local partnerships. Jakarta's Soekarno-Hatta International Airport cluster concentrates lessor technical administration functions.
Vietnam
Low-cost carrier fleet plans remain 40% below regional peers, offering first-mover placement advantages for lessors with established Asia-Pacific relationships. The country's national aviation regulator maintains type certification alignment with EASA standards to facilitate lessor portfolio fluidity. Ho Chi Minh City's Tan Son Nhat International Airport precinct hosts emerging technical asset management service concentration.
Philippines
Seasonal crew shortages expand lessor revenue per airframe through wet lease arrangements transferring full operational control. The Civil Aviation Authority of the Philippines enforces maintenance documentation standards that lessors must integrate into digital lease administration platforms. Manila's Clark International Airport freeport zone attracts lessor regional headquarters seeking regulatory sandbox advantages.
Ireland
Avolon and AerCap Holdings N.V. leverage Dublin's aircraft leasing domicile infrastructure to structure cross-jurisdictional portfolio diversification. The EU CSRD sustainability reporting mandate forces disclosure of Scope 3 emissions from leased asset operations, restructuring portfolio composition toward younger aircraft. Shannon's aviation services cluster supports technical records digitization for end-of-lease transition efficiency.
Aircraft Leasing and Rental Market Vendor Landscape
Irish-domiciled lessors anchor the scale tier; Asia-Pacific specialists hold relationship-driven positioning across emerging aviation corridors. The market consolidates around three strategic archetypes: global diversified portfolios, regional relationship specialists, and niche technical asset managers. Competitive moves concentrate on portfolio turnover acceleration toward next-generation aircraft and digital lease administration platform deployment.
Among Ireland-based lessors, AerCap Holdings N.V., Avolon, and SMBC Aviation Capital exemplify the scale-driven archetype through diversified wide-body and narrow-body placement capability. These entities occupy positions defined by residual value risk absorption capacity and cross-jurisdictional regulatory navigation. Asia-Pacific relationship concentration distinguishes BOC Aviation, which represents the regional specialist archetype through deep operator connectivity across China, Indonesia, and Vietnam. Dubai Aerospace Enterprise anchors Middle East-Africa corridor positioning. Nordic Aviation Capital exemplifies the regional jet specialist archetype through sub-100 seat turbofan concentration.
| Leading Market Players |
|---|
| Avolon |
| BBAM Aircraft Leasing & Management |
| AerCap Holdings N.V. |
| Dubai Aerospace Enterprise |
| Aviation Capital Group |
| SMBC Aviation Capital |
| BOC Aviation |
| Nordic Aviation Capital |
| Air Lease Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed lessors with state-bank funding anchors anchor supply discipline across the aircraft leasing market, compressing lease rate spreads for older-generation airframes while amplifying pricing power for next-engine technology portfolios. This ownership concentration feeds directly into supply chain configuration, as lessor procurement timelines synchronize with OEM production slots at Airbus and Boeing facilities.
Pricing Analysis
Capacity additions in India's domestic aviation corridor are reshaping price floors for narrow-body operating leases as carriers triple monthly commitments to capture slot expansion. Lease rate factors stratify across new-generation A320neo and 737 MAX assets, older pre-2020 airframes, and wet-lease operational packages with crew provision. Pricing pressure stems from EU ETS carbon pricing penalizing pre-2020 generations and compressing residual value assumptions. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while Gulf network carriers accept premium lease factors for wide-body fleet commonality.
Supply Chain Analysis
Titanium and composite airframe components rest on Japanese and Chinese specialty materials producers, with engine production concentrated in US, UK, and French manufacturing clusters. Lessors source forward delivery positions through OEM orderbooks, maintenance reserves through MRO networks, and remarketing channels through technical asset managers. Supply chain risk centers on single-source vulnerability for certain engine types subject to pending FAA airworthiness directives. Distribution runs through Dublin and Singapore domicile structures into operator fleets across Asia-Pacific emerging aviation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by carrier demand shifts toward CORSIA-compliant new-generation aircraft with verified carbon intensity data. Premium specifications now command measurable lease rate premiums over pre-2020 airframes facing residual value compression.
For Market Incumbents: Anticipate regulatory-driven portfolio turnover by accelerating sale-leaseback arrangements with carriers holding A320neo and 737 MAX fleets. Defend against emerging technical asset managers unbundling maintenance reserve functions by embedding predictive maintenance digital platforms directly into lease structures. Vertical integration into blockchain-based maintenance documentation compresses end-of-lease transition friction and displaces third-party technical administrators. For New Entrants and Emerging Players: Vietnam and Philippines low-cost carriers remain 40% below regional fleet penetration, offering white-space placement opportunity for lessors with established Asia-Pacific regulatory navigation capability. Target cargo carrier conversions serving e-commerce logistics networks as the most penetrable segment given AerCap's wide-body concentration with integrators. Enter through digital lease administration platforms that bypass traditional broker channels and capture direct airline contracting relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional jet specialists with sub-100 seat turbofan concentration and limited next-generation transition capability. Long-term viability across the analysis window favors lessors with diversified domicile structures spanning Ireland, Singapore, and Hong Kong regulatory frameworks. Monitor ICAO CORSIA implementation pace as the primary inflection signal for portfolio composition shifts and residual value repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Next-Generation Fleet Transition | ICAO CORSIA compliance preserves residual values for A320neo and 737 MAX assets against pre-2020 generation compression. |
| Digital Lease Administration Platform | Blockchain-based maintenance reserve tracking displaces traditional broker channels and compresses transaction friction. |
| Asia-Pacific Relationship Deepening | Established operator connectivity across India, Indonesia, and Vietnam unlocks first-mover placement in underpenetrated markets. |
| Sustainable Aviation Fuel Certification | SAF-compatible engine credentials capture EU Green Deal blending requirement premiums in lease rate negotiations. |
| Technical Records Digitization | Digital twin integration accelerates end-of-lease transitions and reduces dispute resolution costs with Southeast Asian operators. |
Methodological Framework
Bottom-up carrier fleet planning modeling reconciled against top-down lessor orderbook tracking forms the analytical core of this study. Primary interviews with aircraft leasing executives, airline fleet planning directors, MRO technical managers, and aviation regulatory specialists combined with secondary validation from FAA airworthiness directives, EASA type certification databases, ICAO CORSIA implementation documents, and OEM delivery disclosure filings. This triangulation approach cross-checks lease commitment velocity against production slot allocation and remarketing channel liquidity.
Input-output matrices connect aircraft generation segmentation, lease mechanism type, and customer credit profile to derive deployment timelines and capital commitment patterns across the projection horizon. Segmentation dimensions span narrow-body versus wide-body asset classes, operating versus financial versus wet lease structures, commercial airline versus cargo carrier versus charter service customer types, and short-term versus medium-term versus long-term contract durations. CAGRs emerge from lease rate factor trajectories, fleet expansion plans at named carriers, and regulatory compliance deadlines reshaping portfolio turnover.
Underlying measurement precision varies by segment; narrow-body lease commitments and India domestic carrier expansion carry tighter precision than very large aircraft placements and private operator bespoke configurations. Forecasts reflect documented assumptions regarding CORSIA phase-in timing, OEM delivery schedule realization, and carbon pricing trajectory evolution. Regulatory implementation delays, titanium input cost volatility, and cross-jurisdiction repossession enforcement variability warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Helicopter Flight Control Systems Market
Aircraft
GCC General Aviation Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Aircraft Ailerons Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Firefighting Aircraft Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Middle-East Aviation Market
Aircraft
America Attack Helicopter Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Military Fixed-Wing Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Europe Light and Very Light Jets Market