
 US Aviation Market | 2026-2036
US Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
US Aviation Market Outlook
Capital-intensity divergence between legacy airframers and agile technology suppliers is reorganizing supplier tier structures across the US aviation industrial base. The Boeing Company leverages its integrated defense-commercial manufacturing footprint to sustain dual-use engineering advantages. Lockheed Martin Corporation anchors classified aerospace programs with specialized low-rate production capabilities that competitors struggle to replicate. Northrop Grumman Corporation differentiates through autonomous systems integration, positioning its portfolio for next-generation combat aircraft architectures.
US aviation encompasses the design, manufacture, operation, and servicing of manned and unmanned aircraft systems operating within national airspace, with turbine engines generating thrust through Brayton-cycle thermodynamics and composite materials reducing airframe weight by substantial margins versus aluminum alloys. Commercial aircraft command the largest value pool among product types, though drones represent the fastest-expanding segment driven by beyond-visual-line-of-sight regulatory approvals. Airlines dominate end-user demand structurally, while government agencies concentrate procurement in defense and homeland security applications with long program cycles and stringent qualification requirements.
FAA regulations govern airworthiness certification and operational standards, while EPA emissions frameworks constrain engine pollutant thresholds and OSHA mandates workplace safety protocols across manufacturing and MRO facilities. NHTSA coordinates with FAA on urban air mobility vehicle integration, creating overlapping jurisdiction for emerging eVTOL platforms. Stakeholders must monitor how rapidly evolving airspace integration rules for autonomous systems reshape competitive access and capital allocation priorities.
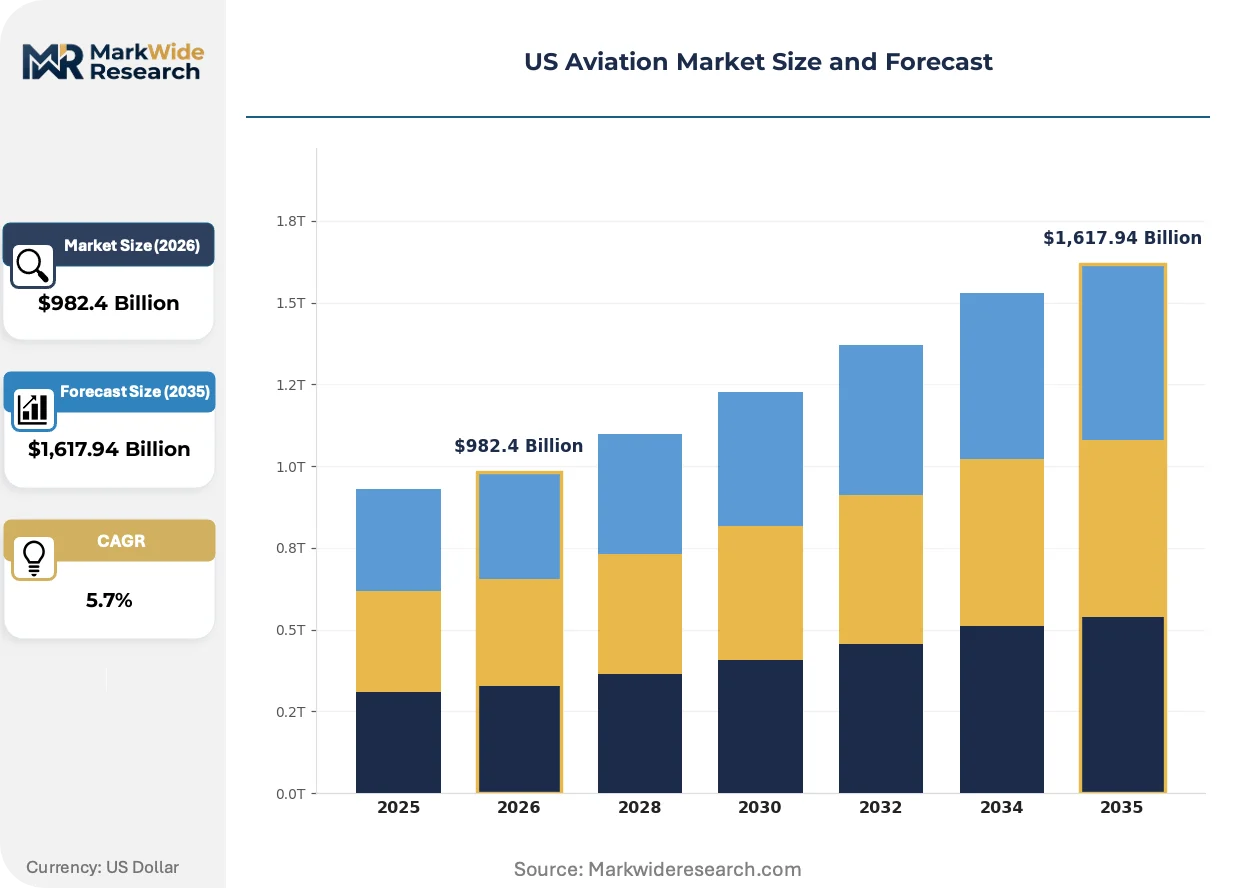
Market Dynamics
NextGen avionics mandates from the FAA are forcing fleet-wide retrofit cycles while e-commerce logistics demand pulls freighter conversions, creating simultaneous pressure on airframe supply chains and MRO capacity allocation across the US.
Growth Catalysts
- NextGen Avionics Mandates:FAA equipage requirements for ADS-B Out and PBN navigation are sustaining demand for retrofit engineering services and certified component manufacturing.
- E-Commerce Logistics Pull:Parcel carriers are expanding dedicated freighter fleets to capture overnight delivery demand from Amazon, Walmart, and regional fulfillment networks.
- Southwest and Southeast Hub Concentration:Dallas-Fort Worth, Atlanta, and Phoenix are absorbing disproportionate fleet basing and maintenance investment, concentrating supplier ecosystems in these corridors.
Market Restraints
- Titanium and Nickel Superalloy Supply Concentration:Critical engine and airframe materials depend on limited domestic smelting capacity and foreign sponge suppliers, exposing producers to price volatility.
- Certification Timeline Friction:FAA type certification and production certificate amendments impose multi-year validation cycles that compress returns on new platform investments.
- Skilled Technician Scarcity:A&P mechanic and avionics specialist pipelines are insufficient to match fleet expansion and retirement replacement needs, constraining MRO throughput.
Strategic Opportunities
- Unmanned Systems Airspace Integration:FAA Part 107 expansion for beyond-visual-line-of-sight operations is opening commercial inspection and cargo delivery applications.
- Sustainable Aviation Fuel Infrastructure:IRA production tax credits and EPA renewable fuel standards are incentivizing SAF offtake agreements and airport fueling system upgrades.
- Digital Thread Manufacturing:Convergence of model-based systems engineering and automated fiber placement is compressing development cycles for composite airframe components.
Industry Challenges
- Legacy System Integration Complexity:New avionics architectures must interface with analog-era wiring and hydraulics, multiplying software verification burdens and failure mode analysis.
- Supply Chain Reconfiguration Friction:Post-pandemic reshoring initiatives require qualifying alternative forging and casting sources, extending lead times for flight-critical hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Aviation Market |
| Market Size in 2026 | $982.4 Billion |
| Market Size in 2035 | $1,617.94 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Business Jets, Helicopters, Drones End User: Airlines, Government Agencies, Private Owners, Cargo Operators Technology: Fly-by-Wire, Avionics, Turbine Engines, Composite Materials Service Type: Maintenance, Repair, Overhaul, Ground Handling |
| Companies Covered | The Boeing Company, Lockheed Martin Corporation, General Dynamics Corporation, Textron Inc., Airbus SE, Northrop Grumman Corporation, American Airlines, Delta Air Lines, United Airlines, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Aviation Market Strategic Shifts
Digital manufacturing and autonomous flight architectures are restructuring how aircraft are designed, certified, and operated, with regulatory frameworks racing to match technical capabilities.
Additive manufacturing is decomposing traditional titanium and aluminum component supply chains by enabling topology-optimized brackets, ducts, and structural nodes printed from powder feedstock. Tier-one suppliers and engine OEMs are adopting electron beam and laser powder bed systems for low-volume flight hardware, collapsing lead times from months to weeks while reducing material scrap rates.
FAA Reauthorization Act provisions on urban air mobility are mandating new operational rules for eVTOL platforms, forcing coordination with NHTSA on ground vehicle interface standards. Manufacturers seeking Part 135 commuter certification must demonstrate equivalent safety levels to rotorcraft while satisfying EPA noise contours, concentrating early commercial deployment in designated corridors around Dallas, Los Angeles, and Miami.
Airline technical procurement is consolidating vendor relationships through integrated power-by-the-hour contracts that bundle component supply, repair management, and logistics under single accountability. MRO providers and OEM service divisions are capturing expanded scope as carriers outsource engineering and inventory risk, with Southwest and ultra-low-cost operators leading this transition domestically.
US Aviation Market Segmentation
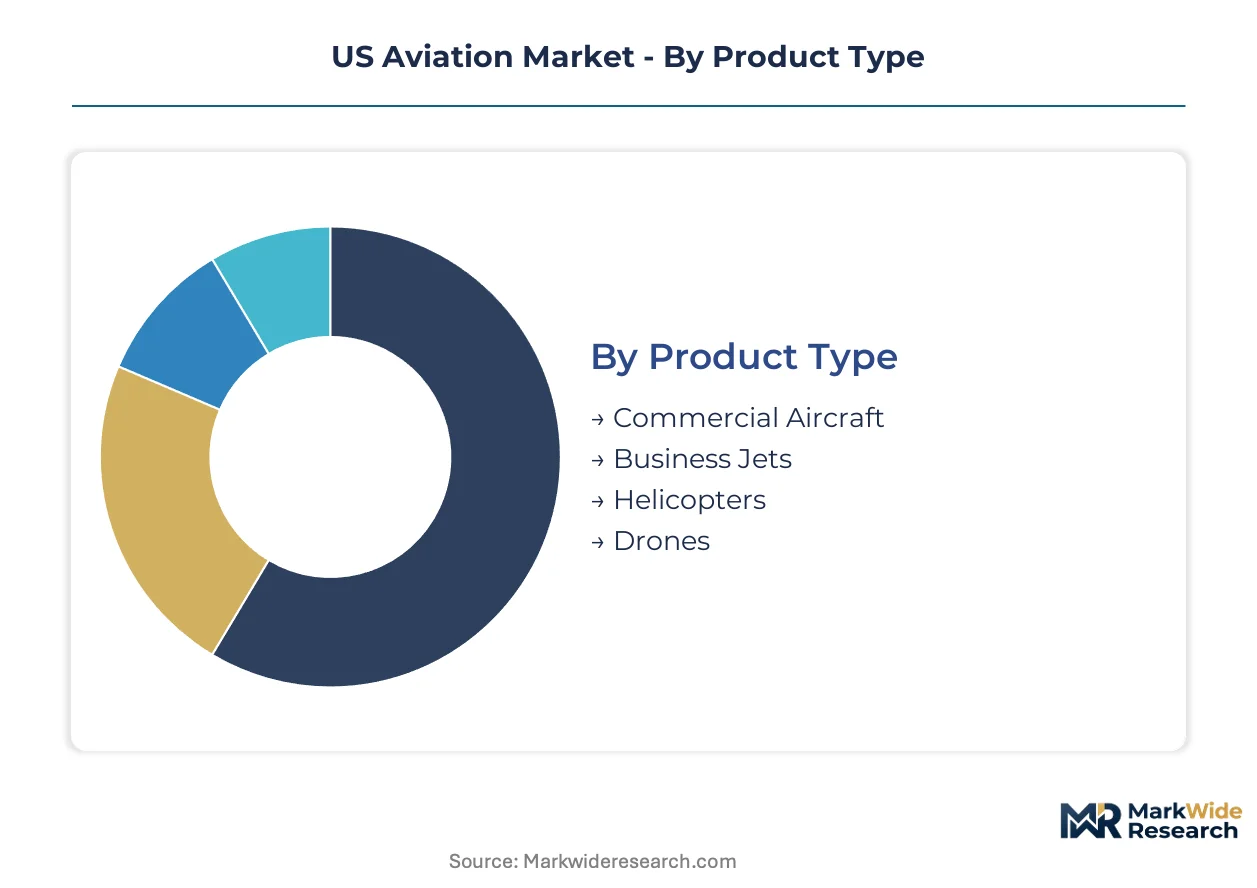
Segmentation in US aviation reveals how capital flows concentrate around regulatory mandates and operational scale. Procurement patterns diverge sharply between commercial fleet operators seeking volume discounts and government buyers prioritizing qualification rigor over unit economics.
Product Type:
Margin pools concentrate in platforms with the longest production runs and deepest aftermarket service attach rates.
- Commercial Aircraft:Twin-aisle and narrow-body airframes dominate manufacturing throughput, with final assembly lines in Washington and South Carolina absorbing the majority of domestic aerospace employment. Airlines in the Southwest and Southeast corridors are absorbing delivery slots fastest, though supply chain constraints on engines and avionics are stretching lead times.
- Drones:Beyond-visual-line-of-sight approvals under FAA Part 107 are unlocking commercial inspection and cargo delivery applications. Agricultural spraying operations in California's Central Valley and infrastructure monitoring along Gulf Coast petrochemical corridors are pulling fixed-wing and multi-rotor unit demand.
- Business Jets:Fractional ownership programs and corporate flight departments sustain demand for super-midsize and large-cabin platforms.
- Helicopters:Offshore energy transport and emergency medical services anchor the installed base, with law enforcement configurations representing a stable replacement cycle.
Commercial Aircraft holds installed capacity. Drones is rotating up the share rankings.
End User:
Volume concentration tracks operational scale, with the largest fleet operators commanding pricing leverage on both acquisition and lifetime service contracts.
- Airlines:Network carriers and ultra-low-cost operators structure procurement through power-by-the-hour agreements that bundle airframe, engine, and component coverage. Southwest's fleet standardization on Boeing 737 variants exemplifies how operational simplicity reduces inventory complexity and MRO turnaround times.
- Cargo Operators:Dedicated freighter fleets are expanding to capture e-commerce logistics demand, with conversions of passenger airframes and factory-built cargo variants both contributing to feedstock. Amazon Air and UPS are driving narrow-body freighter acquisitions, while integrators prioritize wide-body lift for trans-Pacific lanes.
- Government Agencies:Defense and homeland security procurement operates on multi-year program cycles with stringent qualification requirements that exclude commercial suppliers lacking security clearances.
- Private Owners:Individual and corporate flight departments sustain demand for piston and light turbine aircraft, with flight training operations representing a countercyclical demand buffer.
Airlines command the dominant revenue share. Cargo Operators are climbing the fastest as e-commerce logistics reshapes fleet planning priorities.
Technology:
Development cost structures favor platforms where digital architectures can iterate without hardware redesign cycles.
- Avionics:FAA NextGen mandates for ADS-B Out and performance-based navigation are sustaining retrofit demand across legacy fleets. Collins Aerospace and Honeywell are capturing upgrade programs through integrated flight deck offerings that reduce pilot workload and enable required navigation performance approaches.
- Composite Materials:Automated fiber placement and resin transfer molding are displacing aluminum in primary structure, with Boeing 787 and Airbus A350 programs demonstrating weight reductions that translate to fuel burn advantages. Toray and Hexcel supply carbon fiber prepreg to airframe manufacturers under long-term offtake agreements.
- Turbine Engines:Geared turbofan architectures from Pratt & Whitney and high-bypass designs from GE Aviation dominate commercial propulsion, with aftermarket service representing the majority of lifetime revenue.
- Fly-by-Wire:Digital flight control systems with envelope protection are standard on new transport category aircraft, though retrofit complexity limits adoption on legacy platforms.
Avionics carries the largest retrofit opportunity. Composite Materials is gaining share fastest as new programs ramp production rates.
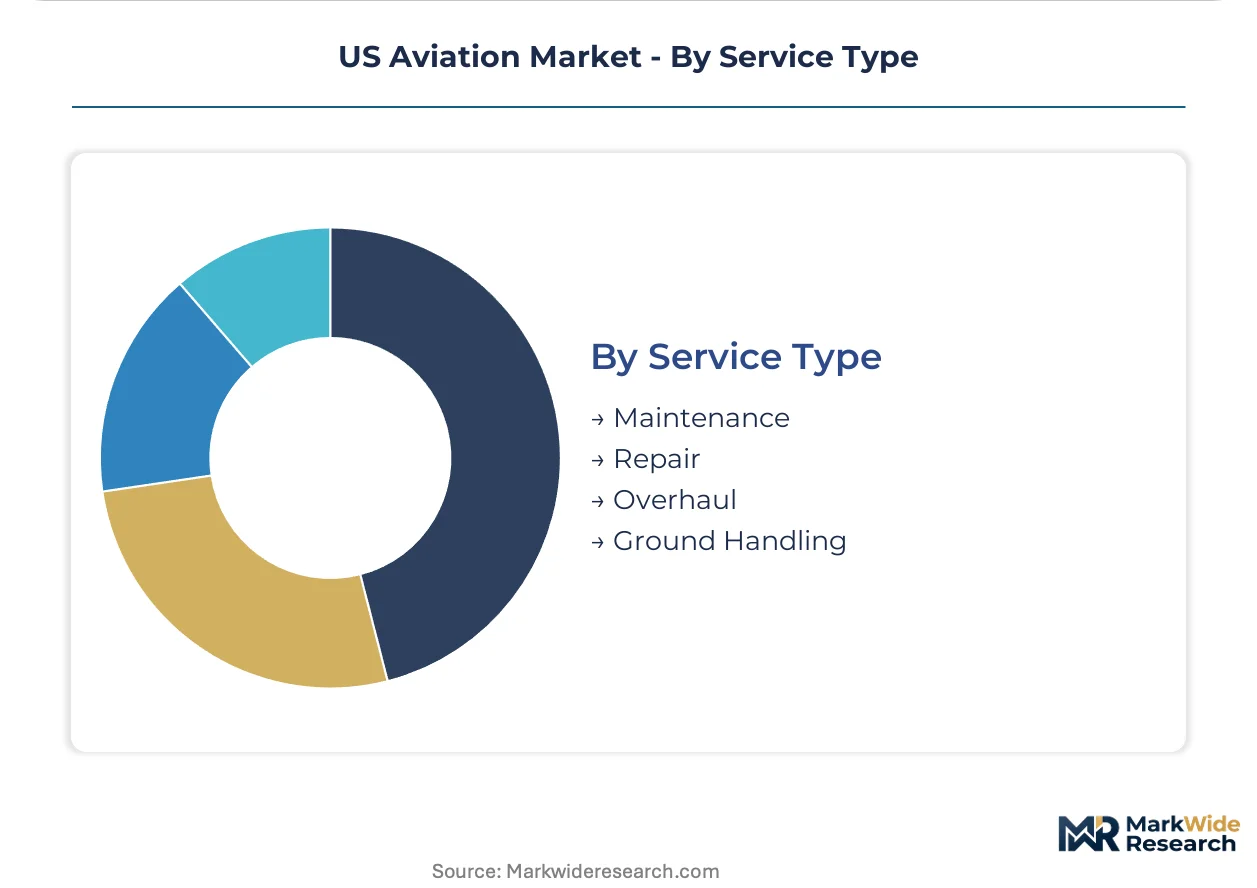
Service Type:
Revenue stability correlates with fleet age profiles, with mature aircraft types generating predictable component replacement cycles.
- Maintenance:Line maintenance at hub airports and base maintenance at dedicated facilities absorb the majority of labor hours, with A&P mechanic scarcity constraining throughput at Southwest and Southeast MRO clusters. Delta TechOps and American's Tulsa facility are expanding capacity to capture third-party work.
- Overhaul:Engine shop visits and landing gear refurbishment operate on condition-based intervals, with OEM service divisions and independent shops competing on turnaround time guarantees. GE Aviation and Pratt & Whitney are verticalizing overhaul capacity to capture margin from their installed propulsion bases.
- Repair:Component repair and structural modification sustain specialized shops with FAA DER-approved engineering capabilities, though parts manufacturer approval processes create friction for alternative suppliers.
- Ground Handling:Ramp services and cargo handling operate on airport concession agreements with thin margins, consolidated through Swissport and dnata acquisitions.
Maintenance holds installed capacity. Overhaul is rotating up the share rankings as engine fleets mature and shop visit intervals compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Georgia corridors where airline hub density and MRO cluster proximity compress supplier margins, while Pacific Northwest airframe manufacturing commands premium rates through Boeing's integrated supplier ecosystem.
Southwest Corridor
Dallas-Fort Worth and Phoenix absorb disproportionate fleet basing as American Airlines and Southwest expand narrow-body operations. FAA NextGen equipage deadlines accelerate retrofit demand across legacy aircraft stationed at these hubs. Maintenance clusters in Tulsa and Dallas-Fort Worth are absorbing third-party MRO contracts from network carriers seeking labor cost arbitrage.
Southeast Hub Belt
Atlanta anchors Delta's technical operations while Florida's cargo gateways feed Amazon Air and UPS freighter networks. EPA emissions frameworks constrain engine pollutant thresholds for aircraft operating through Miami and Orlando corridors. Charleston's Boeing final assembly line and surrounding composite supplier parks concentrate advanced manufacturing employment in South Carolina.
Pacific Northwest Manufacturing Core
Washington state's Everett and Renton facilities produce twin-aisle and narrow-body airframes under long-term airline backlogs. OSHA mandates workplace safety protocols across Boeing's vertically integrated manufacturing and supplier quality audit programs. Oregon's automated fiber placement specialists and Washington's toray carbon fiber prepreg operations form a captive composite materials ecosystem.
California Technology Corridor
Urban air mobility developers cluster around Los Angeles and San Francisco pursuing FAA Part 135 commuter certification for eVTOL platforms. NHTSA coordinates with FAA on ground vehicle interface standards for emerging electric vertical takeoff aircraft. San Diego's unmanned systems integrators and Mojave's flight test ranges support autonomous aircraft development programs.
Mountain West MRO Expansion
Phoenix and Salt Lake City maintenance bases capture overflow from congested coastal facilities as airlines consolidate vendor relationships. Skilled technician scarcity constrains A&P mechanic throughput despite technical school expansion in Arizona and Utah. Denver's cargo hub expansion feeds e-commerce logistics demand from Rocky Mountain distribution centers.
US Aviation Market Competitive Environment
Concentration sits with integrated defense-commercial manufacturers and network carriers with captive technical operations. The vendor base organizes into three tiers: prime contractors with security clearance access, airline-affiliated MRO divisions, and specialized component suppliers. Dominant competitive moves include vertical integration of overhaul capacity and strategic consolidation of power-by-the-hour service contracts.
Within the prime contractor tier, The Boeing Company and Lockheed Martin Corporation exemplify dual-use engineering advantages spanning commercial and classified programs. Northrop Grumman Corporation occupies a position in autonomous systems integration. Among network carriers, Delta Air Lines and American Airlines anchor the airline-affiliated MRO segment through technical operations divisions capturing third-party maintenance demand.
| Leading Market Players |
|---|
| The Boeing Company |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Textron Inc. |
| Airbus SE |
| Northrop Grumman Corporation |
| American Airlines |
| Delta Air Lines |
| United Airlines |
| Others |
Value Chain & Pricing Dynamics
Boeing's Everett and Renton final assembly lines absorb capital at scale economies that tier-two suppliers cannot replicate, compressing margins across the Pacific Northwest manufacturing core while concentrating pricing power in airframe OEM hands. FAA certification burdens and titanium sponge import dependencies tether cost floors to regulatory timeline friction and foreign material sourcing, preventing price erosion even as airline procurement consolidates through power-by-the-hour bundling.
Pricing Analysis
Configured-to-order pricing for custom flight deck configurations and interior completions commands substantial premiums over standard catalog configurations. The dominant pricing structure runs through long-term contract-based offtake agreements with escalation clauses tied to labor indices and raw material baskets. Price differentiation rests on airworthiness certification tier and aftermarket service bundling, with DER-approved repair stations capturing margin premiums over non-certified competitors. Pricing pressure stems from airline fleet standardization strategies that compress supplier margins through volume concentration. Ultra-low-cost carriers exhibit highest price sensitivity, while government defense procurement shows lowest sensitivity due to qualification rigor requirements.
Supply Chain Analysis
Russian titanium sponge export restrictions and Ukrainian semi-finished product disruptions have choked aerospace-grade material flows since early 2022, forcing US producers toward Japanese and Kazakh alternative sourcing. Geographic supply concentration centers on Japan for carbon fiber prepreg, China for rare earth processing, and domestic Washington state for final airframe assembly. Raw material dependencies span titanium sponge, nickel-based superalloys, and Toray carbon fiber feedstock. Single-source vulnerability runs through qualified forging sources for turbine disk production, where FAA production certificate amendments require multi-year requalification cycles. Distribution runs through Boeing's integrated supplier quality audit programs and airline-affiliated MRO technical operations divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US aviation market tracks a cyclical recovery anchored to FAA NextGen retrofit mandates and e-commerce freighter fleet expansion, with capital deployment accelerating as airline balance sheets repair and interest rate pressure moderates.
For Market Incumbents: Fortify MRO capacity in Dallas-Fort Worth and Atlanta corridors to capture overflow from congested coastal facilities as Southwest and Delta consolidate vendor relationships. Deepen captive supply of titanium forgings through backward integration into qualified domestic sources, mitigating exposure to foreign sponge price volatility. Lockheed Martin and Northrop Grumman should accelerate security clearance pipeline investments to defend classified program access against emerging autonomous systems specialists. For New Entrants and Emerging Players: Lead with beyond-visual-line-of-sight drone services in California Central Valley agricultural corridors and Gulf Coast petrochemical infrastructure monitoring, where FAA Part 107 expansion has opened commercial inspection applications with lower certification barriers than manned aviation. Target the SAF infrastructure buildout as the most penetrable segment, leveraging IRA production tax credits to secure offtake agreements with airport fueling system operators. Pursue OEM partnerships for integrated avionics retrofit packages rather than standalone component sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among airline-affiliated MRO technical operations divisions with power-by-the-hour contracts, where Delta TechOps and American's Tulsa facility demonstrate cash flow stability across fleet cycles. Over the projection horizon, acquisition targets should emphasize DER-approved engineering capabilities and FAA production certificate holdings that cannot be replicated quickly. Monitor FAA reauthorization progress on urban air mobility operational rules as the inflection signal for eVTOL platform commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| NextGen Avionics Retrofit Program | Collins Aerospace and Honeywell capture upgrade demand through integrated flight deck offerings that satisfy FAA ADS-B Out mandates. |
| Freighter Conversion Capacity Expansion | Amazon Air and UPS narrow-body acquisitions pull feedstock through passenger-to-cargo modification lines at Southeast MRO clusters. |
| Sustainable Aviation Fuel Infrastructure Buildout | IRA production tax credits incentivize SAF offtake agreements with Dallas-Fort Worth and Los Angeles airport fueling system operators. |
| Autonomous Systems Airspace Integration | FAA Part 107 beyond-visual-line-of-sight approvals unlock commercial inspection applications for California agricultural spraying operations. |
| Composite Manufacturing Digital Thread Investment | Automated fiber placement specialists in Washington and Oregon compress development cycles for Boeing 787 successor programs. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fleet planning executives, MRO operations directors, FAA certification engineers, and titanium procurement specialists; and secondary validation through FAA type certification databases, airline 10-K filings, Bureau of Transportation Statistics traffic data, and Department of Commerce aerospace trade flows. Bottom-up triangulation cross-checked supplier revenue disclosures against top-down fleet projection models built on Boeing and Airbus delivery backlogs.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, end user, technology, and service type dimensions, with additional granularity on regional hub concentration patterns. CAGRs were derived from regression analysis of historical delivery data against fleet age profiles and replacement cycle assumptions. Industry-specific forecast inputs incorporated FAA NextGen equipage deadline schedules and e-commerce logistics demand trajectories from parcel carrier capital expenditure disclosures.
The analysis sits within stated boundaries; outcomes outside sustained FAA regulatory timeline adherence and titanium sponge supply stability would require recalibration. Forecasts reflect documented assumptions regarding airline fleet standardization continuity and defense procurement authorization levels. Practitioners should keep alternative scenarios live as FAA urban air mobility rulemaking and SAF tax credit policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Military Fixed-Wing Aircraft Market
Aircraft
US Business Jet Market
Aircraft
Airplane Ailerons Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
India Aviation Market
Aircraft
Global Helicopter Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
North America Military Helicopters Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Military Helicopters Market
Aircraft
Asia-Pacific Freighter Aircraft Market