
 Aerospace Forging Market | 2026-2036
Aerospace Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Forging Market Intelligence
Additive manufacturing hybridization is reconfiguring how aerospace forgers integrate near-net-shape preforms with traditional hammer and press operations. Precision Castparts Corp. leverages captive titanium melting and ring-rolling capacity to control alloy flow from sponge to finished disc. Howmet Aerospace Inc. sustains dominance in nickel superalloy rotating components through integrated vacuum induction melting and isothermal forging cells. Bharat Forge Limited anchors expanding defense and regional jet supply relationships from its India base.
Aerospace forging subjects metallic billets to controlled compressive deformation above recrystallization temperature, yielding grain structures with fatigue resistance exceeding 100,000 cycles for turbine rotating hardware. Titanium alloy forged rings command premium positioning due to jet engine OEM demand for intermediate compressor stages with strength-to-density ratios above 165 kN·m/kg. Steel alloy forged blocks remain the mature volume base for landing gear and structural fittings where through-thickness toughness requirements exceed 75 MPa·m½. Aluminum alloy segments in wing and fuselage applications compete with advanced extrusions on weight and cost.
FAA airworthiness standards and EASA Part 21G production organization approvals govern forging process qualification, with NADCAP special process audits now mandatory for heat treatment and nondestructive testing. EPA hazardous air pollutant standards for metal finishing operations are forcing capital deployment into closed-loop quench systems and emission controls. Stakeholders must monitor how CSRD supply chain due diligence rules and ISO 14064 carbon accounting reshape sourcing decisions for energy-intensive press and hammer operations.
Market Dynamics
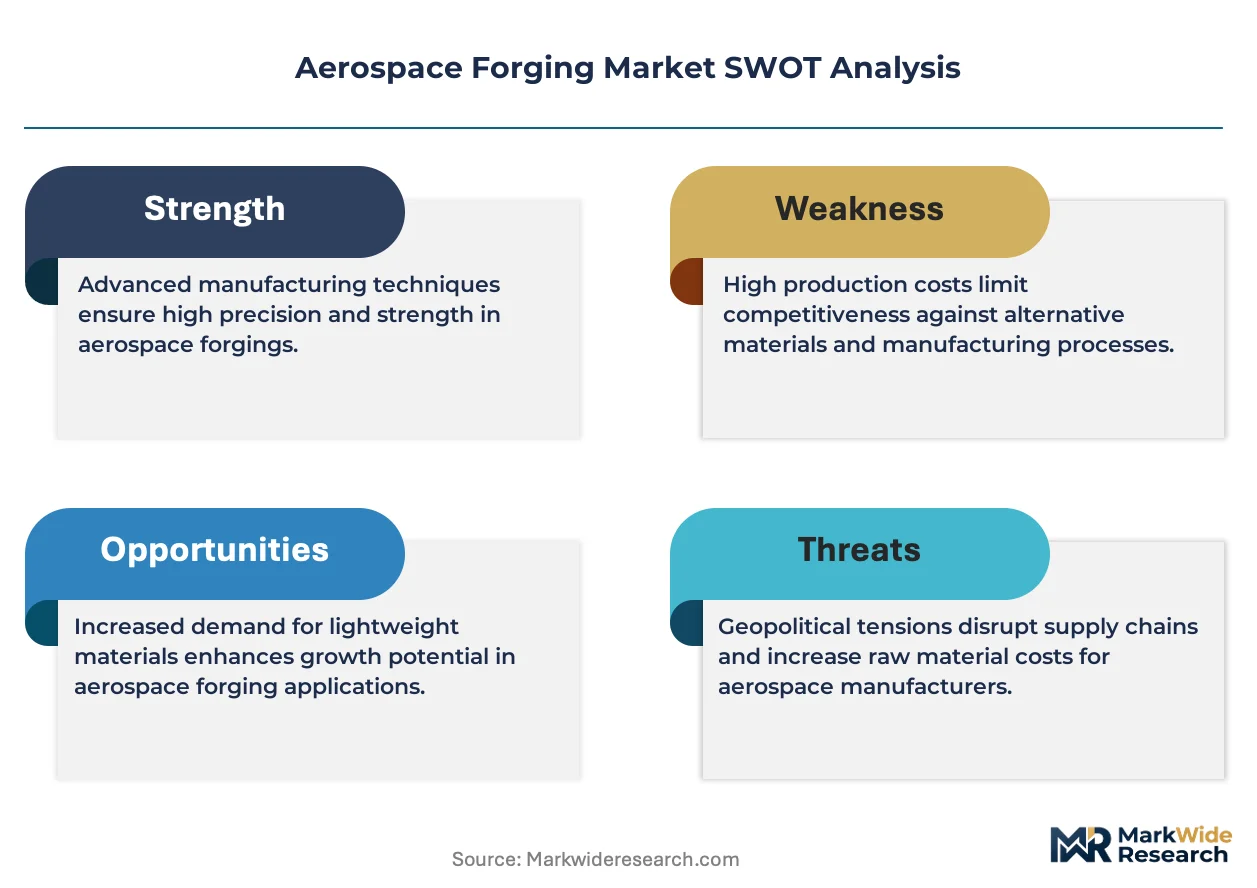
Fleet renewal cycles and additive manufacturing hybridization are compressing traditional forging timelines while tightening material traceability mandates from FAA and EASA certification bodies.
Growth Catalysts
- Commercial aviation fleet replacement:Airlines are retiring aging narrow-body and wide-body aircraft, accelerating procurement of forged turbine discs and structural components for next-generation platforms.
- FAA airworthiness directives:Stringent certification standards for additive-manufacturing hybrid components are mandating enhanced material traceability, favoring established forgers with integrated quality systems.
- Titanium alloy demand:Jet engine OEM specifications for intermediate compressor stages with superior strength-to-density ratios are pulling premium forged ring volumes.
Market Restraints
- Sponge and alloy input volatility:Titanium sponge prices fluctuate with Russian and Ukrainian supply disruptions, compressing margin predictability for non-integrated forgers.
- US supply concentration:Domestic forging capacity anchors around Boeing and defense prime clusters, creating geographic dependency risk for global aerospace programs.
- Aluminum extrusion substitution:Advanced extrusion technologies compete for wing and fuselage applications on weight and cost, capping forged aluminum growth.
Strategic Opportunities
- India defense and regional jet expansion:Bharat Forge and domestic competitors are capturing expanding procurement from indigenous fighter programs and regional aircraft platforms.
- CSRD supply chain due diligence:EU corporate sustainability reporting mandates are reshaping sourcing decisions, creating openings for forgers with ISO 14064 carbon accounting and closed-loop quench systems.
- Isothermal forging convergence:Integration of vacuum induction melting with precision press controls enables nickel superalloy rotating components with enhanced fatigue resistance.
Industry Challenges
- NADCAP special process audits:Mandatory accreditation for heat treatment and nondestructive testing extends qualification timelines and raises compliance overhead for new market entrants.
- Isothermal forging cell capex intensity:Vacuum induction melting and precision press installations demand capital deployment exceeding typical mid-tier forging operations.
- EPA hazardous air pollutant compliance:Metal finishing emission controls require closed-loop quench system investments that strain smaller forger balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Forging Market |
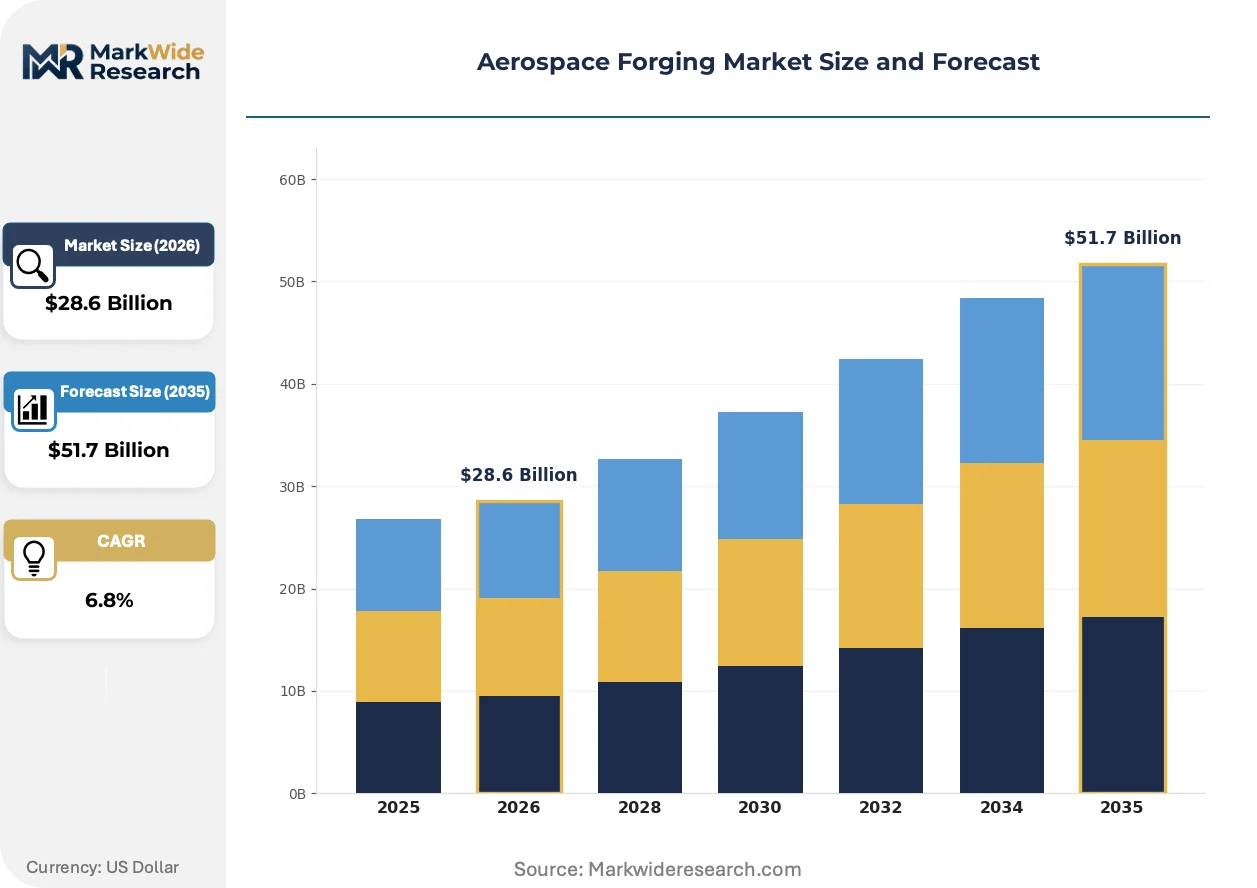
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Components, Forged Rings, Forged Blocks, Forged Shafts Material: Aluminum Alloys, Titanium Alloys, Steel Alloys, Nickel Alloys End User: Aerospace OEMs, Tier-1 Suppliers, Maintenance Providers, Defense Contractors Capacity: Low Volume, Medium Volume, High Volume, Customized |
| Companies Covered | Precision Castparts Corp., Howmet Aerospace Inc., Arconic Corporation, Jiangyin Hengrun Heavy Industries Co. Ltd., Ellwood Group Inc., Bharat Forge Limited, ATI, Larsen & Toubro Ltd., Scot Forge Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Forging Market Strategic Shifts & Innovations
Digital thread integration and regulatory carbon accounting are reconfiguring how aerospace forgers qualify processes and document alloy provenance from melt to finished component.
Digital twin process simulation is digitizing forging die design and thermal cycle optimization, allowing Howmet Aerospace and Precision Castparts to compress qualification timelines for new superalloy formulations. Engine OEMs now mandate digital thread documentation for FAA certification packages. This capability is digitizing competitive differentiation between integrated forgers and smaller tier-two suppliers lacking simulation infrastructure.
EU CSRD supply chain due diligence rules and ISO 14064 carbon accounting standards are forcing energy-intensive press and hammer operations to deploy emission monitoring and renewable power purchase agreements. Forgers serving Airbus and Safran programs face audited Scope 1 and 2 disclosure requirements. Nickel superalloy rotating component suppliers in Germany and France are retrofitting electric induction heating to replace gas-fired furnaces.
Long-term throughput contracts are displacing spot purchasing for titanium alloy forged rings as jet engine OEMs secure dedicated press capacity. Pratt & Whitney and Rolls-Royce now structure multi-year offtake agreements with volume commitments and price collars. This pattern concentrates procurement leverage with tier-one forgers possessing captive titanium melting and ring-rolling capacity in the United States and United Kingdom.
Aerospace Forging Market Segmentation
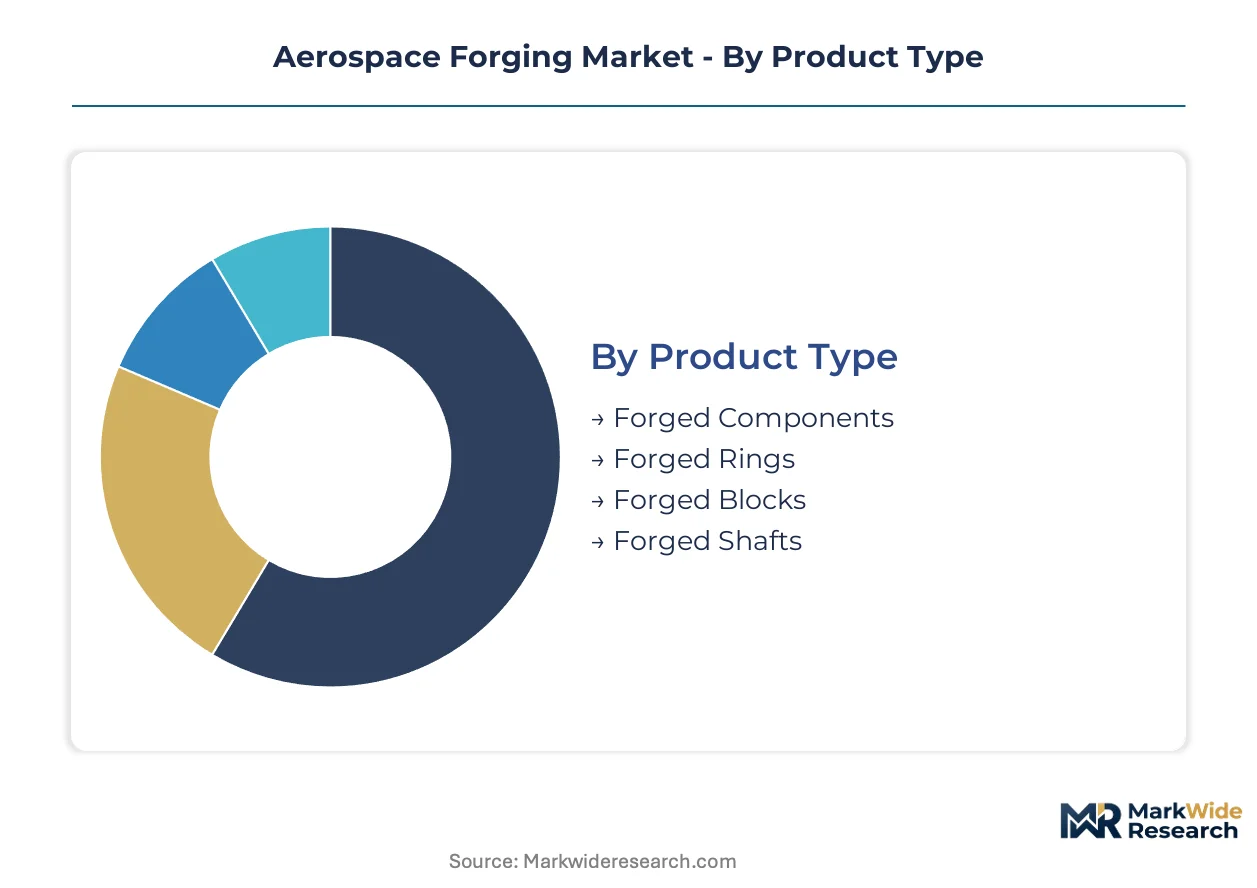
Aerospace forging segmentation maps directly to aircraft certification tiers and procurement leverage structures. Product geometry, alloy chemistry, and end-user integration depth determine margin profiles and qualification barriers across the supply base.
Product Type:
Forged components span discrete structural elements to continuous rotating hardware, with geometry dictating press selection and NADCAP process requirements.
- Forged Components:Discrete structural brackets, fittings, and actuation hardware subject to 100,000-cycle fatigue specifications. Demand concentrates in landing gear and airframe assemblies where Boeing and Airbus tier-one suppliers enforce AS9100 traceability from billet to finished part.
- Forged Rings:Continuous circumferential grain flow yields turbine disc and compressor case geometries with radial tensile properties exceeding 1,200 MPa. Jet engine OEM procurement of titanium alloy rings for intermediate compressor stages pulls dedicated ring-rolling capacity at Precision Castparts and Howmet Aerospace facilities.
- Forged Blocks:Landing gear trunnions and wing carry-through structures require through-thickness toughness above 75 MPa·m½, favoring vacuum arc remelted steel alloys.
- Forged Shafts:Drive shafts and actuator rods compete with machined bar stock on lead time and material utilization.
Established volume favors forged components; emerging adoption favors forged rings.
Material:
Alloy selection trades density against temperature capability, with cost tier separating rotating engine hardware from structural airframe applications.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr formulations deliver strength-to-density ratios above 165 kN·m/kg for compressor stages operating below 540°C. Russian and Ukrainian sponge supply disruptions have compressed margin predictability for non-integrated forgers serving Pratt & Whitney and Rolls-Royce programs.
- Nickel Alloys:Inconel 718 and Rene 41 sustain creep resistance above 650°C in high-pressure turbine discs and combustion chambers. Isothermal forging cells with vacuum induction melting integration enable grain structures with 100,000-cycle fatigue resistance demanded by FAA airworthiness directives.
- Steel Alloys:300M and AerMet 100 dominate landing gear applications where fracture toughness governs specification.
- Aluminum Alloys:7075 and 7050 wing and fuselage extrusions compete on weight and cost, capping forged aluminum growth.
Steel alloys anchor mature volume; nickel alloys are climbing the fastest on next-generation engine temperatures.
End User:
Customer type determines certification burden and contract structure, with OEM direct procurement concentrating leverage at the top tier.
- Aerospace OEMs:Boeing, Airbus, and engine primes specify material grades and approve forging sources through qualified products lists. Long-term throughput contracts with volume commitments and price collars now displace spot purchasing for critical rotating hardware.
- Defense Contractors:Lockheed Martin and Raytheon programs require ITAR compliance and domestic melting sources, restricting qualified supplier pools.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace intermediate procurement adds margin layer but reduces direct OEM leverage.
- Maintenance Providers:Aftermarket demand for replacement discs and structural elements follows fleet age demographics and FAA airworthiness directive schedules.
OEM direct procurement commands premium pricing; defense contracting imposes strictest qualification barriers.
Capacity:
Volume scale separates commodity structural hardware from specialized engine components requiring dedicated press allocation.
- High Volume:Automated hammer and press lines produce standardized landing gear fittings and structural brackets with 48-hour cycle times. Scale economies favor integrated forgers with captive billet supply.
- Customized:Single-piece isothermal forging of nickel superalloy turbine discs demands dedicated vacuum induction melting and precision press controls. Lead times extend to 26 weeks with NADCAP heat treatment and nondestructive testing overlays.
- Medium Volume:Batch production of actuator housings and transmission components balances tooling amortization against flexibility.
- Low Volume:Prototype and development work for new engine programs carries qualification cost recovery premiums.
High-volume operations capture scale returns; customized capacity secures long-term OEM offtake agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet engine OEM procurement concentrates forging demand among defense prime clusters and commercial aviation manufacturing corridors. Boeing and Airbus tier-one supply chains anchor capacity around Everett, Toulouse, and Hamburg. Long-term throughput contracts with volume commitments now displace spot purchasing across these buyer concentrations.
United States
Pratt & Whitney and GE Aerospace procurement of titanium alloy compressor rings pulls dedicated ring-rolling capacity. FAA airworthiness directives for additive-manufacturing hybrid components mandate enhanced material traceability. Everett, Washington and Hartford, Connecticut clusters host integrated forgers with captive titanium melting operations serving next-generation narrow-body programs.
United Kingdom
Rolls-Royce Defence and Civil Aerospace procurement anchors nickel superalloy rotating component demand. EASA Part 21G production organization approvals govern forging process qualification for Airbus wing carry-through structures. Sheffield and Birmingham industrial corridors concentrate isothermal forging cells with vacuum induction melting integration.
France
Safran Aircraft Engines specifications for high-pressure turbine discs drive nickel alloy forging volumes. EU CSRD supply chain due diligence rules reshape sourcing decisions for energy-intensive press operations. Le Creusot and Saint-Étienne forgers retrofit electric induction heating to replace gas-fired furnaces for Airbus A350 and Rafale programs.
Germany
MTU Aero Engines procurement of intermediate compressor stages sustains titanium ring demand amid Russian sponge supply disruptions. REACH compliance and EPA-equivalent hazardous air pollutant standards force closed-loop quench system investments. Hamburg and Munich aerospace clusters integrate digital thread documentation for EASA certification packages.
India
Indigenous fighter programs and regional aircraft platforms expand defense and commercial procurement from domestic forgers. DGFT export control frameworks and BIS material standards govern alloy traceability for HAL and DRDO supply chains. Pune and Hyderabad manufacturing corridors anchor Bharat Forge capacity for expanding airframe and engine component relationships.
Aerospace Forging Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where integrated forgers with captive melting capacity command procurement leverage with engine OEMs. Mid-tier fabricators serving structural airframe applications face margin compression from aluminum extrusion substitution and qualification overhead. Three archetypes dominate: vertically integrated superalloy specialists, titanium ring-rolling operators with sponge-to-disc control, and regional defense-focused forgers with ITAR compliance infrastructure. Competitive moves concentrate on long-term throughput contracting with volume commitments and carbon-accounting differentiation for EU CSRD compliance.
Among North American integrated operators, Precision Castparts Corp. and Howmet Aerospace Inc. occupy positions exemplifying captive titanium melting and nickel superalloy isothermal forging archetypes. Bharat Forge Limited anchors the defense-specialist tier from its India base, representing regional jet and indigenous fighter program expansion. These three entities illustrate how geographic clustering around Boeing, Airbus, and Rolls-Royce procurement centers shapes competitive positioning.
| Leading Market Players |
|---|
| Precision Castparts Corp. |
| Howmet Aerospace Inc. |
| Arconic Corporation |
| Jiangyin Hengrun Heavy Industries Co. Ltd. |
| Ellwood Group Inc. |
| Bharat Forge Limited |
| ATI |
| Larsen & Toubro Ltd. |
| Scot Forge Company |
| Others |
Cost & Logistics Intelligence
Transatlantic air freight corridors connecting titanium sponge suppliers in Russia and Ukraine to ring-rolling facilities in the United States and United Kingdom transmit input cost volatility directly into compressor disc pricing tiers. This logistics architecture concentrates procurement leverage with integrated forgers possessing captive melting capacity while forcing non-integrated suppliers into defensive margin compression.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium sponge indexation dominate procurement between jet engine OEMs and tier-one forgers. Price differentiation rests on NADCAP heat treatment accreditation status and captive vacuum induction melting capability, with certified suppliers commanding substantial premiums over tier-two competitors. Pricing pressure stems from Russian supply disruptions compressing margin predictability for non-integrated operators. Tier-1 suppliers exhibit lowest price sensitivity due to long-term throughput commitments; maintenance providers face highest sensitivity from spot purchasing exposure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure relationships between Airbus and Safran procurement teams and their nickel superalloy suppliers. Geographic concentration centers on the United States, United Kingdom, and France for rotating engine hardware; India and Germany anchor structural component supply. Raw material dependencies include titanium sponge from Russian and Ukrainian sources, nickel cathode from Indonesian refining operations, and specialty steel scrap from domestic defense programs. Single-source vulnerability around titanium sponge creates structural risk. Distribution runs through qualified products lists maintained by Boeing, Airbus, and engine primes with approved supplier pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSRD supply chain due diligence mandates are fragmenting procurement across carbon-accounting differentiated supplier tiers, creating entry niches for forgers with ISO 14064 documentation and closed-loop quench infrastructure.
For Market Incumbents: Harden titanium sponge supply security through backward integration into melting capacity or long-term offtake agreements with alternative feedstock sources. Fortify NADCAP accreditation moats against emerging Indian competitors by accelerating digital thread documentation for FAA certification packages. Aluminum extrusion substitution in wing applications and isothermal forging cell capex intensity represent dual margin pressure points requiring defensive capital allocation.
For New Entrants and Emerging Players: Establish a beachhead in regional jet and indigenous defense programs where ITAR compliance and domestic melting requirements restrict qualified supplier pools. Target India's expanding aerospace manufacturing corridors where Bharat Forge capacity constraints create procurement openings for secondary forgers. A go-to-market angle emphasizing CSRD-compliant carbon accounting and electric induction heating retrofits addresses Airbus and Safran sustainability procurement criteria.
For Investors and Strategic Acquirers: Mid-tier forgers with captive titanium ring-rolling capacity and established EASA Part 21G approvals represent priority acquisition archetypes. Long-term viability hinges on securing dedicated press capacity under multi-year OEM offtake structures. The inflection signal to monitor is Rolls-Royce and Pratt & Whitney procurement shifting from spot purchasing to volume-committed throughput contracts, concentrating leverage with integrated operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Melting Integration | Backward integration into sponge-to-disc control secures margin predictability against Russian supply disruptions. |
| Isothermal Forging Cell Deployment | Precision press and vacuum induction melting integration enables nickel superalloy rotating components with enhanced fatigue resistance. |
| NADCAP Special Process Accreditation | Mandatory heat treatment and nondestructive testing audits qualify suppliers for Boeing and Airbus tier-one procurement. |
| Digital Thread Documentation Investment | FAA certification package digitization compresses qualification timelines for new superalloy formulations. |
| CSRD Carbon Accounting Compliance | ISO 14064 disclosure and closed-loop quench systems address Airbus and Safran sustainability sourcing mandates. |
Research Approach
Initial hypotheses were tested against primary input from forging operations managers, jet engine OEM procurement directors, heat treatment process engineers, and NADCAP audit specialists and refined through secondary validation against FAA airworthiness directive filings, EASA Part 21G production organization approvals, SEC 10-K disclosures from listed aerospace suppliers, and titanium sponge trade flow data. Bottom-up capacity utilization surveys across ring-rolling and isothermal forging facilities were triangulated with top-down jet engine production forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product geometry, alloy chemistry, end-user integration depth, and capacity scale tier. CAGRs were derived from production volume elasticities against commercial aviation fleet renewal schedules and defense procurement cycles. Industry-specific forecast inputs incorporated Pratt & Whitney and Rolls-Royce narrow-body engine ramp timelines and CSRD compliance cost pass-through assumptions.
Stress conditions across titanium sponge price volatility, Russian supply disruption duration, and isothermal forging cell deployment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet renewal acceleration and additive manufacturing hybridization adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market