
 Europe Fighter Aircraft Market | 2026-2036
Europe Fighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fighter Aircraft Market Foresight
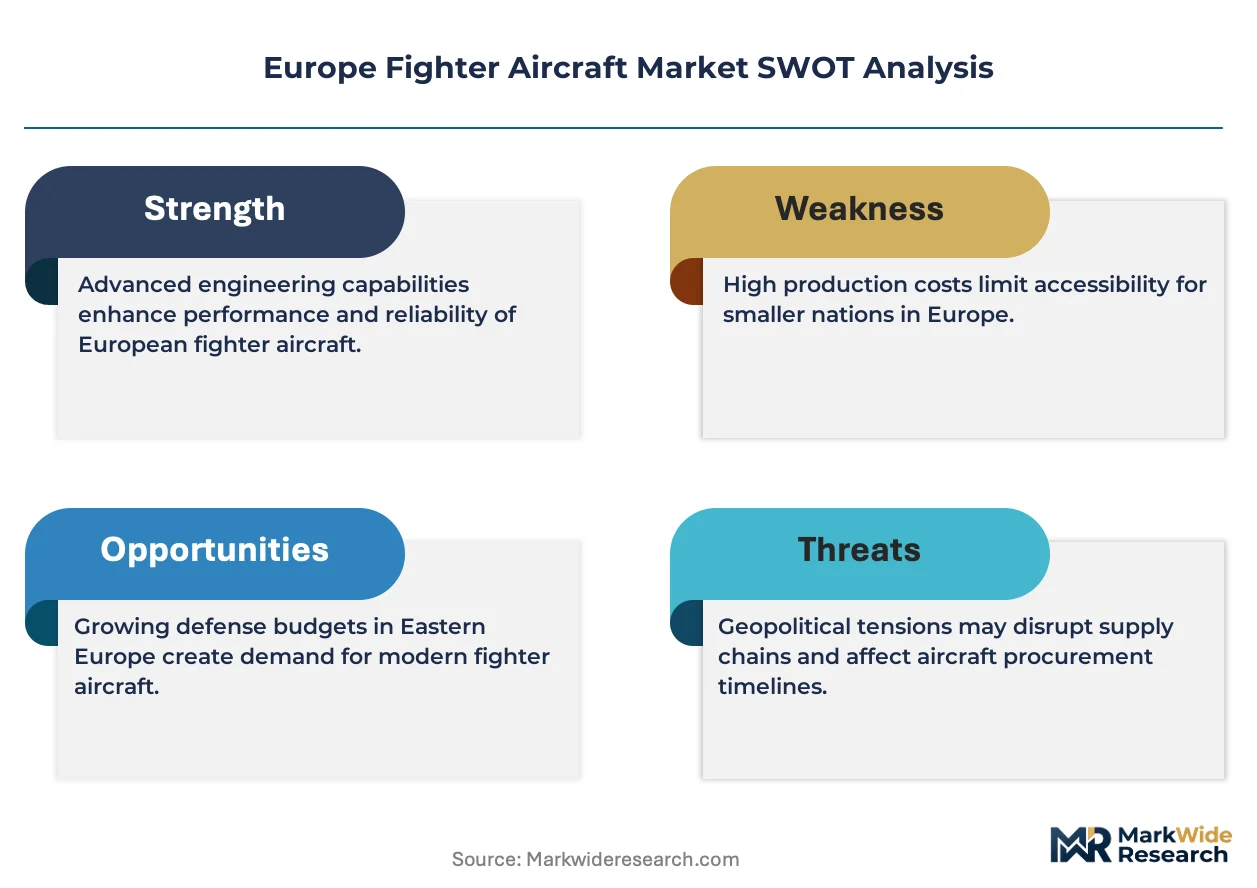
Next-generation stealth specifications are redrawing competitive requirements across European air forces. Leonardo S.p.A. leverages its Tempest partnership with BAE Systems plc and Rolls-Royce Holdings plc to anchor deep R&D commitments in sixth-generation platforms. Saab AB competes through its Gripen E series, specializing in cost-efficient multirole performance for smaller NATO members.
Fighter aircraft encompass fixed-wing military platforms engineered for air superiority, ground attack, and reconnaissance missions, typically achieving Mach 1.6-plus speeds with advanced fly-by-wire control systems and composite airframe construction. Multirole configurations now dominate procurement budgets as European ministries consolidate fleet types, while stealth technology segments absorb disproportionate development investment despite elongated certification timelines. Avionics subsystems represent the fastest-expanding technology category as open-architecture mission computers displace proprietary legacy systems.
EU Green Deal directives, EASA airworthiness standards, and NATO STANAG interoperability frameworks collectively constrain platform design while mandating sustainable aviation fuel compatibility and cross-border maintenance protocols. EMA and national defense procurement agencies enforce dual-use export controls that shape supply chain geography and partner nation access. Stakeholders must weigh collaborative program commitments against sovereign industrial base preservation as platform complexity escalates and budget cycles tighten.
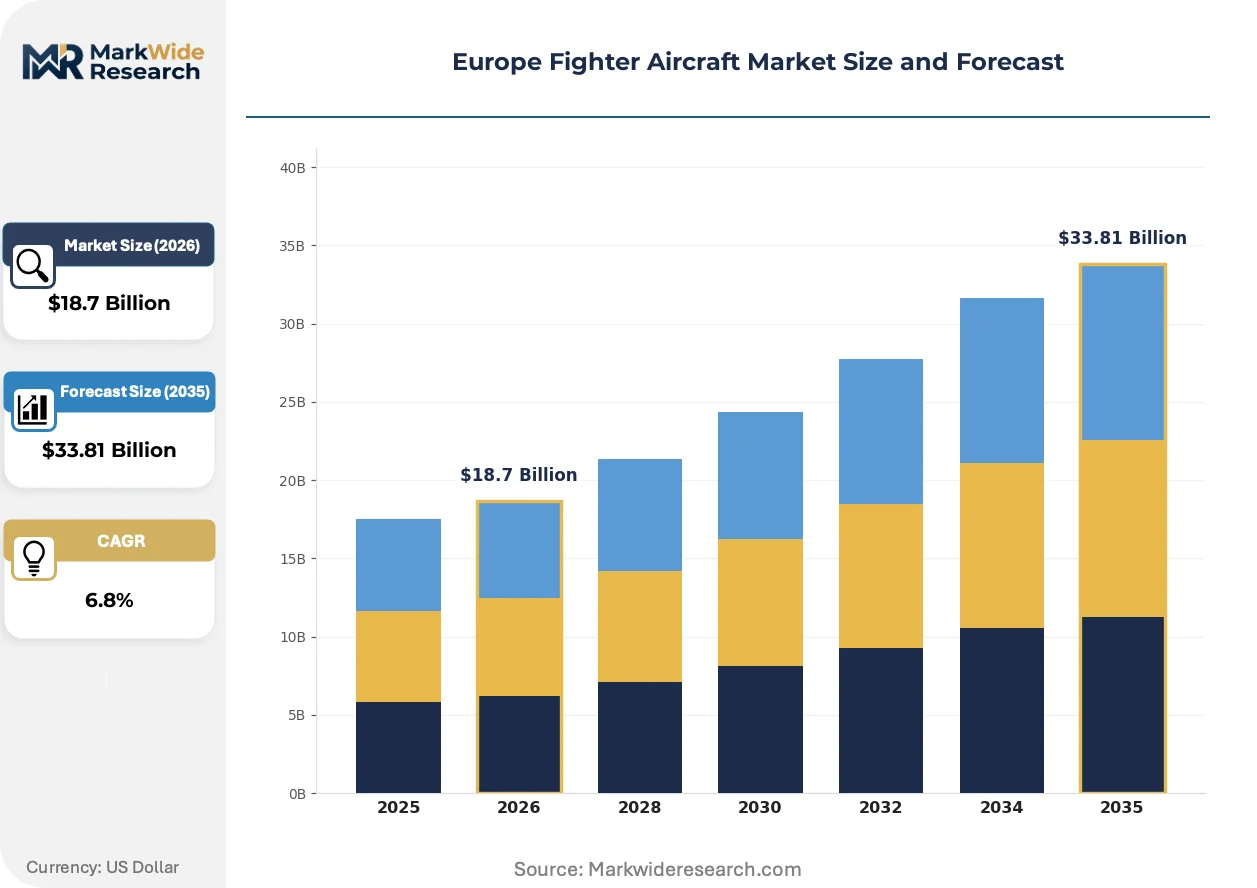
Market Dynamics
NATO capability targets and EU Green Deal sustainability mandates are forcing parallel investments in stealth performance and sustainable aviation fuel compatibility, compressing development timelines while expanding technical scope for European defense ministries.
Growth Catalysts
- EU Green Deal SAF Mandates:Defense sustainability directives require sustainable aviation fuel compatibility in next-generation platforms, redirecting R&D budgets toward propulsion innovation.
- NATO STANAG Interoperability:Standardized maintenance protocols and cross-border logistics frameworks enable multi-national fleet consolidation and shared training infrastructure.
- Collaborative Combat Aircraft Programs:France, Germany, and the United Kingdom are pooling development costs for sixth-generation systems, distributing financial risk across sovereign budgets.
Market Restraints
- Titanium and Nickel Superalloy Concentration:Russian and Chinese dominance in specialty metal refining creates supply vulnerability for engine and airframe manufacturers.
- EASA Dual-Use Export Controls:EMA and national procurement agencies enforce technology transfer restrictions that fragment supplier access and elongate partner qualification.
- Legacy Fleet Sunk Costs:Existing Typhoon and Rafale operators face political pressure to maximize prior capital commitments, delaying next-generation replacement cycles.
Strategic Opportunities
- Poland and Nordic Expansion:Baltic and eastern flank NATO members are accelerating Gripen E and F-35 procurement, creating demand for interoperable support ecosystems.
- Open-Architecture Avionics:Mission computer standardization enables third-party software integration, unlocking recurring revenue through modular capability upgrades.
- CSRD Defense Disclosure:Corporate sustainability reporting requirements for defense contractors create competitive differentiation for platforms with verified carbon reduction pathways.
Industry Challenges
- Systems Engineering Talent Scarcity:Fly-by-wire control law development and low-observable integration require specialized aerodynamicists that European universities produce insufficiently.
- Stealth Certification Timeline Compression:EASA and military airworthiness authorities lack harmonized radar cross-section validation standards, forcing redundant testing across jurisdictions.
- Legacy-Mission System Integration:NATO members demand backward compatibility with existing command-and-control networks, complicating digital backbone architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fighter Aircraft Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Multirole, Stealth, Light Combat, Advanced Trainer End User: Defense Forces, Private Contractors, NATO, Government Agencies Technology: Avionics, Weapons Systems, Radar, Propulsion Deployment Model: Onshore, Offshore, Temporary Bases, Permanent Bases |
| Companies Covered | Leonardo S.p.A., Lockheed Martin Corporation, Airbus SE, Thales Group, Rolls-Royce Holdings plc, BAE Systems plc, Saab AB, MBDA, Dassault Aviation SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fighter Aircraft Market Shifts & Advancements
European fighter development is pivoting toward manned-unmanned teaming architectures and software-defined mission systems, collapsing traditional hardware upgrade cycles into continuous capability delivery models.
Conformal antenna arrays and embedded sensor apertures are miniaturizing radar and electronic warfare systems into load-bearing airframe structures. BAE Systems and Leonardo are integrating these elements into Tempest demonstrators ahead of 2027 flight testing. This integration is miniaturizing avionics packaging volumes by approximately forty percent while expanding spectral coverage.
EU AI Act risk classification frameworks are imposing algorithmic transparency requirements on autonomous targeting and sensor fusion systems. Defense contractors must now document training data provenance and decision audit trails for machine learning components. French and German procurement offices are most advanced in embedding these standards into technical specifications.
Ministry buyers are consolidating multirole fleet types and demanding vendor-managed availability contracts rather than discrete platform purchases. Saab and Lockheed Martin are restructuring offerings around flight-hour guarantees and predictive maintenance commitments. This transformation is most pronounced in Scandinavian and Benelux defense budgets where personnel costs constrain organic technical capacity.
Europe Fighter Aircraft Market Segmentation
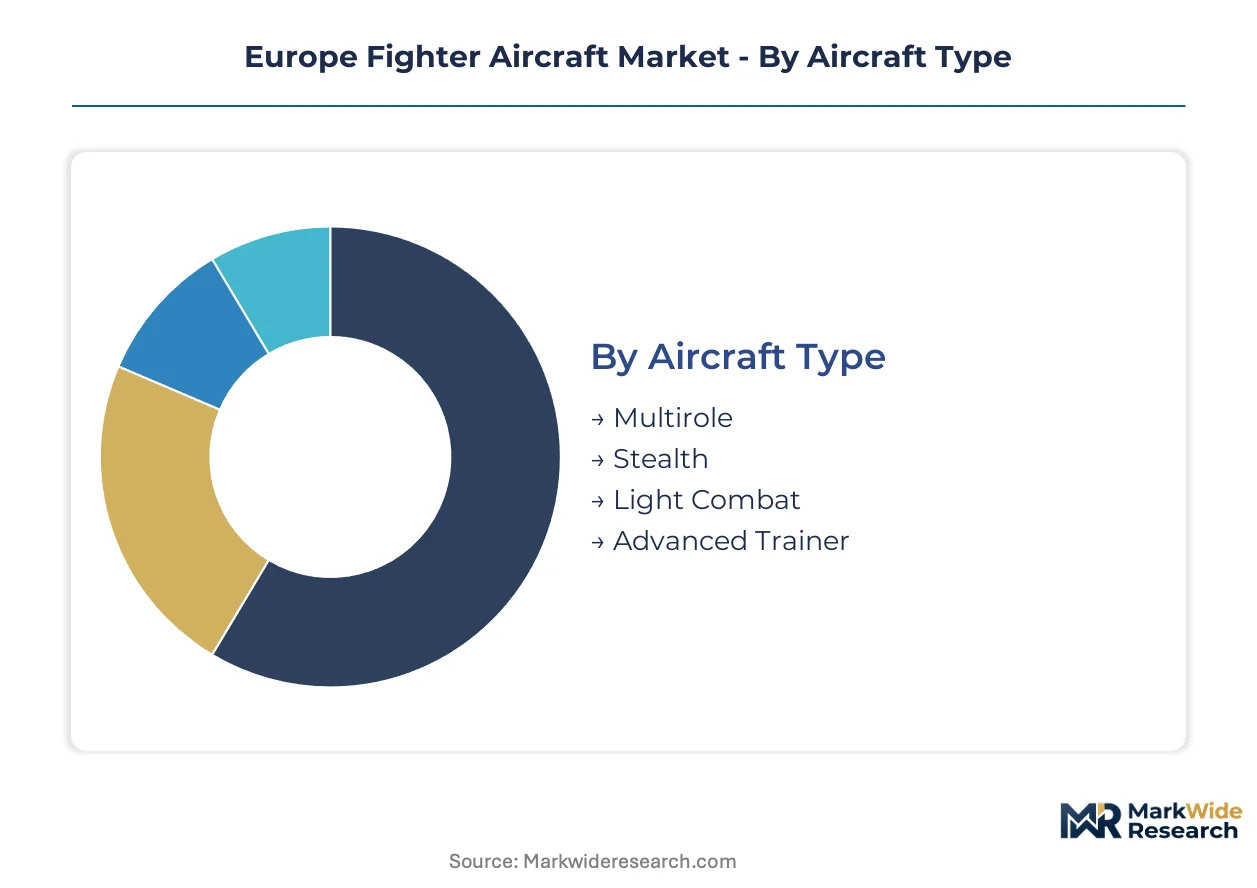
Segmentation in European fighter procurement reveals how budget pressures and NATO interoperability requirements reshape purchasing patterns. Defense ministries consolidate fleet types while sustainability mandates redirect technology investment toward propulsion and avionics categories.
Aircraft Type:
Multirole configurations dominate domestic procurement across France, Germany, and the United Kingdom, while export demand concentrates in lighter, cost-efficient platforms for Baltic and Nordic air forces.
- Multirole:These platforms integrate air superiority, strike, and reconnaissance capabilities within single airframes. French and German defense ministries prioritize multirole consolidation to reduce logistics footprints and training pipelines amid personnel constraints.
- Stealth:Low-observable airframes absorb disproportionate development investment despite elongated certification timelines. The United Kingdom's Tempest program and associated collaborative combat aircraft initiatives anchor European sixth-generation stealth development.
- Light Combat:Compact, single-engine designs serve cost-sensitive NATO members with limited defense budgets.
- Advanced Trainer:Lead-in fighter training platforms bridge operational conversion for next-generation cockpit systems.
Multirole holds the largest share; momentum sits with Stealth as collaborative programs advance.
End User:
Cost tier differentiation separates sovereign defense ministries with full acquisition autonomy from budget-constrained operators dependent on NATO shared funding mechanisms.
- Defense Forces:National air forces constitute the primary procurement channel, with France's Direction Générale de l'Armement and Germany's BAAINBw managing complex multi-year acquisition frameworks. These ministries balance sovereign industrial base preservation against collaborative program cost-sharing.
- NATO:Alliance-funded capability targets drive interoperability requirements and cross-border logistics standardization. Baltic Air Policing missions and enhanced forward presence deployments generate pooled procurement for interoperable support ecosystems.
- Government Agencies:Border patrol and coast guard aviation units operate modified fighter derivatives for sovereignty enforcement.
- Private Contractors:Adversarial air support and training services create secondary demand for surplus platforms.
Defense Forces command the dominant volume; NATO collective procurement is climbing fastest as eastern flank commitments expand.
Technology:
Application-specific investment patterns show avionics and propulsion capturing disproportionate R&D allocation as hardware-defined platforms transition toward software-centric architectures.
- Avionics:Open-architecture mission computers and conformal antenna arrays are displacing proprietary legacy systems. BAE Systems and Leonardo integration efforts miniaturize radar and electronic warfare packaging into load-bearing structures.
- Propulsion:Sustainable aviation fuel compatibility and adaptive cycle engines absorb major development resources under EU Green Deal mandates. Rolls-Royce anchors European propulsion leadership through Tempest powerplant development.
- Weapons Systems:Networked munitions and beyond-visual-range missiles require digital backbone integration.
- Radar:Active electronically scanned arrays remain essential for multirole mission flexibility.
Propulsion holds established investment scale; avionics is gaining share fastest as software-defined capabilities reshape upgrade economics.
Deployment Model:
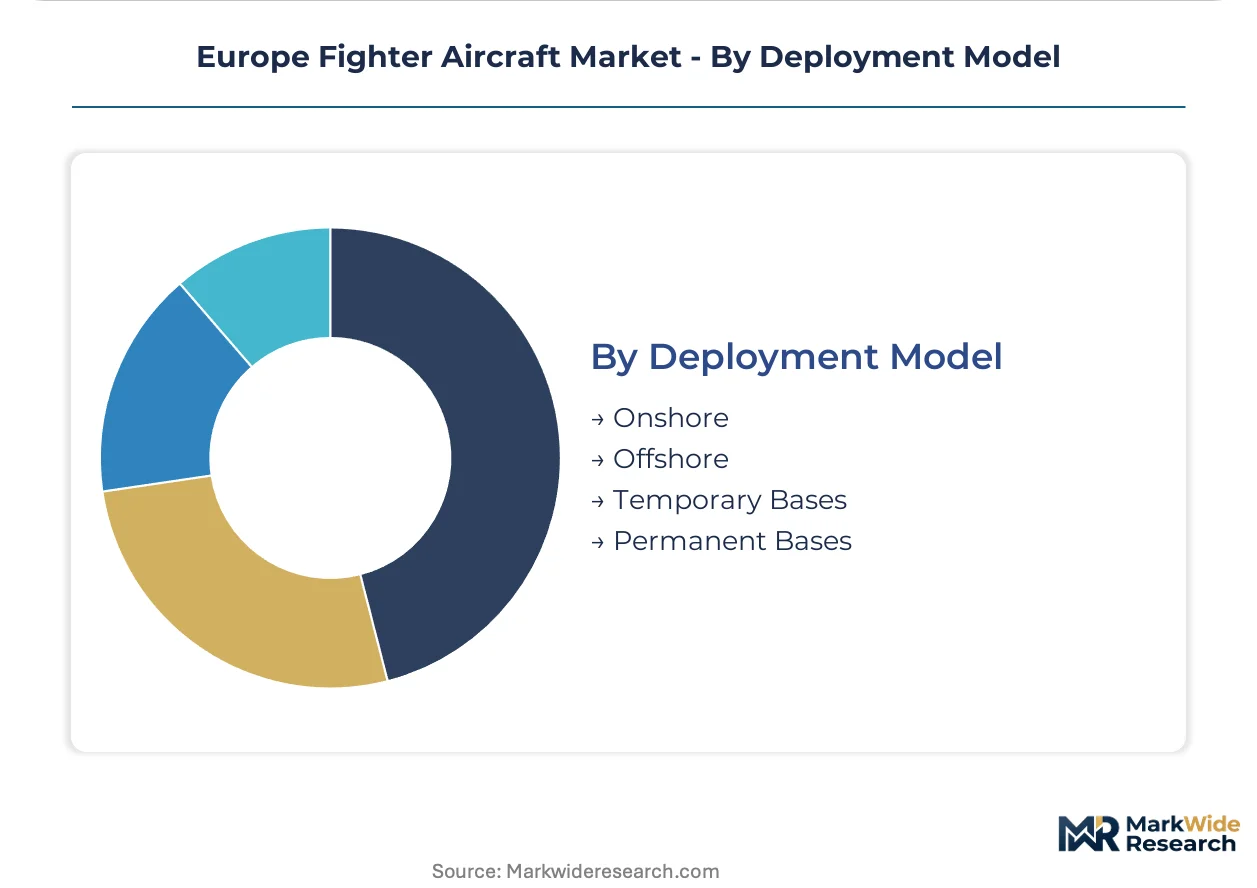
Customer type and operational tempo dictate infrastructure requirements, with permanent basing concentrated in western Europe and rotational deployments dominating eastern flank posture.
- Permanent Bases:Established installations in the United Kingdom, France, and Germany support fleet consolidation and deep maintenance infrastructure. These facilities anchor vendor-managed availability contracts and predictive maintenance ecosystems.
- Temporary Bases:Forward-deployed operations in Poland and Baltic states require rapid deployability and modular support equipment. NATO enhanced forward presence rotations drive demand for expeditionary logistics compatibility.
- Onshore:Domestic territory operations encompass routine training and air policing.
- Offshore:Carrier-based and expeditionary strike group integration applies to limited national assets.
Permanent Bases retain the largest installed footprint; Temporary Bases show the steepest expansion trajectory as alliance posture adapts to eastern flank requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European fighter procurement flows from import-dependent eastern flank states toward export-oriented western manufacturing clusters. France, Germany, and the United Kingdom anchor indigenous production capacity. Poland and Nordic members drive near-term import volume through accelerated fleet modernization timelines.
United Kingdom
Tempest program development absorbs the majority of UK defense aerospace investment, with BAE Systems anchoring sixth-generation prototyping at Warton. UK Ministry of Defence procurement frameworks prioritize sovereign industrial base preservation alongside collaborative cost-sharing. The Lancashire aerospace cluster concentrates fly-by-wire integration and low-observable materials testing for 2027 demonstrator milestones.
Germany
FCAS partnership commitments with France and Spain redirect Bundeswehr procurement toward European collaborative platforms, displacing prior US equipment dependencies. BAAINBw enforces EU Green Deal sustainable aviation fuel mandates through technical specifications for next-generation engines. The Bavarian aerospace corridor around Munich hosts propulsion integration facilities for adaptive cycle engine development.
France
Dassault Aviation anchors Rafale export campaigns across Middle Eastern and Asian markets, cross-subsidizing domestic FCAS development commitments. Direction Générale de l'Armement enforces strict technology transfer controls that shape supplier qualification across collaborative programs. The Île-de-France defense industrial base concentrates mission systems integration and conformal antenna array manufacturing.
Poland
Eastern flank NATO posture accelerates F-35 and Gripen E procurement through pooled alliance funding mechanisms, creating Europe's fastest-growing import demand corridor. Polish defense procurement agencies prioritize expeditionary logistics compatibility for Baltic Air Policing rotations. The Łódź special economic zone hosts emerging maintenance and training infrastructure for multinational fleet support.
Sweden
Gripen E series production targets Baltic and Nordic export markets with cost-efficient multirole positioning against heavier collaborative platforms. Swedish Defence Materiel Administration specifications emphasize Arctic operational compatibility and road-base deployability. Linköping's Saab engineering cluster concentrates open-architecture avionics development for rapid software upgrade cycles.
Europe Fighter Aircraft Market Competitive Landscape
Concentration sits with sovereign aerospace conglomerates and transatlantic platform integrators, with mid-tier subsystem specialists occupying fragmented technology niches. The vendor base stratifies across sixth-generation development consortia, established multirole exporters, and propulsion subsystem leaders. Two dominant competitive vectors are reshaping positioning: collaborative program cost-pooling across national budgets, and vendor-managed availability contracting that shifts revenue toward service guarantees.
Among established European platform developers, Leonardo S.p.A., BAE Systems plc, and Saab AB exemplify divergent strategic archetypes. Leonardo occupies the multinational consortium anchor position through Tempest partnership structures. BAE Systems represents the sovereign industrial base preservation model with deep UK government alignment. Saab AB sits within the cost-efficient export specialist tier, targeting budget-constrained NATO members with lighter platform configurations. These three entities collectively illustrate how European defense industrial policy fragments competitive positioning across collaborative and autonomous development pathways.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| Airbus SE |
| Thales Group |
| Rolls-Royce Holdings plc |
| BAE Systems plc |
| Saab AB |
| MBDA |
| Dassault Aviation SA |
| Others |
Supply & Pricing Matrix
Sustainable aviation fuel substitution for conventional jet propellants is redrawing supply geography toward biofuel refineries in northwestern Europe while compressing engine OEM margins through dual certification requirements. This input transition simultaneously elevates procurement complexity for defense ministries and fragments pricing power across propulsion subsystem tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around vendor-managed availability guarantees rather than discrete platform acquisition, shifting revenue recognition toward flight-hour commitments. Three-tier pricing structure across collaborative sixth-generation, sovereign multirole, and cost-optimized light combat platforms reflects divergent technical specifications and after-sales bundling intensity. Pricing pressure stems from EU Green Deal compliance costs embedded in propulsion R&D budgets. Smaller NATO members with Baltic Air Policing obligations exhibit highest price sensitivity; sovereign ministries with FCAS partnership stakes demonstrate lowest.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals have elevated titanium sponge and nickel superalloy procurement expenses for engine manufacturers dependent on Russian-origin feedstock precursors. Geographic supply concentration centers on United Kingdom airframe assembly, German propulsion integration, and French mission systems manufacturing. Raw material dependencies encompass titanium sponge, nickel-based superalloys, and gallium arsenide substrates for radar components. Single-source vulnerability persists in specialty metal refining. Distribution runs through national defense procurement agencies with NATO STANAG interoperability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as collaborative combat aircraft programs create tiered supplier entry points for subsystem specialists excluded from prime contractor consortia. NATO eastern flank expansion generates demand heterogeneity unmet by standardized platform offerings.
For Market Incumbents: Shield sovereign industrial base positions through accelerated backward integration into titanium and superalloy recycling capabilities, countering Russian feedstock dependency. Deepen Tempest partnership commitment structures to lock out rival consortium bids for sixth-generation development slots. Prioritize EASA military airworthiness certification pathway harmonization to compress radar cross-section validation timelines. For New Entrants and Emerging Players: EASA CS-25 military derivative certification fast-tracks enable subsystem supplier qualification for Gripen E and F-35 support ecosystems without prime contractor status. White-space targets encompass conformal antenna array manufacturing for load-bearing avionics integration and predictive maintenance software for vendor-managed availability contracts. Poland and Baltic states represent most penetrable geography given accelerated procurement timelines. Go-to-market angle should emphasize NATO STANAG interoperability pre-certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed avionics specialists holding open-architecture mission computer IP and established defense ministry relationships. Long-term viability framing centers on software-defined capability delivery models displacing hardware upgrade cycles across the projection horizon. Acquisition target archetype: mid-tier subsystem houses with EASA dual-use export control clearance and embedded positions in collaborative combat aircraft supply chains. Signal to watch: NATO capability target revisions triggering accelerated eastern flank procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Metal Recycling | Reduces dependency on Russian and Chinese titanium sponge supply for Rolls-Royce and Saab propulsion divisions. |
| Open-Architecture Avionics Certification | Enables Leonardo and BAE Systems to capture recurring revenue through modular software upgrade pathways. |
| Vendor-Managed Availability Contracting | Restructures Saab and Lockheed Martin offerings around flight-hour guarantees for Scandinavian defense budgets. |
| Sustainable Aviation Fuel Compatibility Investment | Positions German and French engine OEMs for EU Green Deal mandate compliance in next-generation platforms. |
| NATO STANAG Interoperability Pre-Certification | Accelerates Polish and Baltic market access for subsystem suppliers meeting cross-border logistics standards. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers at BAAINBw and Direction Générale de l'Armement, platform engineering directors at BAE Systems and Leonardo, and aftermarket service heads at Saab. Secondary validation drew from NATO STANAG documentation, EASA military airworthiness certification records, EU Green Deal defense sustainability directives, and national defense budget appropriations. Bottom-up platform delivery forecasts were triangulated against top-down NATO capability target spending projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions encompassing aircraft type, end-user procurement channel, technology subsystem category, and deployment infrastructure requirement. CAGRs were derived from historical budget appropriation patterns and projected collaborative program milestone commitments. Industry-specific inputs incorporated FCAS partnership funding allocations, Tempest demonstrator development timelines, and Baltic Air Policing rotation tempo assumptions.
Decision-makers should treat outputs as directional under sustained NATO eastern flank posture and EU Green Deal mandate continuity; material deviation would warrant model refresh. Specific risk factors encompass titanium supply disruption from sanctions regime evolution and EASA dual-use export control restriction expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Transparencies Market
Aircraft
Aircraft Leasing Market
Aircraft
Airplane Ailerons Market
Aircraft
Flight Management Systems Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Commercial Aerospace Market
Aircraft
Australia Aviation Market
Aircraft
Maritime Patrol Aircraft Market
Aircraft
Small Evtol Aircraft Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Supersonic Jet Market
Aircraft
Tanker Aircraft Market
Aircraft
Middle-East Aviation Market
Aircraft
Global Business Aircraft Market
Aircraft
Middle-East and Africa Commercial Aircraft Market