
 Germany Aerospace and Defense Market | 2026-2036
Germany Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Aerospace and Defense Market Foresight
AS9100 certification is rotating supplier eligibility across Germany's defense industrial base. Airbus SE leverages its integrated civil-military platform architecture to sustain dual-use contracts. Rheinmetall AG anchors land systems modernization through its domestic manufacturing footprint. MTU Aero Engines AG specializes in high-thrust propulsion modules for next-generation fighter programs.
Germany aerospace and defense encompasses the design, integration, and sustainment of manned and unmanned aerial platforms, orbital systems, and ground-based defense assets operating at altitudes from sea level to geostationary orbit. The sector relies on titanium-aluminide turbine blades, carbon-fiber composite airframes, and gallium-nitride radar substrates to achieve thrust-to-weight ratios exceeding 10:1 in combat aircraft. Aircraft platforms command the largest revenue pool due to Eurofighter and Future Combat Air System program commitments. Unmanned Systems within the technology dimension is expanding fastest as the Bundeswehr prioritizes attritable reconnaissance assets. Federal Defense Forces as the dominant end user concentrate procurement through multi-year framework agreements that lock in supplier relationships.
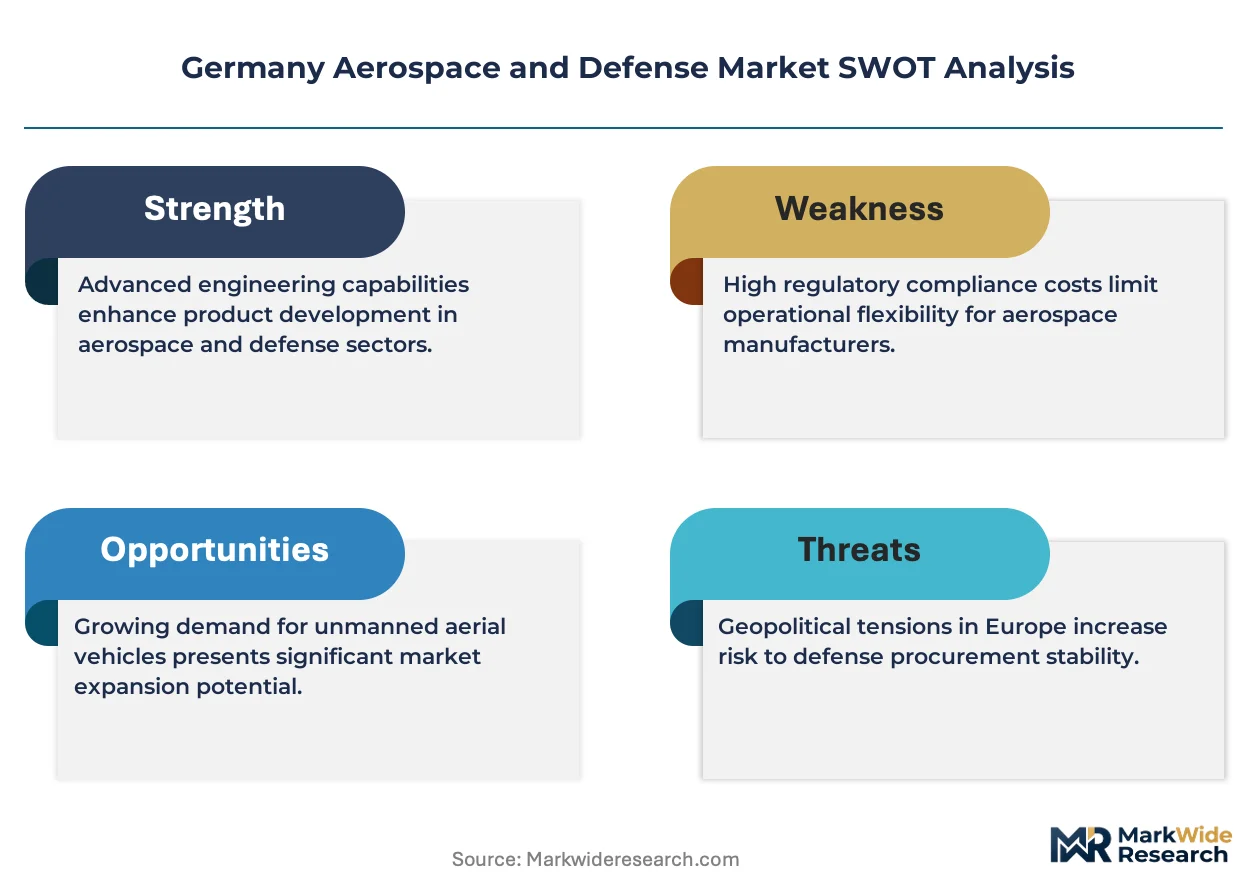
KBA oversees military vehicle type approval while the EU AI Act imposes algorithmic transparency mandates on autonomous targeting systems. REACH chemical regulations constrain composite resin formulations and surface treatments used in airframe manufacturing. Stakeholders must monitor how Berlin implements the EU Green Deal's sustainable aviation fuel mandates alongside defense-specific exemptions.
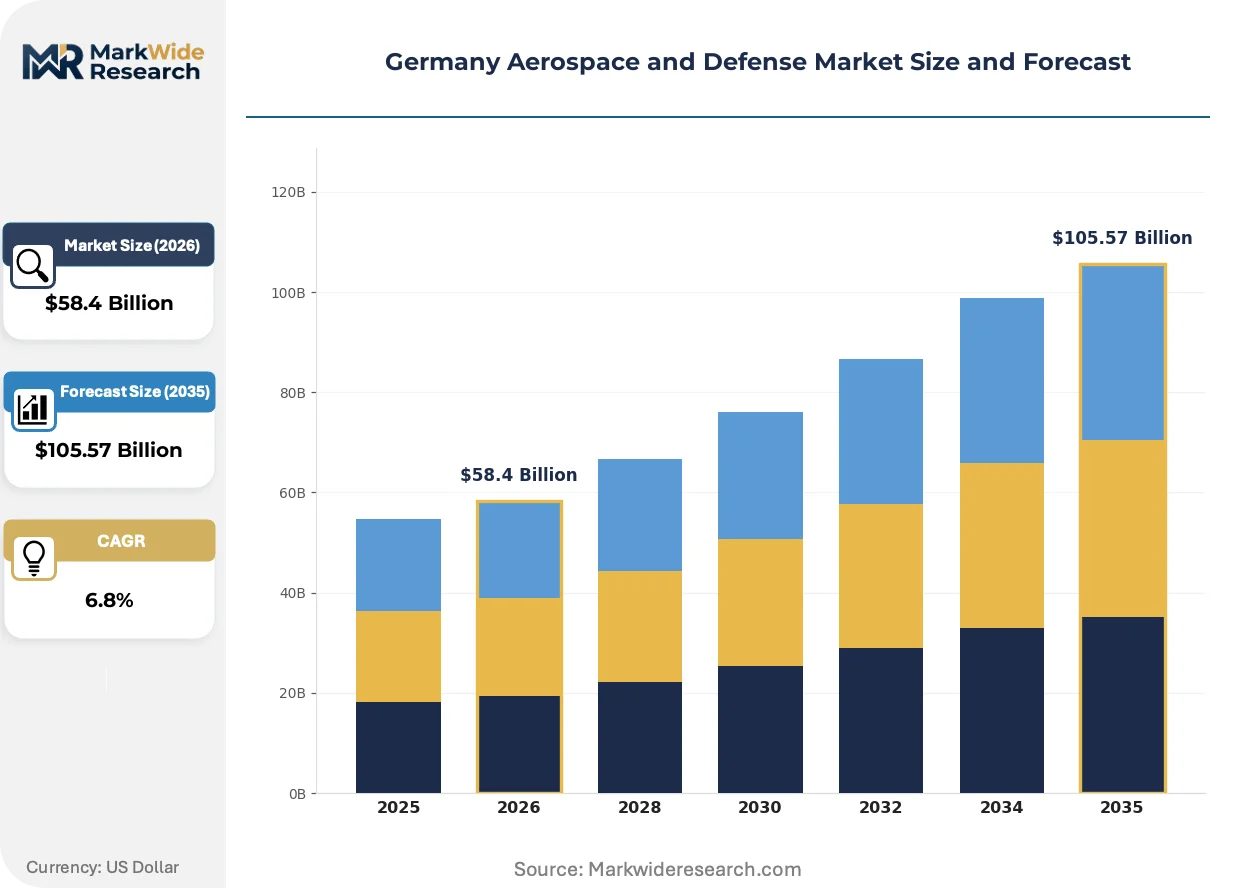
Market Dynamics
Bundeswehr procurement programs are restructuring supplier relationships through multi-year framework agreements that prioritize AS9100-certified domestic manufacturers for combat aircraft and unmanned systems.
Growth Catalysts
- FCAS Program Commitments:The trilateral Franco-German-Spanish Future Combat Air System is channeling development funding toward next-generation fighter propulsion and sensor architectures. Bundeswehr demand for attritable reconnaissance assets is accelerating unmanned systems adoption.
- EU Green Deal SAF Mandates:Sustainable aviation fuel requirements for civil aviation are creating technology spillover into military propulsion efficiency programs. Defense-specific exemptions are preserving operational flexibility while driving fuel-system upgrades.
- Bavaria Aerospace Cluster Concentration:Munich's integrated supply base around MTU Aero Engines and Airbus Defence and Space facilities is concentrating specialized manufacturing capability and reducing supplier qualification timelines.
Market Restraints
- Titanium-Aluminide Supply Concentration:High-temperature turbine blade casting capacity is concentrated among a limited set of European foundries, creating single-source vulnerability for next-generation engine programs.
- REACH Chemical Constraints:ECHA restrictions on composite resin formulations and surface treatments are forcing reformulation of airframe manufacturing processes, extending qualification cycles.
- Dual-Use Export Control Friction:EU and national licensing requirements for gallium-nitride radar substrates and autonomous targeting algorithms are delaying international contract execution.
Strategic Opportunities
- EU AI Act Certification Pathways:Algorithmic transparency mandates for autonomous systems are creating first-mover advantage for German suppliers who establish compliant development workflows ahead of enforcement.
- North Rhine-Westphalia Land Systems Hub:Rheinmetall's consolidated manufacturing footprint around Düsseldorf is positioning the region for Bundeswehr ground vehicle modernization contracts.
- GaN-on-SiC Radar Convergence:The intersection of wide-bandgap semiconductor fabrication with active electronically scanned array architectures is opening domestic sourcing opportunities for radar substrate production.
Industry Challenges
- Aerostructures Welding Certification Gap:Qualified technician pools for titanium and carbon-fiber joining processes are insufficient to match Bundeswehr production timelines.
- Legacy Platform Software Integration:Eurofighter avionics architectures require complex middleware development to host modern mission systems, compressing upgrade contract margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Aerospace and Defense Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Satellites, Missiles, Radar Systems, Avionics, Navigation Equipment Technology: Unmanned Systems, Electronic Warfare, Propulsion Systems, Simulation & Training, Cybersecurity, Autonomous Systems Application: Military Aviation, Space Exploration, Border Security, Maritime Surveillance, Disaster Management, Defense Communications End User: Federal Defense Forces, Security Agencies, Aviation Manufacturers, Space Agencies, Homeland Security, Research Institutes |
| Companies Covered | Rheinmetall AG, Airbus SE, MTU Aero Engines AG, Hensoldt AG, OHB SE, Diehl Stiftung & Co. KG, Krauss-Maffei Wegmann GmbH & Co. KG, Liebherr Group, MBDA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Aerospace and Defense Market Shifts & Advancements
Digital engineering workflows and wide-bandgap electronics are compressing development cycles for combat aircraft while regulatory pressure on autonomous systems is restructuring certification requirements across the Bundeswehr supply base.
Additive manufacturing of titanium-aluminide turbine blades is displacing conventional investment casting for low-volume, high-complexity engine components. MTU Aero Engines and Bundeswehr propulsion contractors are adopting powder-bed fusion for rapid prototyping and limited production runs. This technology is displacing traditional foundry relationships and enabling iterative design cycles that compress development timelines by eliminating tooling lead times.
The EU AI Act imposes mandatory algorithmic transparency and human oversight requirements on autonomous targeting and reconnaissance systems. German defense contractors must document decision logic for machine-learning-based threat classification and engagement authorization. Unmanned aerial system developers in Bavaria are most affected, with several programs restructuring software architectures to isolate human-in-the-loop verification points.
Bundeswehr procurement offices are consolidating maintenance and logistics contracts under performance-based service agreements that transfer operational risk to prime contractors. Rheinmetall and Airbus Defence and Space are absorbing sustainment responsibility for vehicle and aircraft fleets, replacing transactional spare-part sales with availability guarantees. This restructuring is most visible in land systems programs, where multi-year vehicle readiness contracts now dominate Rheinmetall's order backlog.
Germany Aerospace and Defense Market Segmentation
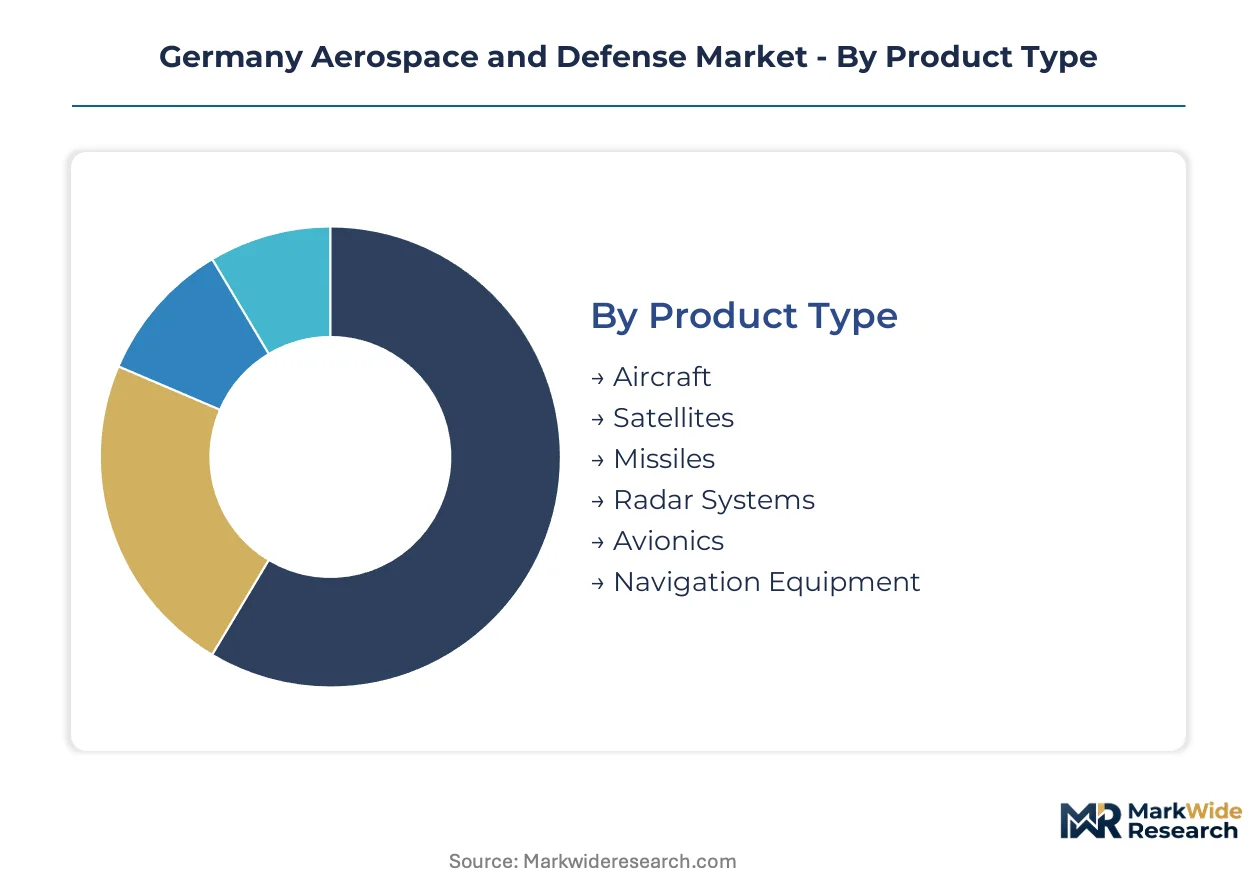
Segmentation in Germany's aerospace and defense sector reveals how procurement concentration shapes supplier viability. Bundeswehr framework agreements favor certain product configurations over others, while technology choices determine AS9100 certification requirements.
Product Type:
Aircraft platforms command the deepest margin pools due to multi-decade sustainment contracts and upgrade cycles.
- Aircraft:Manned aerial platforms integrate titanium-aluminide turbine blades and carbon-fiber composite airframes for thrust-to-weight ratios exceeding 10:1. Bundeswehr Eurofighter and FCAS program commitments concentrate procurement in Bavaria's aerospace cluster around Munich.
- Satellites:Orbital systems span low-Earth orbit reconnaissance constellations through geostationary communications platforms. German Space Agency demand for earth observation payloads drives domestic bus and payload integration capability.
- Missiles:Precision strike and air defense munitions require gallium-nitride seeker substrates and composite motor casings.
- Radar Systems:Active electronically scanned arrays leverage GaN-on-SiC architectures for fighter and ground-based applications.
- Avionics:Mission computers, displays, and sensor fusion processors host middleware for legacy platform integration.
- Navigation Equipment:GPS-denied positioning systems combine inertial measurement units with celestial references.
Aircraft holds installed capacity. Satellites is rotating up the share rankings.
Technology:
Cost tier separation distinguishes developmental technologies from mature production systems.
- Unmanned Systems:Attritable reconnaissance assets and combat drones prioritize modular payloads and rapid field replacement. Bundeswehr procurement is accelerating adoption as operational concepts shift toward distributed sensing architectures.
- Electronic Warfare:Spectrum dominance systems span jamming pods, decoys, and signals intelligence suites. FCAS program funding is channeling development toward next-generation electromagnetic attack and protection capabilities.
- Propulsion Systems:High-thrust turbofans and hypersonic scramjets demand specialized foundry capacity.
- Simulation & Training:Synthetic environment systems reduce live flight hours while maintaining pilot proficiency.
- Cybersecurity:Platform hardening and network defense protect mission systems from electronic intrusion.
- Autonomous Systems:Machine-learning-based threat classification requires EU AI Act compliance for algorithmic transparency.
Unmanned Systems holds installed capacity. Autonomous Systems is rotating up the share rankings.
Application:
Volume concentration follows Bundeswehr operational priorities with distinct procurement rhythms per mission area.
- Military Aviation:Combat aircraft, transport platforms, and rotary-wing systems absorb the largest procurement allocations. Airbus Defence and Space facilities in Bavaria anchor domestic manufacturing for fighter and transport programs.
- Space Exploration:Launch services, orbital infrastructure, and planetary science missions compete for limited agency budgets. German Space Agency commitments to European Space Agency programs sustain domestic payload and subsystem suppliers.
- Border Security:Persistent surveillance and intercept capabilities address Schengen perimeter monitoring requirements.
- Maritime Surveillance:Anti-submarine warfare and exclusive economic zone patrol drive maritime patrol aircraft demand.
- Disaster Management:Rapid response airlift and communications restoration support civil-military coordination.
- Defense Communications:Secure networks and satellite links connect distributed forces across operational theaters.
Military Aviation holds installed capacity. Space Exploration is rotating up the share rankings.
End User:
Customer type determines contract structure, with framework agreements dominating Federal Defense Forces procurement.
- Federal Defense Forces:The Bundeswehr concentrates demand through multi-year framework agreements that lock in supplier relationships and prioritize AS9100-certified domestic manufacturers for combat aircraft and unmanned systems.
- Security Agencies:Federal police and intelligence services procure specialized surveillance and communications equipment outside standard defense acquisition channels.
- Aviation Manufacturers:Airbus SE leverages integrated civil-military platform architecture to sustain dual-use contracts across European programs.
- Space Agencies:National and European space organizations fund science and exploration missions with distinct procurement rules.
- Homeland Security:Critical infrastructure protection and emergency response capabilities require interoperable systems.
- Research Institutes:Fraunhofer and university laboratories develop enabling technologies with defense application potential.
Federal Defense Forces holds installed capacity. Security Agencies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Bavaria's dominance in German aerospace manufacturing, connecting Munich's industrial cluster to North Sea ports and continental supply chains.
Bavaria
Eurofighter sustainment contracts and FCAS development funding drive procurement concentration in Munich's aerospace corridor. KBA military vehicle type approvals intersect with EU AI Act mandates for autonomous systems certification. MTU Aero Engines and Airbus Defence and Space facilities anchor specialized turbine blade casting and final assembly operations.
North Rhine-Westphalia
Bundeswehr land systems modernization programs channel ground vehicle demand toward Düsseldorf's manufacturing basin. REACH chemical regulations constrain composite resin formulations used in armored hull production. Rheinmetall's consolidated footprint around Kassel and Düsseldorf concentrates qualified welding capacity for titanium structures.
Baden-Württemberg
Precision machining clusters in Stuttgart support aerostructures and avionics subsystem supply. EU Green Deal sustainable aviation fuel mandates create technology spillover into military propulsion efficiency programs. Diehl Stiftung & Co. KG operations around Nuremberg and Überlingen specialize in missile electronics and defense avionics integration.
Lower Saxony
OHB SE satellite manufacturing in Bremen and surrounding facilities drives orbital systems demand for earth observation payloads. ESA program commitments sustain domestic bus and payload integration capability. The Bremen-Bremerhaven port complex enables oversized component logistics for launch vehicle structures.
Berlin-Brandenburg
Hensoldt AG radar and electronic warfare development concentrates in the capital region's research corridor. Federal defense research funding through Fraunhofer institutes accelerates GaN-on-SiC semiconductor prototyping. The Adlershof technology park hosts unmanned systems developers restructuring software architectures for EU AI Act compliance.
Germany Aerospace and Defense Market Competitive Landscape
Listed leaders compete with private specialists across platform integration and subsystem supply, creating a tiered structure where scale-driven primes absorb sustainment risk through performance-based contracts while mid-cap component suppliers defend position through AS9100 certification and foundry capacity. Three archetypes dominate: integrated platform architects managing multi-decade fighter and transport programs; propulsion and sensor specialists capturing development funding for next-generation engine and radar architectures; and land systems consolidators consolidating maintenance and logistics contracts under availability guarantees. Competitive moves center on multi-year framework agreement capture and additive manufacturing qualification for titanium-aluminide components.
Within the integrated platform tier, Airbus SE exemplifies dual-use civil-military architecture leverage, while Rheinmetall AG anchors ground vehicle modernization through consolidated domestic manufacturing. MTU Aero Engines AG occupies a specialized position in high-thrust propulsion modules, representing the subsystem specialist archetype that captures FCAS and Eurofighter engine development funding.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Airbus SE |
| MTU Aero Engines AG |
| Hensoldt AG |
| OHB SE |
| Diehl Stiftung & Co. KG |
| Krauss-Maffei Wegmann GmbH & Co. KG |
| Liebherr Group |
| MBDA |
| Others |
Supply & Pricing Matrix
Powder-bed fusion of titanium-aluminide turbine blades is displacing conventional investment casting across Bundeswehr propulsion programs, simultaneously shifting supplier geography toward Bavaria's additive manufacturing clusters and compressing pricing economics for low-volume engine components by eliminating foundry tooling costs.
Pricing Analysis
AS9100 certification tier creates the primary spread between qualified defense suppliers and commercial-grade competitors. Three-tier pricing structure across flight-certified, industrial-grade, and prototype tiers reflects qualification burden and traceability requirements. Cost compression in the prototype tier is intensifying because additive manufacturing entrants are bypassing traditional foundry relationships. Federal Defense Forces exhibit lowest price sensitivity due to multi-year framework agreement structures, while export customers face dual-use licensing premiums.
Supply Chain Analysis
Inbound logistics costs through Hamburg and Bremerhaven container terminals fluctuate with North Sea port congestion, affecting gallium-nitride radar substrate deliveries from Asian foundries. German aerospace supply chains draw from Japan and South Korea for wide-bandgap semiconductors, France and Spain for FCAS program components, and domestic Bavarian clusters for turbine blade casting. Single-source vulnerability in titanium-aluminide foundry capacity poses structural risk. Distribution runs through prime contractor consolidated hubs rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bundeswehr procurement cycles are entering an upswing phase as FCAS development funding accelerates and Eurofighter sustainment contracts renew, creating favorable conditions for defense suppliers with established framework agreement positions.
For Market Incumbents: Compound AS9100 certification advantages by absorbing adjacent subsystem suppliers before EU AI Act compliance costs reshape autonomous systems vendor eligibility. Acquire specialized welding capacity for titanium-carbon-fiber joining to address the technician shortage threatening production timelines. Lock in gallium-nitride substrate supply agreements ahead of radar modernization program awards.
For New Entrants and Emerging Players: Anchor in Berlin-Brandenburg's unmanned systems corridor where EU AI Act compliance tooling creates first-mover opportunity for algorithmic transparency solutions. Target the attritable reconnaissance segment as the most penetrable Bundeswehr priority with lower qualification barriers than manned platforms. Pursue direct subcontractor relationships with MTU Aero Engines for additive manufacturing qualification rather than competing for prime contracts.
For Investors and Strategic Acquirers: The market sits at a procurement expansion phase that favors subsystem specialists with captive foundry capacity or GaN-on-SiC fabrication capability. Long-term viability hinges on positioning within FCAS supply tiers rather than legacy platform exposure. Watch for Bundeswehr performance-based logistics contract awards as the signal indicating which primes will absorb sustainment risk and consolidate supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks Bundeswehr framework agreement eligibility for combat aircraft and unmanned systems procurement. |
| Additive Manufacturing Qualification | Enables powder-bed fusion production of titanium-aluminide blades, displacing traditional foundry relationships. |
| EU AI Act Compliance Architecture | Positions Bavarian autonomous systems developers ahead of algorithmic transparency enforcement deadlines. |
| GaN-on-SiC Substrate Sourcing | Secures domestic radar substrate production capacity for active electronically scanned array programs. |
| Performance-Based Logistics Contracting | Transfers operational risk from Bundeswehr to primes, consolidating maintenance and spare parts revenue. |
Research Methodology
Desk research of Bundeswehr procurement databases, ECHA REACH regulatory filings, and EU AI Act implementation guidance preceded structured interviews with defense procurement officers, AS9100 certification auditors, additive manufacturing engineers, and prime contractor program managers. Secondary validation drew from KBA military vehicle type approval records, ESA program commitment disclosures, and Bavarian aerospace cluster economic development reports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Variance decomposition across product type, technology maturity, and end-user procurement channel shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include platform category, propulsion architecture, autonomy level, and regional manufacturing cluster. CAGRs were derived from contract award velocity analysis and supplier capacity expansion announcements. Forecast inputs incorporated FCAS program funding trajectories and EU Green Deal sustainable aviation fuel mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued Bundeswehr procurement acceleration and stable REACH regulatory enforcement; material deviation in defense budget allocation or chemical restriction scope would warrant model refresh. Specific risk factors include titanium-aluminide supply disruption, dual-use export license delays, and EU AI Act compliance timeline shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Altimeter Market