
 Global Transfection Technologies Market | 2026-2036
Global Transfection Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transfection Technologies Market Foresight
China is reshaping transfection technology supply dynamics through domestic biomanufacturing expansion and government-backed precision medicine initiatives. Thermo Fisher Scientific leverages its global reagent infrastructure to sustain leadership in lipofection and electroporation workflows. Lonza Group anchors high-value positions through specialized viral vector manufacturing platforms. Bio-Rad Laboratories differentiates with advanced electroporation systems optimized for difficult-to-transfect cell types.
Transfection technologies encompass methods for introducing nucleic acids into eukaryotic cells using chemical carriers, physical force, or viral particles, with critical parameters including transfection efficiency, cell viability post-delivery, and scalability from research to GMP production. These systems serve gene therapy manufacturing, functional genomics, and bioproduction where precise genetic manipulation determines therapeutic or research outcomes. Lipofection retains dominant share in routine research applications due to ease of use and reproducibility, while viral vector methods command premium positioning in clinical-grade gene therapy contexts where regulatory stringency elevates barrier to entry. Electroporation is gaining fastest adoption in cell line engineering and CRISPR workflows as instrument precision improves for sensitive primary and stem cell populations.
FDA gene therapy guidance, EMA's ATMP framework, and China's NMPA cell therapy regulations collectively elevate quality and documentation requirements for clinical-grade transfection reagents and instruments. These frameworks compel manufacturers to invest in GMP-compliant production, validated supply chains, and extensive safety testing that reshapes competitive economics. Stakeholders must monitor regulatory convergence across jurisdictions and assess which platform technologies can scale across both research and regulated therapeutic manufacturing environments.
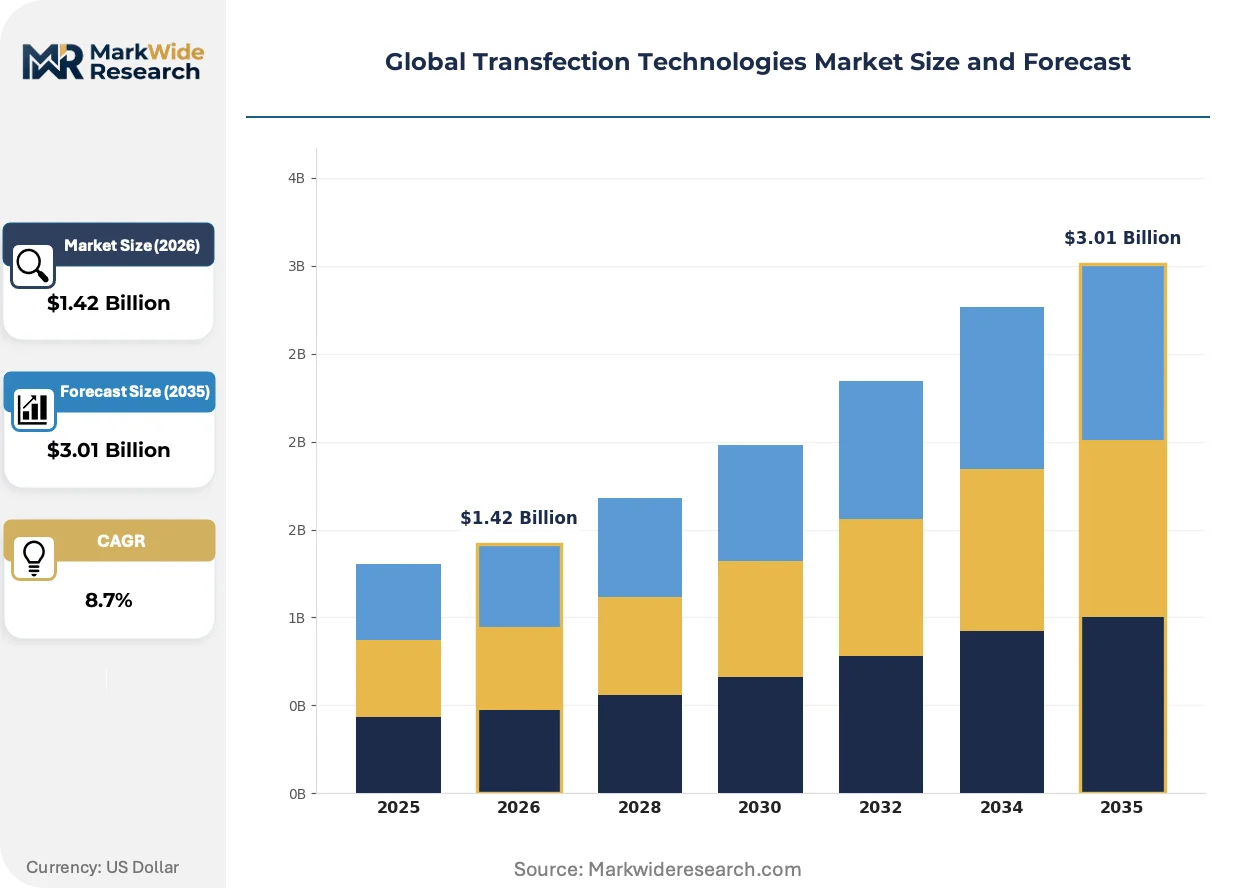
Market Dynamics
CRISPR-guided delivery systems are compressing development timelines for gene therapy candidates, forcing platform providers to integrate electroporation and viral vector workflows into unified manufacturing stacks. This convergence is redrawing competitive boundaries between reagent suppliers and instrument manufacturers.
Growth Catalysts
- FDA gene therapy guidance:Accelerated approval pathways for rare disease indications are expanding GMP-grade transfection capacity requirements across US-based CDMO networks.
- Cell line engineering:Biopharmaceutical manufacturers are scaling electroporation infrastructure to support CRISPR-mediated knock-in workflows for complex protein production.
- China's precision medicine initiatives:Government-backed funding for domestic gene therapy manufacturing is driving demand for viral vector transfection platforms in Shanghai and Suzhou bioclusters.
Market Restraints
- Plasmid DNA supply volatility:GMP-grade plasmid manufacturing capacity concentrates among fewer than ten specialized suppliers globally, creating input bottlenecks for viral vector production.
- EMA ATMP framework complexity:Divergent documentation requirements across EU member states extend regulatory validation timelines for novel transfection reagents.
- Physical method limitations:Electroporation-induced cell mortality rates above 30% in primary T-cell populations restrict adoption in autologous cell therapy manufacturing.
Strategic Opportunities
- India's biologics manufacturing expansion:CDSCO's streamlined biosimilar approval pathways are attracting investment in GMP transfection infrastructure for export-oriented production.
- mRNA manufacturing convergence:Lipid nanoparticle formulation expertise developed for COVID-19 vaccines is transferring to non-viral gene therapy delivery applications.
- Japan's regenerative medicine commercialization:PMDA's conditional approval framework for iPSC-derived therapies is creating demand for specialized stem cell transfection protocols.
Industry Challenges
- GMP compliance talent scarcity:Qualified personnel for validated transfection process development remain concentrated in Boston, Basel, and Singapore, constraining facility expansion elsewhere.
- Instrument-reagent interoperability:Proprietary electroporation protocols lock customers into single-vendor ecosystems, complicating multi-platform manufacturing strategies.
- Supply chain reconfiguration:Cold-chain logistics for temperature-sensitive reagents require redundant distribution nodes that strain working capital for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transfection Technologies Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Method Type: Lipofection, Electroporation, Calcium Phosphate, Viral Vector, DEAE-Dextran, Microinjection Application Area: Gene Editing, Protein Expression, RNA Interference, Vaccine Development, Cell Line Engineering, Drug Discovery Cell Type: Mammalian Cells, Insect Cells, Yeast Cells, Plant Cells, Primary Cells, Stem Cells End User: Biopharmaceutical Companies, Academic Research Institutes, Contract Research Organizations, Biotechnology Startups, Clinical Laboratories, Government Agencies |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Lonza Group, QIAGEN, Merck KGaA, Promega Corporation, MaxCyte, Polyplus-transfection, Mirus Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transfection Technologies Market Shifts & Advancements
Transfection technology architectures are converging around modular, automated platforms that bridge research-scale discovery and GMP manufacturing. This integration is compressing technology transfer timelines and reshaping vendor-customer relationships.
Microfluidic electroporation systems are migrating from specialized stem cell research applications toward standardized clinical manufacturing workflows. Gene therapy CDMOs in the United States and Germany are adopting these platforms to reduce cell processing variability. The technology is migrating from niche academic settings to become the default approach for primary cell engineering in commercial settings.
EMA's revised ATMP quality guidelines are mandating enhanced characterization of residual transfection reagents in final drug products. Manufacturers must now implement additional analytical testing protocols that extend batch release timelines. Viral vector producers in the Netherlands and Belgium are responding by investing in process analytical technology to demonstrate real-time clearance.
Biopharmaceutical procurement teams are consolidating transfection reagent sourcing under long-term supply agreements with technical service attachments. This displaces spot purchasing through distributors and shifts negotiation leverage toward vendors with integrated application support. The pattern is most pronounced among US-based cell therapy developers with multiple assets in Phase II trials.
Global Transfection Technologies Market Segmentation
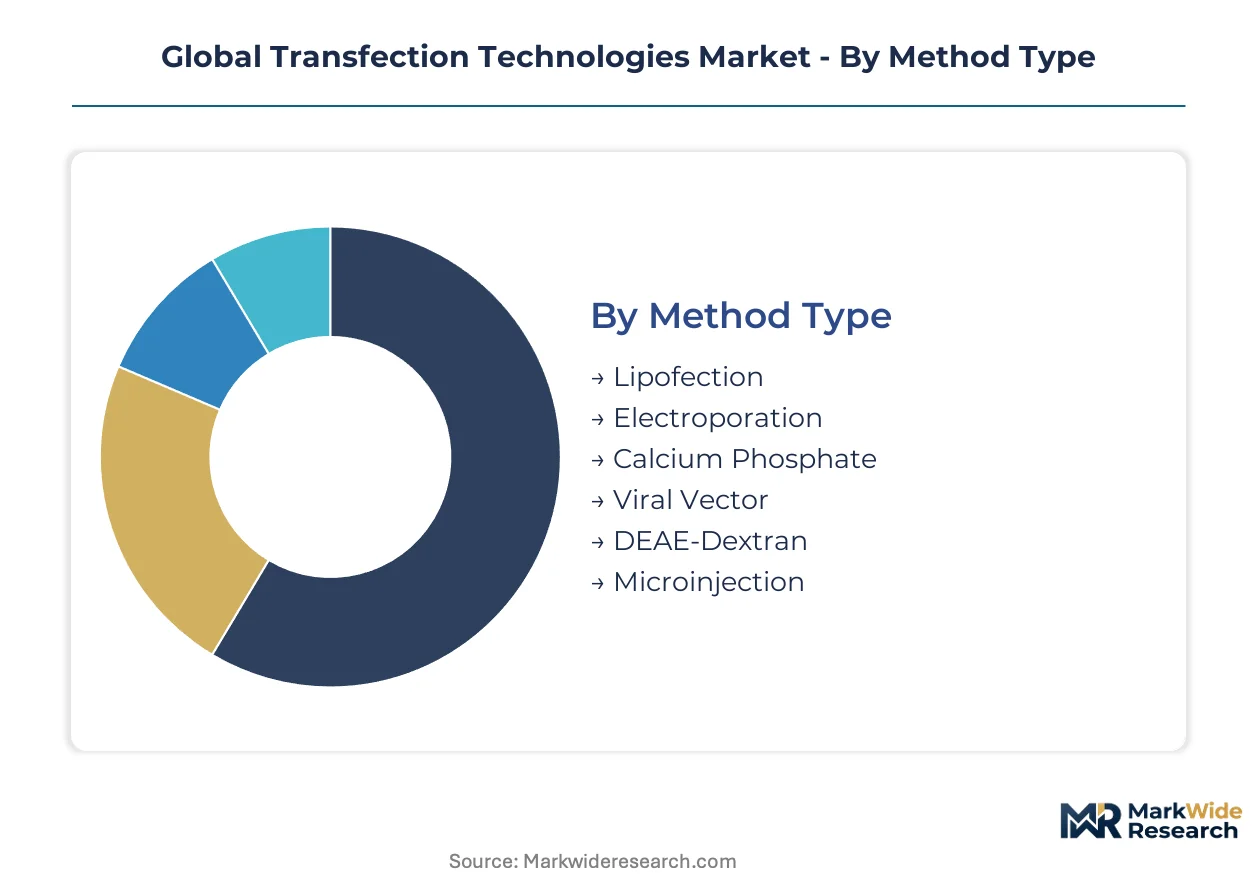
Transfection technology purchasing decisions diverge sharply across method types, applications, and end-user sophistication levels. Manufacturers must align platform development with the technical requirements and regulatory constraints specific to each segment combination.
Method Type:
Cost tier determines adoption velocity, with premium physical and viral methods commanding GMP workflows while chemical carriers dominate routine research spending.
- Lipofection:Lipid-based complexes form micellar structures that fuse with cellular membranes to deliver nucleic acid payloads. Academic laboratories in Germany and the United States deploy these reagents for high-throughput screening where reproducibility outweighs peak efficiency concerns. Lipofection holds installed capacity. Viral Vector is rotating up the share rankings.
- Electroporation:Controlled electrical pulses transiently permeabilize cell membranes, enabling direct nucleic acid entry without chemical carriers. CRISPR workflows in Boston and San Diego bioclusters are scaling electroporation infrastructure for primary T-cell engineering where viral methods introduce unacceptable immunogenicity risks. Steep expansion trajectory in clinical manufacturing settings.
- Calcium Phosphate:Inexpensive co-precipitation chemistry suits stable cell line generation in budget-constrained academic settings.
- Viral Vector:Lentiviral and adeno-associated virus platforms dominate FDA-regulated gene therapy manufacturing where permanent genomic integration or long-term expression is required.
- DEAE-Dextran:Cationic polymer chemistry retains niche applications for transient protein expression in insect cell systems.
- Microinjection:Direct physical delivery into individual cells supports embryo engineering and single-cell genomics research.
Electroporation gains share fastest as instrument precision improves for sensitive cell populations.
Application Area:
Application maturity shapes vendor-customer relationships, with established workflows favoring commoditized reagent supply and emerging modalities requiring integrated technical partnerships.
- Gene Editing:CRISPR-Cas9 ribonucleoprotein delivery demands high-efficiency, low-toxicity transfection platforms that preserve cell viability through multiple editing rounds. Chinese CDMOs in Suzhou are deploying electroporation systems for CAR-T knock-in manufacturing under NMPA cell therapy regulations. Gene Editing commands premium platform investment. Vaccine Development is climbing the fastest.
- Protein Expression:Transient transfection of HEK293 and CHO cells supports rapid antibody production for early-stage drug candidate characterization. Biopharmaceutical manufacturers in Basel and Singapore maintain captive electroporation capacity for complex glycoprotein expression where stable line generation timelines are unacceptable. Protein Expression maintains volume concentration.
- RNA Interference:siRNA delivery for target validation concentrates in academic screening facilities with established lipofection protocols.
- Vaccine Development:mRNA and DNA vaccine manufacturing is transferring lipid nanoparticle formulation expertise from COVID-19 platforms to personalized cancer vaccines.
- Cell Line Engineering:Stable knock-in and knock-out workflows require co-transfection of targeting constructs and selection markers.
- Drug Discovery:High-content screening campaigns depend on consistent multi-well transfection performance across diverse cell models.
Cell Line Engineering anchors capital expenditure. Vaccine Development is expanding most quickly.
Cell Type:
Customer type fragmentation drives product portfolio complexity, with specialized primary and stem cell protocols commanding price premiums over standardized immortalized line workflows.
- Mammalian Cells:HEK293, CHO, and HeLa lines constitute the reference standard for therapeutic protein production and viral vector packaging. Thermo Fisher Scientific and Lonza Group compete intensely for GMP-grade reagent supply contracts with US-based gene therapy CDMOs. Mammalian Cells dominates reagent consumption. Stem Cells is gaining share fastest.
- Primary Cells:Non-immortalized human T-cells, hepatocytes, and neurons present membrane properties that resist chemical transfection. Japanese iPSC-derived therapy developers under PMDA conditional approval frameworks are investing in microfluidic electroporation to achieve viable transfection rates above 60% in clinically relevant cell populations. Primary Cells demands specialized instrumentation.
- Insect Cells:Baculovirus expression systems support complex protein folding requirements for vaccine antigens.
- Yeast Cells:Pichia pastoris and Saccharomyces cerevisiae platforms serve industrial enzyme and biosimilar manufacturing.
- Plant Cells:Transient expression in Nicotiana benthamiana supports rapid vaccine antigen production for emerging infectious diseases.
- Stem Cells:Pluripotent and induced pluripotent stem cell engineering requires gentle delivery methods that preserve differentiation capacity.
Mammalian Cells holds installed base. Stem Cells is rotating up the share rankings.
End User:
Geography concentrates purchasing authority, with biocluster proximity to regulatory agencies and talent pools determining vendor market access.
- Biopharmaceutical Companies:Integrated drug developers in Cambridge, Massachusetts and South San Francisco are consolidating transfection reagent procurement under multi-year supply agreements with embedded application scientists. FDA gene therapy guidance compliance requirements are forcing these organizations to validate reagent lots for residual impurity profiles that extend batch release timelines. Biopharmaceutical Companies drives premium platform adoption. Contract Research Organizations is climbing fastest.
- Academic Research Institutes:Principal investigators at Max Planck Institutes and NIH-funded laboratories prioritize publication-grade reproducibility and distributor availability over GMP documentation. Academic Research Institutes sustains volume base. Biotechnology Startups is gaining traction.
- Contract Research Organizations:CDMOs in Germany and the United States are building GMP electroporation capacity to capture cell therapy manufacturing outsourcing from venture-backed developers.
- Biotechnology Startups:Seed-stage companies in Shanghai and Boston bioclusters favor flexible instrument leasing over capital purchase.
- Clinical Laboratories:Diagnostic transfection applications for rare disease screening remain limited to reference laboratory settings.
- Government Agencies:BARDA and DARPA funding supports pandemic preparedness through rapid vaccine platform development.
Biopharmaceutical Companies holds purchasing concentration. Contract Research Organizations is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gene therapy guidance anchors the United States as the dominant geography, with EMA's ATMP framework and China's NMPA cell therapy regulations shaping complementary demand centers across Germany and China.
United States
Cambridge and South San Francisco bioclusters drive electroporation infrastructure investment for CRISPR-mediated cell therapy manufacturing. FDA accelerated approval pathways for rare disease indications expand GMP-grade transfection capacity requirements across CDMO networks. Boston-based developers consolidate reagent procurement under multi-year supply agreements with embedded technical service attachments.
Germany
Basel-proximate manufacturers maintain captive electroporation capacity for complex glycoprotein expression where stable line generation timelines prove unacceptable. EMA ATMP framework complexity extends regulatory validation timelines for novel transfection reagents across member states. Max Planck Institutes sustain academic volume demand through distributor-availability priorities over GMP documentation.
China
Shanghai and Suzhou bioclusters attract government-backed funding for domestic gene therapy manufacturing infrastructure. NMPA cell therapy regulations elevate quality and documentation requirements for clinical-grade transfection reagents and instruments. Suzhou-based CDMOs deploy electroporation systems for CAR-T knock-in manufacturing under evolving national precision medicine initiatives.
Japan
Osaka and Tokyo iPSC-derived therapy developers invest in microfluidic electroporation to achieve viable transfection rates above 60% in clinically relevant cell populations. PMDA conditional approval frameworks for regenerative medicine commercialization create specialized stem cell transfection protocol demand. Kansai region manufacturers respond with process analytical technology investments for real-time residual reagent clearance demonstration.
India
Hyderabad and Bengaluru CDMOs attract investment in GMP transfection infrastructure for export-oriented biologics production. CDSCO streamlined biosimilar approval pathways reduce regulatory friction for contract manufacturing expansion. Domestic biomanufacturing growth concentrates procurement authority among integrated drug developers with multi-asset Phase II pipelines.
Global Transfection Technologies Market Competitive Landscape
Capability concentration sits with specialized viral vector and electroporation platform developers; scale advantage sits with diversified life science conglomerates with global reagent distribution infrastructure. The vendor base stratifies into three tiers: integrated conglomerates with full workflow portfolios, mid-scale specialists with GMP-certified manufacturing capabilities, and regional reagent suppliers serving price-sensitive academic segments. Dominant competitive moves include strategic partnerships between instrument manufacturers and CDMOs for co-developed manufacturing protocols, plus backward integration into GMP-grade plasmid DNA production to secure input supply.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning through global reagent infrastructure and lipofection workflow dominance. Lonza Group occupies a specialized position representing the GMP manufacturing services archetype, anchoring high-value viral vector platform supply. Bio-Rad Laboratories exemplifies the precision instrumentation specialist archetype, with electroporation systems optimized for difficult-to-transfect cell populations. These three company types collectively span the capability spectrum from research-grade reagent supply through clinical-grade manufacturing validation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Lonza Group |
| QIAGEN |
| Merck KGaA |
| Promega Corporation |
| MaxCyte |
| Polyplus-transfection |
| Mirus Bio |
| Others |
Supply & Pricing Matrix
Overcapacity in GMP-grade plasmid DNA manufacturing concentrates pricing leverage among fewer than ten specialized suppliers globally, compressing margins for viral vector producers while elevating procurement costs for CDMOs in Boston and Basel bioclusters. This utilization asymmetry forces mid-scale transfection reagent manufacturers to absorb input volatility or risk losing long-term supply agreements with integrated biopharmaceutical developers.
Pricing Analysis
Geographic price spreads of 40-60 percent separate GMP-certified electroporation systems in the United States from research-grade lipofection reagents in Chinese academic markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and embedded technical service intensity. Cost compression in viral vector manufacturing is intensifying because plasmid DNA supply volatility forces producers to carry redundant inventory buffers. Academic research institutes exhibit highest price sensitivity, while gene therapy CDMOs prioritize validated supply chains over unit cost.
Supply Chain Analysis
Export control regimes limiting microfluidic electroporation instrument flows from the United States and Germany constrain technology transfer to Chinese and Indian biomanufacturing facilities. Supply concentration sits in Switzerland, the United States, and Singapore for precision instrumentation, while plasmid DNA production draws from specialized GMP facilities in the United States and Belgium. Single-source vulnerability in cationic lipid supply chains for lipofection reagents exposes manufacturers to raw material disruption. Distribution runs through authorized distributor networks with technical service attachments for clinical-grade products, direct e-commerce for research reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-viral delivery platforms, particularly lipid nanoparticle systems refined during mRNA vaccine scale-up, present a credible substitution threat to electroporation and viral vector incumbents in gene therapy manufacturing workflows.
For Market Incumbents: Pre-empt margin erosion in viral vector manufacturing by securing captive plasmid DNA supply through backward integration or exclusive offtake agreements with Belgian and US-based GMP producers. Anchor positioning in CRISPR-mediated cell therapy workflows by embedding application scientists within Boston and San Diego biocluster facilities to lock in multi-year reagent procurement contracts before non-viral alternatives achieve regulatory validation.
For New Entrants and Emerging Players: Pursue white-space opportunity in microfluidic electroporation instrumentation for Japanese iPSC-derived therapy developers under PMDA conditional approval frameworks, where viable transfection rates above 60 percent in primary cell populations command premium pricing. Target India's CDSCO-regulated biosimilar manufacturing expansion with GMP-grade lipofection reagents priced below Thermo Fisher and Merck KGaA tier-one positioning. Deploy instrument leasing models with embedded technical training to overcome capital constraints among Shanghai and Suzhou biotechnology startups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GMP-certified viral vector manufacturing platforms as EMA ATMP framework complexity extends validation timelines and forces redundant quality infrastructure investment. Long-term viability favors specialized CDMOs with validated electroporation capacity in proximity to FDA and EMA regulatory clusters over pure-play reagent suppliers facing commoditization pressure. Monitor NMPA cell therapy regulation evolution as signal for Chinese domestic manufacturing substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Plasmid DNA Backward Integration | Secures input supply for viral vector producers facing fewer than ten qualified global suppliers. |
| Microfluidic Electroporation Platform Launch | Captures Japanese iPSC therapy demand under PMDA conditional approval frameworks. |
| Application Scientist Embedded Partnership | Locks multi-year reagent contracts with Boston biocluster gene therapy developers. |
| India GMP Infrastructure Joint Venture | Positions for CDSCO biosimilar manufacturing export growth in Hyderabad and Bengaluru. |
| Process Analytical Technology Integration | Demonstrates real-time residual reagent clearance for EMA ATMP compliance in Netherlands and Belgium. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with gene therapy manufacturing executives, regulatory affairs leads at CDMOs, and procurement managers at US-based biopharmaceutical companies; and secondary validation through FDA gene therapy guidance documents, EMA ATMP framework updates, NMPA cell therapy regulations, ClinicalTrials.gov intervention records, and SEC 10-K filings from listed life science conglomerates. Bottom-up reagent consumption modeling and top-down platform instrumentation revenue triangulation anchored market size estimation.
Forecast inputs considered transfection method type segmentation by application area and cell type, with cross-dimensional analysis across regulatory framework clusters and biocluster geographic concentration. CAGRs derived from instrument replacement cycles, reagent consumption per manufacturing slot, and GMP facility expansion pipelines across the analysis window. CRISPR workflow adoption velocity and lipid nanoparticle formulation technology transfer from vaccine to gene therapy applications served as industry-specific demand drivers.
Sensitivities concentrate around regulatory timeline slippage in FDA accelerated approval pathways, EMA ATMP framework harmonization failures across member states, and Chinese domestic manufacturing substitution under NMPA localization mandates. Forecasts reflect documented assumptions regarding plasmid DNA supply capacity expansion and electroporation instrument precision improvement trajectories. Material shifts in viral vector immunogenicity profiles or non-viral delivery efficiency breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Amino Acid Analyzer Market