
 Balloon Valvuloplasty Device Market | 2026-2036
Balloon Valvuloplasty Device Market Size, Share, and Industry Trends Forecast 2026-2036
Balloon Valvuloplasty Device Market Analysis
Catheter-based delivery miniaturization is tilting engineering priorities toward lower-profile balloon shafts and integrated guidewire lumens. Boston Scientific Corporation leverages polymer science expertise to sustain leadership in high-pressure balloon durability. Edwards Lifesciences Corporation anchors its position through structural heart specialization across multiple valvular indications. Medtronic competes on manufacturing scale, with vertical control over catheter extrusion and balloon molding operations.
Balloon valvuloplasty devices are inflatable, catheter-mounted dilators constructed from nylon, polyethylene terephthalate, or polyurethane films, designed to fracture calcified valve leaflets and restore orifice area under fluoroscopic guidance. Transcatheter balloon systems command the largest revenue share due to their compatibility with percutaneous delivery modes that minimize surgical recovery time. High-pressure balloon variants represent the fastest-expanding product category, driven by rising procedural volumes in aortic stenosis cases where calcific resistance demands rated burst pressures exceeding twenty atmospheres. Standard balloon configurations retain utility in pediatric pulmonary stenosis applications where lower inflation pressures suffice.
FDA premarket notification and EU MDR conformity assessment create dual compliance burdens for manufacturers seeking access to the two largest reimbursement environments. ISO 13485 quality management and IEC 60601 electromagnetic compatibility standards further constrain design validation and clinical testing protocols. Stakeholders must monitor evolving CMS national coverage determinations and EU notified body capacity constraints to anticipate commercialization timelines for next-generation balloon platforms.
Market Dynamics
Transcatheter balloon systems are displacing surgical valvuloplasty across cardiac catheterization labs, compressing procedural recovery windows from weeks to days and forcing device manufacturers to prioritize catheter shaft miniaturization over legacy balloon durability metrics.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited premarket notification for predicate balloon platforms accelerates commercialization timelines for iterative catheter designs.
- Fluoroscopy-guided intervention protocols:Cardiac catheterization labs in Germany and Japan standardize percutaneous delivery techniques, expanding addressable procedural volumes.
- Calcific aortic stenosis prevalence:Aging demographics in Western Europe generate sustained demand for high-pressure balloon variants rated above twenty atmospheres.
Market Restraints
- Nylon and PET film supply concentration:Specialty polymer feedstock for balloon membranes concentrates among Asian chemical processors, exposing manufacturers to input cost volatility.
- EU MDR notified body capacity constraints:Extended conformity assessment timelines delay product launches across the European Economic Area.
- Surgical valve replacement durability:Mechanical and bioprosthetic substitutes retain preference in younger patient cohorts with longer life expectancy horizons.
Strategic Opportunities
- Pediatric pulmonary stenosis applications:Underpenetrated procedural segments in India offer expansion potential for standard-pressure balloon configurations.
- Integrated guidewire lumen convergence:Combining rapid-exchange platforms with optical coherence tomography compatibility enables real-time leaflet visualization.
- Japan's geriatric reimbursement incentives:METI-aligned coverage policies for minimally invasive cardiac interventions reduce patient out-of-pocket burdens.
Industry Challenges
- Interventional cardiologist training pipelines:Specialized fellowship programs for transcatheter valvular procedures face capacity limitations relative to procedural demand growth.
- ISO 13485 quality system recertification:Sustained compliance audits for balloon molding and catheter extrusion operations consume operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balloon Valvuloplasty Device Market |
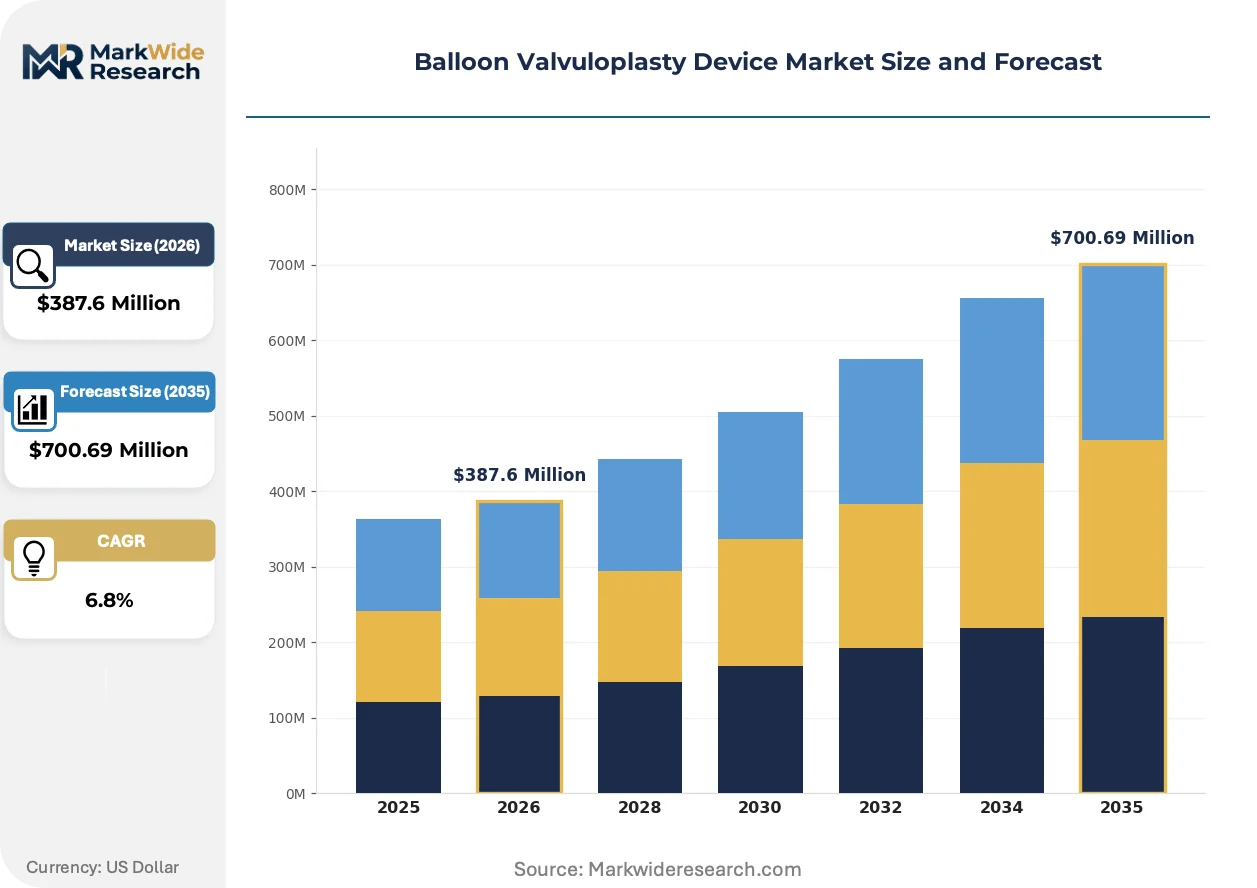
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcatheter Balloon, High-Pressure Balloon, Standard Balloon, Custom Balloon Application: Aortic Stenosis, Mitral Stenosis, Pulmonary Stenosis, Tricuspid Stenosis End User: Hospitals, Cardiac Clinics, Ambulatory Surgery Centers, Research Institutions Delivery Mode: Catheter-Based, Surgical Techniques, Percutaneous Access, Others |
| Companies Covered | Becton, Dickinson and Company, B. Braun SE, Boston Scientific Corporation, Edwards Lifesciences Corporation, Medtronic, Terumo Corporation, TORAY INDUSTRIES, INC., InterValve Medical, Inc., PFM Medical AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balloon Valvuloplasty Device Market Emerging Trajectories
Engineering priorities across balloon valvuloplasty platforms are converging on real-time procedural guidance, polymer film optimization, and cath lab workflow integration. These shifts compress development cycles while elevating performance thresholds.
Optical coherence tomography integration is virtualizing leaflet assessment during balloon inflation. Interventional cardiologists in tertiary cardiac centers adopt OCT-compatible catheter platforms to visualize calcific fracture patterns in real time. This capability is virtualizing the traditional reliance on angiographic silhouette interpretation, reducing fluoroscopy exposure and improving procedural precision.
EU MDR Article 10 technical documentation requirements are reshaping clinical evidence standards for Class III balloon devices. Manufacturers must now submit post-market surveillance data and periodic safety update reports to maintain CE marking validity. High-pressure balloon variants face the steepest compliance burden, as their rated burst pressure claims demand extensive fatigue testing protocols.
Hospital procurement committees are consolidating supplier relationships around full structural heart portfolios rather than standalone balloon devices. Cardiac catheterization labs in the United States increasingly bundle valvuloplasty platforms with transcatheter valve replacement systems under multi-year supply agreements. This concentration is most visible in integrated delivery networks where standardization reduces inventory complexity and training overhead.
Balloon Valvuloplasty Device Market Segmentation
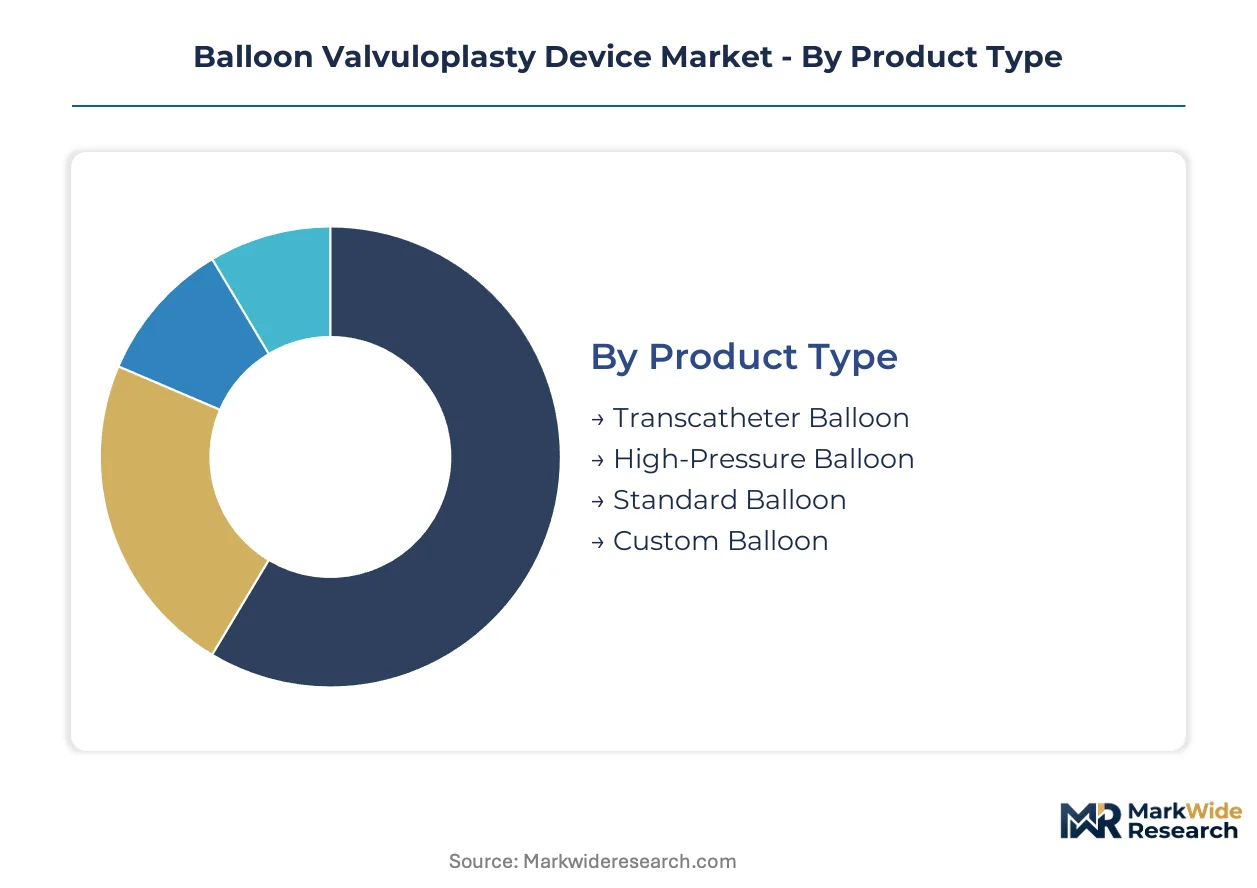
Device segmentation in balloon valvuloplasty tracks divergent engineering requirements across pressure ratings, anatomical targets, and procedural settings. Procurement patterns vary sharply between high-volume hospital systems and specialized cardiac centers, creating distinct commercial entry points for manufacturers.
Product Type:
High-pressure variants turn over fastest as calcific aortic cases surge, while standard balloons retain longer replacement cycles in pediatric applications. Transcatheter platforms command premium positioning through integrated delivery systems.
- Transcatheter Balloon:Catheter-mounted dilators integrate guidewire lumens and radiopaque markers for fluoroscopic navigation. Demand concentrates in German and Japanese cardiac catheterization labs where percutaneous protocols dominate mitral stenosis interventions. These systems displace surgical alternatives by compressing recovery timelines from weeks to days.
- High-Pressure Balloon:Nylon and PET film constructions rated above twenty atmospheres fracture heavily calcified leaflets in aortic stenosis procedures. Western European hospitals drive procurement as aging demographics expand the addressable patient pool. Rated burst pressure claims trigger extensive fatigue testing under EU MDR protocols.
- Standard Balloon:Lower-pressure polyurethane configurations serve pediatric pulmonary stenosis where anatomical compliance reduces force requirements.
- Custom Balloon:Patient-specific geometries address anatomical variations in complex tricuspid cases requiring non-standard dimensions.
Transcatheter balloon systems dominate installed base. High-pressure balloon variants are where expansion concentrates.
Application:
Cost tiering separates emergency aortic interventions from elective mitral procedures, with pulmonary applications occupying a distinct reimbursement band.
- Aortic Stenosis:Calcific valve degeneration in elderly patients demands durable balloon membranes capable of withstanding repetitive inflation cycles. German catheterization labs report the highest procedural volumes for degenerative aortic cases. High-pressure device adoption accelerates as surgical risk scores exclude growing patient cohorts.
- Mitral Stenosis:Rheumatic heart disease remnants and degenerative etiologies create dual demand streams across emerging and developed markets. Japanese tertiary centers specialize in complex mitral interventions requiring precise balloon sizing. Transcatheter delivery compatibility reduces dependency on surgical backup.
- Pulmonary Stenosis:Congenital presentations in pediatric populations utilize lower-pressure configurations with smaller French sizes.
- Tricuspid Stenosis:Rare isolated pathology typically accompanies left-sided valve disease in combined procedural settings.
Aortic stenosis claims the largest procedure volume. Mitral stenosis applications are gaining share fastest.
End User:
Volume concentration differs dramatically between integrated hospital networks and standalone cardiac clinics, with ambulatory migration creating new site-of-service economics.
- Hospitals:Tertiary cardiac centers in the United States and Germany maintain captive catheterization labs with dedicated structural heart teams. These institutions bundle valvuloplasty procurement with transcatheter valve replacement systems under multi-year agreements. Inventory standardization reduces training overhead across high-turnover nursing staff.
- Cardiac Clinics:Specialized outpatient facilities in Japan leverage METI-aligned reimbursement incentives to expand minimally invasive service lines. Fluoroscopy infrastructure investments separate viable operators from general cardiology practices. Procedure throughput constraints limit device inventory breadth.
- Ambulatory Surgery Centers:Emerging site-of-service for low-complexity pulmonary valvuloplasty in selected pediatric cases.
- Research Institutions:Academic medical centers pilot OCT-integrated platforms and next-generation polymer formulations.
Hospitals anchor procurement volume. Cardiac clinics represent the steepest expansion trajectory.
Delivery Mode:
Catheter shaft miniaturization is forcing surgical technique volumes into decline, while percutaneous access protocols standardize across training curricula.
- Catheter-Based:Rapid-exchange and over-the-wire configurations dominate commercial portfolios, with integrated guidewire lumens reducing procedural steps. Boston Scientific and Edwards Lifesciences compete on shaft profile reduction and pushability metrics. FDA 510(k) pathway streamlining accelerates iterative design commercialization.
- Percutaneous Access:Femoral and radial entry sites minimize vascular complications compared to surgical cutdown approaches. Japanese interventionists pioneered transradial valvular access techniques now diffusing to Western European centers. Vascular closure device compatibility influences catheter platform selection.
- Surgical Techniques:Direct valve exposure through thoracotomy or sternotomy retains indication for concomitant procedures.
- Others:Hybrid operating room configurations combine surgical backup with percutaneous primary approaches.
Catheter-based delivery dominates installed base. Percutaneous access protocols are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catheterization labs export procedural expertise and training protocols to cardiac centers across Eastern Europe and the Middle East, establishing a knowledge-transfer corridor that shapes device specifications in recipient markets.
United States
Tertiary cardiac centers in Cleveland and Houston drive procurement of high-pressure balloon systems for calcific aortic interventions. FDA 510(k) premarket notification pathways accelerate iterative catheter commercialization timelines. The Texas Medical Center anchors structural heart specialization, with bundled supply agreements linking valvuloplasty platforms to transcatheter valve replacement systems.
Germany
Rheumatic heart disease remnants and degenerative mitral pathologies sustain procedural volumes in Frankfurt and Munich catheterization labs. EU MDR conformity assessment requirements extend technical documentation obligations for Class III balloon devices. The Baden-Württemberg medical technology cluster concentrates polymer film processing capabilities for balloon membrane production.
Japan
Transradial valvular access techniques pioneered in Tokyo and Osaka diffuse to Western European interventionists. METI-aligned reimbursement policies reduce patient out-of-pocket burdens for minimally invasive cardiac procedures. The Kanto region's geriatric care infrastructure generates sustained demand for percutaneous delivery systems in elderly patient cohorts.
India
Congenital pulmonary stenosis presentations in pediatric populations create demand for standard-pressure balloon configurations. CDSCO medical device registration requirements govern import and distribution pathways for catheter-based platforms. Maharashtra's Mumbai-Pune corridor concentrates cardiac specialty hospitals expanding structural heart service lines.
United Kingdom
NHS England national coverage determinations influence reimbursement thresholds for balloon valvuloplasty procedures. The London-Southeast corridor integrates cardiac catheterization capacity within academic medical centers piloting OCT-compatible platforms. MHRA post-market surveillance requirements align with EU MDR technical documentation standards for device vigilance.
Balloon Valvuloplasty Device Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated vendor base. Scale-driven manufacturers with backward integration into catheter extrusion operations hold procurement advantages in integrated hospital networks. Two strategic archetypes dominate: diversified cardiovascular conglomerates with full structural heart portfolios, and focused interventional specialists with polymer science expertise. Competitive moves concentrate on multi-year supply agreement consolidation and rapid-exchange platform miniaturization.
Among diversified cardiovascular conglomerates, Boston Scientific Corporation and Edwards Lifesciences Corporation exemplify the structural heart portfolio archetype, occupying positions where catheter-based delivery system breadth anchors hospital procurement relationships. Medtronic represents the manufacturing scale archetype with captive supply of balloon molding operations. Terumo Corporation sits within the specialized interventional tier, reflecting Japanese precision engineering traditions in catheter platform design.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun SE |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Medtronic |
| Terumo Corporation |
| TORAY INDUSTRIES, INC. |
| InterValve Medical, Inc. |
| PFM Medical AG |
| Others |
Supply Flow & Price Mechanics
Freight corridors connecting Asian polymer processors to Western European medical device manufacturers transmit raw material cost volatility directly into balloon membrane pricing tiers. These logistics dynamics concentrate procurement leverage among integrated hospital networks while fragmenting margin structures for standalone cardiac clinics.
Pricing Analysis
Current-generation high-pressure balloon platforms command substantial premiums over prior-generation standard configurations, while next-generation OCT-integrated systems are entering at super-premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by rated burst pressure certification and catheter shaft miniaturization complexity. Cost compression in the standard balloon tier is intensifying because Asian chemical processors are consolidating nylon and PET film supply. Integrated delivery networks in Germany and the United States exhibit lowest price sensitivity due to bundled procurement agreements, while standalone cardiac clinics in India face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Asian specialty polymer producers and Western European device manufacturers dominates supply chain risk assessment for balloon membrane feedstock. Nylon and PET film production concentrates in China, Japan, and South Korea, while catheter extrusion operations anchor in Germany and the United States. Raw material dependencies rest on specialty polymer films, radiopaque marker compounds, and precision guidewire alloys. Single-source vulnerability persists for medical-grade polyurethane formulations. Distribution runs through GPO contracts in the United States, direct hospital agreements in Germany, and layered importer-distributor networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The balloon valvuloplasty device market sits in early-cycle expansion, with transcatheter platform penetration in mitral stenosis procedures still below saturation thresholds across Japanese and German cardiac catheterization labs.
For Market Incumbents: Insulate installed base relationships by deepening backward integration into balloon molding operations and securing multi-year supply agreements with integrated delivery networks. The threat of OCT-compatible platforms from specialized interventional players demands accelerated R&D investment in real-time visualization compatibility. Capacity addition in the Baden-Württemberg medical technology cluster reinforces proximity to German catheterization lab demand. For New Entrants and Emerging Players: Build out pediatric pulmonary stenosis service lines in Maharashtra's Mumbai-Pune corridor, where CDSCO registration pathways remain less congested than mature markets. Standard-pressure balloon configurations offer the most penetrable entry point given lower regulatory burden and reduced fatigue testing requirements. A go-to-market angle anchored on distributor partnerships with cardiac specialty hospitals bypasses entrenched GPO relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized medical device divisions lacking structural heart specialization. Long-term viability hinges on sustained procedural volume growth in calcific aortic stenosis interventions as surgical risk scores exclude expanding patient cohorts. The signal to watch is EU MDR notified body capacity expansion timelines, which would decompress commercialization bottlenecks for Class III balloon platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Expedited premarket notification accelerates iterative catheter design commercialization timelines for predicate platforms. |
| CE Marking Pathway | EU MDR Article 10 technical documentation compliance determines market access validity across German and UK hospitals. |
| Hospital System Partnership | Multi-year supply agreements with integrated delivery networks in Texas and Cleveland anchor procurement volume concentration. |
| Software Companion Development | OCT-integrated platforms enable real-time leaflet visualization during balloon inflation in Tokyo tertiary centers. |
| Reimbursement Strategy | METI-aligned coverage policies in Japan reduce patient out-of-pocket burdens for minimally invasive cardiac interventions. |
Methodological Framework
Cross-validation between primary interviews with interventional cardiologists and secondary validation through hospital procurement databases anchors the qualitative findings. Conversations with catheterization lab directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists informed operational constraints and adoption barriers. Secondary sources drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS national coverage determinations, and Japanese METI reimbursement policy circulars. Bottom-up procedural volume estimates and top-down market sizing triangulated demand quantification.
Calibration against historical adoption curves for transcatheter valve replacement systems informed the projection framework. Segmentation dimensions modeled encompass product type, application anatomy, end-user facility tier, and delivery mode complexity. CAGRs derived from fitted growth curves adjusted for regulatory approval timelines and reimbursement policy shifts. Industry-specific forecast inputs incorporated aging demographic trajectories in Western Europe and rheumatic heart disease prevalence patterns in South Asia.
Stress conditions across EU MDR notified body capacity constraints, Asian polymer feedstock price volatility, and interventional cardiologist training pipeline bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedural migration from surgical to percutaneous approaches and OCT platform diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Breast Pumps Market
Medical Devices
External Defibrillator Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Disposable Lancets Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Pleural Catheters Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Slit Lamps Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Anesthesia Laryngeal Masks Market