
 Stoma Care Market | 2026-2036
Stoma Care Market Size, Share, and Industry Trends Forecast 2026-2036
Stoma Care Market Intelligence
CE marking under the EU Medical Device Regulation is bifurcating competitive access between established manufacturers and new entrants. Coloplast Group leverages its integrated manufacturing footprint across Denmark and Hungary to sustain premium positioning in skin barriers and pouches. Hollister Incorporated competes through specialized distribution networks that anchor its presence in North American home care channels.
Stoma care encompasses the clinical management of surgically created openings connecting internal organs to the abdominal surface, utilizing hydrocolloid-based skin barriers with moisture vapor transmission rates between 300-800 g/m²/24h to prevent peristomal complications while enabling controlled effluent collection. Stoma bags occupy the largest revenue pool within product type segmentation, reflecting recurring purchase patterns and patient dependency, while home care settings within end user segmentation represent the fastest structural shift as reimbursement frameworks favor outpatient management. Online stores are gaining share within distribution channel segmentation, displacing traditional medical supply stores among digitally literate patient cohorts.
FDA 510(k) clearance pathways govern U.S. market entry for ostomy appliances, while the EU MDR and ISO 13485 quality management standards collectively elevate clinical evidence requirements for barrier adhesives and extended-wear systems. Japan's PMDA maintains distinct biocompatibility testing protocols that shape product formulation decisions for Asian market access. Stakeholders must monitor evolving reimbursement codes in Medicare and national health systems, as coverage determinations directly influence patient switching costs between one-piece and two-piece appliance systems.
Market Dynamics
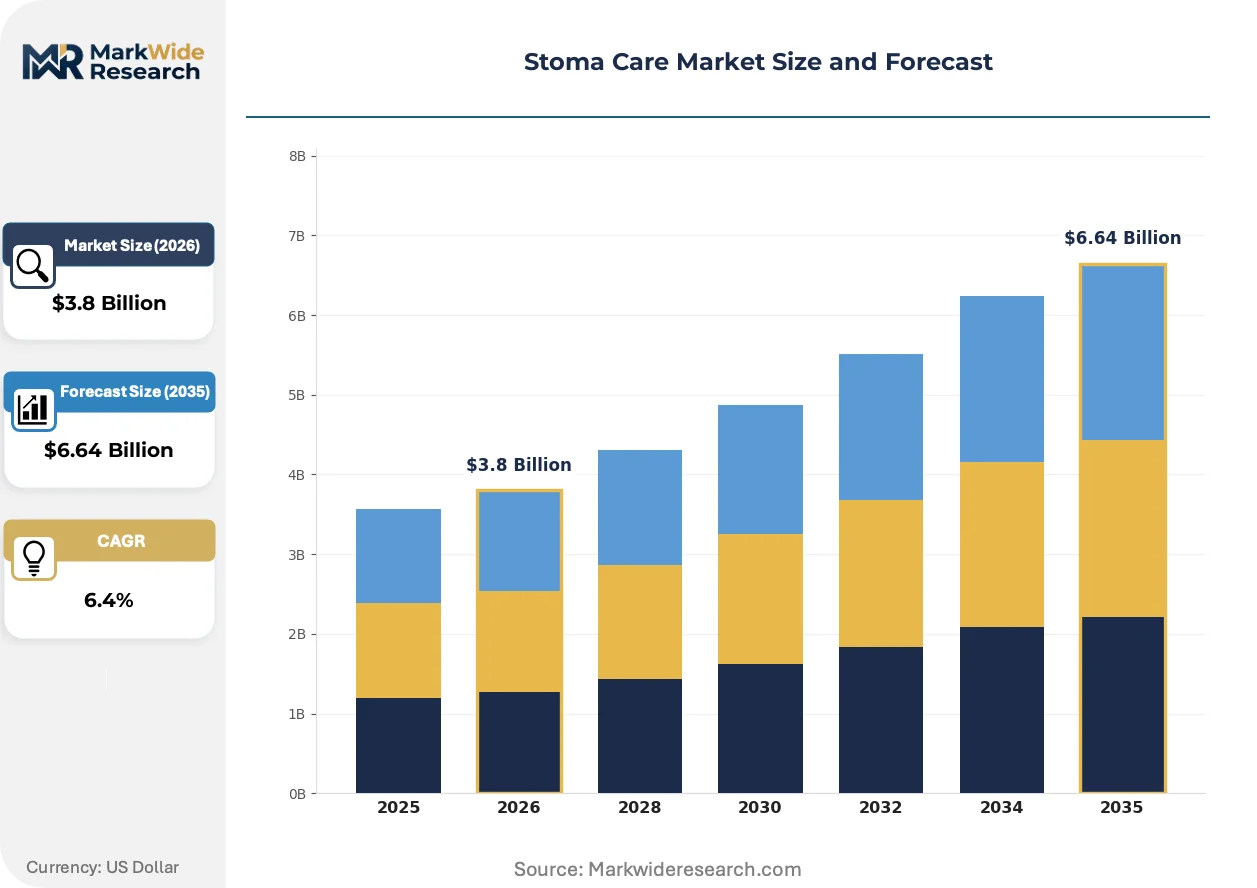
The stoma care market is restructuring around outpatient migration pressures, with Medicare reimbursement codes and EU MDR conformity timelines compressing manufacturer margins while accelerating home care channel development. Hydrocolloid adhesive chemistry and extended-wear barrier systems now determine competitive differentiation.
Growth Catalysts
- MDR Clinical Evidence Requirements:The EU Medical Device Regulation mandates biocompatibility dossiers for barrier adhesives, forcing portfolio rationalization that benefits manufacturers with captive testing infrastructure.
- Home Care Reimbursement Expansion:Medicare Advantage plans in the United States are expanding coverage for one-piece and two-piece appliance systems, reducing institutional dependency for post-operative patients.
- Aging Surgical Volumes:Colorectal cancer screening protocols in Japan and Germany are expanding the incident patient pool requiring permanent or temporary ostomy procedures.
Market Restraints
- Hydrocolloid Input Concentration:Medical-grade pectin and carboxymethylcellulose supply concentrates among three specialty chemical suppliers, creating raw material vulnerability for barrier manufacturers.
- PMDA Biocompatibility Testing:Japan's Pharmaceuticals and Medical Devices Agency maintains distinct cytotoxicity protocols that extend product registration timelines by 18-24 months versus FDA pathways.
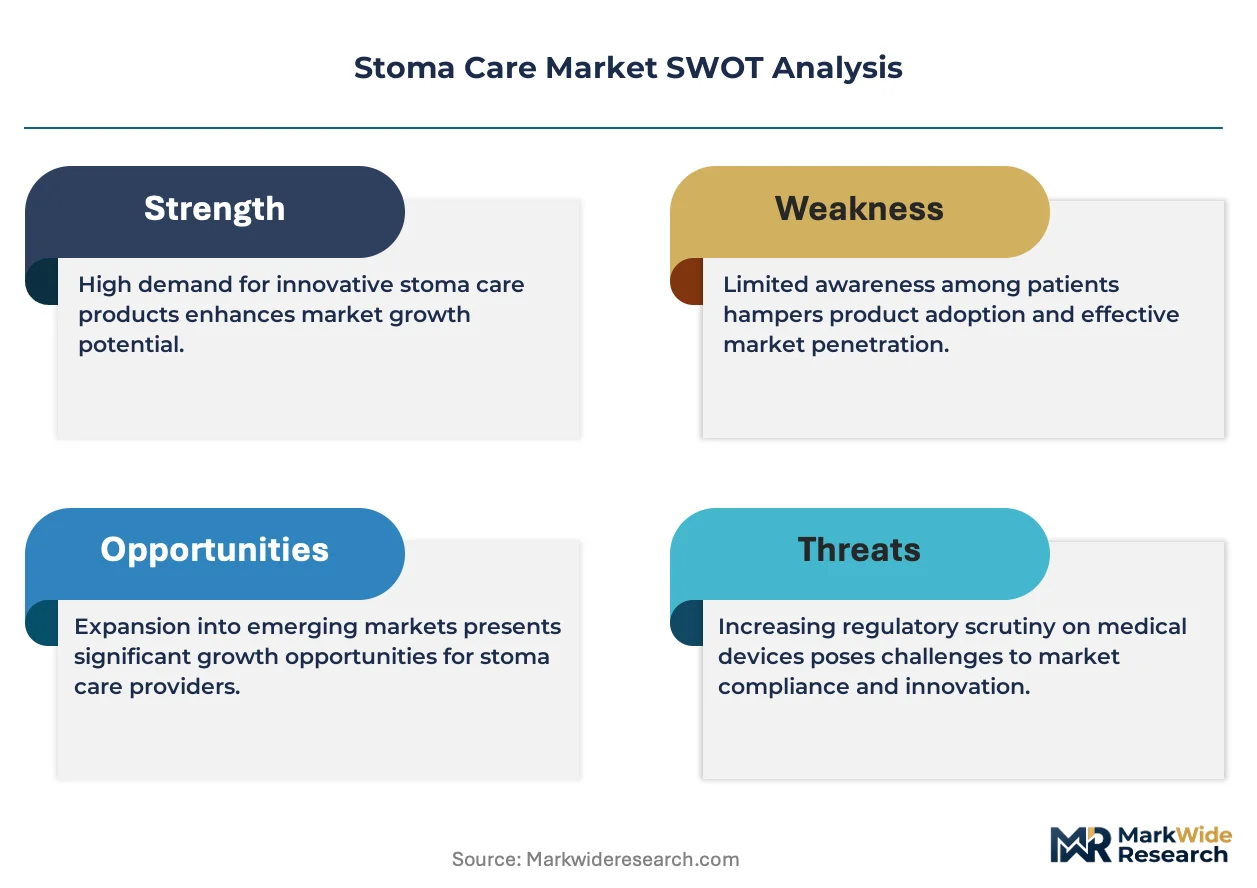
- Skin Barrier Substitution Risk:Silicone-based alternatives are gaining traction among patients with peristomal dermatitis, threatening hydrocolloid market position in sensitivity-prone segments.
Strategic Opportunities
- Direct-to-Patient Subscription Models:Online pharmacies and manufacturer portals are bypassing durable medical equipment distributors, capturing recurring revenue from digitally literate ostomy patients.
- CSRD Supply Chain Disclosure:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for manufacturers with verified sustainable sourcing for pouch films and closure systems.
- Pediatric Application Expansion:Neonatal and adolescent stoma procedures remain underserved by standard adult-form factor appliances, presenting formulation and sizing white space.
Industry Challenges
- Adhesive Formulation Talent Scarcity:Polymer chemists with hydrocolloid-silicone hybrid expertise are concentrated among legacy medical device employers, constraining R&D expansion for mid-tier manufacturers.
- ISO 13485 Audit Backlogs:Notified body capacity constraints under MDR implementation are delaying quality management system certifications, freezing new product introductions for 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stoma Care Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stoma Bags, Skin Barriers, Adhesives, Accessories Application: Colorectal Surgery, Urologic Surgery, Pediatric Use, Geriatric Care End User: Hospitals, Home Care Settings, Long-Term Care Facilities, Outpatient Clinics Distribution Channel: Online Stores, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Coloplast Group, ConvaTec Group PLC, Hollister Incorporated, B. Braun Melsungen AG, ALCARE Co., Ltd., Salts Healthcare, Welland Medical Limited, Cymed, Marlen Manufacturing & Development Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stoma Care Market Strategic Shifts & Innovations
Wearable sensor integration and biodegradable pouch materials are converging to redefine patient monitoring and waste management paradigms. Regulatory pressure on single-use plastics is accelerating material science investment.
Closed-loop ostomy systems with integrated gas filtration and odor neutralization are miniaturizing previously bulky appliance profiles. Home care patients in Denmark and the Netherlands are adopting these systems at rates exceeding institutional forecasts. The technology is compressing differentiation between premium and standard tier offerings by democratizing previously high-end features.
REACH restrictions on persistent organic pollutants are forcing reformulation of adhesive backings and pouch films across EU supply chains. Manufacturers are substituting phthalate-free plasticizers and bio-based polyolefins to maintain market access. Extended-wear barrier segments face the steepest compliance costs due to multi-layer construction complexity.
Patient education platforms are displacing traditional nurse-led fitting consultations as the primary switching cost determinant. Digital onboarding tools from manufacturers and independent patient advocacy sites are reducing brand loyalty stickiness in the United States. Younger patient cohorts demonstrate higher switching rates between one-piece and two-piece systems when presented with comparative efficacy data.
Stoma Care Market Segmentation
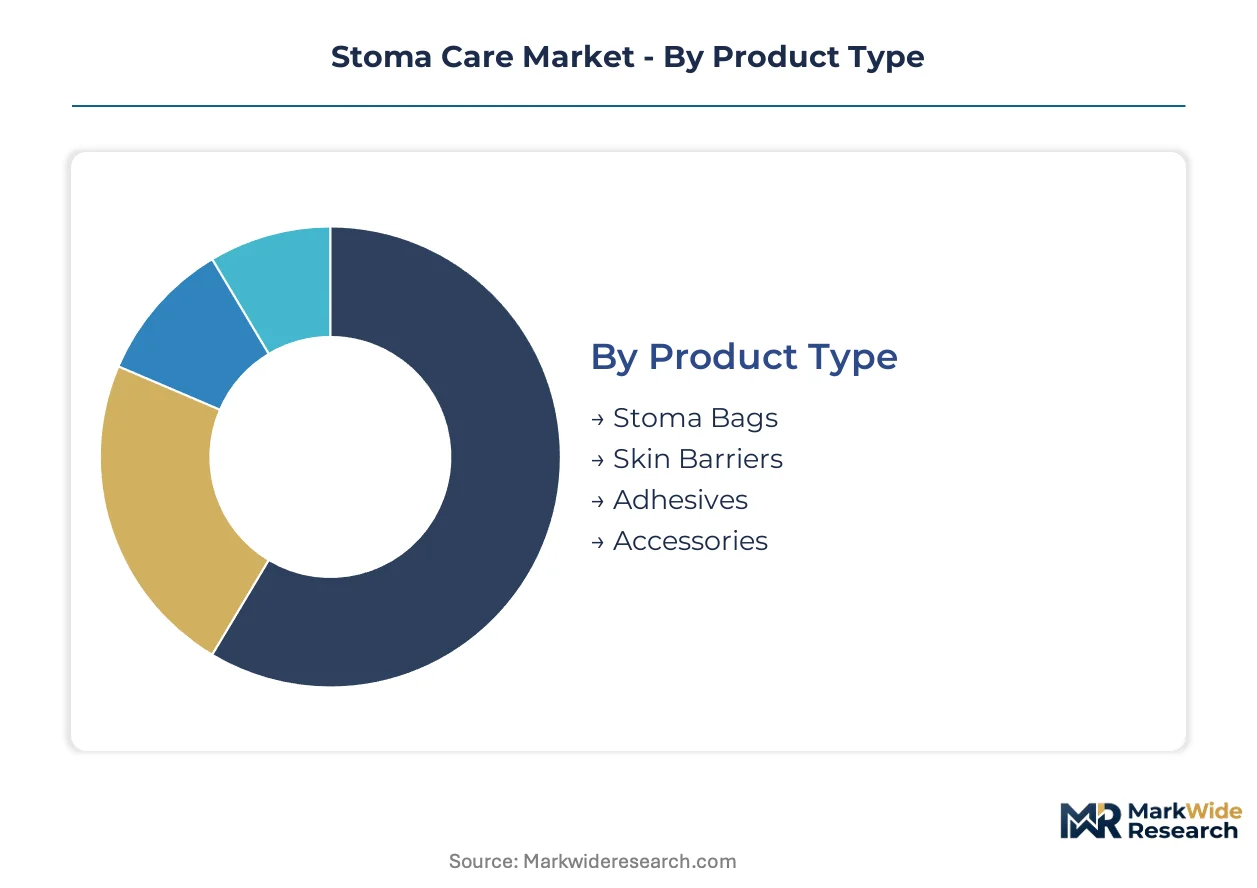
Stoma care segmentation reveals how reimbursement flows, patient acuity, and supply chain access fragment purchasing authority across disconnected decision-makers. Manufacturers must align product specifications with the clinical requirements of surgical teams, the convenience priorities of home care patients, and the procurement constraints of institutional buyers simultaneously.
Product Type:
Skin barriers face the most acute substitution pressure from silicone-based alternatives, while stoma bags defend their position through recurring revenue lock-in and patient habit formation.
- Stoma Bags:These one-piece and two-piece collection systems utilize multi-layer films with odor-barrier properties and integrated closure mechanisms. Demand concentrates in United States Medicare Advantage populations where monthly reimbursement allotments sustain predictable reorder patterns. The recurring purchase dependency of this segment insulates it from competitive switching.
- Skin Barriers:Hydrocolloid-based wafers with moisture vapor transmission rates between 300-800 g/m²/24h protect peristomal skin while enabling appliance adhesion. German and Japanese hospitals specify extended-wear formulations for high-output ileostomy patients, driving premium tier adoption. Silicone flange alternatives threaten market position in dermatitis-prone patient cohorts.
- Adhesives:Medical-grade pressure-sensitive formulations bond barriers to abdominal contours under moisture and mechanical stress conditions.
- Accessories:Deodorants, barrier rings, and pouch covers address patient quality-of-life concerns outside core appliance functionality.
Stoma bags retain volume leadership; skin barriers hold the steepest expansion curve as extended-wear chemistry extends replacement intervals.
Application:
Procedure volume concentration and post-acute care complexity determine where manufacturers allocate clinical education resources and specialized product development.
- Colorectal Surgery:Oncologic resections and diverticular disease interventions create permanent or temporary stomas requiring lifelong or transitional management. United States screening protocol expansion and Japan's aging demographics sustain incident patient pool growth. The clinical complexity of high-output stomas drives demand for advanced barrier systems.
- Urologic Surgery:Cystectomy and urinary diversion procedures generate urostomy patient populations with distinct effluent chemistry and appliance requirements. German university hospitals pioneer continent diversion techniques that reduce permanent stoma incidence, compressing addressable market scope in advanced care settings.
- Pediatric Use:Neonatal necrotizing enterocolitis and congenital anomaly repairs create sizing and adhesion challenges unmet by adult-form factor portfolios.
- Geriatric Care:Age-related skin fragility and dexterity limitations demand simplified application systems and enhanced wear security.
Colorectal surgery anchors revenue concentration; pediatric use climbs the fastest as formulation gaps in neonatal sizing attract development investment.
End User:
Reimbursement migration from institutional to outpatient settings is redistributing purchasing authority away from hospital supply chains toward patient-directed channels.
- Home Care Settings:Post-operative discharge protocols and Medicare Advantage expansion enable patients to manage stoma care outside acute facilities. Denmark and Netherlands lead adoption of closed-loop systems with integrated filtration. The shift compresses differentiation between premium and standard tiers as home-based patients prioritize convenience over clinical feature depth.
- Hospitals:Surgical suites and wound care units specify appliances during acute post-operative phases, establishing initial patient product preferences. United States health systems negotiate centralized contracts that lock in formulary positioning for 24-36 month cycles.
- Long-Term Care Facilities:Skilled nursing environments manage stoma care for cognitively impaired or physically dependent residents requiring staff-assisted appliance changes.
- Outpatient Clinics:Ambulatory surgery centers perform increasing volumes of stoma-creating procedures under accelerated discharge protocols.
Hospitals retain volume leadership; home care settings gain share fastest as reimbursement frameworks favor outpatient management.
Distribution Channel:
Patient digital literacy and insurance portability rules determine whether procurement flows through traditional intermediaries or direct manufacturer relationships.
- Online Stores:Manufacturer portals and specialty pharmacies bypass durable medical equipment distributors to capture recurring revenue from digitally engaged patients. United States ostomy patients under 55 demonstrate switching rates between one-piece and two-piece systems that correlate with digital platform exposure. Subscription models lock in predictable reorder patterns.
- Pharmacies:Retail and mail-order channels serve insured populations with prescription-based appliance coverage under Medicare Part D and commercial plans.
- Medical Supply Stores:Local durable medical equipment dealers retain relevance for rural populations and patients requiring hands-on fitting assistance.
- Direct Sales:Manufacturer field representatives serve hospital and long-term care contract accounts with volume pricing and clinical education bundles.
Medical supply stores retain volume leadership; online stores expand most quickly as digitally literate patient cohorts bypass traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and home care patients constitute the dominant buyer archetypes, with reimbursement portability and digital literacy determining channel preference across national markets.
United States
Medicare Advantage enrollment expansion and colorectal cancer screening protocol intensification drive patient pool growth. FDA 510(k) clearance pathways govern ostomy appliance market entry with streamlined predicate device referencing. Minneapolis and Chicago host specialized durable medical equipment distribution clusters serving Midwest home care populations.
Germany
Aging demographics and diverticular disease intervention volumes sustain surgical stoma creation rates. EMA device conformity requirements under EU MDR elevate clinical evidence standards for barrier adhesives. Bavarian university hospitals pioneer continent diversion techniques that reshape permanent stoma incidence projections.
Japan
National colorectal screening program expansion and geriatric surgical volumes expand incident patient populations. PMDA biocompatibility testing protocols extend product registration timelines versus FDA pathways by 18-24 months. Tokyo-Osaka corridor concentrates specialty medical device distribution infrastructure.
Denmark
Accelerated post-operative discharge protocols and digital health integration drive home care channel development. REACH restrictions on persistent organic pollutants force adhesive backing reformulation across EU supply chains. Copenhagen anchors Coloplast's integrated manufacturing footprint serving premium skin barrier segments.
Netherlands
Outpatient reimbursement frameworks and patient self-management education programs compress institutional dependency. CSRD supply chain disclosure requirements create competitive differentiation for verified sustainable sourcing. Eindhoven medical technology cluster supports closed-loop ostomy system adoption exceeding institutional forecasts.
Stoma Care Market Key Industry Players
Player mix skews toward integrated medical device conglomerates with captive hydrocolloid manufacturing and specialized ostomy-focused mid-tier specialists. Market structure concentrates revenue among three dominant archetypes: diversified wound care multinationals, regional European manufacturers with MDR-ready quality systems, and Asia-Pacific specialists navigating PMDA registration complexity. Capacity expansion in extended-wear barrier chemistry and strategic partnerships for biodegradable pouch materials constitute the dominant competitive moves.
Within the diversified multinational tier, Coloplast Group and ConvaTec Group PLC exemplify archetypes with integrated manufacturing footprints and premium positioning in skin barriers and collection systems. Hollister Incorporated occupies a position among North American channel specialists with concentrated presence in home care distribution networks. These three entities represent the structural concentration around hydrocolloid chemistry expertise and regulatory compliance infrastructure that defines competitive differentiation.
| Leading Market Players |
|---|
| Coloplast Group |
| ConvaTec Group PLC |
| Hollister Incorporated |
| B. Braun Melsungen AG |
| ALCARE Co., Ltd. |
| Salts Healthcare |
| Welland Medical Limited |
| Cymed |
| Marlen Manufacturing & Development Company |
| Others |
Cost & Logistics Intelligence
Ninety-day hydrocolloid inventory cycles at Danish manufacturing hubs concentrate pricing power among three specialty chemical suppliers while compressing margins for mid-tier barrier manufacturers navigating EU MDR compliance timelines. This lead-time band reflects the tight coupling between medical-grade pectin availability and extended-wear skin barrier production economics.
Pricing Analysis
Cost-plus contracts with medical-grade carboxymethylcellulose indexation dominate raw material procurement for hydrocolloid barrier manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates extended-wear formulations with 7-day adhesion from basic 3-day systems and economy pouches without odor barriers. Pricing pressure stems from silicone flange substitution in dermatitis-prone patient segments, eroding hydrocolloid premium capture. Home care patients under Medicare Advantage demonstrate highest price sensitivity, while German hospital procurement committees prioritize clinical performance over unit cost.
Supply Chain Analysis
Inventory buffers for hydrocolloid adhesives stretch 60-90 days as Danish and Hungarian manufacturing sites balance REACH-compliant reformulation against production continuity. Denmark, Hungary, and the United States anchor medical-grade pectin processing and barrier lamination capacity. Raw material dependencies center on carboxymethylcellulose, medical-grade polyolefins, and silicone elastomers. Single-source vulnerability concentrates in three specialty chemical suppliers controlling pharmaceutical-grade pectin extraction. Distribution runs through durable medical equipment distributors for institutional accounts and direct-to-patient portals for reimbursed home care populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stoma care sits in early-cycle expansion as home care reimbursement frameworks and closed-loop system adoption compress institutional dependency while expanding addressable patient lifetime value.
For Market Incumbents: Shield premium positioning in extended-wear barriers by accelerating captive hydrocolloid testing infrastructure under EU MDR clinical evidence requirements. Backward integration into medical-grade pectin processing defends margin structure against raw material concentration among three specialty chemical suppliers. ISO 13485 certification investment freezes out mid-tier competitors facing 12-18 month notified body backlogs. For New Entrants and Emerging Players: FDA 510(k) predicate device pathways offer faster clearance than PMDA biocompatibility protocols, opening U.S. home care channels for digitally native subscription models. Pediatric sizing white space in neonatal and adolescent stoma applications remains underserved by adult-form factor portfolios. Direct-to-patient portals bypass incumbent distributor relationships among Medicare Advantage populations. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue healthcare consumables play because patient dependency on monthly pouch replenishment generates predictable cash flows insulated from clinical substitution. Acquisition targets with EU MDR-ready quality systems and REACH-compliant adhesive formulations command strategic premium. Watch PMDA registration timeline compression as signal for Asia-Pacific market entry inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Clinical evidence dossiers for barrier adhesives bifurcate competitive access between established and new entrants. |
| Hospital System Partnership | U.S. health system formulary contracts lock in 24-36 month procurement cycles for acute-phase patient conversion. |
| Direct-to-Patient Subscription Launch | Online portals capture recurring revenue from digitally literate ostomy patients bypassing durable medical equipment distributors. |
| Biodegradable Pouch Material Development | REACH restrictions on persistent organic pollutants force reformulation investment to maintain EU market access. |
| Software Companion Development | Patient education platforms reduce nurse-led fitting consultation switching costs and accelerate brand switching. |
Research Approach
The analysis maps skin barriers, stoma bags, adhesives, and accessories, each validated through procurement managers at hospital systems, biomedical engineers at wound care units, GPO contracts managers, and home care patient advocacy coordinators. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and hospital procurement contract disclosures. Bottom-up patient pool modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with regional regulatory clusters as cross-cutting variables. CAGRs derived from procedure volume trajectories, reimbursement code expansion patterns, and patient switching cost elasticity. Forecast inputs incorporated colorectal screening protocol intensification and Medicare Advantage enrollment migration.
Decision-makers should treat outputs as directional under assumptions of stable reimbursement frameworks and MDR implementation timelines; material deviation in notified body capacity or hydrocolloid supply concentration would warrant model refresh. Specific risk factors include REACH regulatory expansion, silicone flange substitution acceleration, and PMDA protocol harmonization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Physical Therapy Supplies Market