
 South America Oil and Gas Storage Tank Market | 2026-2036
South America Oil and Gas Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
South America Oil and Gas Storage Tank Market Insights
The divergence between premium corrosion-resistant tank specifications and commodity carbon steel installations is hardening across South America. Petrobras SA anchors the premium tier through its dominance of pre-salt logistics infrastructure, while Shawcor leverages its composite material expertise to differentiate in coastal corrosion environments. McDermott International Ltd competes on modular fabrication scale for remote upstream deployments.
Oil and gas storage tanks are welded or bolted pressure vessels engineered to API 650 and API 620 standards, with shell courses typically fabricated from ASTM A285 or A516 carbon steel plate and designed to contain hydrocarbons at atmospheric or low internal pressure. Above ground steel tanks sustain the largest installed base across the region, though fiberglass and composite alternatives are capturing share in offshore platform and chemical plant applications where weight reduction and saltwater corrosion resistance command structural priority. Terminal operators represent the fastest-growing end user category as independent storage providers expand hub capacity along Brazil's coast, while fixed roof designs retain maturity in conventional crude service even as floating roof systems gain traction for volatile product containment.
ANP in Brazil, Argentina's Secretariat of Energy, and Peru's OSINERGMIN enforce tank integrity standards that directly shape inspection cycles, retrofit obligations, and new construction specifications across their respective jurisdictions. These frameworks elevate demand for certified welding procedures, cathodic protection systems, and secondary containment engineering. Stakeholders must weigh the capital efficiency of brownfield retrofits against greenfield modular construction as regulatory stringency tightens and labor mobility constraints persist.
Market Dynamics
Brazil's ANP regulatory tightening on tank integrity and emissions monitoring is forcing terminal operators to accelerate capital deployment toward corrosion-resistant specifications, creating a bifurcation between premium composite installations and commodity carbon steel retrofits.
Growth Catalysts
- Pre-salt logistics expansion:Petrobras SA's offshore production corridors require dedicated floating storage and offloading vessels, pulling demand for specialized tank fabrication along Brazil's southeastern coast.
- ANP Resolution 783:Mandatory ultrasonic thickness monitoring and cathodic protection upgrades for existing above-ground storage tanks are triggering inspection-driven replacement cycles.
- Independent terminal proliferation:Third-party storage providers are constructing greenfield hub capacity near Santos and Paranaguá to capture arbitrage flows between domestic refining and import terminals.
Market Restraints
- ASTM A516 plate volatility:Carbon steel input costs fluctuate with Brazilian flat-rolled import tariffs, compressing margins for commodity tank fabricators serving midstream distributors.
- Specialized welding labor scarcity:Certified API 650 welders concentrate in São Paulo and Rio de Janeiro industrial zones, constraining project velocity in Peru and Colombia.
- Composite material substitution ceiling:Fiberglass reinforced polymer tanks face pressure rating limitations above 50,000 barrels, capping penetration in large crude storage applications.
Strategic Opportunities
- Argentina Vaca Muerta midstream gap:Neuquén Basin shale production lacks sufficient condensate storage infrastructure, creating first-mover positioning for modular tank farm developers.
- Colombia Pacific coast corridor:Buenaventura port expansion plans include petroleum product storage zones where floating roof specifications remain undersupplied.
- Chilean mining-energy nexus:Copper belt diesel demand is pulling tank construction toward Antofagasta and Calama logistics clusters with seismic-resistant API 620 designs.
Industry Challenges
- API 653 recertification bottlenecks:Tank inspection intervals have compressed from ten to five years under ANP amendments, overwhelming certified inspector availability.
- Legacy fixed-roof retrofit complexity:Converting atmospheric tanks to floating roof configurations for volatile product service requires structural reinforcement engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Oil and Gas Storage Tank Market |
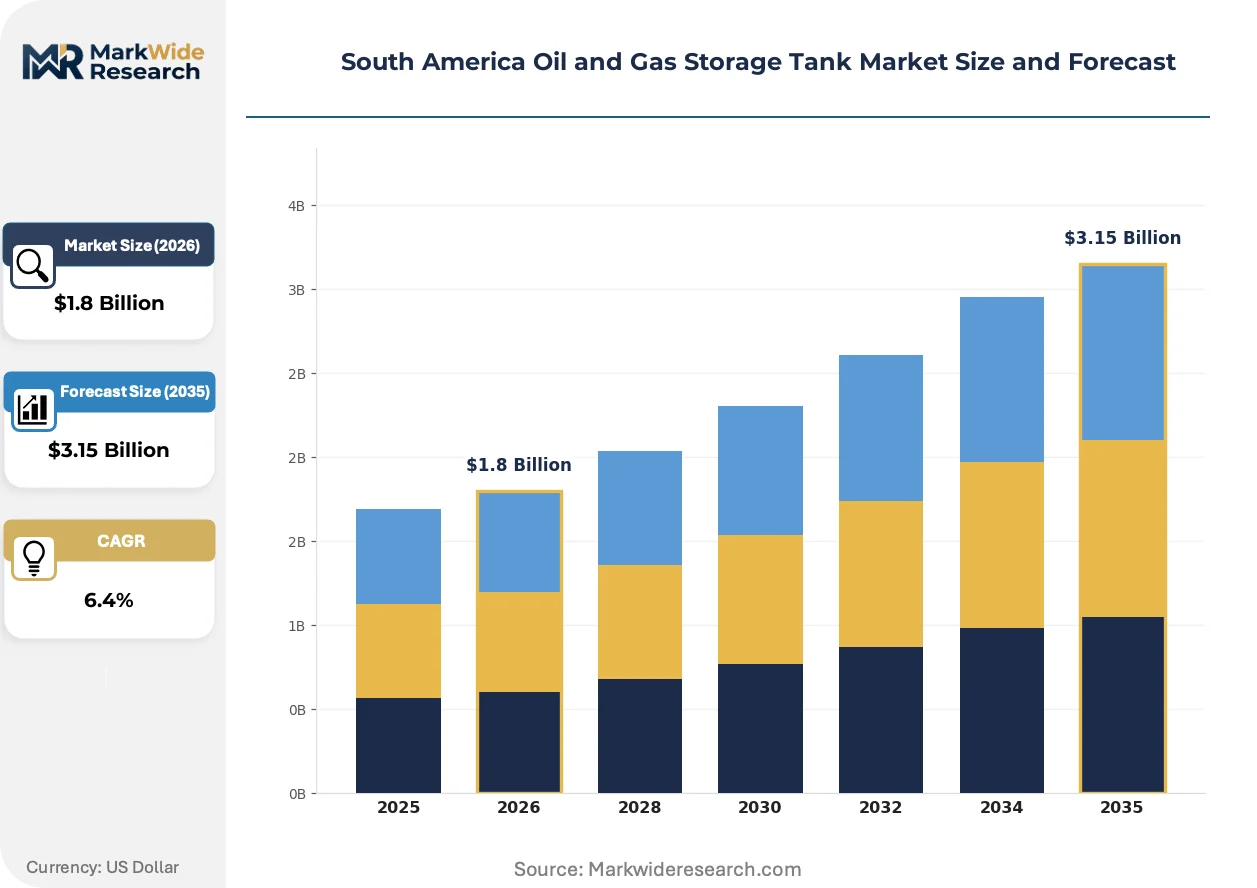
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Above Ground, Underground, Floating Roof, Fixed Roof Material: Steel, Fiberglass, Aluminum, Composite End User: Oil Refineries, Chemical Plants, Terminal Operators, Distribution Facilities Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | Sener, McDermott International Ltd, Shawcor, Petrobras SA, YPF S.A, Rosen Group, Caldwell Tanks Inc, Vitol Tank Terminals International BV (VTTI), Petróleo Brasileiro S.A, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Oil and Gas Storage Tank Market Trends and Innovations
Digital integrity monitoring systems and advanced composite materials are actively displacing conventional inspection regimes and carbon steel specifications across South American storage infrastructure.
Composite tank technologies incorporating vinyl ester resin matrices and fiberglass reinforcement are rewriting coastal corrosion protection economics. Offshore platform operators in Brazil's Campos Basin are specifying these systems for produced water and chemical storage, eliminating recurring sandblasting and recoating cycles. The shift is compressing total cost of ownership calculations for twenty-year asset life comparisons.
ANP's integration of real-time emissions monitoring into operating permits is tightening leak detection and repair protocols. Terminal operators must now deploy automated tank gauging with vapor recovery unit interlocks, elevating capital requirements for new construction. Brazil's southeastern refining corridor is responding fastest, with Santos-based independents leading retrofit installations.
Integrated service contracts bundling engineering, procurement, and construction with decade-long maintenance obligations are displacing transactional tank procurement. National oil companies favor single-source accountability for remote upstream deployments, particularly in Amazon Basin logistics constrained sites. This consolidation is most visible in Ecuador's Oriente production fields where operator staffing limitations drive outsourcing preference.
South America Oil and Gas Storage Tank Market Segmentation
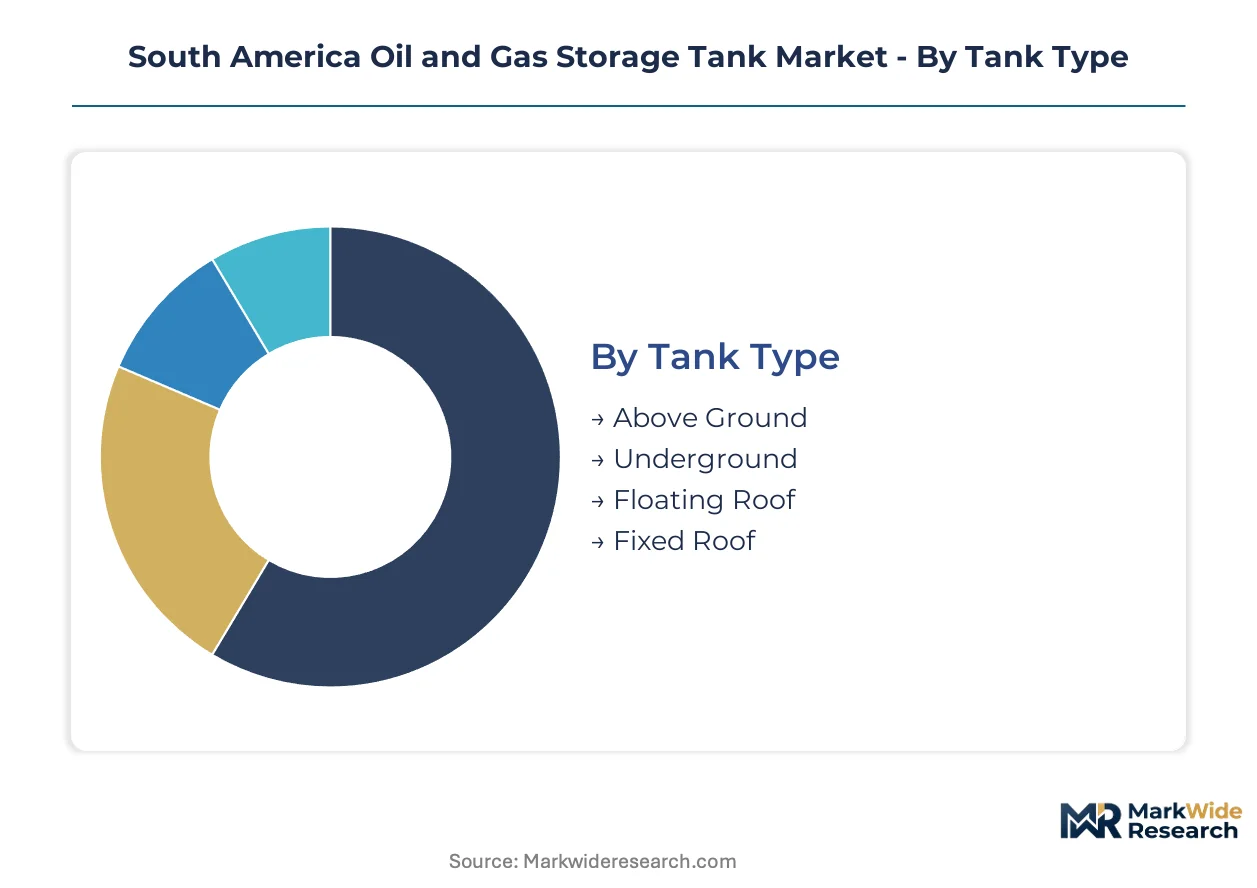
Storage tank procurement across South America fragments sharply by corrosion exposure, seismic risk, and regulatory jurisdiction. Buyers optimize capex against inspection burden, driving specification divergence between coastal terminals and inland refineries.
Tank Type:
Application environment and vapor emission exposure separate buyers across this category.
- Above Ground:Welded carbon steel vessels fabricated to API 650 dominate Brazil's southeastern refining corridor. ANP Resolution 783 mandates ultrasonic thickness monitoring, pushing terminal operators toward corrosion-resistant coatings for coastal installations.
- Floating Roof:Internal and external floating roof designs seal volatile product storage against vapor losses. Demand concentrates at Santos and Paranaguá independent terminals where gasoline and ethanol blending operations require emission-compliant containment.
- Fixed Roof:Atmospheric cone roof structures serve conventional crude service at legacy refineries. Argentina's YPF operates extensive fixed-roof farms at La Plata and Luján de Cuyo facilities.
- Underground:Buried steel or fiberglass systems address space-constrained urban distribution depots. Chile's Santiago metropolitan zone specifies these for retail fuel station networks.
Volume sits with fixed roof designs at established refineries; growth tilts toward floating roof specifications at independent coastal terminals.
Material:
Total cost of ownership calculations split procurement between commodity steel and premium corrosion-resistant alternatives.
- Steel:ASTM A285 and A516 carbon steel plate constitutes the baseline specification for large crude storage. Brazilian fabricators source plate from domestic flat-rolled mills, though import tariff volatility compresses margins.
- Composite:Vinyl ester resin matrices with fiberglass reinforcement eliminate recurring maintenance cycles. Petrobras pre-salt platforms specify these for produced water handling in Campos Basin salt spray environments.
- Fiberglass:Reinforced polymer tanks penetrate chemical plant and offshore platform applications where weight reduction matters. Pressure rating limitations above 50,000 barrels constrain crude storage adoption.
- Aluminum:Geodesic dome roofs and specialty alloy shells serve floating roof seals and cryogenic service. Limited penetration outside LNG adjacent storage.
Steel dominates transaction volume; composite alternatives are climbing the fastest in offshore and coastal corrosion zones.
End User:
Capital deployment timelines and regulatory exposure differentiate procurement patterns across buyer categories.
- Terminal Operators:Independent storage providers construct greenfield hub capacity near Brazil's port complexes. ANP emissions monitoring requirements force automated gauging and vapor recovery investments.
- Oil Refineries:Petrobras and Argentina's YPF operate integrated tank farms tied to downstream processing units. Brownfield retrofit obligations dominate capex over new construction.
- Chemical Plants:Specialty chemical and petrochemical facilities require lined or alloy-constructed vessels for aggressive fluid service. Brazil's Triunfo complex and Argentina's Bahía Blanca cluster drive specification.
- Distribution Facilities:Midstream distributors and retail supply depots prioritize rapid-deploy modular tanks. Labor mobility constraints in Peru and Colombia limit project velocity.
Refinery demand anchors installed base volume; terminal operators show the steepest expansion trajectory as third-party storage proliferates.
Capacity:
Economies of scale in fabrication and foundation engineering concentrate procurement at opposite ends of the size spectrum.
- Large Scale:Tanks exceeding 100,000 barrels serve crude export terminals and refinery feedstock storage. Foundation and wind load engineering dominate project economics at this scale.
- Medium Scale:25,000 to 100,000 barrel vessels balance throughput flexibility against capital efficiency. Colombia's Pacific coast corridor plans target this range for Buenaventura petroleum product zones.
- Extra Large:Ultra-large crude carriers and dedicated floating storage units exceed standard API 650 scope. Petrobras pre-salt logistics corridors pull specialized fabrication demand.
- Small Scale:Package tanks and skid-mounted systems serve remote upstream production and mining diesel supply. Chilean copper belt operations in Antofagasta specify seismic-resistant API 620 designs.
Large scale units command capital deployment volume; small scale modular systems are gaining share fastest in remote and constrained logistics environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santos anchors South American storage tank demand through its pre-salt logistics corridor and independent terminal proliferation. Brazil's southeastern refining cluster concentrates capital deployment, while Argentina's shale basins and Colombia's Pacific expansion create secondary growth poles across the region.
Brazil
Petrobras SA's pre-salt production corridors pull specialized fabrication demand toward Rio de Janeiro and São Paulo industrial zones. ANP Resolution 783 mandates ultrasonic thickness monitoring and cathodic protection upgrades, compressing inspection cycles from ten to five years. Terminal operators near Santos and Paranaguá are constructing greenfield hub capacity to capture arbitrage flows between domestic refining and import terminals.
Argentina
Vaca Muerta shale production in the Neuquén Basin lacks sufficient condensate storage infrastructure, creating deployment opportunities for modular tank farm developers. The Secretariat of Energy enforces tank integrity standards that shape inspection cycles and retrofit obligations across the country's refining footprint. YPF operates extensive fixed-roof farms at La Plata and Luján de Cuyo facilities while independent midstream developers target the shale corridor.
Colombia
Buenaventura port expansion plans include petroleum product storage zones where floating roof specifications remain undersupplied. OSINERGMIN regulates tank integrity standards that directly influence new construction specifications and secondary containment engineering requirements. Labor mobility constraints limit project velocity in Pacific coast corridor developments despite infrastructure investment commitments.
Chile
Copper belt diesel demand is pulling tank construction toward Antofagasta and Calama logistics clusters with seismic-resistant API 620 designs. The Santiago metropolitan zone specifies underground fiberglass systems for retail fuel station networks constrained by urban space limitations. Mining-energy nexus investments are accelerating procurement of small-scale package tanks for remote operations.
Peru
Amazon Basin logistics constraints drive outsourcing preference for integrated service contracts bundling engineering, procurement, and construction with long-term maintenance obligations. OSINERGMIN enforcement of tank integrity standards elevates demand for certified welding procedures and cathodic protection systems. Labor scarcity for certified API 650 welders concentrates project execution capacity in Lima-Callao industrial zones.
South America Oil and Gas Storage Tank Market Competitive Landscape
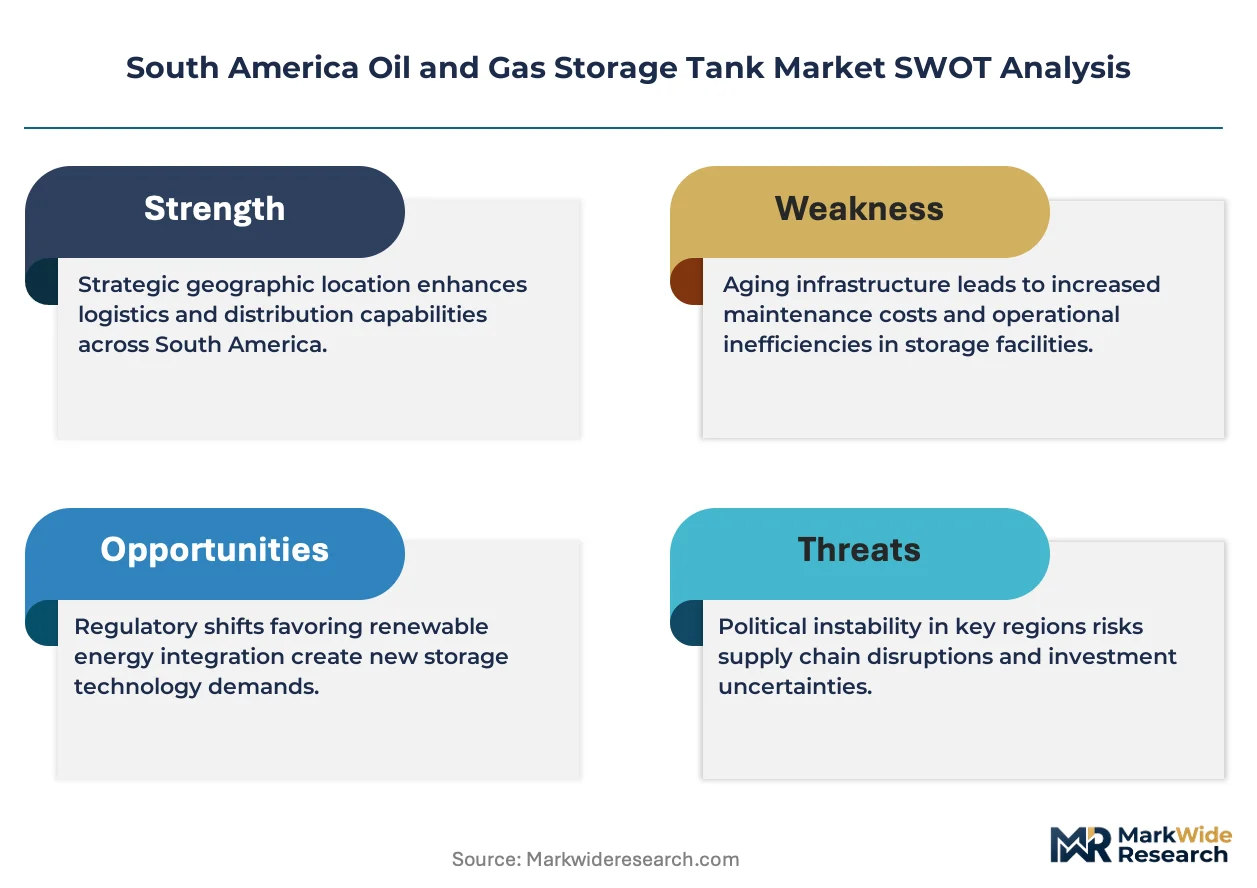
Premium-margin players sit above commodity-margin players across corrosion resistance and fabrication complexity. The market structures around three tiers: national oil companies controlling integrated infrastructure, specialized fabricators delivering modular solutions for remote deployments, and composite material specialists penetrating coastal corrosion environments. Strategic moves concentrate on brownfield retrofit contracting against greenfield modular construction, with integrated service contracts displacing transactional procurement.
Among the named participants, Petrobras SA and YPF S.A. occupy positions as national oil company anchors with captive infrastructure ownership. McDermott International Ltd exemplifies the large-scale fabrication archetype, while Shawcor represents composite material specialization for aggressive service environments. These three entities illustrate the competitive vectors shaping procurement decisions across Brazilian pre-salt logistics, Argentine shale midstream gaps, and coastal corrosion protection specifications.
| Leading Market Players |
|---|
| Sener |
| McDermott International Ltd |
| Shawcor |
| Petrobras SA |
| YPF S.A |
| Rosen Group |
| Caldwell Tanks Inc |
| Vitol Tank Terminals International BV (VTTI) |
| Petróleo Brasileiro S.A |
| Others |
Pricing and Supply Chain Analysis
ASTM A516 carbon steel plate volatility cascades through South American tank fabrication economics, compressing margins for commodity fabricators serving midstream distributors while elevating premium-tier pricing power for corrosion-resistant composite specialists. Brazilian flat-rolled import tariffs amplify this divergence, forcing terminal operators toward long-term offtake contracts that lock in coating specifications and cathodic protection bundles.
Pricing Analysis
Value-based pricing anchored to inspection-cycle outcomes separates premium fabricators from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—API 653 recertification bundling commands highest tiers, while uncoated carbon steel retrofits compete on volume scale. Cost compression in the standard tier intensifies because Brazilian plate import tariffs squeeze midstream distributor budgets. Terminal operators show least price sensitivity for coastal corrosion protection, while inland distribution facilities prioritize rapid-deploy modular economics.
Supply Chain Analysis
Dual-sourcing requirements from ANP-mandated contractor qualification lists force terminal operators to maintain approved fabricator relationships across Brazil, Argentina, and Colombia. Raw material feeds draw from domestic Brazilian flat-rolled mills, imported ASTM plate from North American mills, and vinyl ester resin systems from specialized chemical suppliers. Single-source vulnerability concentrates in certified API 650 welding labor pools centered on São Paulo and Rio de Janeiro. Distribution runs through integrated EPC contractors bundling engineering, procurement, and decade-long maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANP Resolution 783 functions as a cost-of-compliance moat, elevating capital barriers for uncertified competitors while rewarding incumbent fabricators with established inspection and recertification capabilities. Compliant players capture pricing premiums as regulatory stringency tightens.
For Market Incumbents:Lock in brownfield retrofit contracting relationships before five-year inspection cycles overwhelm certified inspector availability. Vertical integration into cathodic protection system supply secures margin capture against commodity fabricators. Composite material certification investments defend positioning as coastal corrosion specifications harden.
For New Entrants and Emerging Players:ANP Resolution 783 in Brazil opens a window for specialized inspection and recertification service providers. Argentina's Vaca Muerta shale corridor presents the most penetrable geography for modular tank farm developers. Target integrated service contract bundling as the go-to-market angle, leveraging decade-long maintenance obligations to displace transactional procurement.
For Investors and Strategic Acquirers:Compressed API 653 inspection intervals from ten to five years is the leading indicator that recertification service demand will outpace fabrication capacity growth. Long-term viability favors vertically integrated specialists combining fabrication, inspection, and maintenance capabilities. Watch for ANP enforcement actions against non-compliant terminals as the signal for accelerated replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Certification Program | Vinyl ester resin qualification unlocks Petrobras pre-salt platform specifications in Campos Basin salt spray environments. |
| Integrated Service Contract Expansion | Bundling EPC with decade-long maintenance displaces transactional procurement in Amazon Basin logistics-constrained sites. |
| Backward Integration into Coating Supply | Cathodic protection system captive production secures margin capture against ASTM plate volatility. |
| Modular Fabrication Scale-Up | Remote upstream deployment capability addresses Vaca Muerta shale midstream infrastructure gaps. |
| Digital Integrity Monitoring Platform | Real-time emissions monitoring integration meets ANP operating permit requirements for Santos terminal operators. |
Research Methodology
Trade flow databases, ANP regulatory filings, and petrochemical industry association reports formed the secondary backbone, cross-referenced against primary interviews with tank farm operations managers, EPC procurement leads, certified API 653 inspectors, and cathodic protection system engineers. Bottom-up project pipeline tracking triangulated against top-down terminal capacity utilization modeling to validate volume assumptions across the analysis window.
Bottom-up segmentation by tank type, material specification, end-user category, and capacity tier anchored the analytical framework, with growth rates derived from project announcement velocity and regulatory compliance cycle compression. Modeled inputs included pre-salt logistics corridor expansion timelines, ANP inspection interval amendments, and composite material penetration curves in coastal corrosion environments.
The model assumes a particular technology adoption path; alternative pathways for digital integrity monitoring and automated tank gauging would alter the outlook if deployment accelerates beyond Santos-based independent terminal adoption. Deviation in ANP enforcement intensity or ASTM plate tariff policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Digital Oilfield Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
North America Shale Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Oilwell Completion Tools Market