
 Italy Magnetic Resonance Imaging Market | 2026-2036
Italy Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Magnetic Resonance Imaging Market Foresight
A widening capital-intensity divergence between installed-base incumbents and emerging system vendors is unwinding traditional procurement patterns in Italian radiology. Siemens Healthineers leverages its domestic manufacturing footprint in Forchheim to sustain shorter delivery cycles for high-field systems across Lombardy and Veneto. Esaote SpA anchors its competitive stance through specialized extremity MRI designs that occupy niche outpatient segments where space constraints dominate purchasing criteria.
Magnetic resonance imaging denotes a non-invasive diagnostic modality employing strong magnetic fields, typically 1.5 to 3.0 Tesla for clinical systems, and radiofrequency pulses to generate detailed tomographic images of soft tissues, organs, and physiological processes without ionizing radiation exposure. Superconducting MRI systems dominate Italian hospital procurement due to superior signal-to-noise ratios and faster acquisition protocols, though permanent magnet configurations retain relevance in smaller imaging centers constrained by helium supply logistics and infrastructure budgets. Closed MRI architectures lead installed capacity while functional MRI gains traction in research institutes mapping neural activation patterns for pre-surgical planning.
Italy's Ministry of Health collaborates with CE marking requirements under EU Medical Device Regulation to shape safety benchmarks and post-market surveillance obligations for MRI manufacturers. The Italian Medicines Agency enforces conformity assessment protocols that extend time-to-market for non-EU vendors while reinforcing quality assurance standards for domestic distribution networks. Stakeholders must monitor evolving reimbursement thresholds for advanced MRI sequences and the regional fragmentation of healthcare commissioning across Italy's autonomous provinces.
Market Dynamics
Italy's MRI market confronts a structural squeeze between helium supply chain fragility and the Ministry of Health's reimbursement compression for standard imaging sequences. Public hospital procurement timelines elongate as regional health authorities demand outcome documentation before releasing capital budgets.
Growth Catalysts
- Helium recycling infrastructure:Closed-loop cryogenic systems reduce dependency on volatile global helium markets. University hospital networks in Lombardy deploy these systems to stabilize operating costs.
- Oncology protocol expansion:Advanced MRI sequences for tumor characterization gain priority in regional cancer network tenders. The Italian Ministry of Health's essential levels of care framework mandates diagnostic imaging access.
- Neurology caseload concentration:Northern Italy's aging demographic accelerates demand for dementia and stroke imaging. Specialized stroke units in Emilia-Romagna require 24/7 MRI availability.
Market Restraints
- Superconducting magnet cost concentration:Liquid helium price volatility strains operational budgets for 3.0 Tesla systems. Smaller imaging centers in southern Italy defer fleet upgrades.
- CE marking timeline friction:EU Medical Device Regulation conformity assessment extends time-to-market for non-EU vendors. Domestic distributors face working capital pressure from inventory holding periods.
- Permanent magnet performance ceiling:Signal-to-noise ratio limitations restrict clinical applications in body imaging. Outpatient centers accepting these trade-offs lose referral volume for complex cases.
Strategic Opportunities
- Extremity MRI outpatient penetration:Space-constrained private imaging centers in Veneto adopt compact systems for musculoskeletal diagnostics. These installations bypass helium logistics entirely.
- Functional MRI research commercialization:Pre-surgical neural mapping protocols migrate from academic institutes to high-volume neurosurgical centers. University hospital networks monetize research infrastructure.
- Regional health authority outcome contracting:Performance-based procurement models reward diagnostic accuracy metrics. Equipment vendors embed predictive maintenance guarantees to secure multi-year agreements.
Industry Challenges
- Specialized radiologist scarcity:Neuroradiology and oncologic imaging subspecialists concentrate in Milan and Bologna. Southern regions face recruitment gaps that limit scanner utilization rates.
- Legacy PACS integration complexity:New MRI systems must interface with decade-old hospital information architectures. IT standardization delays postpone go-live dates by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Magnetic Resonance Imaging Market |
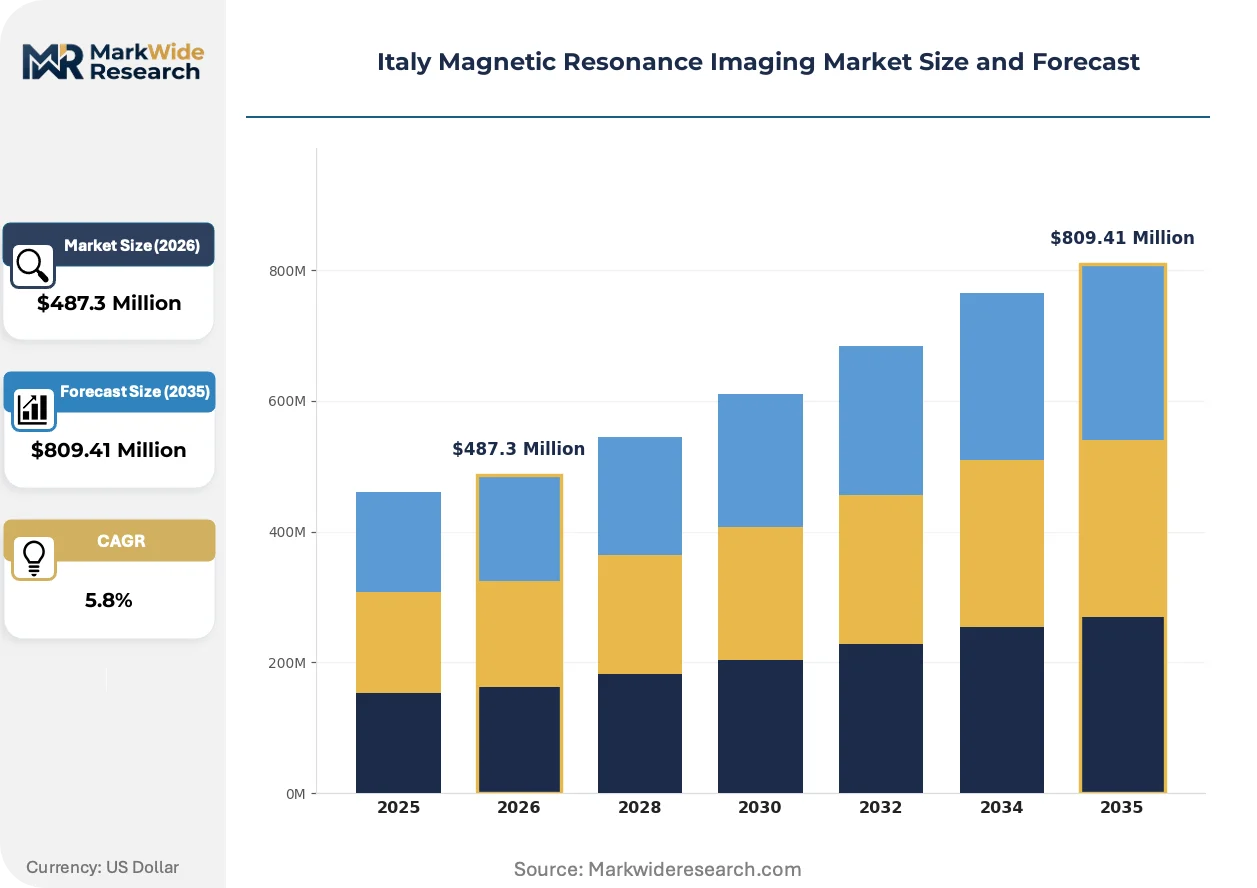
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Imaging Centers, Research Institutes, Laboratories Technology: Superconducting MRI, Permanent Magnet MRI, High-Field MRI, Low-Field MRI Application: Neurology, Orthopedics, Oncology, Cardiovascular |
| Companies Covered | Siemens Healthcare AG, Fujifilm Holdings Corporation, Esaote SpA, Siemens Healthineers, Bruker, GE Healthcare, Canon Medical Systems Corporation, United Imaging, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Magnetic Resonance Imaging Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and zero-helium magnet designs are compressing the traditional hardware-software boundary in Italian radiology. These shifts force vendors to reconfigure service revenue models.
Compressed sensing AI reconstruction is displacing conventional parallel imaging protocols in high-throughput hospital environments. Large university hospitals in Lombardy deploy these algorithms to sustain scan volumes without magnet upgrades. The technology compresses examination times by forty percent while maintaining diagnostic equivalence, forcing equipment vendors to unbundle software subscriptions from hardware sales.
EU Medical Device Regulation post-market surveillance obligations reshape vendor liability structures for MRI manufacturers distributing in Italy. The Italian Medicines Agency enforces vigilance reporting timelines that accelerate field correction cycles. High-field system vendors face disproportionate compliance costs relative to compact extremity specialists, compressing their margin structures on service contracts.
Public hospital consortia consolidate procurement authority across provincial boundaries, displacing individual facility purchasing autonomy. Regional health authorities in Piedmont and Tuscany aggregate MRI fleet decisions into multi-year framework agreements. Equipment vendors respond with dedicated key account structures that bypass traditional distributor relationships in northern industrial corridors.
Italy Magnetic Resonance Imaging Market Segmentation
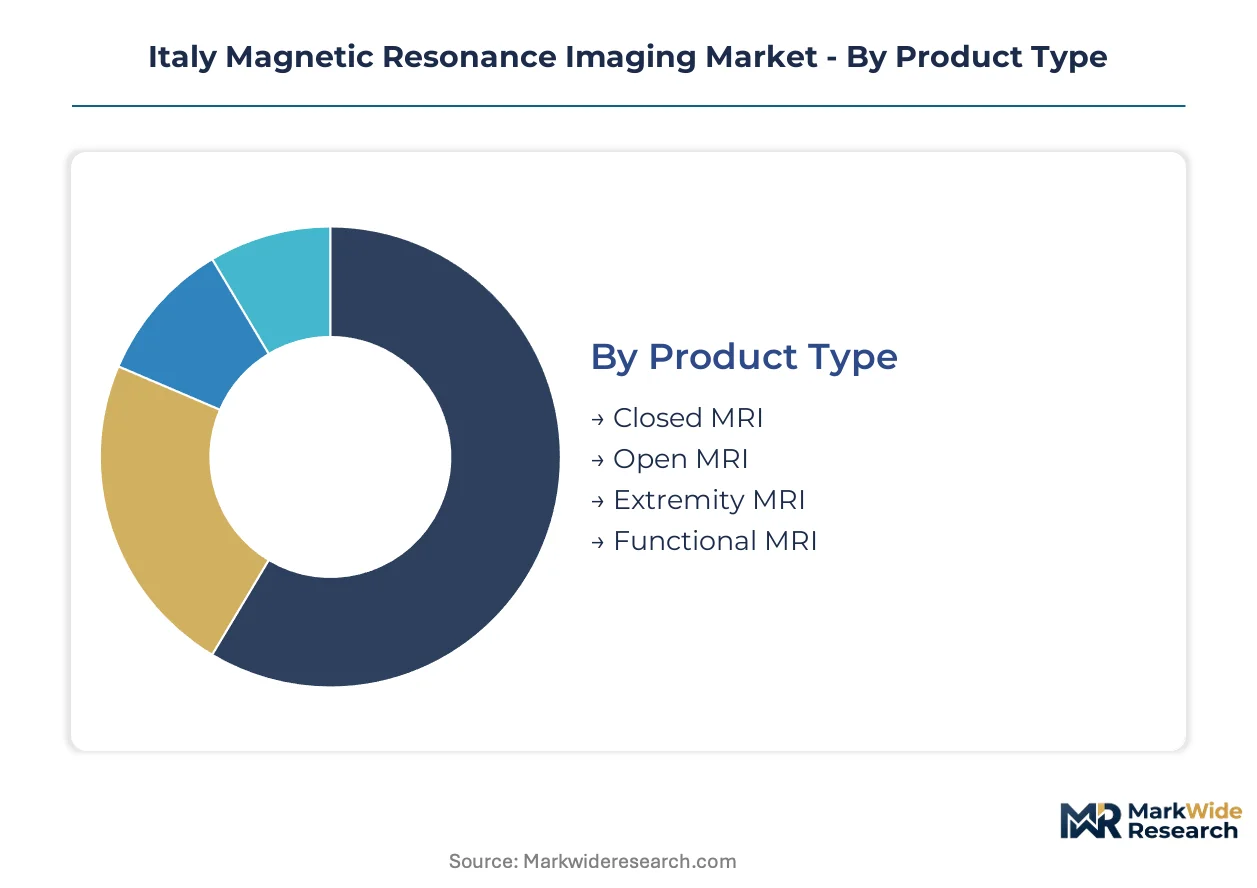
Procurement patterns in Italian radiology diverge sharply across product architectures and clinical settings. CE marking pathways under EU MDR create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
CE marking timelines under EU MDR stretch longest for complex superconducting architectures, compressing margins for high-field system vendors while accelerating compact alternative penetration.
- Closed MRI:Superconducting cylindrical designs dominate hospital procurement for body imaging protocols. Lombardy's university hospital networks concentrate demand here, driven by oncology and neurology caseload expansion requiring superior signal-to-noise ratios.
- Extremity MRI:Compact permanent magnet configurations bypass helium logistics entirely. Private imaging centers in Veneto and space-constrained outpatient facilities adopt these systems for musculoskeletal diagnostics where infrastructure budgets limit conventional magnet deployment.
- Open MRI:Vertical or horizontal gap architectures accommodate claustrophobic patients and bariatric cases. Regional health authorities in Emilia-Romagna specify open configurations for pediatric and geriatric screening programs.
- Functional MRI:Blood-oxygen-level-dependent imaging protocols map neural activation for pre-surgical planning. Research institutes in Milan and Bologna monetize this infrastructure through neurosurgical center partnerships.
Established volume favors Closed MRI; emerging adoption favors Extremity MRI.
End User:
Reimbursement compression from Italy's Ministry of Health reshapes capital allocation across facility types, elongating procurement cycles for public institutions while private operators exploit faster decision pathways.
- Hospitals:Public and private acute care facilities anchor installed base capacity. Radiology departments in northern Italy's industrial corridor expand fleets to handle rising oncology caseloads under essential levels of care mandates.
- Imaging Centers:Standalone diagnostic facilities concentrate in Milan, Turin, and Bologna. These operators prioritize throughput optimization and AI reconstruction algorithms to sustain margins against reimbursement pressure.
- Research Institutes:University hospital networks in Lombardy and Veneto deploy advanced sequences for clinical trial recruitment. Functional MRI commercialization creates hybrid revenue models spanning academic and clinical applications.
- Laboratories:Preclinical imaging facilities support pharmaceutical development pipelines. These installations concentrate near Milan's life sciences cluster, requiring specialized small-bore magnet configurations.
Capital deployment concentrates in Hospitals; margin expansion concentrates in Imaging Centers.
Technology:
Helium supply chain fragility and magnet cooling economics drive technology selection, with superconducting systems carrying operational risk premiums that permanent magnet alternatives exploit.
- Superconducting MRI:Liquid helium-cooled niobium-titanium coils enable 1.5 to 3.0 Tesla field strengths. University hospitals in northern Italy deploy closed-loop cryogenic systems to stabilize operating costs against volatile helium markets.
- High-Field MRI:3.0 Tesla and above configurations deliver enhanced resolution for neurovascular and oncologic protocols. The Italian Medicines Agency's post-market surveillance obligations impose disproportionate compliance costs on these system vendors.
- Permanent Magnet MRI:Ferrite or rare-earth configurations eliminate cryogenic dependencies entirely. Southern Italian imaging centers defer fleet upgrades to these systems as helium price volatility strains superconducting operational budgets.
- Low-Field MRI:Sub-1.0 Tesla designs enable point-of-care deployment with simplified siting requirements. These systems gain traction in emergency stroke units requiring 24/7 availability without specialized infrastructure.
Clinical capability concentrates in Superconducting MRI; deployment flexibility concentrates in Permanent Magnet MRI.
Application:
Regional health authority outcome contracting prioritizes diagnostic accuracy metrics that favor advanced sequence deployment in high-complexity clinical domains.
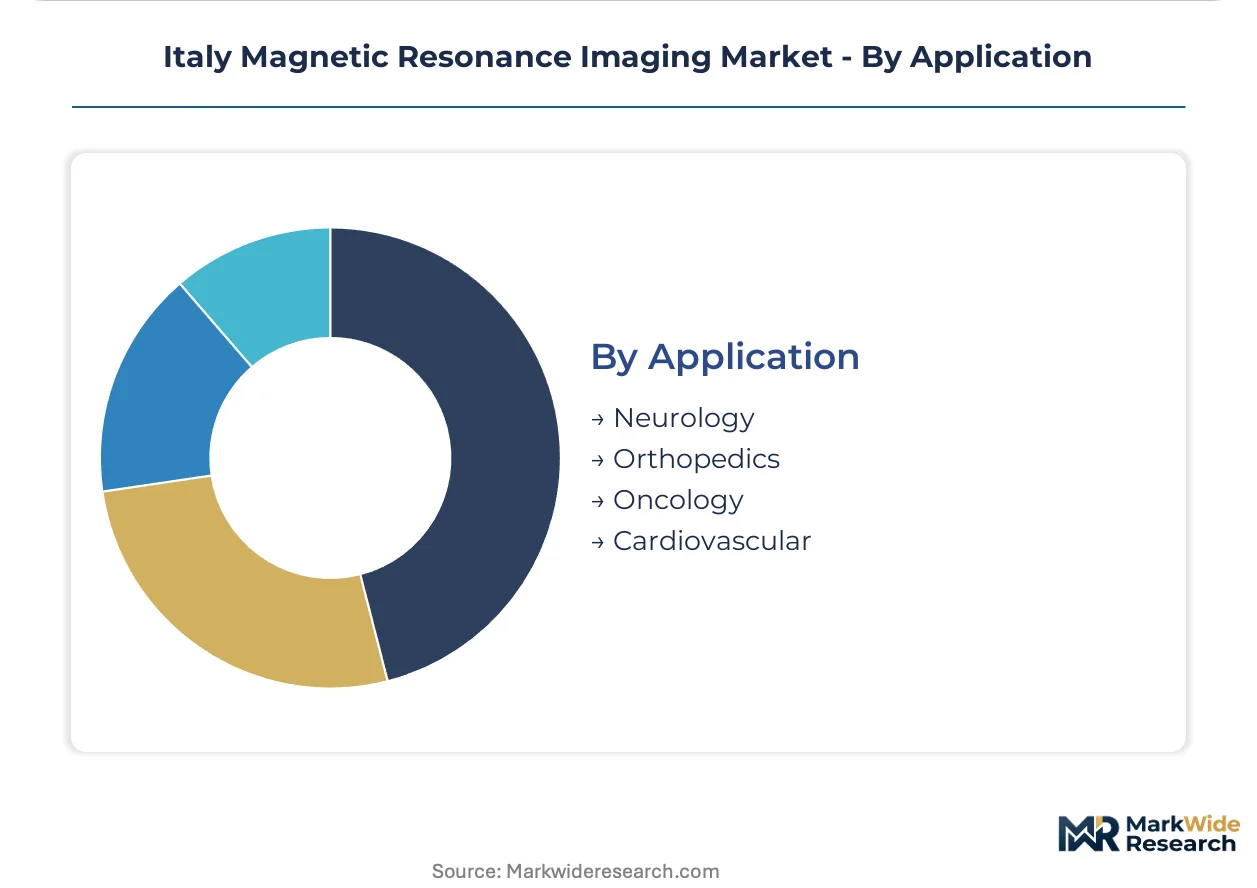
- Oncology:Multiparametric MRI protocols characterize tumor microstructure and treatment response. The Ministry of Health's essential levels of care framework mandates diagnostic imaging access, concentrating procurement in regional cancer networks.
- Neurology:Diffusion-weighted and perfusion imaging protocols support stroke and dementia diagnostics. Northern Italy's aging demographic accelerates demand, with specialized stroke units in Emilia-Romagna requiring continuous scanner availability.
- Orthopedics:Musculoskeletal imaging concentrates in outpatient and sports medicine settings. Extremity MRI penetration displaces conventional closed systems for joint and soft tissue evaluation.
- Cardiovascular:Cardiac MRI remains underutilized relative to CT angiography and echocardiography. Reimbursement thresholds for advanced cardiac sequences lag other applications, constraining fleet expansion.
Reimbursement priority favors Oncology; demographic tailwinds favor Neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's MRI consumption concentrates in northern industrial corridors where university hospital networks drive high-field system deployment, while southern regions rely on compact permanent magnet alternatives constrained by infrastructure budgets and helium supply logistics.
Lombardy
Oncology and neurology caseloads from Milan's regional cancer network and aging demographics fuel demand for 3.0 Tesla superconducting systems. The Ministry of Health's essential levels of care framework mandates diagnostic imaging access, accelerating procurement timelines for public hospitals. Milan's university hospital cluster deploys closed-loop cryogenic systems to stabilize operating costs against volatile helium markets.
Piedmont
Stroke unit expansion across Turin's metropolitan health authority drives 24/7 MRI availability requirements for dementia and neurovascular diagnostics. Regional health authorities aggregate fleet decisions into multi-year framework agreements, displacing individual facility purchasing autonomy. Turin's medical technology corridor hosts specialized service providers supporting high-field system maintenance.
Veneto
Space-constrained private imaging centers prioritize compact extremity MRI systems for musculoskeletal diagnostics, bypassing helium logistics entirely. The Italian Medicines Agency enforces CE marking conformity assessments that accelerate time-to-market for EU-based vendors. Verona and Padua host outpatient networks adopting permanent magnet configurations for joint and soft tissue evaluation.
Emilia-Romagna
Specialized stroke units in Bologna require continuous scanner availability for emergency neuroimaging protocols. Regional health authority outcome contracting rewards diagnostic accuracy metrics, embedding predictive maintenance guarantees in multi-year procurement agreements. Bologna's research institutes commercialize functional MRI infrastructure through neurosurgical center partnerships.
Lazio
Rome's public hospital consortia face elongated procurement cycles as regional health authorities demand outcome documentation before releasing capital budgets. Reimbursement compression for standard imaging sequences strains operational budgets across the metropolitan network. The capital's imaging centers concentrate in the northern periphery where private operators exploit faster decision pathways.
Italy Magnetic Resonance Imaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Italy's MRI market structure. Siemens Healthineers leverages domestic manufacturing footprint advantages while Esaote SpA anchors niche positioning through specialized system designs. Three archetypes dominate: full-stack imaging conglomerates with service network density, compact system specialists exploiting infrastructure constraints, and research-grade vendors monetizing academic partnerships. Competitive moves concentrate on multi-year framework agreements with regional health authorities and predictive maintenance guarantees embedded in outcome-based contracts.
Among German-integrated imaging conglomerates, Siemens Healthcare AG and Siemens Healthineers exemplify the full-stack archetype with manufacturing proximity advantages. Esaote SpA, the Italian specialist, occupies a position within the compact system tier targeting space-constrained outpatient segments. Koninklijke Philips NV and GE Healthcare represent diversified health technology portfolios competing for high-field hospital procurement. Canon Medical Systems Corporation and Fujifilm Holdings Corporation anchor the Asia-Pacific vendor presence navigating CE marking timelines under EU MDR. United Imaging exemplifies emerging vendor archetypes seeking penetration through accelerated regulatory pathways.
| Leading Market Players |
|---|
| Siemens Healthcare AG |
| Fujifilm Holdings Corporation |
| Esaote SpA |
| Siemens Healthineers |
| Bruker |
| GE Healthcare |
| Canon Medical Systems Corporation |
| United Imaging |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
Domestic manufacturing scale at Siemens Healthineers' Forchheim facility compresses delivery cycles and anchors price floors for high-field superconducting systems across Lombardy and Veneto. This concentration of production capacity reinforces vendor pricing power while regional health authority consolidation into multi-year framework agreements shifts negotiation leverage toward volume buyers.
Pricing Analysis
Service contract extensions and predictive maintenance subscriptions generate lifetime value multiples exceeding hardware margins for superconducting MRI vendors. Three-tier pricing structure across premium, standard, and economy levels separates 3.0 Tesla research-grade configurations from 1.5 Tesla clinical workhorses and compact extremity alternatives. Cost compression in the mid-tier clinical segment intensifies because CE marking timelines under EU MDR extend working capital cycles for non-EU vendors. Public hospital consortia in northern Italy exhibit acute price sensitivity due to reimbursement compression from the Ministry of Health, while private imaging centers in Milan's periphery prioritize throughput optimization over capital expenditure minimization.
Supply Chain Analysis
Inventory holding periods for niobium-titanium superconducting coils and liquid helium cryogenic systems stretch operational budgets across quarters, not months. Germany, the United States, and Japan anchor superconducting magnet manufacturing, while China and South Korea concentrate rare-earth permanent magnet production for compact extremity alternatives. Raw material dependencies span helium extraction from Qatar and Algeria, niobium from Brazil, and high-purity copper from Chile. Single-source vulnerability concentrates in liquid helium logistics, where global supply fragility forces Italian university hospitals toward closed-loop recycling infrastructure. Distribution runs through authorized service networks with dedicated field engineering teams rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as regional health authorities in Piedmont and Tuscany aggregate MRI procurement into multi-year framework agreements, displacing individual hospital purchasing autonomy and compressing vendor margins.
For Market Incumbents: Fortify service revenue streams through embedded predictive maintenance guarantees that lock in multi-year relationships with regional cancer networks. Deepen backward integration into helium recycling infrastructure to neutralize supply volatility that threatens 3.0 Tesla system operating costs. The emerging threat of compact permanent magnet alternatives from Esaote SpA and Asian vendors demands response through AI reconstruction software unbundling that sustains high-field value propositions. For New Entrants and Emerging Players: Lead with zero-helium magnet designs targeting southern Italian imaging centers where infrastructure budgets and supply logistics exclude superconducting deployment. The most penetrable white space sits in compact low-field systems for emergency stroke units requiring 24/7 availability without specialized siting. A reimbursement-focused go-to-market angle emphasizing essential levels of care compliance accelerates access to public hospital consortia. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compact system specialists with regulatory fast-track capabilities under EU MDR. Long-term viability over a five-to-ten-year window hinges on software-hardware hybrid models that monetize AI reconstruction algorithms separately from magnet sales. Acquisition targets should demonstrate installed base density in northern Italy's industrial corridor. The signal to watch is regional health authority migration toward outcome-based contracting with diagnostic accuracy metrics embedded in procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR conformity assessment compression enables faster time-to-market for compact system vendors against high-field incumbents. |
| Helium Recycling Infrastructure Deployment | Closed-loop cryogenic systems at university hospitals in Lombardy stabilize operating costs against volatile global helium markets. |
| Hospital System Partnership | Multi-year framework agreements with regional health authorities in Piedmont displace traditional distributor relationships entirely. |
| Software Companion Development | AI reconstruction algorithms unbundled from hardware sales sustain margins against permanent magnet price competition. |
| Reimbursement Strategy | Advanced sequence documentation for oncology protocols secures priority within Ministry of Health essential levels of care mandates. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, regional health authority procurement leads, and GPO contracts managers, then refined through secondary validation. Hospital procurement databases, GPO contract repositories, Italian Medicines Agency vigilance filings, and EU MDR notified body assessment records provided structured data layers. Bottom-up triangulation across installed base estimates and top-down reconciliation against Ministry of Health reimbursement frameworks ensured cross-verification.
Variance decomposition across product architecture, field strength tier, and regional health authority procurement maturity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed magnet technology, clinical application priority, end-user facility type, and geographic infrastructure density. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and capacity expansion announcements. Forecast inputs incorporated helium price volatility scenarios and CE marking timeline distributions under EU MDR.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement stability for advanced MRI sequences or abrupt helium supply disruption would require recalibration. Forecasts reflect documented assumptions regarding regional health authority consolidation trajectories and EU MDR enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Teleradiology Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Japan Mammography Market