
 Polydextrose Market | 2026-2036
Polydextrose Market Size, Share, and Industry Trends Forecast 2026-2036
Polydextrose Market Intelligence
EU F-Gas Regulation is repositioning the cost-of-entry calculus for polydextrose manufacturers targeting European processed food channels. Tate & Lyle PLC leverages its UK-based specialty carbohydrate infrastructure to sustain formulation partnerships across continental bakery and dairy applications. Cargill Incorporated anchors North American supply through its corn-derived ingredient platform, while Roquette Frères competes from its European pea and starch processing base with differentiated plant-origin positioning.
Polydextrose is a randomly bonded condensation polymer of glucose, containing minor amounts of sorbitol and citric acid, with a molecular weight averaging approximately 22,000 and digestible energy of one kilocalorie per gram, functioning primarily as a low-calorie bulking agent and soluble dietary fiber in reduced-sugar and reduced-fat food systems. Powder formulations dominate current volume given superior shelf stability and ease of dry blending in commercial bakery and confectionery operations, though liquid and syrup variants are capturing share in beverage applications where pumpable dosing and homogeneous dispersion prove critical. The bulking agent functionality commands the deepest margin pool as it underpins sugar replacement architectures in reformulated confectionery and frozen dairy desserts, while stabilizer applications in reduced-fat spreads represent a maturing but still expanding use case.
FDA dietary fiber guidance, EFSA health claim frameworks, and China's GB standards for food additives collectively shape polydextrose qualification pathways, with each jurisdiction imposing distinct analytical thresholds for molecular weight distribution and monomer content that determine label eligibility and permitted health statements. Manufacturers must monitor evolving prebiotic classification debates across these regulatory theaters, as fiber definition rulings directly determine which end-product categories qualify for reduced-sugar or digestive health positioning. Stakeholders should track how harmonization pressures between FDA and EFSA methodologies reshape formulation investment priorities and regional production allocation decisions.
Market Dynamics
Clean-label reformulation mandates across processed food categories are compressing the acceptable ingredient list, forcing polydextrose suppliers to validate fiber claims through evolving analytical protocols while maintaining functional equivalence in reduced-sugar applications.
Growth Catalysts
- China's GB standards alignment:Domestic nutraceutical brands are accelerating polydextrose inclusion to meet digestive health positioning requirements under updated food additive classifications.
- Beverage pumpable dosing:Liquid syrup variants are capturing share in functional drink formulations where homogeneous dispersion and processing line compatibility prove critical.
- FDA dietary fiber definition:The updated qualification framework is repositioning ingredient eligibility standards, expanding addressable categories for fiber-fortified products.
Market Restraints
- Corn feedstock concentration:North American supply chains remain anchored to maize-derived glucose, exposing margin structures to agricultural commodity volatility and weather-driven input cost swings.
- EFSA health claim friction:Divergent analytical thresholds for molecular weight distribution between European and US regulators create compliance duplication costs for multinational formulations.
- Allulose substitution pressure:Emerging low-calorie bulk sweeteners with simpler regulatory pathways are contesting sugar-replacement architectures in confectionery and frozen dessert segments.
Strategic Opportunities
- Pea-origin positioning:European plant-protein processing infrastructure enables differentiated polydextrose sourcing narratives targeting clean-label bakery and dairy channels.
- Prebiotic classification tailwind:Evolving gut microbiome research frameworks across FDA and EFSA jurisdictions may expand permitted health statements beyond basic fiber claims.
- Direct-to-manufacturer digital channels:Specialty ingredient platforms are disintermediating traditional distribution, enabling formulation partnerships with mid-scale functional food startups.
Industry Challenges
- Analytical chemistry talent scarcity:Molecular weight distribution validation and monomer content quantification require specialized expertise that outpaces current technical training pipelines.
- Legacy system integration:Dry blending equipment in commercial bakery operations requires retrofit compatibility testing for powder polydextrose variants with modified particle size distributions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polydextrose Market |
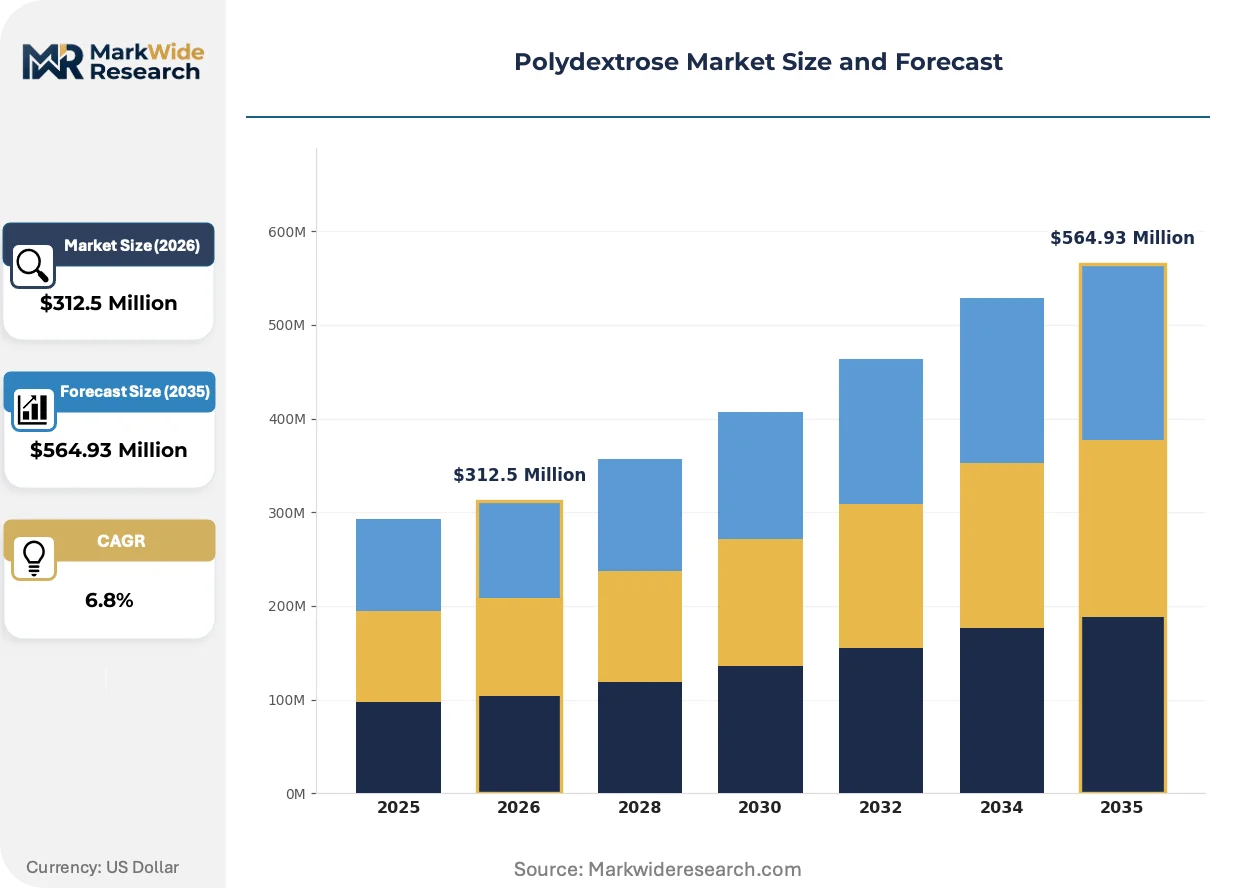
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Syrup Application: Beverages, Dairy Products, Confectionery, Bakery End User: Food Manufacturers, Pharmaceutical Companies, Nutraceuticals, Dietary Supplements Functionality: Stabilizer, Texturizer, Sweetener, Bulking Agent |
| Companies Covered | Tate & Lyle PLC, Cargill Incorporated, DuPont de Nemours Inc., Ingredion Incorporated, Baolingbao Biology Co. Ltd., Samyang Corporation, Shandong Bailong Chuangyuan Bio-Tech Co. Ltd., Roquette Frères, CJ CheilJedang Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polydextrose Market Strategic Shifts & Innovations
Reformulation science is converging with regulatory analytics, creating new technical requirements for ingredient suppliers who must now prove functional fiber equivalence while navigating divergent jurisdictional definitions.
Encapsulation technology is unifying stability and release-profile control in polydextrose delivery systems. Confectionery manufacturers are adopting microencapsulated variants to manage hygroscopicity in reduced-sugar chocolate applications. This convergence is compressing the traditional trade-off between shelf-life extension and processing line efficiency.
REACH substance evaluation protocols are tightening purity documentation requirements for imported food additives entering European processed food channels. Manufacturers must now submit expanded analytical datasets covering residual citric acid and sorbitol content thresholds. Bakery and dairy formulators are responding by qualifying dual-source supply arrangements to mitigate documentation timeline risks.
Brand procurement teams are consolidating supplier relationships around vertically integrated carbohydrate specialists capable of delivering integrated fiber-sweetener-bulking systems. This concentration is displacing discrete ingredient sourcing in large-scale confectionery operations. The shift is most visible in North American frozen dessert manufacturing, where single-supplier accountability for reformulation outcomes is becoming a contractual standard.
Polydextrose Market Segmentation
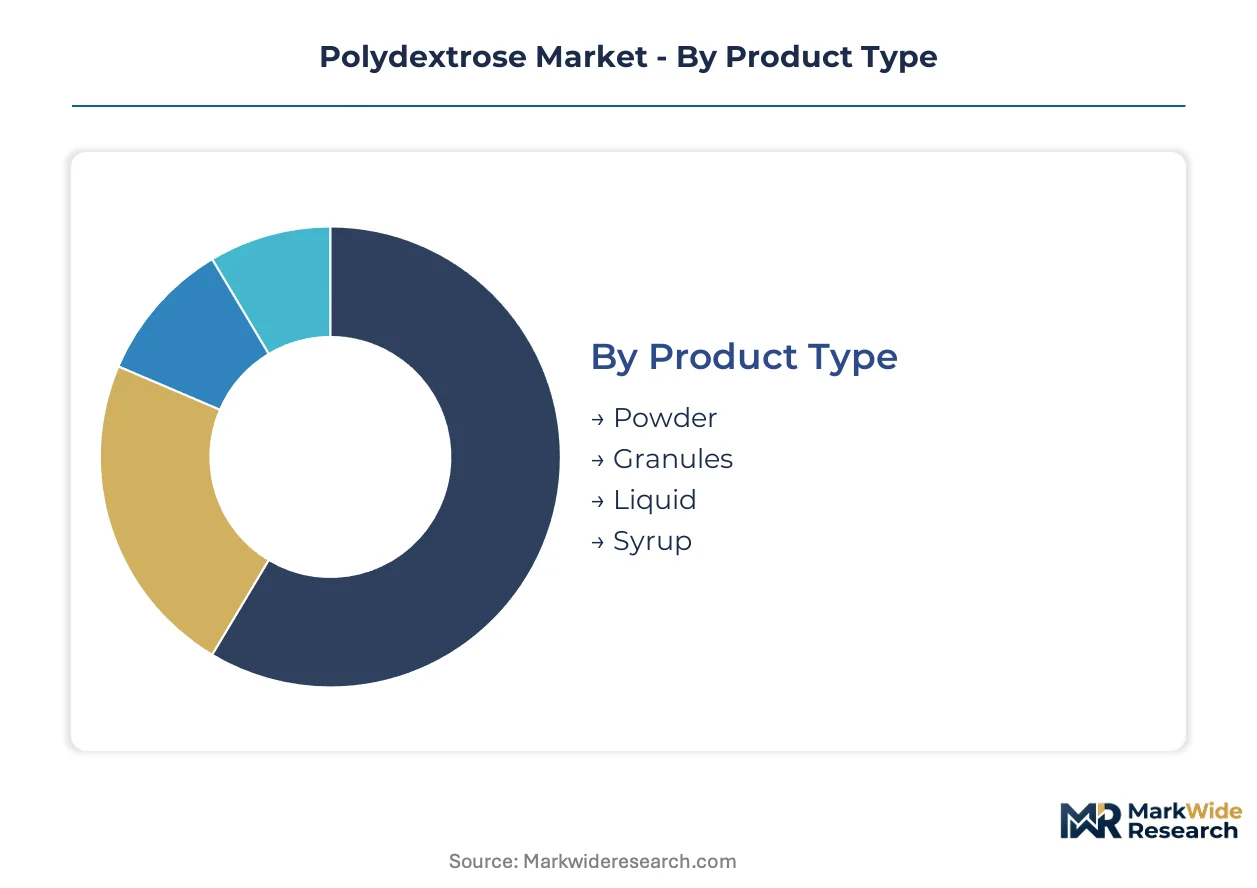
Polydextrose suppliers must align molecular specifications with distinct processing requirements across food, pharmaceutical, and nutraceutical channels. Each segment imposes unique constraints on particle size distribution, solubility profiles, and regulatory documentation burdens.
Product Type:
Buyers differentiate primarily by handling characteristics and integration complexity with existing production lines.
- Powder:Fine particulate formulations averaging 80-200 mesh deliver superior shelf stability and compatibility with commercial dry blending systems. Bakery and confectionery operations in China and the United States concentrate procurement here due to established handling infrastructure and GB standards alignment for fiber content claims.
- Liquid:Pumpable aqueous solutions enable homogeneous dispersion in high-speed beverage filling lines without hydration delays. Functional drink manufacturers in Germany and Japan favor this format for reduced cleaning cycle frequency and metered dosing precision.
- Granules:Agglomerated particles reduce dusting during pneumatic transfer in large-scale dairy powder operations. Spray-dried variants from European pea-starch processing facilities serve reduced-fat spread applications requiring controlled dissolution kinetics.
- Syrup:Viscous concentrated solutions bind water in frozen dessert matrices while maintaining freeze-thaw stability. North American frozen dairy manufacturers specify this grade for sugar replacement architectures in clean-label reformulations.
Powder leads volumes today; liquid is gaining share fastest in beverage channel expansion.
Application:
End-use concentration follows regional dietary habits and regulatory tolerance for reduced-sugar positioning claims.
- Confectionery:Chocolate and hard candy applications exploit polydextrose's one kilocalorie per gram energy density to achieve sugar reduction targets without volume loss. EFSA health claim frameworks and FDA dietary fiber definitions determine permissible digestive health statements on European and US packaging.
- Beverages:RTD functional drinks and meal replacement shakes incorporate liquid variants for viscosity modulation and prebiotic fiber delivery. China's nutraceutical corridor drives formulation innovation as domestic brands pursue GB standards compliance for digestive health positioning.
- Dairy Products:Reduced-fat yogurts and ice creams employ polydextrose as a fat mimetic to restore mouthfeel in reformulated systems. German and French dairy processors prioritize REACH-compliant documentation for imported additive qualifications.
- Bakery:Bread and pastry applications leverage water-binding capacity to extend shelf life in reduced-sugar formulations. US commercial bakeries retrofit dry blending equipment to accommodate modified particle size distributions from specialty carbohydrate suppliers.
Confectionery anchors current revenue; beverages show steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between established food manufacturers and emerging nutraceutical startups.
- Food Manufacturers:Large-scale bakery, dairy, and confectionery operations demand integrated fiber-sweetener-bulking systems from vertically integrated suppliers with validated analytical protocols for molecular weight distribution.
- Nutraceuticals:Chinese domestic brands accelerate polydextrose inclusion to meet reformulated digestive health positioning under updated food additive classifications and GB standards.
- Dietary Supplements:Capsule and powder blenders prioritize USP-grade material with expanded residual citric acid and sorbitol documentation for FDA inspection readiness.
- Pharmaceutical Companies:Excipient applications require batch-specific certificates of analysis covering monomer content thresholds and microbial specifications for tablet and suspension formulations.
Food manufacturers dominate procurement scale; nutraceuticals demonstrate the most rapid demand acceleration.
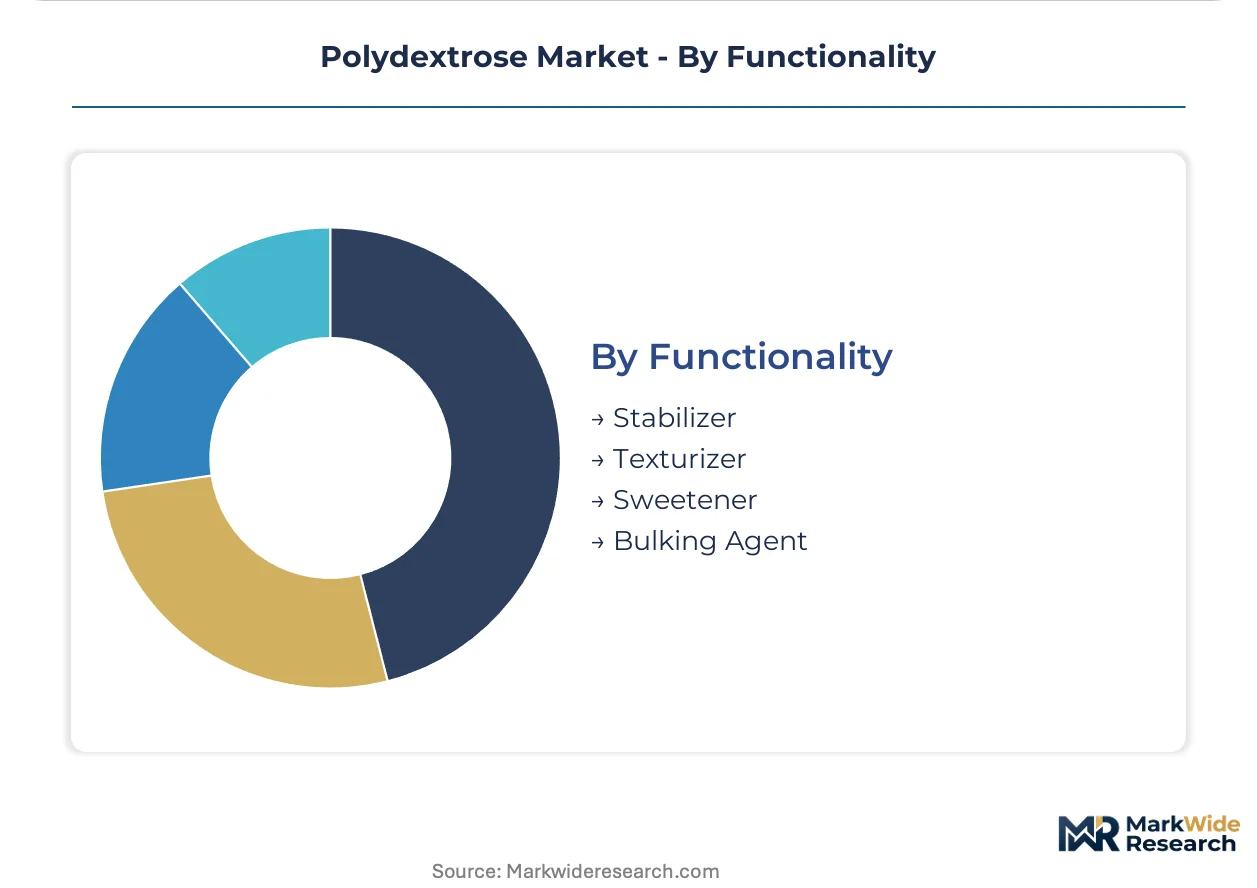
Functionality:
Margin structures diverge based on technical substitution difficulty and formulation system criticality.
- Bulking Agent:Sugar replacement architectures in confectionery and frozen desserts command premium positioning due to irreplaceable volume maintenance in reduced-calorie systems. The functionality underpins reformulation partnerships between Tate & Lyle and continental European bakery operations.
- Stabilizer:Reduced-fat spreads and dressings rely on polydextrose to prevent syneresis and maintain emulsion integrity during temperature cycling. Applications mature but expand with clean-label mandates compressing synthetic stabilizer acceptance.
- Sweetener:Modest sweetness contribution (approximately ten percent of sucrose intensity) supports partial sugar reduction without complete taste profile reconstruction. Cargill's corn-derived platform serves North American clients seeking simplified label declarations.
- Texturizer:Viscosity building and mouthfeel modification in beverage and dairy systems compete with alternative hydrocolloids on cost-performance matrices.
Bulking agent commands the deepest margin pool; stabilizer applications mature with steady volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized carbohydrate chemists and food formulation scientists cluster in industrial corridors where regulatory expertise intersects with processing infrastructure. Their concentration shapes where polydextrose suppliers anchor technical service capabilities and analytical validation laboratories.
United States
FDA dietary fiber definition updates are expanding qualification pathways for fiber-fortified products across bakery and confectionery channels. Commercial bakeries in the Midwest retrofit dry blending equipment to accommodate modified particle size distributions from corn-derived ingredient platforms. Chicago and Minneapolis-St. Paul anchor North American procurement scale for reduced-sugar frozen dessert reformulations.
Germany
REACH substance evaluation protocols are tightening purity documentation requirements for imported food additives entering European processed food channels. EFSA health claim frameworks determine permissible digestive health statements on packaging across reduced-fat dairy applications. The Rhine-Ruhr corridor concentrates formulation partnerships between specialty carbohydrate suppliers and continental bakery operations.
China
Domestic nutraceutical brands accelerate polydextrose inclusion to meet reformulated digestive health positioning under updated GB standards for food additives. SAMR oversight of food additive classifications is repositioning ingredient eligibility for fiber content claims. The Yangtze River Delta anchors manufacturing scale for functional drink formulations incorporating liquid syrup variants.
Japan
Functional drink manufacturers favor liquid polydextrose formats for reduced cleaning cycle frequency and metered dosing precision in high-speed beverage filling lines. METI industrial standards shape quality specifications for prebiotic fiber ingredients in meal replacement shake applications. The Kanto region around Tokyo concentrates demand from aging-population targeted digestive health products.
France
Reduced-fat spread applications rely on polydextrose to prevent syneresis and maintain emulsion integrity during temperature cycling. EFSA analytical thresholds for molecular weight distribution create compliance benchmarks distinct from FDA methodologies. The Hauts-de-France region anchors pea-starch processing infrastructure enabling differentiated plant-origin sourcing narratives.
Polydextrose Market Key Industry Players
The competitive structure tilts toward vertically integrated carbohydrate specialists with captive analytical chemistry capabilities. Three to four multinational ingredient platforms dominate procurement relationships with large-scale food manufacturers, while regional specialists compete on plant-origin positioning and regulatory documentation speed. Two strategic archetypes prevail: corn-derived supply chain anchors and pea-starch processing diversifiers. Capacity expansion in liquid syrup formats and backward integration into glucose feedstock production represent the dominant competitive moves.
Among UK-based specialty carbohydrate platforms, Tate & Lyle PLC exemplifies the integrated fiber-sweetener-bulking system supplier archetype. Cargill Incorporated occupies a position representing North American corn-derived supply chain concentration. Roquette Frères sits within the European plant-origin positioning tier, leveraging pea and starch processing infrastructure. These three anchors illustrate how geographic feedstock advantages and regulatory proximity shape competitive differentiation in qualification-intensive markets.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| Ingredion Incorporated |
| Baolingbao Biology Co. Ltd. |
| Samyang Corporation |
| Shandong Bailong Chuangyuan Bio-Tech Co. Ltd. |
| Roquette Frères |
| CJ CheilJedang Corp. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between pharmaceutical-grade and food-grade polydextrose manifests in divergent pricing architectures and supply chain configurations. Pharmaceutical-grade material commands substantial premia due to batch-specific analytical documentation and microbial specification testing, while food-grade supply chains optimize for volume throughput and GB standards alignment in China's nutraceutical corridor.
Pricing Analysis
Bundled analytical services versus unbundled commodity supply splits the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and molecular weight distribution validation rigor. Price differentiation stems from REACH documentation completeness and FDA dietary fiber qualification status. Pricing pressure stems from allulose substitution in confectionery sugar-replacement architectures. Mid-scale functional food startups exhibit highest price sensitivity; pharmaceutical excipient buyers demonstrate lowest elasticity due to regulatory switching costs.
Supply Chain Analysis
Freight cost escalation from European pea-starch processing hubs to North American dairy manufacturers reshapes regional procurement patterns. Supply concentrates in the United States, China, and France, with corn-derived glucose feedstock anchoring North American production and European plant-protein infrastructure enabling differentiated sourcing narratives. Raw material dependencies include glucose syrup, sorbitol, and citric acid monomer inputs. Single-source vulnerability concentrates in analytical chemistry talent pools for molecular weight validation. Distribution runs through vertically integrated carbohydrate specialists with captive technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as clean-label mandates compress acceptable ingredient lists and elevate fiber-claim validation requirements. Demand is shifting toward premium specifications with expanded residual content documentation and prebiotic classification readiness.
For Market Incumbents: Anchor defensive positioning through backward integration into glucose feedstock production and capacity expansion in liquid syrup formats. Tate & Lyle PLC exemplifies consolidation through integrated fiber-sweetener-bulking system supply. Threat from allulose substitution in frozen dessert segments necessitates prebiotic classification investment to expand permitted health statements beyond basic fiber claims.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital channels targeting mid-scale functional food startups in China's Yangtze River Delta nutraceutical corridor. White-space opportunities concentrate in beverage pumpable dosing applications and encapsulated variants for reduced-sugar chocolate. Pea-origin positioning from European processing infrastructure offers differentiated clean-label narratives against corn-derived incumbents.
For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemistry talent scarcity intersects with REACH documentation timeline risks for imported additives. Long-term viability favors vertically integrated platforms with captive validation laboratories and multi-jurisdictional regulatory expertise. Acquisition target archetype: regional specialists with plant-origin positioning and accelerated GB standards compliance capabilities. Signal to watch: harmonization progress between FDA and EFSA molecular weight methodologies reshaping formulation investment priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Corn-derived supply anchors North American margin structures against agricultural commodity volatility. |
| Prebiotic Classification Investment | Expanded health statements beyond fiber claims differentiate against allulose substitution pressure. |
| Liquid Syrup Capacity Expansion | Pumpable dosing formats capture beverage channel growth in Germany and Japan functional drink markets. |
| Encapsulation Technology Adoption | Microencapsulated variants manage hygroscopicity in reduced-sugar chocolate shelf-life extension. |
| Direct-to-Manufacturer Digital Channels | Specialty ingredient platforms disintermediate traditional distribution for mid-scale startup partnerships. |
Research Approach
Coverage spans the United States, Germany, China, Japan, and France, with primary inputs from each jurisdiction's regulatory and manufacturing clusters. The analysis combines structured interviews with formulation scientists at Tate & Lyle PLC and Cargill Incorporated, procurement leads at continental European bakery operations, regulatory affairs specialists navigating REACH protocols, and technical directors at Chinese nutraceutical brands. Secondary validation draws from FDA dietary fiber guidance documents, EFSA health claim framework updates, SAMR GB standards publications, METI industrial standards, and SEC filings from publicly traded ingredient platforms. Bottom-up volume modeling triangulates against top-down market sizing from trade flow analysis.
Granularity-level modeling extends to product type specifications across powder, liquid, granule, and syrup formats; application segmentation covering confectionery, beverages, dairy, and bakery channels; functionality differentiation between bulking agent, stabilizer, sweetener, and texturizer roles; and end-user procurement sophistication tiers from multinational food manufacturers to emerging nutraceutical startups. CAGRs derive from regression analysis against historical pricing trajectories and projected reformulation cycle frequencies. Industry-specific forecast inputs include prebiotic classification timeline assumptions and EFSA-FDA harmonization progress indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory reclassification scenarios or feedstock price shocks from agricultural commodity volatility. Forecasts reflect documented assumptions regarding clean-label mandate adoption rates and analytical chemistry talent pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
China Food Hydrocolloids Market