
 Asia Pacific Food Grade Carbon Dioxide Market | 2026-2036
Asia Pacific Food Grade Carbon Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Food Grade Carbon Dioxide Market Analytics
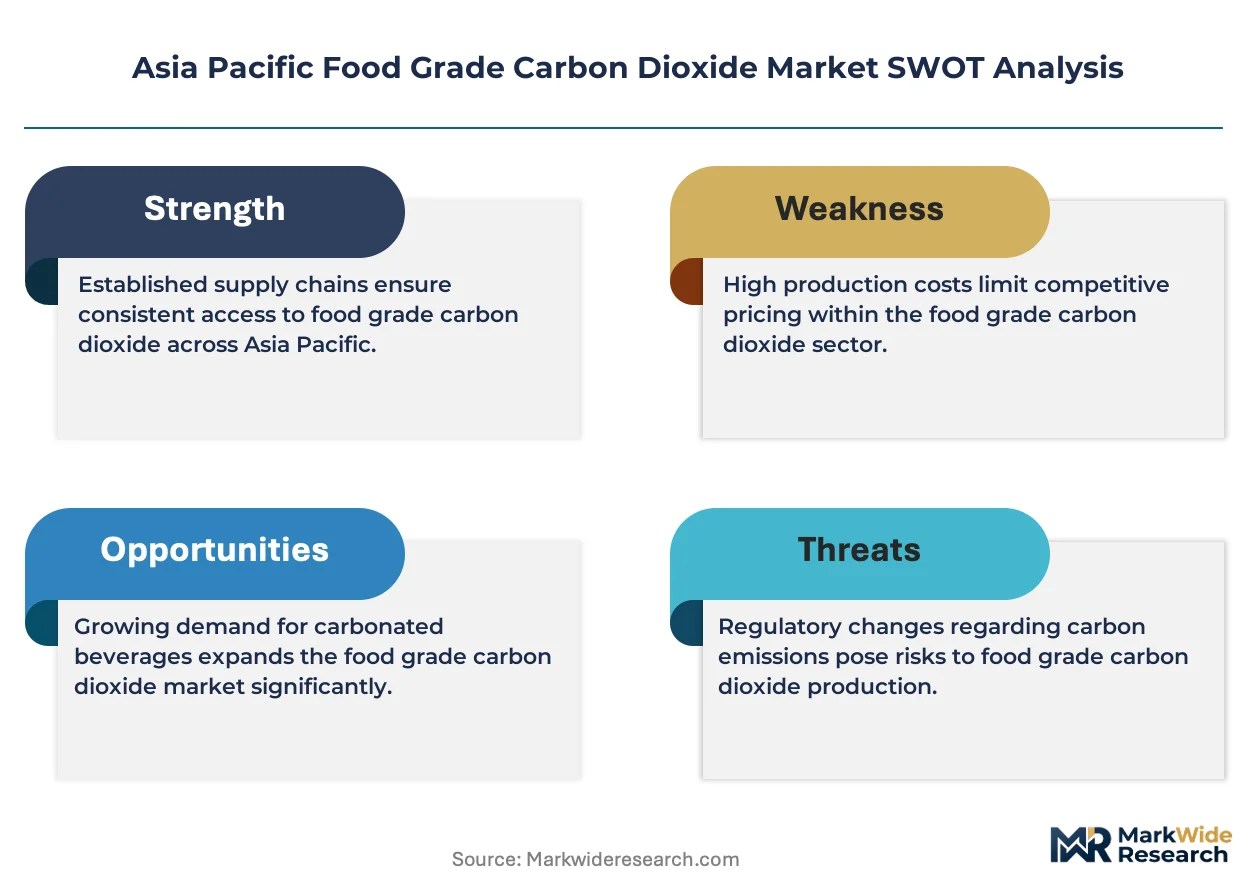
ISO 22000 certification is rotating as the primary gatekeeper for supplier qualification across the Asia Pacific Food Grade Carbon Dioxide Market. Air Liquide leverages its integrated production network to sustain supply security for beverage clients in ASEAN markets. Linde plc anchors its position through cryogenic distribution infrastructure that spans Australian dairy and Japanese meat processing corridors. TAIYO NIPPON SANSO CORPORATION differentiates via ultra-high-purity capture technologies tailored to pharmaceutical-adjacent food applications.
Food grade carbon dioxide designates carbon dioxide refined to meet food safety purity thresholds, typically requiring elimination of aromatic hydrocarbons, sulfur compounds, and moisture to below specified parts-per-million levels for direct contact with consumables. The gas functions primarily as a processing aid for carbonation, inert atmosphere packaging, and temperature-controlled transport of perishables. Beverage applications dominate volume throughput across the region, while food preservation segments command margin premiums due to cryogenic handling requirements and shorter distribution cycles. Liquid product form leads infrastructure-heavy deployments, whereas solid dry ice formats are gaining traction in last-mile cold chain segments where direct sales channels bypass wholesale intermediaries.
India's FSSAI mandates periodic purity auditing for CO2 deployed in food contact, while China's SAMR enforces GB 1886.228 standards on additive-grade gas composition. Japan's METI coordinates with JIS frameworks to align industrial gas specifications with export-oriented food manufacturer requirements. Stakeholders must monitor divergence between national purity thresholds and the harmonization pressure from ASEAN-wide food safety protocols that could reshape cross-border supplier eligibility.
Market Dynamics
ASEAN beverage manufacturing clusters are consolidating procurement around ISO 22000-certified suppliers as carbonation volumes surge and cold chain integrity becomes non-negotiable for export qualification.
Growth Catalysts
- GB 1886.228 enforcement:China's SAMR purity mandates are disqualifying unqualified CO2 sources and redirecting volume toward certified industrial gas networks.
- Dairy processing expansion:Australian and New Zealand exporters are scaling cryogenic chilling infrastructure to meet shelf-life requirements for Southeast Asian retail channels.
- Packaged beverage consumption:Urban demand for carbonated soft drinks and ready-to-drink coffee in Indonesia, Vietnam, and the Philippines is pulling liquid CO2 throughput through dedicated distribution corridors.
Market Restraints
- Feedstock concentration:Ammonia and ethanol plant off-gas remains the dominant CO2 source, tying supply security to fertilizer and biofuel production cycles in China and India.
- Cryogenic infrastructure capex:Liquid storage and transport assets require specialized tankage that locks capital for 15-20 year depreciation cycles.
- Direct air capture economics:Emerging purification technologies face cost disadvantages against established industrial off-gas recovery, limiting alternative supply development.
Strategic Opportunities
- Last-mile dry ice channels:E-commerce fresh food platforms in India and Southeast Asia are bypassing wholesale intermediaries through direct-to-restaurant solid CO2 distribution.
- Pharmaceutical-adjacent food:Ultra-high-purity capture systems originally developed for vaccine cold chains are transferring specifications to premium frozen food export segments.
- ASEAN harmonization protocols:Cross-border food safety frameworks under development could streamline supplier eligibility across Indonesia, Thailand, Vietnam, and Malaysia simultaneously.
Industry Challenges
- Auditor capacity constraints:FSSAI-mandated purity verification in India faces bottlenecks as certified laboratory capacity lags behind the number of CO2 installations requiring periodic assessment.
- Legacy equipment retrofit costs:Existing beverage carbonation lines in older Chinese manufacturing zones require stainless steel upgrades to meet evolving moisture and hydrocarbon thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Food Grade Carbon Dioxide Market |
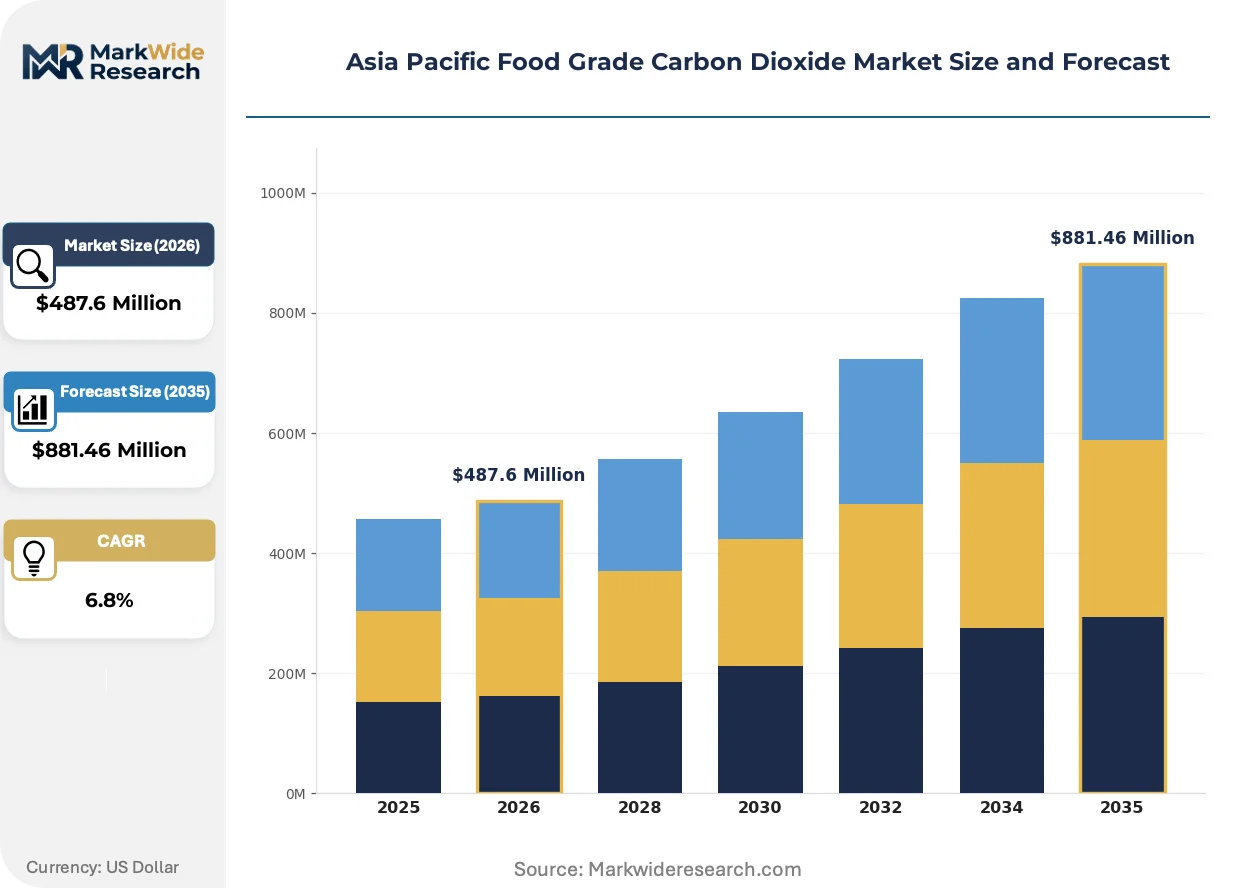
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Beverages, Food Preservation, Bakery, Meat Processing Product Form: Liquid, Gas, Solid, Carbonated Distribution Channel: Wholesale, Retail, Direct Sales, Online End User: Food Manufacturers, Beverage Companies, Restaurants, Catering Services |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Inc., TAIYO NIPPON SANSO CORPORATION, Messer Group, Sicgil India Limited, Coregas, Ellenbarrie Industrial Gases, WKS Industrial Gas Pte Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Food Grade Carbon Dioxide Market Evolving Landscape
Capture technology diversification and distribution model compression are redrawing competitive boundaries as beverage manufacturers seek supply security beyond traditional industrial off-gas dependencies.
Membrane separation systems for CO2 purification from biogas and fermentation streams are fragmenting the conventional ammonia-plant supply base. Craft breweries and ethanol distilleries in Thailand and Australia are installing on-site capture units to supply adjacent food processors. This distributed production model is compressing the geographic radius between CO2 generation and carbonation endpoints, reducing transport cost exposure for regional bottlers.
Japan's METI has aligned JIS K 1106 industrial gas standards with export-oriented food manufacturer requirements, creating unified specifications that simplify cross-border supplier qualification. This regulatory convergence reduces testing redundancy for CO2 moving between Japanese processing facilities and ASEAN packaging operations. Dairy and meat exporters are the primary beneficiaries as they consolidate multi-country supplier panels.
Direct sourcing contracts between beverage manufacturers and industrial gas producers are displacing traditional merchant distributor relationships in high-volume corridors. Major bottlers in China and India are negotiating dedicated offtake agreements with ammonia plant operators and ethanol refiners. This channel compression is most visible in carbonated soft drink manufacturing zones surrounding Shanghai, Guangzhou, Mumbai, and Delhi where annual CO2 consumption exceeds 10,000 tonnes per facility.
Asia Pacific Food Grade Carbon Dioxide Market Segmentation
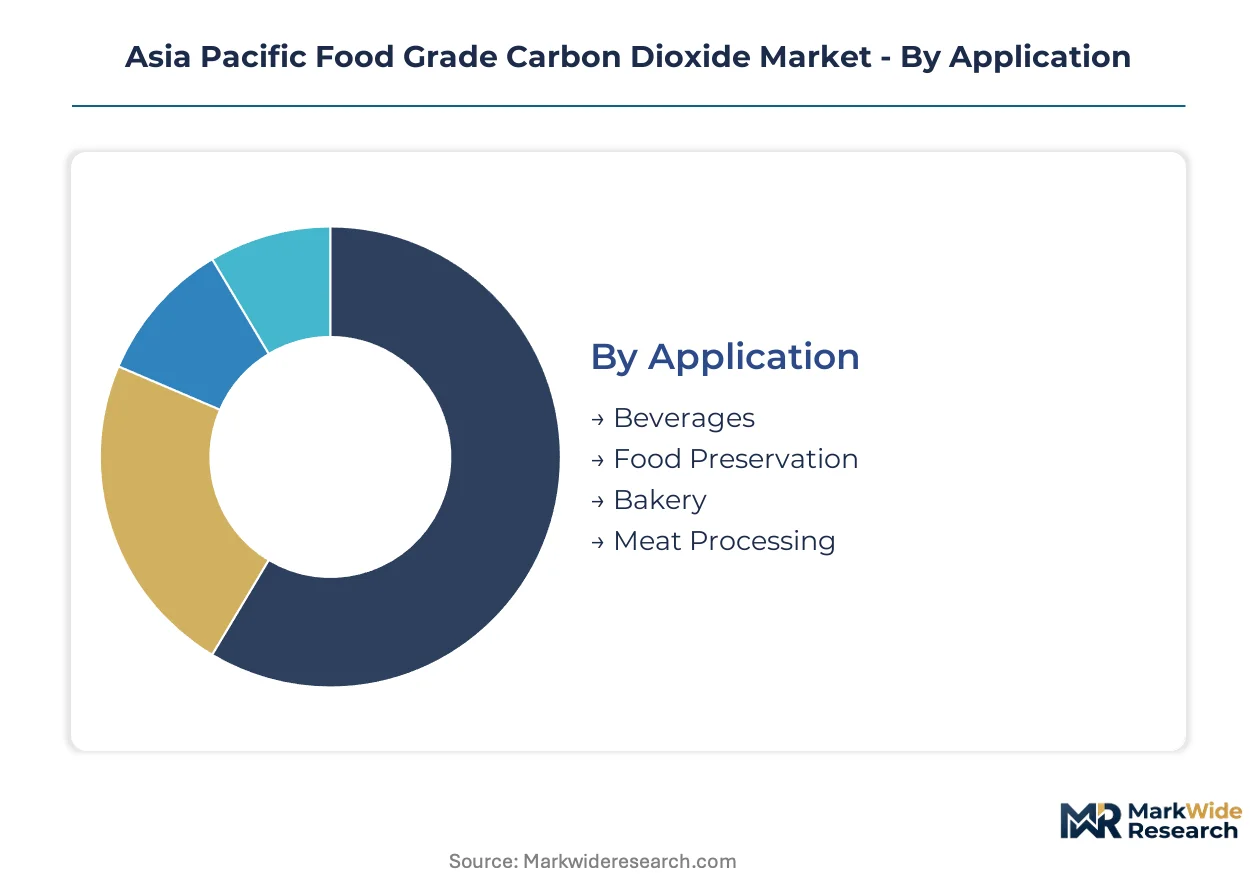
Segmentation in the Asia Pacific Food Grade Carbon Dioxide Market reveals how purity specifications, physical state requirements, and channel economics fragment procurement strategies across beverage carbonation, cold chain logistics, and food processing corridors.
Application:
Margin pools concentrate heaviest in cryogenic food preservation where pharmaceutical-grade cold chain specifications command premium pricing over standard beverage carbonation volumes.
- Beverages:Carbonation of soft drinks, ready-to-drink coffee, and alcoholic beverages dominates volume throughput. Demand clusters in Indonesian, Vietnamese, and Philippine manufacturing zones where urban consumption of packaged drinks is climbing fastest.
- Food Preservation:Cryogenic chilling and modified atmosphere packaging for perishables generates the highest unit economics. Australian and New Zealand dairy exporters deploy liquid CO2 systems to meet shelf-life thresholds for Southeast Asian retail channels.
- Bakery:Controlled atmosphere applications for dough conditioning and product shelf-life extension. Japanese and South Korean industrial bakeries represent concentrated demand pockets.
- Meat Processing:Blast freezing and transport chilling for poultry, seafood, and red meat supply chains. Thai and Vietnamese processing facilities are scaling cryogenic infrastructure for export qualification.
The dominant share belongs to Beverages, while Food Preservation is closing the gap fastest.
Product Form:
Physical state selection hinges on transport distance and handling infrastructure maturity across the region's fragmented cold chain networks.
- Liquid:Bulk tanker deliveries to high-volume manufacturing facilities with dedicated storage infrastructure. China's SAMR-enforced GB 1886.228 standards are redirecting procurement toward certified liquid supply networks.
- Solid:Dry ice blocks and pellets for last-mile cold chain segments. Indian e-commerce fresh food platforms are bypassing wholesale intermediaries through direct-to-restaurant solid CO2 distribution.
- Gas:Cylinder supply for small-scale food processors and remote manufacturing locations. Southeast Asian island economies rely heavily on compressed gas logistics.
- Carbonated:Pre-carbonated water and syrup solutions for specific beverage manufacturing workflows. Limited to specialized bottling configurations in Japan and Australia.
Liquid form retains the volume lead, though Solid is expanding most quickly in direct-to-customer channels.
Distribution Channel:
Channel structure reflects the tension between capital-intensive bulk infrastructure and emerging platform-based procurement models.
- Wholesale:Traditional merchant gas distributors with regional tanker fleets and depots. Established networks in China and India still handle the majority of beverage carbonation volumes.
- Direct Sales:Long-term offtake contracts between industrial gas producers and major bottlers. Shanghai and Delhi manufacturing corridors show the highest concentration of direct procurement relationships.
- Retail:Cylinder exchange programs and small-lot deliveries to independent food processors. Fragmented across Southeast Asian secondary cities.
- Online:Digital platforms connecting dry ice suppliers with restaurants and catering operators. Emerging fastest in Indian metropolitan markets.
Wholesale channels maintain the largest share, while Direct Sales is gaining share fastest among high-volume beverage manufacturers.
End User:
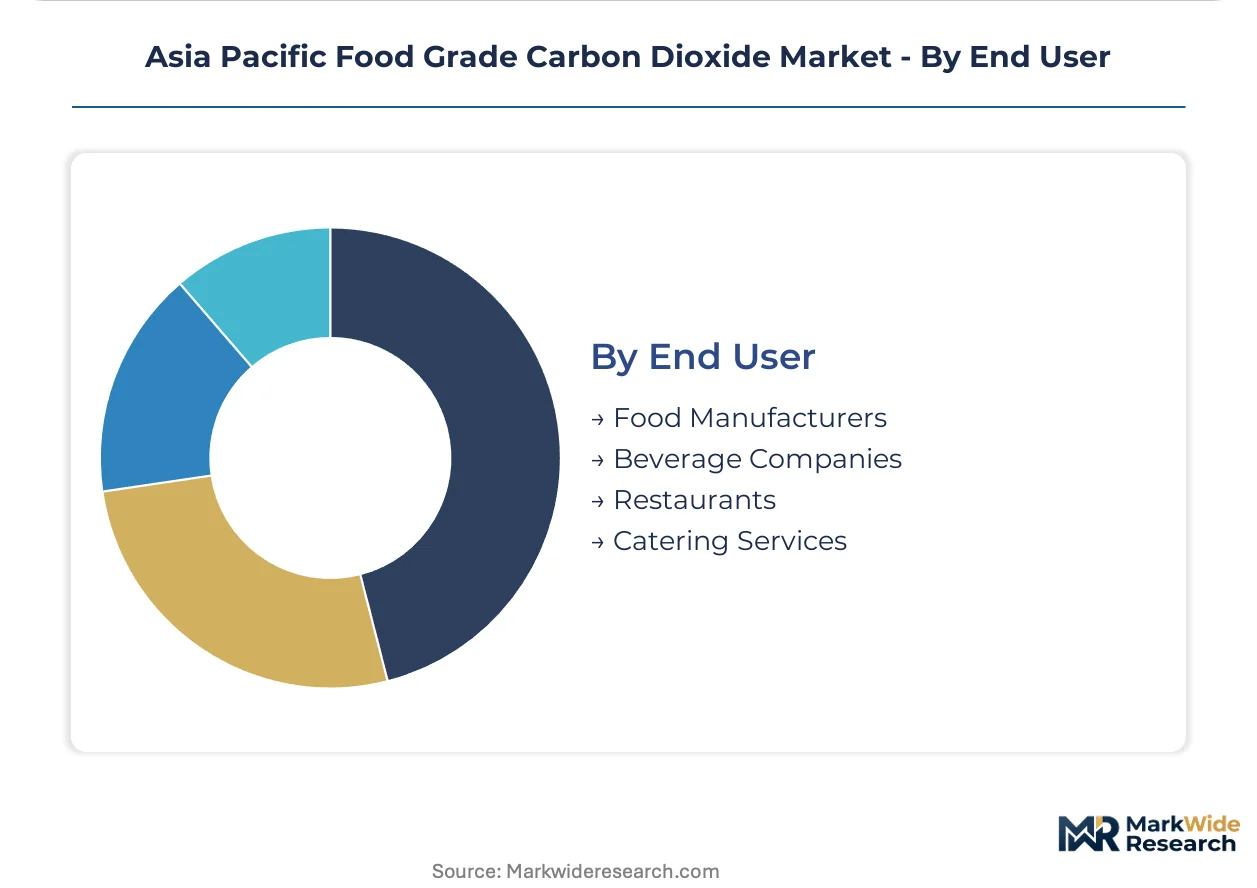
End-user segmentation tracks the divergence between industrial-scale carbonation demand and fragmented food service procurement patterns.
- Food Manufacturers:Industrial processors of frozen, chilled, and packaged foods requiring consistent cryogenic supply. Australian meat and dairy exporters anchor this segment's premium tier.
- Beverage Companies:Carbonated soft drink, beer, and ready-to-drink coffee producers. Indonesian and Vietnamese bottlers are pulling the steepest volume expansion.
- Restaurants:Food service establishments sourcing dry ice for beverage service and kitchen applications. Concentrated in urban Indian and Southeast Asian markets.
- Catering Services:Event and institutional food service operators with intermittent bulk requirements. Seasonal demand spikes align with festival calendars across the region.
Beverage Companies hold the dominant position, while Restaurants are climbing the fastest as food service platforms professionalize cold chain procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's liquid bulk terminal network underwrites China's dominance in food grade CO2 distribution, connecting Yangtze River Delta ammonia plants to Southeast Asian beverage corridors.
China
Carbonated soft drink manufacturing in Guangzhou and Shanghai manufacturing zones pulls liquid CO2 volumes through dedicated distribution corridors. SAMR enforces GB 1886.228 purity mandates that disqualify unqualified sources and redirect procurement toward certified industrial gas networks. The Yangtze River Delta cluster anchors supply security for domestic bottlers and ASEAN export channels.
India
Urban demand for packaged beverages in Mumbai and Delhi-NCR is accelerating liquid CO2 throughput at ammonia and ethanol plant off-gas recovery facilities. FSSAI mandates periodic purity auditing that faces bottlenecks as certified laboratory capacity lags behind installation growth. The Gujarat industrial corridor concentrates captive CO2 recovery from fertilizer production for food contact applications.
Japan
Pharmaceutical-adjacent food applications in Osaka and Nagoya processing zones command premium pricing for ultra-high-purity capture systems. METI coordinates with JIS K 1106 frameworks to align industrial gas specifications with export-oriented manufacturer requirements. The Kanto region integrates cryogenic chilling infrastructure for premium frozen food export segments.
Australia
Dairy and meat exporters in Victoria and New South Wales scale cryogenic chilling infrastructure to meet shelf-life requirements for Southeast Asian retail channels. TGA-aligned food safety protocols govern CO2 deployment in cold chain logistics for perishable exports. The Melbourne-Geelong manufacturing belt concentrates liquid CO2 storage assets serving trans-Tasman trade routes.
Vietnam
Urban consumption of carbonated beverages in Ho Chi Minh City and Hanoi is pulling liquid CO2 through dedicated distribution corridors from regional ammonia plant networks. Emerging ASEAN-wide food safety protocols under development could streamline supplier eligibility across cross-border manufacturing operations. The Mekong Delta beverage processing zone anchors procurement consolidation around ISO 22000-certified suppliers.
Asia Pacific Food Grade Carbon Dioxide Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with consolidated industrial gas majors controlling bulk liquid infrastructure while regional fabricators capture last-mile dry ice segments. The vendor base fragments across three strategic archetypes: integrated production-distribution networks, purity-specialized capture technology providers, and platform-based direct-to-restaurant channels. Capacity expansion and backward integration into ammonia plant off-gas sourcing represent the dominant competitive moves as supply security tightens.
Among the integrated majors, Air Liquide, Linde plc, and TAIYO NIPPON SANSO CORPORATION exemplify divergent specialization vectors. Air Liquide occupies a position emphasizing ASEAN supply security through production network integration. Linde plc anchors the cryogenic infrastructure tier across Australian dairy and Japanese meat processing corridors. TAIYO NIPPON SANSO CORPORATION sits within the ultra-high-purity capture segment, transferring vaccine cold chain specifications to pharmaceutical-adjacent food applications.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals, Inc. |
| TAIYO NIPPON SANSO CORPORATION |
| Messer Group |
| Sicgil India Limited |
| Coregas |
| Ellenbarrie Industrial Gases |
| WKS Industrial Gas Pte Ltd |
| Others |
Value Network & Pricing Analysis
Membrane separation systems displacing ammonia-plant off-gas as the primary CO2 source are redrawing supply geography across China and Thailand while compressing pricing spreads between fermentation-derived and industrial-captured volumes. This substitution dynamic simultaneously fragments production concentration and intensifies cost competition in beverage carbonation corridors.
Pricing Analysis
Certification level under GB 1886.228 and ISO 22000 creates the primary spread between premium liquid CO2 and uncertified merchant gas. Three-tier pricing structure across pharmaceutical-adjacent, food-grade certified, and industrial-standard levels segments buyer access. Cost compression in standard beverage carbonation is intensifying because membrane capture from biogas is flooding regional supply. Small-scale food processors show highest price sensitivity, while Australian dairy exporters absorb premium tiers for cryogenic integrity.
Supply Chain Analysis
China and India anchor ammonia-plant off-gas recovery for bulk liquid CO2, while Thailand and Australia feed growing membrane-capture volumes from ethanol and biogas streams. Feedstock supply draws from fertilizer production cycles, biofuel fermentation, and emerging direct air capture pilots. Single-source vulnerability concentrates around Yangtze River Delta ammonia complexes serving ASEAN bottlers. Distribution runs through dedicated tanker corridors linking production clusters to Shanghai, Guangzhou, Mumbai, and Delhi manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as e-commerce fresh food marketplaces in India and Southeast Asia disintermediate wholesale gas distributors, creating new interoperability standards between dry ice suppliers and restaurant procurement systems.
For Market Incumbents: Secure captive offtake agreements with ammonia and ethanol plant operators before membrane capture scales fragment feedstock access. Anchor cryogenic infrastructure investments in Australian dairy and Japanese meat processing corridors where pharmaceutical-grade specifications command durable premium tiers. Defend against platform-based disintermediation by embedding tank monitoring and automated replenishment into direct sales contracts. For New Entrants and Emerging Players: Last-mile dry ice fulfillment gaps in Indian metropolitan markets offer the most penetrable entry vector, as incumbent distributors lack temperature-verified delivery networks for restaurant and catering segments. Target direct-to-restaurant digital procurement platforms with modular solid CO2 production units sited near urban consumption clusters. Lead with traceability dashboards that document chain-of-custody for FSSAI and SAMR audit compliance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors purity-specialized capture technology providers with transferable vaccine cold chain credentials. Long-term viability hinges on backward integration into biogas and fermentation feedstocks rather than exposure to ammonia plant production cycles. Watch for ASEAN harmonization protocol announcements as the signal indicating cross-border supplier eligibility rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biogas Feedstocks | Captive CO2 supply from Thai and Australian ethanol plants reduces ammonia-plant dependency. |
| ISO 22000 Certification Investment | GB 1886.228 and FSSAI alignment unlocks procurement from ASEAN beverage manufacturing clusters. |
| Last-Mile Dry Ice Platform Development | Direct-to-restaurant channels in Indian metros bypass wholesale margin extraction. |
| Cryogenic Infrastructure Expansion | Liquid CO2 storage assets in Victoria and New South Wales serve trans-Tasman dairy exports. |
| Membrane Capture Technology Deployment | On-site purification at craft breweries fragments traditional merchant gas supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage carbonation engineers, cold chain logistics managers, FSSAI compliance auditors, and industrial gas procurement leads at ammonia plant operators. Secondary validation drew from SAMR regulatory filings, FSSAI purity audit protocols, ASEAN food safety framework drafts, and customs trade data on liquid CO2 tanker movements. Bottom-up volume modeling triangulated against top-down production capacity assessments across certified industrial gas networks.
Across the analysis window, forecasts applied segmentation by application, product form, distribution channel, and end-user archetype, with additional modeling of certification tier and geographic regulatory cluster. CAGRs were derived from installed capacity trajectories, consumption intensity per beverage manufacturing facility, and cold chain infrastructure investment pipelines. Industry-specific inputs included ammonia plant operating rates, ethanol refinery expansion schedules, and e-commerce fresh food platform growth curves.
Material uncertainties — feedstock substitution economics, ASEAN harmonization timing, and auditor capacity constraints in India — sit outside the modeled envelope. Forecasts reflect documented assumptions on membrane capture cost curves and platform-based procurement penetration. Recalibration cycles align with material shifts in regulatory enforcement intensity and cross-border supplier eligibility frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market