
 Data Center Outsourcing and Infrastructure Utility Services Market | 2026-2036
Data Center Outsourcing and Infrastructure Utility Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Outsourcing and Infrastructure Utility Services Market Analysis
ISO 27001 certification is bifurcating the competitive landscape into audit-ready operators and second-tier providers scrambling to qualify. Amazon Web Services sustains its position through captive fiber networks and custom silicon development. Equinix dominates interconnection density across metro markets, while Digital Realty anchors wholesale capacity in major European and Asian hubs.
Data center outsourcing and infrastructure utility services encompass the third-party provision of compute, storage, networking, and physical facility resources, typically delivered through multi-tenant facilities with power densities exceeding 15 kW per rack and redundant cooling architectures. Colocation services command the deepest margin pools where cross-connect revenue stacks above base rent, while edge computing deployments represent the fastest-expanding technology segment as latency-sensitive workloads push processing toward metropolitan peripheries.
The EU AI Act and CSRD impose algorithmic transparency and sustainability reporting obligations that filter procurement eligibility for government and large corporate clients. India's BIS and the US EPA Energy Star program enforce divergent efficiency benchmarks that operators must reconcile across portfolios. Stakeholders must monitor how jurisdictional data sovereignty rules fragment cloud architecture decisions before committing to multi-billion-dollar facility investments.
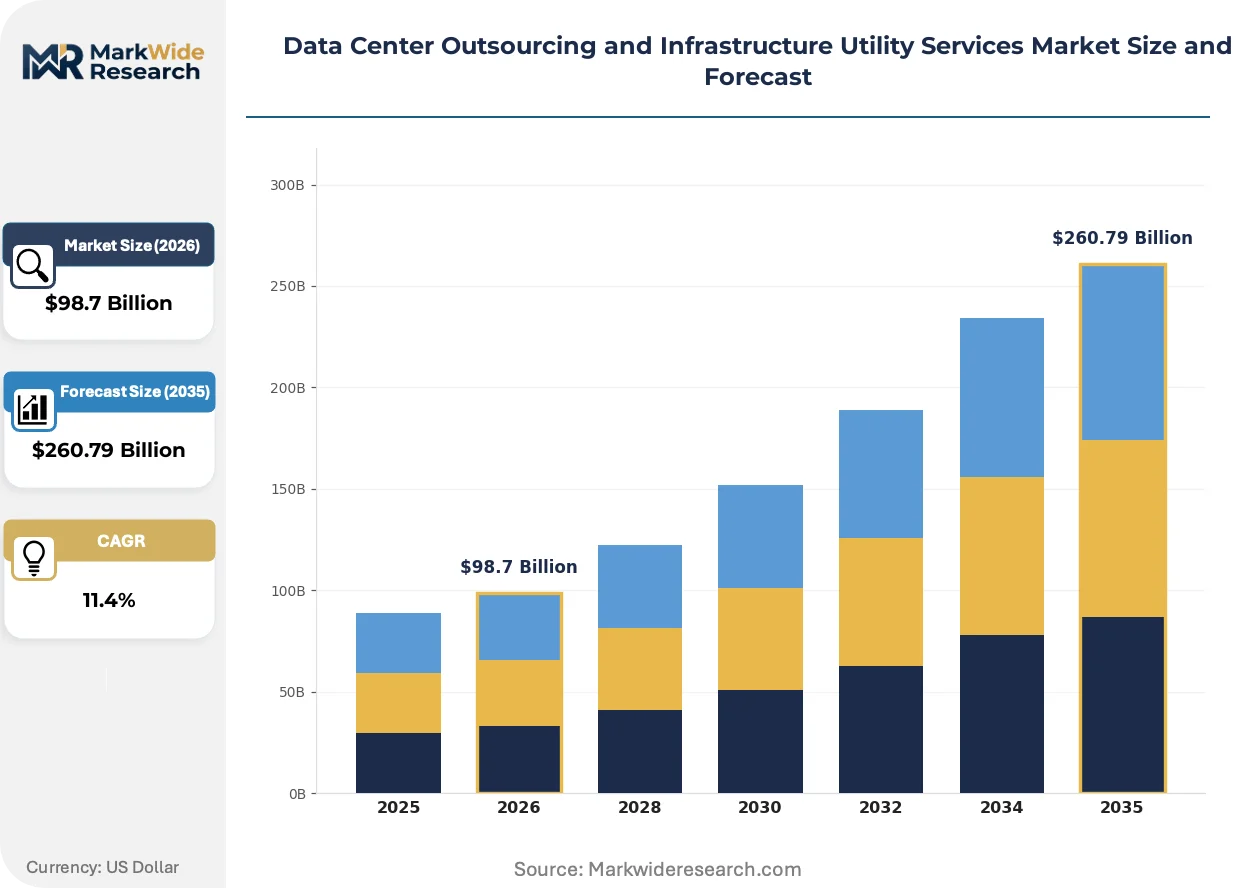
Market Dynamics
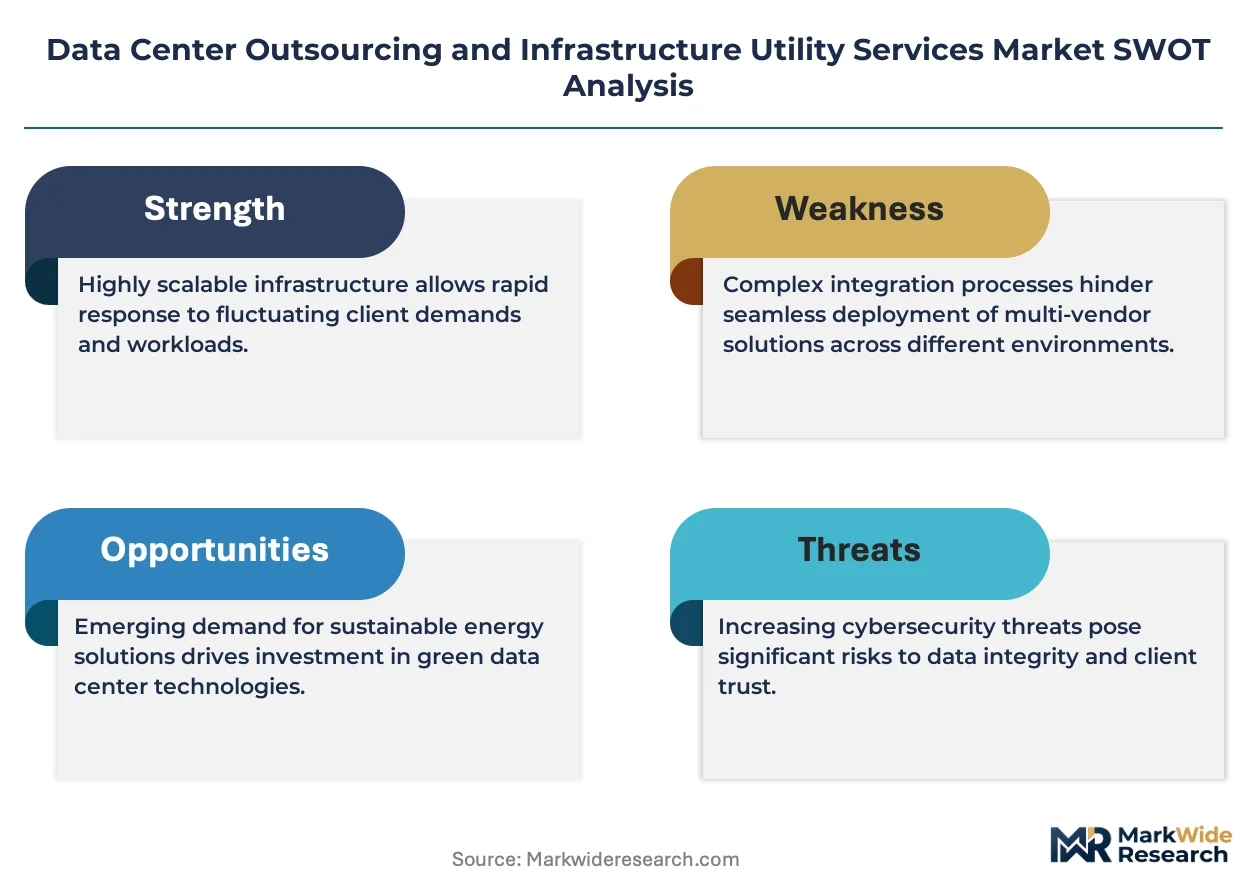
Hyperscale cloud operators are compressing procurement cycles and forcing facility operators to pre-certify against emerging sustainability and data sovereignty frameworks before contract award. This structural pressure is accelerating capital deployment into captive fiber networks and liquid-cooled architectures.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for high-risk AI systems are disqualifying uncertified operators from government and enterprise RFPs across France, Germany, and the Netherlands.
- Edge computing latency thresholds:Autonomous vehicle and industrial IoT applications are mandating sub-10 millisecond response times that central cloud cannot deliver.
- India's PLI scheme for electronics manufacturing:Domestic data center construction incentives in Mumbai and Bangalore are attracting hyperscale investment commitments.
Market Restraints
- Copper and lithium-ion supply concentration:Battery backup system costs fluctuate with Chilean copper output and Chinese cathode processing capacity.
- US EPA Energy Star fragmentation:Divergent efficiency benchmarking against EU CSRD creates dual-reporting burdens for transatlantic operators.
- Land scarcity in tier-one metros:Singapore, Amsterdam, and Frankfurt zoning restrictions limit greenfield expansion to brownfield retrofits.
Strategic Opportunities
- Saudi Arabia's NEOM giga-project:Sovereign wealth-funded smart city construction creates demand for 100% renewable-powered hyperscale campuses.
- Direct liquid cooling convergence with AI workloads:NVIDIA GPU clusters and immersion cooling systems are co-evolving to handle 50+ kW rack densities.
- ISO 50001 energy management certification:Early adopters capture premium pricing from sustainability-linked procurement mandates in European banking.
Industry Challenges
- Critical facilities engineering talent scarcity:Experienced commissioning engineers for 2N electrical topologies command 40% salary premiums over standard electrical contractors.
- Legacy mainframe migration complexity:Financial services clients require parallel-run validation periods that extend revenue recognition timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Outsourcing and Infrastructure Utility Services Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Colocation, Cloud Services, Hosting Services Technology: Virtualization, IoT, AI, Edge Computing Client Type: Small Enterprises, Large Corporations, Government, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Dedicated Infrastructure |
| Companies Covered | Equinix, Google Cloud Platform, Amazon Web Services (AWS), QTS Data Centers, Alibaba Cloud, Microsoft Azure, NTT Global Data Centers, Vantage Data Centers, Digital Realty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Outsourcing and Infrastructure Utility Services Market Emerging Trajectories
Workload distribution patterns are fragmenting as AI training clusters demand dedicated high-density footprints while inference workloads disperse toward metropolitan edge nodes. This bifurcation is reshaping facility design standards and interconnection strategies.
Modular data center enclosures are miniaturizing compute delivery into standardized 40-foot shipping containers with integrated power and cooling. Mining operations and military deployments are adopting these units for rapid field deployment. The technology is miniaturizing traditional facility construction into factory-integrated systems that compress deployment timelines from 18 months to 90 days.
The EU CSRD and F-Gas Regulation are mandating refrigerant phase-downs and embodied carbon disclosure across facility lifecycles. Operators must now account for Scope 3 emissions from steel and concrete procurement. Wholesale colocation providers in Frankfurt and Amsterdam are retrofitting existing shells rather than ground-up construction to preserve embodied carbon credits.
Enterprise procurement teams are unbundling managed services from base colocation contracts and sourcing hyperscale-direct for cloud while retaining third-party operators for bare-metal compliance workloads. This split-stack model disrupts traditional cross-sell economics. German automotive manufacturers and Japanese pharmaceutical groups exhibit the strongest preference for this disaggregated sourcing structure.
Data Center Outsourcing and Infrastructure Utility Services Market Segmentation
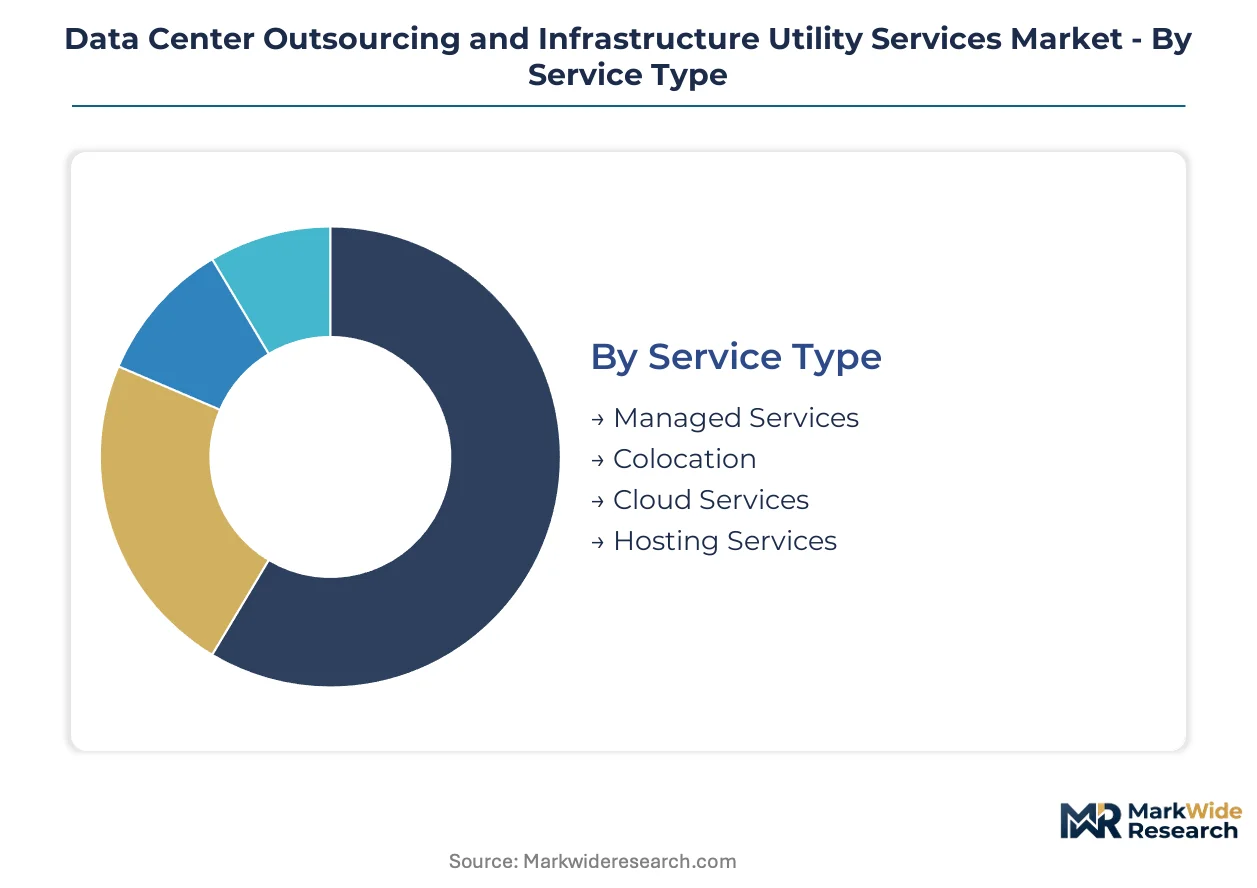
Channel economics in data center outsourcing vary sharply by service complexity. Managed services and colocation flow through direct sales teams with long contracting cycles, while cloud services route through self-service portals and partner marketplaces with compressed procurement timelines.
Service Type:
Channel mix splits between consultative enterprise sales for complex deployments and automated provisioning for standardized offerings. Managed services and colocation dominate direct channel revenue, while cloud services concentrate in digital marketplaces.
- Managed Services:Comprehensive IT infrastructure oversight spanning server administration, network operations, and security monitoring delivered through long-term service agreements. Financial services and healthcare verticals in Frankfurt and Singapore concentrate procurement here, driven by EU AI Act compliance mandates that require certified operational oversight for high-risk AI systems.
- Colocation:Physical rack and cage space leasing with cross-connect revenue stacking above base rent through interconnection ecosystems. Wholesale demand concentrates in Amsterdam and Mumbai where hyperscale operators pre-certify facilities against emerging sustainability frameworks before contract award.
- Cloud Services:On-demand compute and storage provisioning through hyperscale platforms with consumption-based billing.
- Hosting Services:Dedicated server leasing with managed operating system maintenance for mid-market clients.
Colocation dominates installed base. Cloud services is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive infrastructure from software-layer solutions. Virtualization and edge computing command premium pricing for specialized hardware, while AI and IoT layers run on standardized compute substrates.
- Virtualization:Hypervisor-based server abstraction enabling multi-tenant resource pooling and workload mobility. Legacy enterprise workloads in Germany and Japan remain concentrated here, constrained by mainframe migration complexity that extends parallel-run validation periods.
- Edge Computing:Distributed processing nodes positioned within 10 milliseconds of metropolitan endpoints for latency-sensitive applications. Autonomous vehicle and industrial IoT deployments in Bangalore and Dallas are expanding most quickly, driven by sub-10 millisecond response requirements that central cloud cannot deliver.
- IoT:Sensor data ingestion and device management platforms for connected industrial equipment.
- AI:GPU-accelerated training and inference infrastructure for machine learning workloads.
Virtualization anchors legacy infrastructure spend. Edge computing captures the steepest expansion trajectory.
Client Type:
Volume concentration follows procurement sophistication. Large corporations and government entities drive multi-year contract value, while small enterprises and educational institutions generate higher transaction velocity with lower per-deal economics.
- Large Corporations:Multi-site, multi-terabyte deployments with custom compliance requirements and dedicated account management. German automotive manufacturers and Japanese pharmaceutical groups are splitting procurement stacks, sourcing hyperscale-direct for cloud while retaining third-party operators for bare-metal compliance workloads.
- Government:Sovereign data residency mandates with security clearance requirements and extended RFP cycles. EU member states and India are disqualifying uncertified operators from procurement eligibility under algorithmic transparency and data sovereignty rules.
- Small Enterprises:Standardized colocation and cloud subscriptions with minimal customization.
- Educational Institutions:Research computing grants with seasonal utilization patterns and public funding constraints.
Large corporations dominate contract value. Government is where compliance-driven expansion concentrates.
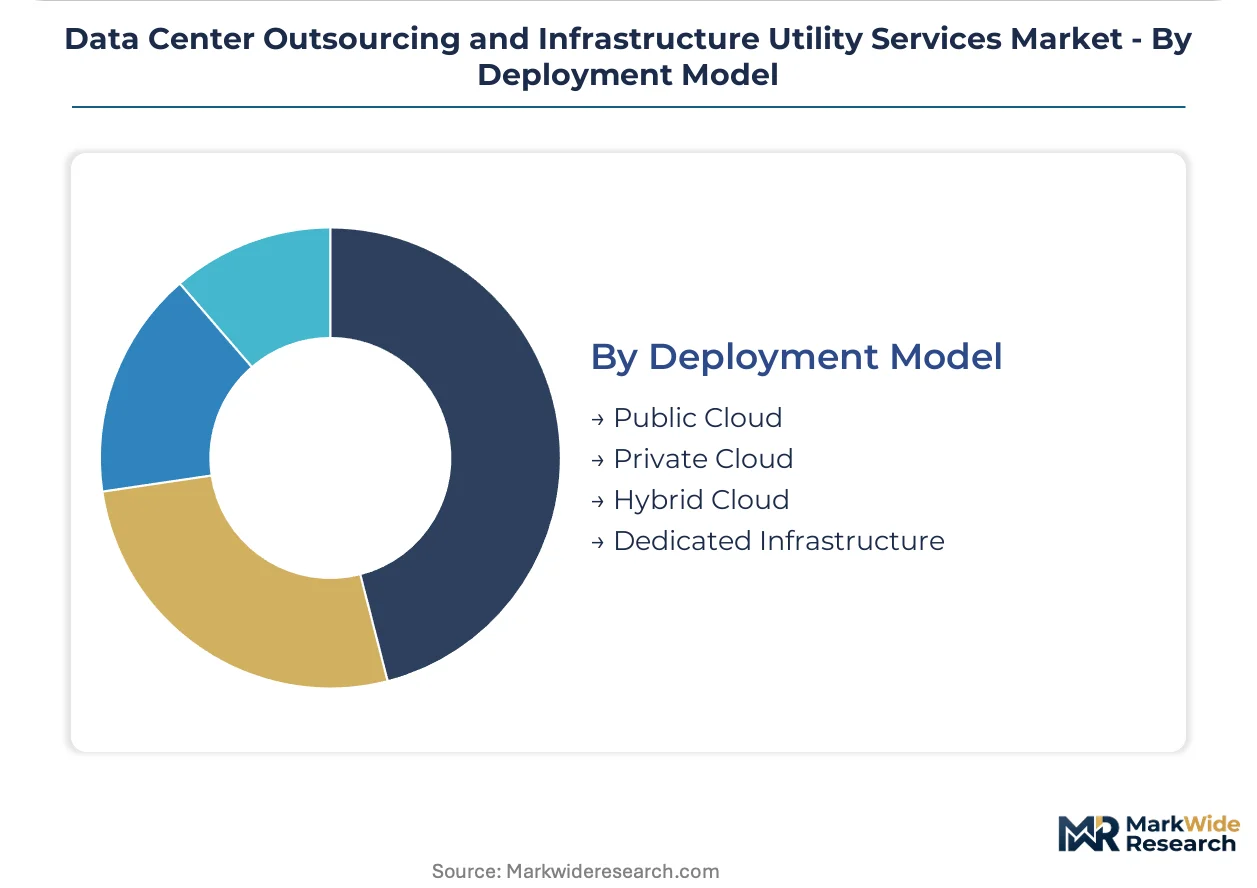
Deployment Model:
Margin structure varies by operational control. Dedicated infrastructure and private cloud capture premium pricing for single-tenant isolation, while public cloud and hybrid models trade margin for scale efficiency.
- Hybrid Cloud:Orchestrated workload portability across on-premises, private cloud, and public cloud substrates with unified management planes. European banking and US healthcare verticals concentrate adoption here, prioritizing ISO 50001-certified operators for sustainability-linked procurement mandates.
- Dedicated Infrastructure:Single-tenant physical or virtualized environments with guaranteed resource isolation and custom security postures. Saudi Arabia's NEOM giga-project and other sovereign wealth-funded developments are anchoring demand for 100% renewable-powered hyperscale campuses with dedicated facility commitments.
- Public Cloud:Shared multi-tenant infrastructure with automatic scaling and pay-per-use economics.
- Private Cloud:Exclusively allocated cloud resources within third-party facilities or on-premises.
Dedicated infrastructure dominates high-assurance deployments. Hybrid cloud is where workload portability investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The subsea cable landing stations at Mumbai and Chennai anchor India's emergence as Asia's primary data center hub. Frankfurt's DE-CIX internet exchange underwrites continental European interconnection density. Singapore's Tuas submarine cable corridor sustains Southeast Asian gateway status despite land constraints.
United States
Virginia's Data Center Alley and Dallas-Fort Worth anchor hyperscale expansion driven by AI training clusters and cloud inference workloads. The EPA Energy Star program enforces efficiency benchmarking that operators must reconcile against emerging state-level clean energy mandates. Northern Virginia's Loudoun County maintains the densest concentration of commissioned power capacity worldwide.
Germany
Frankfurt's banking sector and automotive manufacturing drive compliance-heavy colocation demand for bare-metal workloads. The EU AI Act and CSRD impose algorithmic transparency and sustainability reporting obligations that filter procurement eligibility for government contracts. Hesse and North Rhine-Westphalia concentrate new facility construction as brownfield retrofits predominate over greenfield development.
India
Mumbai and Bangalore anchor hyperscale facility construction fueled by domestic data localization mandates and cloud adoption acceleration. The BIS and PLI scheme for electronics manufacturing incentivize domestic construction and equipment sourcing. Maharashtra and Karnataka state governments compete for investment commitments through power tariff concessions and land allocation.
Saudi Arabia
The NEOM giga-project and Riyadh's financial district create demand for 100% renewable-powered hyperscale campuses with sovereign wealth backing. The SFDA and national data residency regulations mandate in-country processing for healthcare and government workloads. The Eastern Province and Tabuk region host new submarine cable landings that reduce latency to European and Asian markets.
Singapore
Tropical climate constraints and land scarcity have shifted expansion toward Johor Bahru across the strait while Singapore proper focuses on interconnection and financial services workloads. The Infocomm Media Development Authority enforces sustainability criteria for new data center approvals that privilege carbon-neutral designs. The Tuas industrial corridor accommodates remaining domestic capacity through vertical construction and liquid cooling retrofits.
Data Center Outsourcing and Infrastructure Utility Services Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The market structure consolidates around three tiers: hyperscale cloud operators with captive infrastructure, wholesale colocation providers with interconnection density, and regional specialists with compliance certifications. Strategic archetypes include fiber-integrated platform operators, sustainability-first developers, and sovereign-cloud joint ventures. Capacity pre-certification against emerging frameworks and captive renewable energy contracting represent dominant competitive moves.
Within the hyperscale cloud tier, Amazon Web Services and Microsoft Azure exemplify platform-integrated infrastructure operators with global fiber network investments. Among wholesale colocation specialists, Equinix occupies a position emphasizing interconnection density across metropolitan markets, while Digital Realty anchors wholesale capacity in major European and Asian hubs. These three companies represent divergent strategic postures: captive silicon and network development, ecosystem-centric metro positioning, and portfolio-scale wholesale leasing.
| Leading Market Players |
|---|
| Equinix |
| Google Cloud Platform |
| Amazon Web Services (AWS) |
| QTS Data Centers |
| Alibaba Cloud |
| Microsoft Azure |
| NTT Global Data Centers |
| Vantage Data Centers |
| Digital Realty |
| Others |
Supply Flow & Price Mechanics
EU AI Act compliance mandates and ISO 27001 certification requirements simultaneously gate supplier qualification and stratify price tiers across procurement contracts. Operators lacking pre-certification against algorithmic transparency frameworks face disqualification from government and enterprise RFPs, compressing their pricing power while audit-ready providers capture premium positioning.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with hyperscale operators commanding 30-40% unit economics advantages over mid-tier providers at committed capacity thresholds. Price differentiation rests on certification grade—ISO 50001 and CSRD-aligned sustainability disclosure separate premium tiers from standard offerings—and geographic delivery cost differentials between tier-one metros and secondary markets. Cost compression in wholesale colocation is intensifying because hyperscale cloud operators are compressing procurement cycles and forcing pre-certification investments before contract award. Small enterprises exhibit highest price sensitivity through standardized cloud subscriptions, while government entities and large corporations demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Strategic stockpiling of copper busbar and lithium-ion battery systems prevails over just-in-time approaches given Chilean mining output volatility and Chinese cathode processing concentration. Critical supply inputs draw from China for switchgear and power distribution components, South Korea for advanced battery cells, and Taiwan for precision cooling systems. Single-source vulnerability in Chinese rare earth processing for permanent magnet motors in cooling infrastructure represents persistent structural risk. Distribution runs through direct OEM relationships for hyperscale operators and tiered distributor networks for mid-market colocation providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hyperscale cloud operators consolidate procurement volumes and compress supplier margins through pre-certification requirements and captive infrastructure development.
For Market Incumbents: Fortify interconnection density in metro markets through fiber network expansion and liquid-cooled architecture deployment to defend against hyperscale vertical integration. ISO 50001 certification investment captures premium pricing from European banking sustainability-linked procurement mandates. Capacity addition in Mumbai and Bangalore preserves growth optionality as India's PLI scheme accelerates domestic construction. For New Entrants and Emerging Players: ISO 27001 fast-track certification opens procurement eligibility for government and healthcare verticals previously closed to uncertified operators. Edge computing deployments in secondary metros—Dallas, Phoenix, Denver—offer penetrable white space with sub-10 millisecond latency requirements that central cloud cannot satisfy. Bare-metal compliance workload specialization for German automotive and Japanese pharmaceutical split-stack procurement provides differentiated go-to-market positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled AI training clusters as rack densities exceed 50 kW and immersion cooling infrastructure becomes mandatory. Long-term viability over the projection horizon favors operators with captive renewable energy contracting and pre-certified sustainability frameworks. Acquisition targets should demonstrate established interconnection ecosystems or sovereign-cloud joint venture structures. The signal to monitor is hyperscale procurement cycle compression and pre-certification requirement diffusion across European and Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Program | Captures premium pricing from EU CSRD-aligned banking procurement mandates in Frankfurt and Amsterdam. |
| Liquid Cooling Infrastructure Deployment | Enables 50+ kW rack densities for NVIDIA GPU clusters as AI training workloads expand. |
| Captive Fiber Network Expansion | Reduces latency dependency on third-party carriers for hyperscale interconnection in Northern Virginia. |
| Sovereign Cloud Joint Venture | Satisfies Saudi SFDA data residency requirements for NEOM healthcare and government workloads. |
| Modular Container Manufacturing Scale-Up | Compresses deployment timelines from 18 months to 90 days for mining and military field deployments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler capex disclosures, EPA Energy Star benchmarking data, EU regulatory filings, and subsea cable landing databases. Primary interviews engaged data center facility operators, enterprise IT procurement officers, critical facilities commissioning engineers, and interconnection exchange managers. Secondary validation drew from customs trade data for copper and battery imports, state-level power tariff filings, and BIS equipment certification registries. Bottom-up capacity installation tracking triangulates against top-down cloud revenue attribution models.
Segmentation dimensions modeled span service type, deployment model, client vertical, and technology layer across the analysis window. CAGRs derive from facility commissioning pipelines, hyperscale lease-up rates, and edge node deployment trajectories. Forecast inputs incorporate power density evolution curves for AI workloads, refrigerant phase-down schedules under EU F-Gas Regulation, and land availability constraints in Singapore, Amsterdam, and Frankfurt zoning jurisdictions.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale capex commitment and stable copper-lithium supply chains; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding EU AI Act enforcement timelines and India's PLI scheme continuation. Revision becomes warranted when hyperscale vertical integration into captive facility ownership crosses threshold levels or when sovereign data residency rules fragment cloud architecture decisions beyond current jurisdictional patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Mexico Data Center Physical Security Market