
 Data Center Power Market | 2026-2036
Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Power Market Analysis
North American transformer and switchgear manufacturing capacity is hardening after years of underinvestment, creating procurement bottlenecks for data center developers racing to energize new facilities. Schneider Electric leverages its integrated power distribution portfolio to capture bundled infrastructure contracts across hyperscale campuses. Eaton anchors its position through advanced UPS architectures that bridge grid-interactive and islanded operating modes. Vertiv specializes in thermal-electrical co-design, differentiating where power density and cooling loads converge.
Data center power encompasses the generation, conditioning, distribution, and backup infrastructure that delivers conditioned electricity to IT loads with target availability exceeding 99.999 percent, typically operating at voltages from 480V AC down to 12V DC at the server rack. The primary purpose is eliminating single points of failure while optimizing energy efficiency across variable load profiles. UPS systems dominate capital allocation among system types, reflecting their role as the first line of defense against grid disturbances. Above 100 kW power capacity segments attract the fastest investment growth, driven by AI training clusters that concentrate megawatts into single halls. Renewable energy solutions within the technology dimension remain nascent in direct data center integration but expand through utility-scale power purchase agreements that offset carbon exposure.
The EPA regulates stationary generator emissions under Tier 4 Final standards, while OSHA mandates arc flash protection and electrical safety protocols for maintenance personnel. IEEE 1547 interconnection standards shape how on-site generation and storage integrate with utility distribution networks. Stakeholders must monitor evolving grid interconnection queues and utility tariff structures, as these administrative bottlenecks now constrain deployment timelines more severely than equipment availability.
Market Dynamics
AI training clusters are compressing megawatt-scale loads into single halls, forcing power infrastructure to evolve from distributed redundancy toward centralized high-capacity architectures that strain conventional UPS and switchgear form factors.
Growth Catalysts
- EPA Tier 4 Final Emissions Standards:The EPA's tightening regulations on stationary diesel generators are accelerating adoption of natural gas and battery-based backup systems in hyperscale facilities across the United States.
- Liquid-Cooled AI Racks:Thermal-electrical co-design requirements for GPU-intensive training workloads are bundling power and cooling procurement decisions, expanding contract values for integrated infrastructure vendors.
- Virginia's Data Center Corridor:Concentrated utility investment in transmission capacity around Loudoun County is attracting contiguous campus developments that aggregate demand for 100+ MW substations.
Market Restraints
- Copper and Electrical Steel Volatility:Transformer core materials face price instability tied to mining output and trade policy, compressing margins for switchgear manufacturers already operating at capacity limits.
- North American Manufacturing Concentration:Years of underinvestment in domestic transformer production have created 18-24 month lead times for critical substation equipment, throttling facility energization schedules.
- Grid Interconnection Queues:Utility administrative backlogs now exceed equipment procurement cycles, with interconnection studies delaying project completion independent of hardware availability.
Strategic Opportunities
- India's Data Center Buildout:The country's PLI scheme for electronics manufacturing is attracting hyperscale investment in Mumbai and Chennai, creating demand for localized power infrastructure partnerships.
- Behind-the-Meter Solar Plus Storage:Declining lithium-ion costs are enabling on-site generation configurations that reduce exposure to utility tariff volatility while satisfying corporate renewable targets.
- 480V DC Distribution Architectures:Eliminating AC-DC conversion losses at the rack level is absorbing interest from cloud operators seeking fractional efficiency gains at megawatt scale.
Industry Challenges
- Medium-Voltage Engineering Talent Scarcity:Specialized expertise in 15kV-35kV switchgear design and commissioning is concentrating among retiring utility veterans, constraining project execution velocity.
- IEEE 1547 Interconnection Certification Complexity:Evolving grid codes for inverter-based resources require repeated firmware validation cycles, extending commissioning timelines for battery energy storage systems.
- Legacy 480V Infrastructure Stranding:Existing facilities face capital-intensive retrofits to accommodate 415/240V IT equipment power supplies, complicating upgrade economics for colocation operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Power Market |
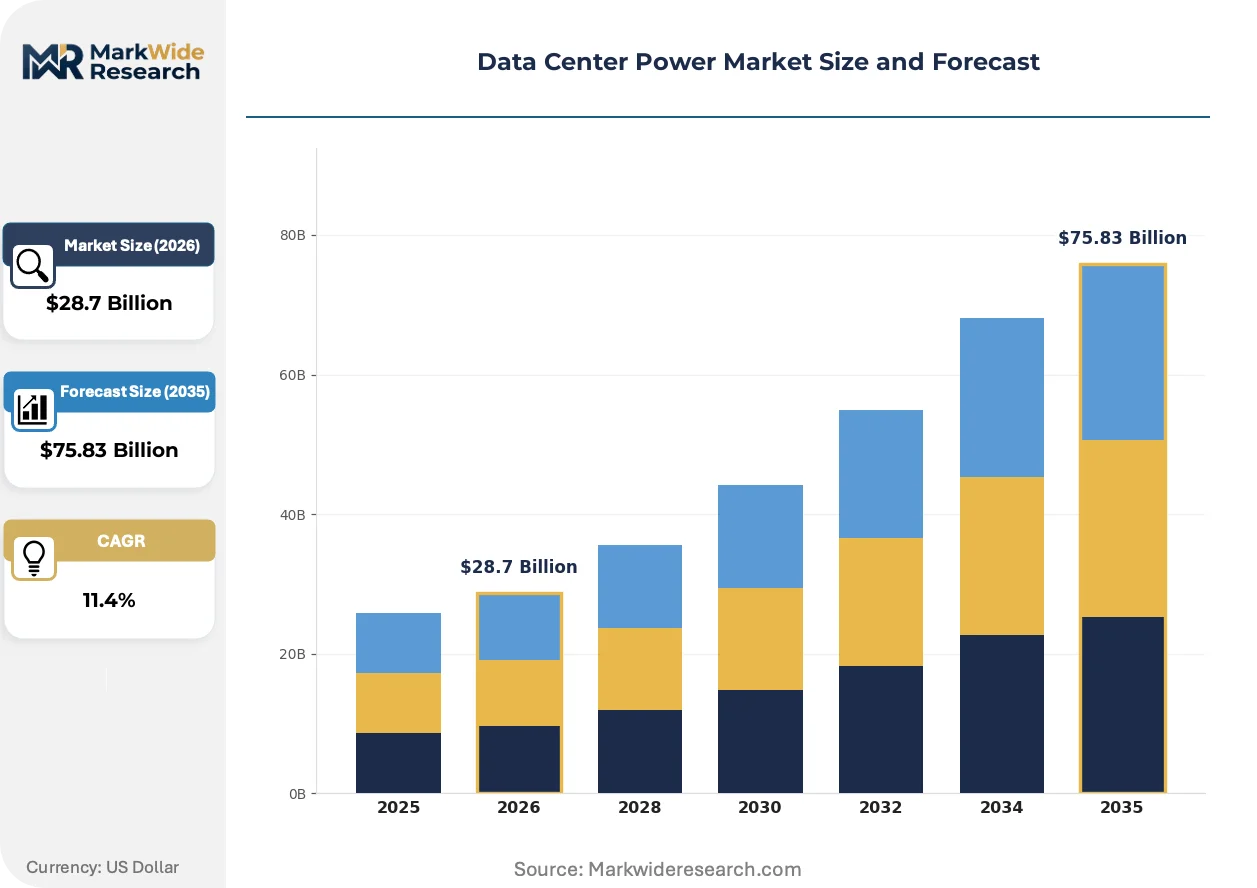
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: UPS, Generators, Power Distribution Units, Power Cables Power Capacity: 10-20 kW, 20-50 kW, 50-100 kW, Above 100 kW End User Type: Hyperscale Operators, Colocation Providers, Enterprise Users, Managed Service Providers Technology: AC Power, DC Power, Renewable Energy Solutions, Energy Storage Systems |
| Companies Covered | ABB, Delta Electronics, Schneider Electric, Bloom Energy, Emerson Electric, Eaton, Legrand, Generac Holdings, Vertiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Power Market Emerging Trajectories
Solid-state power electronics and software-defined energy management are converging to displace electromechanical protection systems, compressing footprint while enabling granular load orchestration that electromechanical relays cannot match.
Silicon carbide (SiC) power semiconductors are absorbing switching losses in high-frequency UPS and rectifier designs, enabling 50% volume reduction in power conversion hardware. Hyperscale operators in the United States are specifying SiC-based architectures for new 100+ MW facilities, treating the premium as acceptable against real estate constraints. This technology is absorbing capital allocation that previously flowed to conventional IGBT-based systems, compressing the addressable market for legacy topologies.
The EU Green Deal's carbon border adjustment mechanism is reshaping equipment sourcing decisions for data center developers with European footprints, favoring suppliers with documented Scope 3 emissions reductions. Manufacturers are responding by certifying transformer cores to IEC 60076 efficiency standards that exceed baseline CE requirements. Asian suppliers serving European customers face the steepest compliance burden, accelerating partnerships with EU-based steel producers.
Utility-scale power purchase agreements are displacing on-site renewable generation as the primary carbon accounting mechanism for cloud operators, decoupling facility location from clean energy procurement. This contractual innovation allows developers to site in transmission-rich locations like Northern Virginia while attributing Wyoming wind or Texas solar to their consumption. The shift is most visible among North American hyperscalers, where virtual PPAs now dominate sustainability disclosures over rooftop solar or fuel cell installations.
Data Center Power Market Segmentation
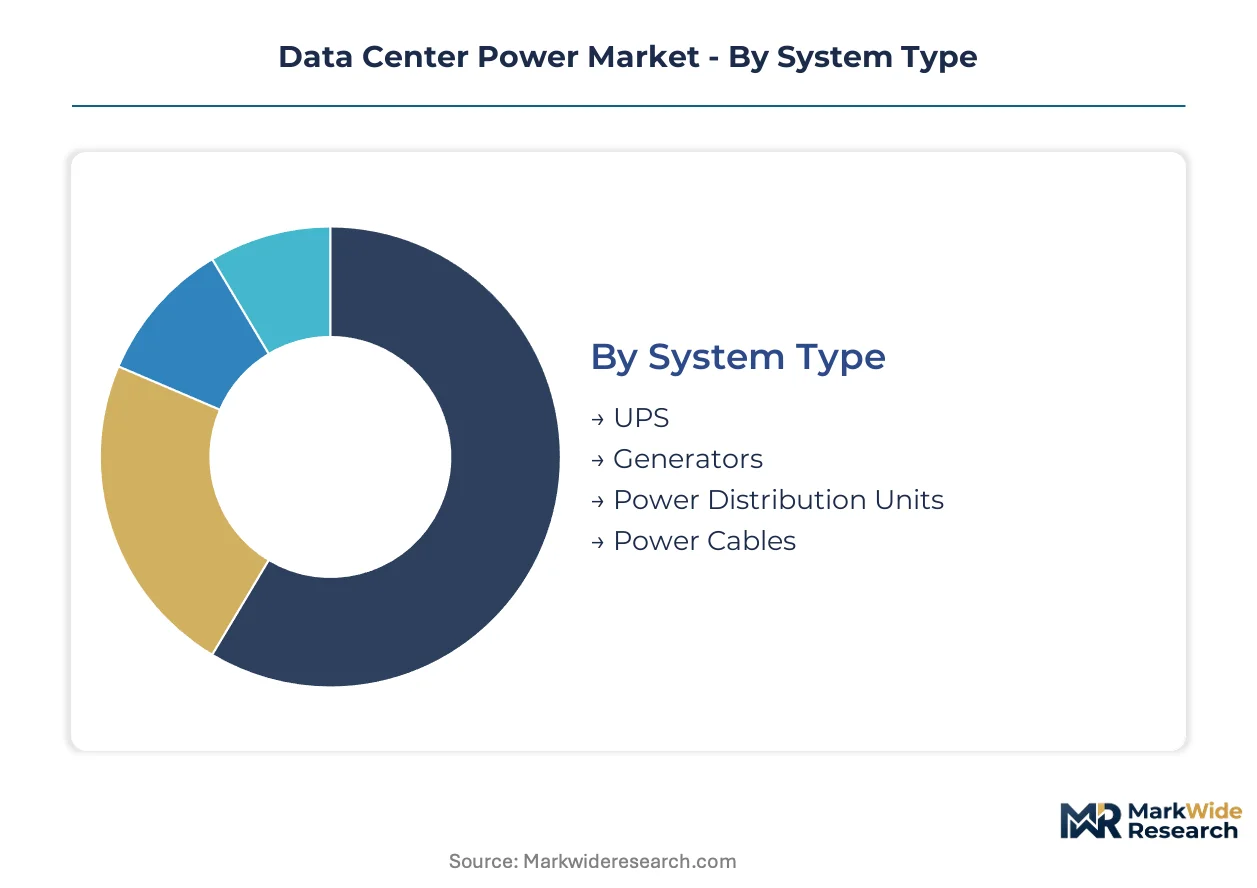
Power infrastructure procurement in data centers diverges sharply by operational scale and electrical architecture. Segmentation reveals where capital concentrates versus where technology shifts are disrupting incumbent suppliers.
System Type:
Equipment selection follows availability requirements and the criticality tier of protected loads.
- UPS:Double-conversion online systems dominate hyperscale deployments for their zero-transfer capability during grid disturbances. Virginia's Northern Virginia corridor consumes the highest concentration of megawatt-class UPS modules globally, driven by contiguous AI training campus construction.
- Generators:Diesel and natural gas reciprocating engines provide backup power for sustained outages beyond battery autonomy. EPA Tier 4 Final compliance costs are compressing diesel's share in new U.S. builds while accelerating natural gas adoption.
- Power Distribution Units:Rack-level and floor-mounted units manage final power delivery to IT equipment with branch circuit protection.
- Power Cables:Medium-voltage and low-voltage conductors connect substations through busway to rack power whips.
UPS leads on scale; Generators leads on momentum as emissions regulations force fuel switching.
Power Capacity:
Capacity segmentation maps directly to server density evolution and the shift from distributed to centralized power architectures.
- Above 100 kW:Single-cabinet and row-based systems serving GPU-intensive AI clusters where rack densities exceed 40 kW. Demand concentrates in Northern Virginia, Dallas, and Phoenix where hyperscalers are consolidating megawatt halls.
- 50-100 kW:High-density compute and storage applications in enterprise and colocation facilities. India's Mumbai and Chennai markets are absorbing significant volume as the PLI scheme attracts cloud infrastructure investment.
- 20-50 kW:Standard density enterprise workloads and traditional virtualization environments.
- 10-20 kW:Legacy enterprise servers and network equipment in retrofit-constrained facilities.
Above 100 kW leads on scale; 50-100 kW leads on momentum as international markets replicate U.S. density trajectories.
End User Type:
Procurement patterns separate by ownership model and the tradeoff between capital deployment speed and operational control.
- Hyperscale Operators:Self-operated cloud campuses with dedicated substations and customized medium-voltage architectures. These buyers specify silicon carbide UPS and direct liquid cooling integration, compressing vendor qualification cycles.
- Colocation Providers:Multi-tenant facilities selling space and power by the rack or cage. Lease structures favor modular, rapidly deployable power infrastructure with standardized redundancy tiers.
- Enterprise Users:Corporate-owned data centers with mixed legacy and modernized infrastructure.
- Managed Service Providers:Outsourced IT operators with variable density requirements across client portfolios.
Hyperscale Operators lead on scale; Colocation Providers lead on momentum as enterprise demand shifts to outsourced capacity.
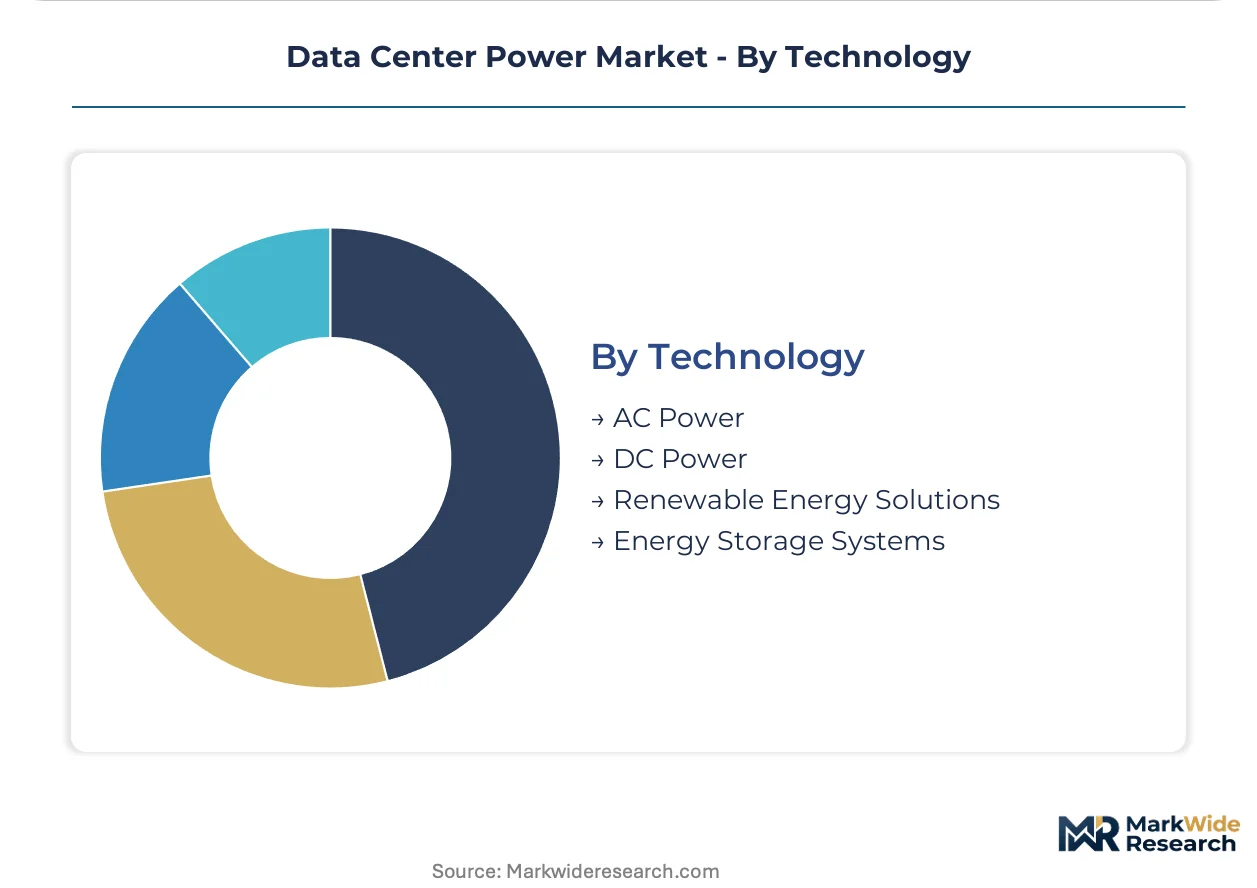
Technology:
Electrical architecture choices determine conversion efficiency, integration complexity, and compatibility with distributed energy resources.
- AC Power:Dominant 480V/208V distribution with redundant conversion stages from utility to server. Established supply chains and technician familiarity sustain its position despite conversion losses.
- DC Power:380V DC and 48V DC architectures eliminating inversion stages for battery and solar integration. Pilot deployments in hyperscale facilities are validating fault protection and equipment availability.
- Renewable Energy Solutions:On-site solar, fuel cells, and wind with direct facility connection or virtual power purchase agreement structures.
- Energy Storage Systems:Lithium-ion and emerging solid-state batteries replacing traditional lead-acid for short-duration backup and grid services participation.
AC Power leads on scale; Energy Storage Systems leads on momentum as battery costs decline and grid interconnection queues extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing data center power infrastructure investment as operators migrate toward jurisdictions with favorable interconnection policies and emissions compliance costs. Developers now prioritize locations where utility administrative efficiency outweighs marginal labor or land savings.
United States
Virginia's Loudoun County hosts the world's densest concentration of computing infrastructure, with hyperscalers procuring 100+ MW substations for contiguous AI training campuses. EPA Tier 4 Final standards are accelerating fuel switching from diesel to natural gas backup systems across new hyperscale builds. Northern Virginia's utility investment in transmission capacity continues attracting megawatt-scale hall construction from cloud operators.
Germany
The EU Green Deal's carbon border adjustment mechanism is reshaping equipment sourcing decisions for developers with European footprints, favoring suppliers with documented Scope 3 emissions reductions. Manufacturers are certifying transformer cores to IEC 60076 efficiency standards exceeding baseline CE requirements. Frankfurt's banking sector concentration sustains demand for high-availability power architectures in financial services data centers.
India
The country's PLI scheme for electronics manufacturing is attracting hyperscale investment in Mumbai and Chennai, creating localized demand for power infrastructure partnerships. CEA regulations on grid interconnection shape how on-site generation and storage integrate with utility distribution networks. Maharashtra's Mumbai metro area is absorbing significant volume for 50-100 kW systems as cloud infrastructure investment accelerates.
China
MIIT guidance on data center energy efficiency is concentrating new capacity in western provinces with abundant renewable resources and cooler climates. GB standards for power distribution equipment govern procurement specifications for domestic operators. Sichuan-Chongqing's hydroelectric surplus is attracting mining and AI training facilities seeking low-carbon power procurement.
United Kingdom
Ofgem's grid connection queue reforms are attempting to reduce administrative bottlenecks that now constrain deployment timelines more severely than equipment availability. CSRD disclosure requirements are elevating Scope 3 emissions scrutiny across supply chains for power infrastructure. London's Slough corridor maintains its position as Europe's premier data center cluster despite land constraints and planning restrictions.
Data Center Power Market Vendor Landscape
European producers anchor one tier; Asia-Pacific specialists hold contract manufacturing relationships for commodity components. The market structures around three tiers: integrated power distribution conglomerates, thermal-electrical co-design specialists, and component-focused manufacturers. Strategic moves concentrate on M&A for medium-voltage engineering talent and capacity expansion in transformer core materials.
Within the integrated infrastructure tier, Schneider Electric and Eaton occupy positions that exemplify bundled system approaches, while Vertiv represents the thermal-electrical convergence archetype. These three anchors demonstrate how vendor qualification cycles compress when hyperscale operators specify silicon carbide architectures and direct liquid cooling integration. Their collective positioning illustrates the shift from distributed redundancy toward centralized high-capacity power architectures.
| Leading Market Players |
|---|
| ABB |
| Delta Electronics |
| Schneider Electric |
| Bloom Energy |
| Emerson Electric |
| Eaton |
| Legrand |
| Generac Holdings |
| Vertiv |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud operators concentrated in Northern Virginia and Dallas anchor procurement volumes, compressing vendor margins through consolidated 100+ MW substation contracts that favor bundled infrastructure packages over component-level sourcing.
Pricing Analysis
Distributor margins on medium-voltage switchgear have compressed as direct manufacturer-hyperscale relationships displace traditional electrical supply houses. Pricing stratifies across premium silicon carbide UPS architectures, standard IGBT-based systems, and economy-tier refurbished units, with EPA Tier 4 Final compliance costs driving diesel generator premiums upward. Cost compression in transformer cores is intensifying because copper and electrical steel volatility feeds directly into landed equipment costs. Colocation providers exhibit the highest price sensitivity due to lease-structured capital constraints, while hyperscale operators absorb premiums for footprint reduction.
Supply Chain Analysis
Regional distribution centers in Texas, Virginia, and Ohio maintain hub-and-spoke patterns for emergency generator and UPS module deployment. Manufacturing concentrates in the United States, Germany, and China, with domestic transformer production operating at capacity limits following years of underinvestment. Supply chains draw from Chilean copper, Ukrainian electrical steel, and rare earth elements processed in China. Single-source vulnerability in transformer core materials threatens project timelines. Distribution runs through manufacturer-direct channels for hyperscale contracts and electrical distributors for mid-market enterprise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as AI training clusters force specification upgrades toward silicon carbide architectures and liquid-cooled integration that reward engineering depth over cost minimization.
For Market Incumbents: To counter medium-voltage engineering talent scarcity, Schneider Electric and Eaton should acquire specialized switchgear design firms in Germany and the United States while expanding captive transformer core production to secure material access against commodity volatility. For New Entrants and Emerging Players: Channel partners serving India's Mumbai and Chennai data center corridors offer the most penetrable entry path, with localized power infrastructure partnerships representing white-space demand as PLI scheme incentives attract hyperscale investment. For Investors and Strategic Acquirers: Integrated infrastructure conglomerates are the most active acquirer in this space, targeting thermal-electrical co-design specialists and medium-voltage engineering boutiques. Long-term viability favors vendors with silicon carbide certification and direct liquid cooling integration capabilities. The signal to watch is utility interconnection queue reform announcements in Virginia and Texas as inflection indicators for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Architecture Certification | Schneider Electric and Eaton capture bundled contracts as hyperscalers specify SiC-based UPS for footprint reduction. |
| Medium-Voltage Engineering Acquisition | Vertiv defends thermal-electrical positioning by acquiring retiring utility veteran expertise in 15kV-35kV switchgear design. |
| Transformer Core Material Backward Integration | Domestic manufacturers secure captive copper and electrical steel supply against 18-24 month procurement bottlenecks. |
| India Localization Partnership | EPC contractors in Mumbai and Chennai establish local power infrastructure assembly to serve PLI-attracted hyperscale campuses. |
| Natural Gas Generator Fuel Switching | EPA Tier 4 Final compliance accelerates adoption of cleaner backup architectures in Virginia and Dallas corridor builds. |
Methodological Framework
Direct dialogue with data center developers, utility interconnection planners, EPC contractors, and medium-voltage switchgear engineers grounded qualitative findings, validated against SEC filings from Schneider Electric and Eaton, EPA regulatory dockets, FERC interconnection queue databases, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked equipment procurement volumes against utility transmission investment patterns.
Bottom-up modeling aggregated individual facility power capacity specifications across the projection horizon, while top-down analysis calibrated against aggregate transformer and switchgear manufacturing capacity. Segmentation dimensions included system type, power capacity tier, end user ownership model, and electrical architecture technology. CAGRs derived from facility energization timelines and equipment replacement cycles, with Virginia's Loudoun County cluster and India's PLI scheme buildout serving as demand anchors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to utility interconnection queue reform progress, copper and electrical steel trade policy shifts, and EPA emissions standard evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
North America Data Center Power Market