
 DC Powered Servers Market | 2026-2036
DC Powered Servers Market Size, Share, and Industry Trends Forecast 2026-2036
DC Powered Servers Market Outlook
Enterprise-grade 48V rack-mount specifications is collapsing the legacy 12V infrastructure base across hyperscale facilities. Dell Technologies leverages its PowerEdge portfolio to anchor North American supply chains for high-density DC racks. Huawei Technologies competes through integrated power distribution architectures that collapse conversion stages in telecom edge deployments. Vertiv dominates thermal management pairing with DC busbars, sustaining technical differentiation against conventional AC-integrated competitors.
DC powered servers are computing platforms engineered to operate on direct current input, typically at 48V or 400V, eliminating alternating current conversion losses through native rectifier bypass and onboard DC-DC regulation stages. Rack-mount servers lead volume shipments as cloud service providers standardize Open Compute Project 48V power shelves, while blade servers capture premium margins in financial services co-location facilities where space density governs total cost of ownership. Managed services represent the fastest-expanding service type as operators outsource DC busbar maintenance and battery-backed rack commissioning to specialized integrators.
FERC interconnection standards and EPA Energy Star server specifications shape US deployment timelines by mandating efficiency reporting at partial load conditions where DC architectures outperform legacy designs. China's GB standards for data center power usage effectiveness and India's CEA renewable purchase obligations create parallel compliance pathways that favor native DC topologies in solar-wind hybrid facilities. Stakeholders must monitor evolving electrical codes governing fault protection in 400V DC distribution zones before committing to next-generation rack architectures.
Market Dynamics
Hyperscale data center operators in Northern Virginia, Frankfurt, and Singapore are collapsing legacy 12V power distribution in favor of 48V native DC architectures as rack densities exceed 30kW per cabinet and thermal loads strain conventional AC-DC conversion chains.
Growth Catalysts
- EPA Energy Star server specifications:Tightened efficiency thresholds at partial load conditions favor native DC topologies over legacy AC-integrated designs in US hyperscale facilities.
- China's GB standards for data center PUE:National green data center mandates compress power usage effectiveness ratios below 1.3, accelerating 400V DC busbar deployment in utility-scale renewable integration projects.
- Solar-wind hybrid facilities:Native DC coupling eliminates double-conversion losses between renewable generation and compute loads, concentrating procurement in India under CEA renewable purchase obligations.
Market Restraints
- Copper busbar cost volatility:Raw material price swings in 48V power distribution components compress margin structures for rack integrators.
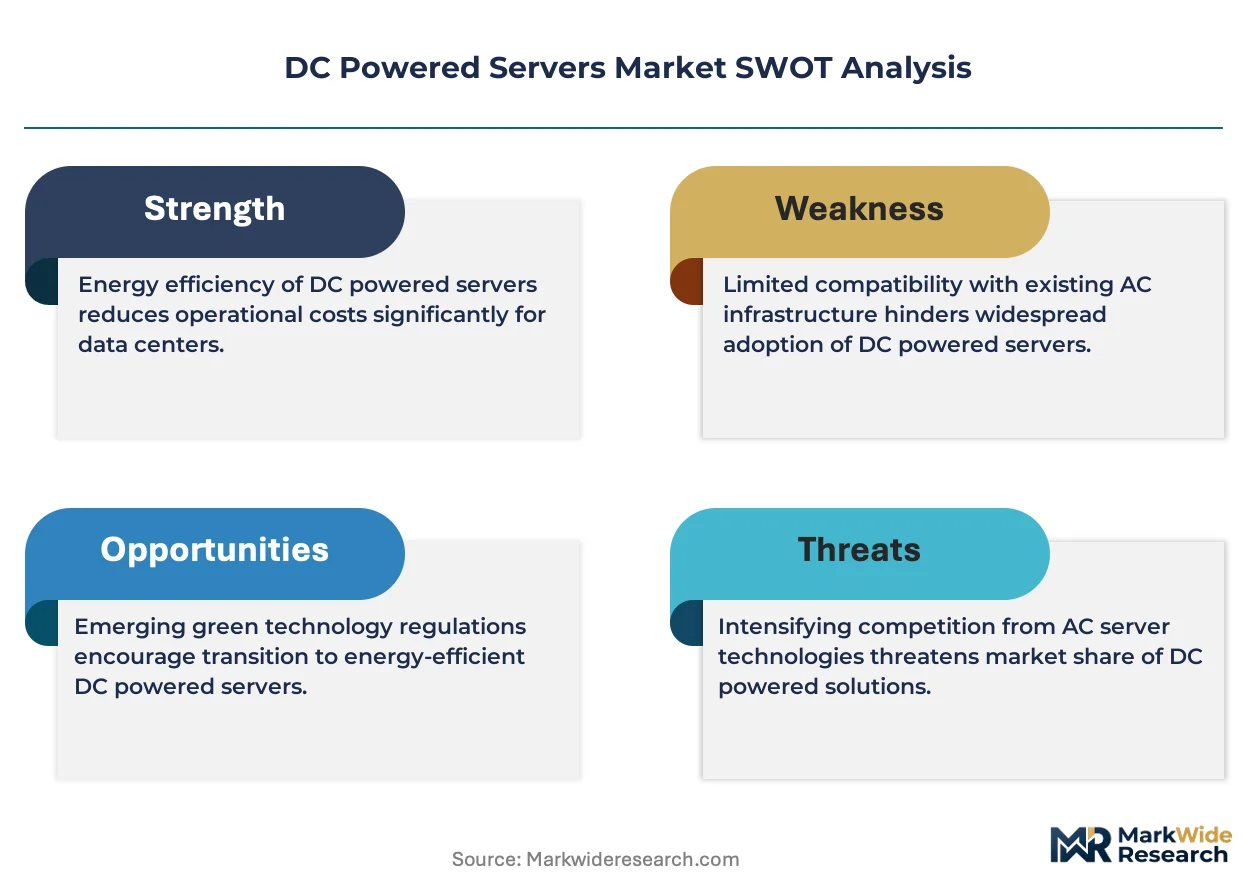
- 400V DC fault protection standards:Evolving electrical codes governing arc interruption and ground-fault detection create compliance uncertainty before next-generation architecture commitments.
- Legacy AC infrastructure lock-in:Existing UPS and PDU investments in mature facilities create substitution friction against full DC retrofit cycles.
Strategic Opportunities
- Telecom edge deployments:Integrated power distribution architectures that collapse conversion stages capture unpenetrated base station and micro data center buildouts across Germany.
- Managed DC busbar services:Outsourced maintenance and battery-backed rack commissioning represent white-space revenue streams as operators shed in-house electrical expertise.
- Open Compute Project 48V power shelves:Standardization tailwinds enable volume procurement scale previously reserved for proprietary designs.
Industry Challenges
- Electrical commissioning expertise scarcity:Qualified technicians for 400V DC distribution zone certification remain concentrated with specialized integrators, constraining deployment velocity.
- Legacy AC-DC hybrid integration complexity:Transitional architectures requiring simultaneous AC backup and DC primary power create control system interoperability failures during fault events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Powered Servers Market |
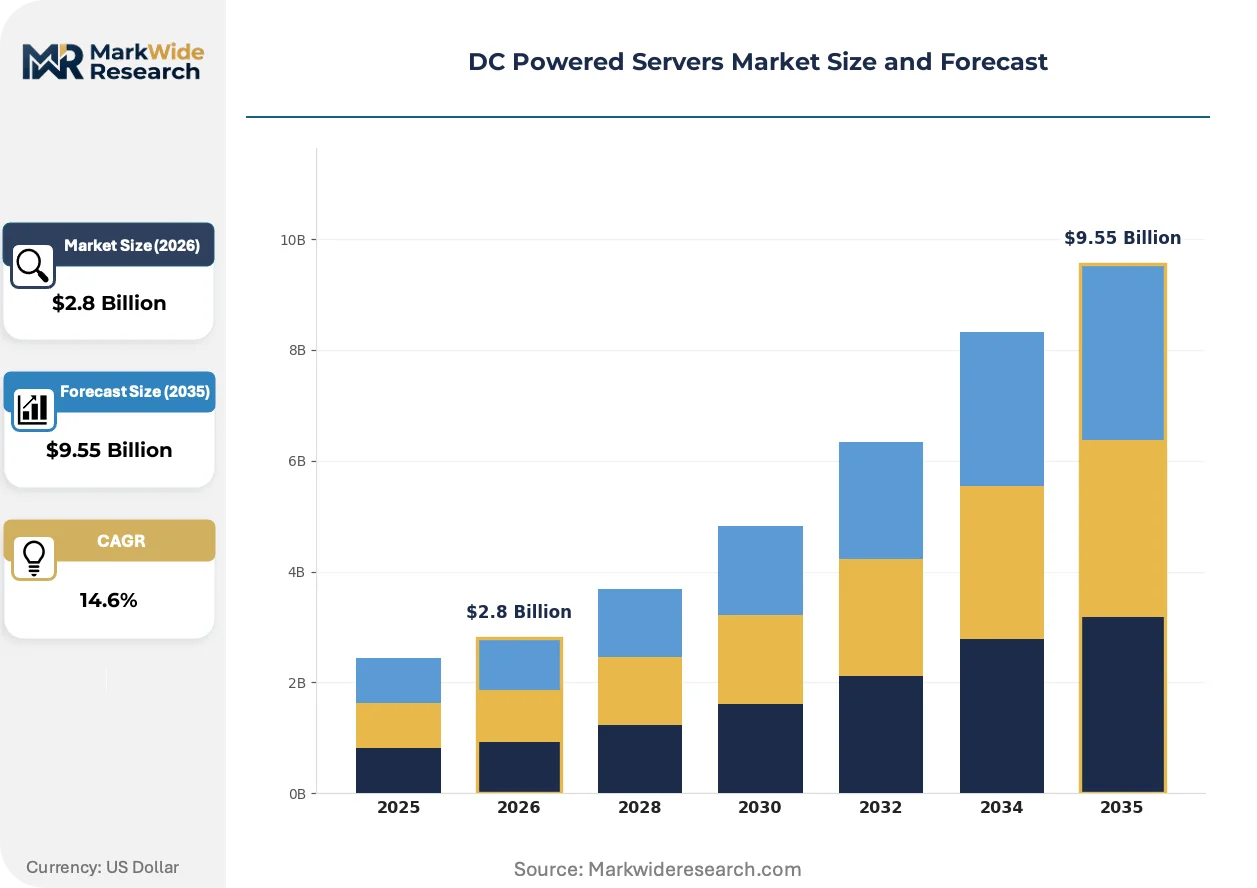
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack-Mount Servers, Blade Servers, Tower Servers, Modular Servers End User: Data Centers, Cloud Service Providers, Telecom, Enterprises Technology: Power Distribution, Cooling Systems, Load Balancing, Virtualization Service Type: Managed Services, Maintenance Services, Installation Services, Consulting Services |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, IBM Corporation, Vertiv, Schneider Electric, Intel Corporation, Lenovo, Cisco Systems, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Powered Servers Market Strategic Shifts
Technical evolution across power electronics, thermal management, and procurement structures is compressing traditional supply chain boundaries while elevating electrical efficiency from a cost center to a competitive differentiator.
Silicon carbide power semiconductors are decomposing the traditional silicon MOSFET and IGBT hierarchy in 48V DC-DC regulation stages. Hyperscale operators in Northern Virginia and Singapore have accelerated adoption timelines from five-year evaluation cycles to eighteen-month deployment schedules. This material transition is decomposing thermal management cost structures by enabling higher switching frequencies that shrink magnetics and reduce cooling overhead.
EU F-Gas Regulation phase-down schedules are compressing refrigerant choices for thermal management systems paired with high-density DC racks. The industrial consequence mandates transition to natural refrigerants or water-based cooling in facilities exceeding 1MW compute loads. Blade server configurations in Frankfurt co-location facilities are most affected, driving rapid specification updates to liquid-cooled cold plate architectures.
Cloud service provider procurement is consolidating around Open Compute Project reference designs that commoditize power shelf and busbar specifications. Traditional OEM channel structures face disintermediation as direct-to-operator sourcing of DC infrastructure components accelerates. This pattern is most visible in Northern Virginia hyperscale clusters where vertical integration into power distribution hardware is displacing third-party electrical contractor relationships.
DC Powered Servers Market Segmentation
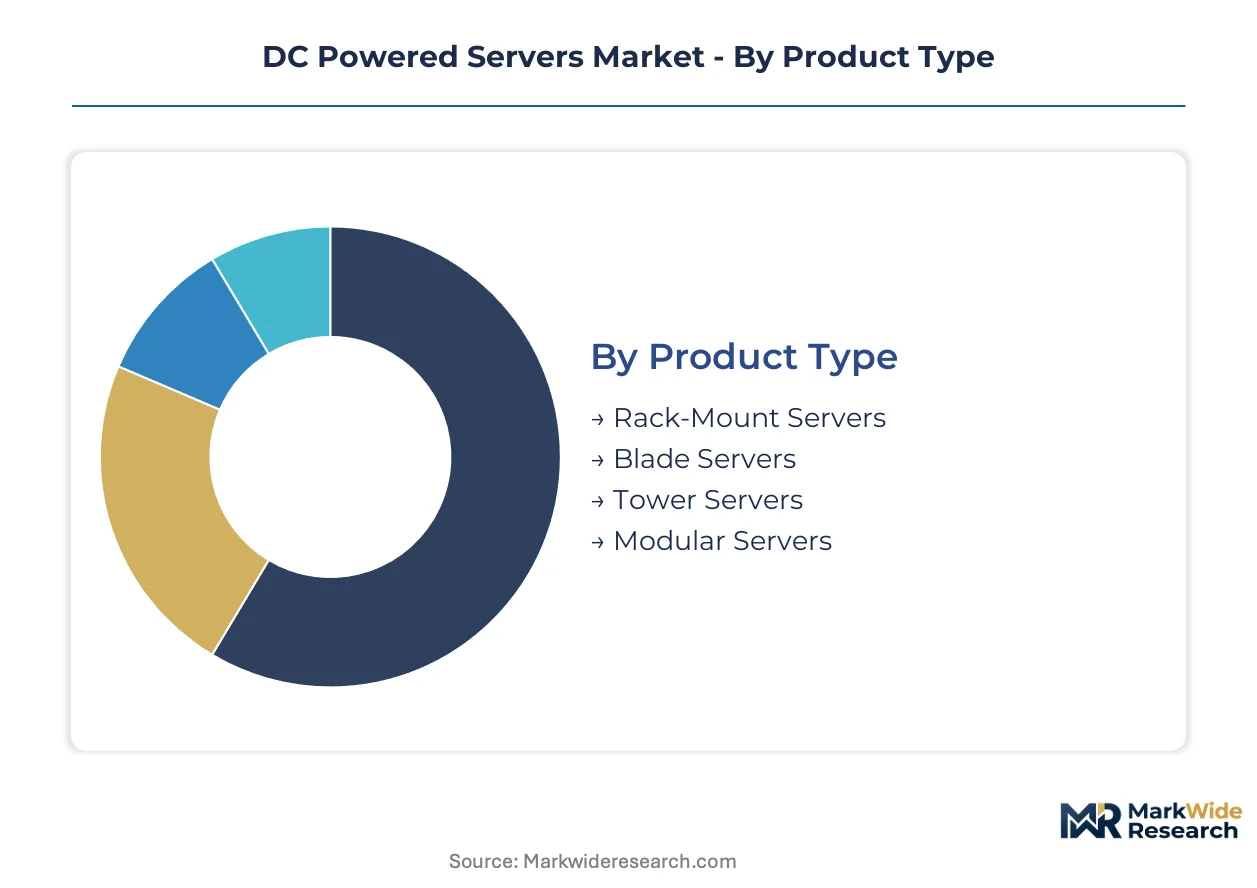
Segmentation in the DC powered servers market reveals how regulatory pressure, infrastructure topology, and procurement economics fragment demand across distinct technical configurations. Understanding these divisions exposes where efficiency mandates concentrate purchasing power and which specifications capture premium positioning.
Product Type:
EPA Energy Star specifications and China's GB standards for data center PUE create divergent compliance pathways that favor different form factors based on rack density and conversion efficiency requirements.
- Rack-Mount Servers:These units integrate directly with 48V Open Compute Project power shelves, eliminating intermediate AC-DC conversion stages. Cloud service providers in Northern Virginia and hyperscale facilities across Frankfurt standardize on this form factor as cabinet densities exceed 30kW and thermal loads strain legacy distribution chains.
- Blade Servers:High-density configurations compress multiple compute nodes into shared power and cooling infrastructure. Financial services co-location facilities in Singapore and Frankfurt deploy these for space-constrained environments where total cost of ownership depends on square-meter efficiency rather than per-unit pricing.
- Tower Servers:Standalone vertical enclosures serve edge computing sites and small enterprise data rooms with limited rack infrastructure.
- Modular Servers:Disaggregated compute, storage, and networking components enable incremental scaling in renewable-powered micro data centers.
Rack-mount servers handle the majority of throughput; blade servers are gaining share fastest in premium co-location segments.
End User:
Procurement scale and technical sophistication separate customers into distinct specification tiers, with the largest operators dictating standards that cascade downstream.
- Data Centers:Multi-tenant facilities in Northern Virginia and Singapore anchor volume demand through standardized 48V busbar deployments. These operators specify native DC architectures to compress PUE ratios below regulatory thresholds while accommodating tenant densities above 30kW per cabinet.
- Cloud Service Providers:Vertical integration into power distribution hardware enables direct sourcing of DC infrastructure components, bypassing traditional OEM channels. Amazon Web Services, Microsoft Azure, and Google Cloud Platform drive Open Compute Project adoption timelines from five-year evaluation cycles to eighteen-month deployment schedules.
- Telecom:Base station and micro data center buildouts across Germany concentrate demand for integrated power distribution architectures that collapse conversion stages in space-constrained edge locations.
- Enterprises:Legacy AC infrastructure lock-in constrains retrofit velocity, though greenfield facilities in India under CEA renewable purchase obligations increasingly specify native DC coupling.
Data centers command the largest procurement volumes; cloud service providers are expanding most quickly as vertical integration accelerates.
Technology:
Silicon carbide semiconductor transitions and EU F-Gas Regulation phase-downs are restructuring cost allocation across power and thermal subsystems.
- Power Distribution:48V and 400V DC busbar architectures eliminate double-conversion losses between renewable generation and compute loads. China's GB standards and India's CEA obligations favor these topologies in solar-wind hybrid facilities where native DC coupling maximizes efficiency.
- Cooling Systems:EU F-Gas Regulation mandates transition to natural refrigerants or water-based cooling in facilities exceeding 1MW compute loads. Liquid-cooled cold plate architectures are displacing conventional air handling in Frankfurt co-location deployments.
- Load Balancing:Software-defined power management optimizes DC-DC regulation stages across variable compute workloads.
- Virtualization:Hypervisor-level resource allocation maximizes utilization rates in high-density DC rack configurations.
Power distribution absorbs the majority of capital allocation; cooling systems are climbing the fastest as thermal density thresholds tighten.
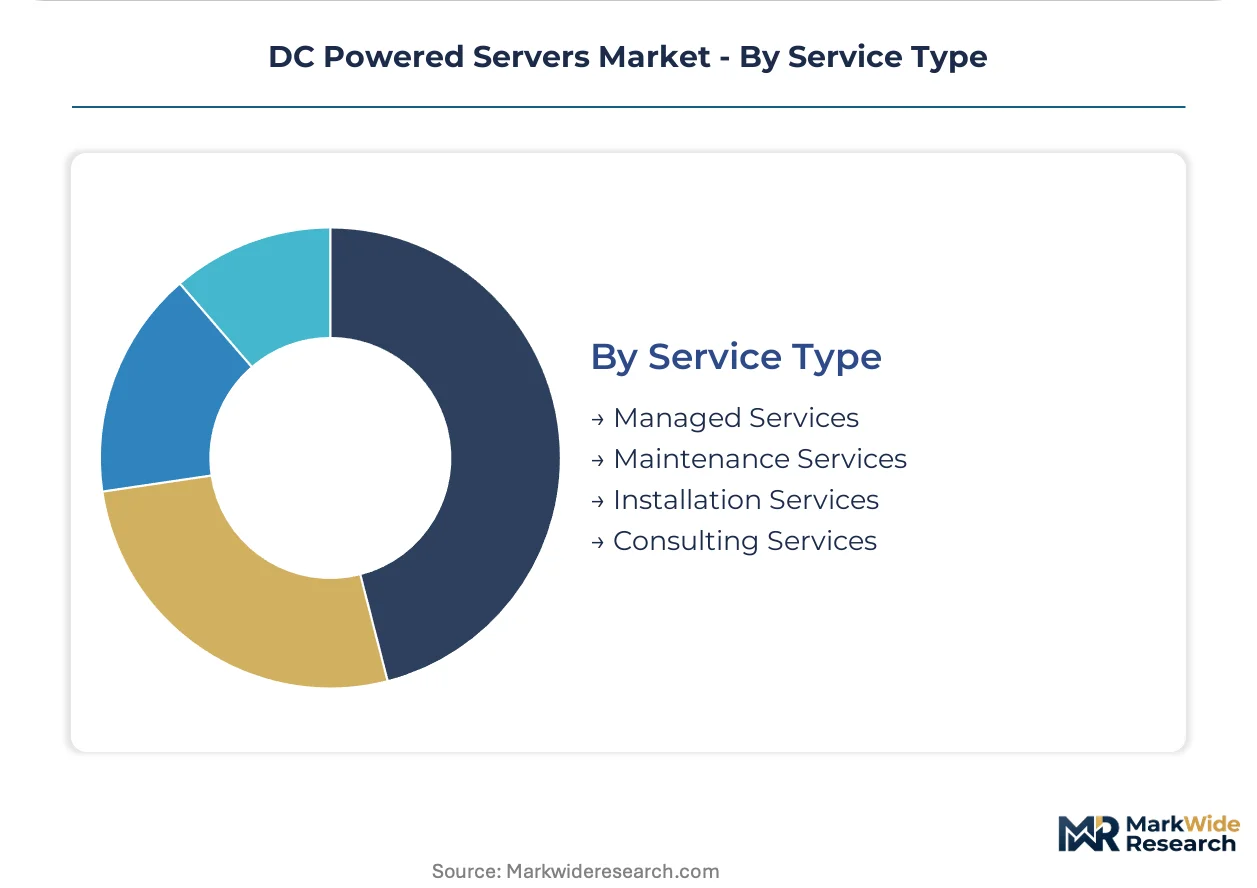
Service Type:
Electrical commissioning expertise scarcity is shifting operational responsibility from in-house teams to specialized integrators.
- Managed Services:Outsourced DC busbar maintenance and battery-backed rack commissioning address qualified technician shortages. Operators across Northern Virginia and Singapore shed in-house electrical expertise as 400V DC distribution zone certification requirements concentrate capability with specialized providers.
- Maintenance Services:Predictive analytics and remote monitoring reduce unplanned downtime in mission-critical hyperscale environments.
- Installation Services:Turnkey commissioning ensures compliance with evolving electrical codes governing arc interruption and ground-fault detection in 400V DC zones.
- Consulting Services:Design-phase advisory navigates fault protection standard uncertainty before architecture commitments.
Managed services capture the steepest expansion trajectory as outsourcing accelerates; installation services anchor near-term revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor nations with integrated renewable generation and domestic hyperscale buildouts, while import-dependent markets face copper busbar cost volatility and specialized technician shortages.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth are collapsing legacy 12V infrastructure as rack densities exceed 30kW per cabinet. EPA Energy Star server specifications mandate efficiency reporting at partial load conditions where native DC architectures outperform legacy designs. FERC interconnection standards shape deployment timelines for solar-wind hybrid facilities seeking native DC coupling.
China
GB standards for data center power usage effectiveness compress PUE ratios below 1.3, accelerating 400V DC busbar deployment in utility-scale renewable integration projects. MIIT guidelines favor integrated power distribution architectures that eliminate double-conversion losses between generation and compute loads. Yangtze River Delta facilities anchor procurement volume as state-owned cloud operators standardize on Open Compute Project reference designs.
Germany
Telecom edge deployments across Bavaria and North Rhine-Westphalia concentrate demand for space-constrained integrated power architectures in base station and micro data center buildouts. EU F-Gas Regulation phase-down schedules mandate transition to natural refrigerants or water-based cooling in facilities exceeding 1MW compute loads. Frankfurt co-location facilities drive premium blade server specifications where square-meter efficiency governs total cost of ownership.
India
CEA renewable purchase obligations create compliance pathways favoring native DC topologies in solar-wind hybrid facilities where direct coupling maximizes efficiency. Greenfield data centers in Maharashtra and Karnataka increasingly specify 48V architectures over legacy AC infrastructure. Domestic operators shed in-house electrical expertise, accelerating outsourcing of DC busbar maintenance to specialized integrators.
Singapore
Limited land availability drives extreme density requirements above 30kW per cabinet, favoring 48V native DC architectures with liquid-cooled cold plate thermal management. National sustainability mandates for data center efficiency align procurement with Open Compute Project standardization timelines. Cloud service provider clusters concentrate direct-to-operator sourcing of power distribution hardware, displacing traditional OEM channel structures.
DC Powered Servers Market Competitive Environment
Concentration sits with diversified technology conglomerates possessing captive server portfolios and integrated power distribution capabilities. The vendor base spans three distinct tiers: hyperscale-focused hardware OEMs, specialized thermal and power infrastructure providers, and telecom-anchored integrated solution vendors. Strategic moves center on backward integration into power electronics manufacturing and upstream control over silicon carbide semiconductor supply chains. Partnership structures with Open Compute Project consortia determine reference design access and procurement eligibility.
Within the diversified technology tier, Dell Technologies and Hewlett Packard Enterprise exemplify hardware OEMs with established North American supply chain positions. Huawei Technologies occupies a position among integrated solution vendors leveraging power distribution architecture expertise. Vertiv represents the specialized infrastructure archetype, pairing thermal management systems with DC busbar deployments. These three anchors illustrate how competitive positioning fragments across technical specialization rather than consolidating around full-stack dominance.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Vertiv |
| Schneider Electric |
| Intel Corporation |
| Lenovo |
| Cisco Systems |
| Huawei Technologies |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for silicon carbide MOSFETs concentrate pricing power with Taiwanese foundries and compress margin structures for rack integrators dependent on just-in-time power electronics procurement. Cloud service providers in Northern Virginia exploit volume scale to negotiate preferential allocation, while smaller operators absorb spot-market volatility in 48V busbar components.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade positioning under UL 1741-SA and IEEE 1547 standards for grid-interactive power distribution, while economy tiers serve non-critical edge deployments with stripped-down thermal management. Cost compression in standard-tier rack-mount configurations is intensifying because Open Compute Project commoditization eliminates proprietary markup leverage. Hyperscale cloud operators exhibit lowest price sensitivity due to captive sourcing teams, whereas regional co-location facilities in India and Germany face acute budget constraints.
Supply Chain Analysis
Sixty-day inventory cycles for copper busbar stock expose rack integrators to London Metal Exchange price swings that propagate downstream into final assembly costs. Manufacturing concentrates in China, Taiwan, and South Korea for power semiconductors, with Mexico and Vietnam emerging for final rack integration. Raw material dependencies center on copper cathodes, silicon carbide wafers, and rare-earth magnetics for DC-DC regulation stages. Single-source vulnerability in 400V DC contactor supply creates disruption risk for European deployments. Distribution runs through direct-to-operator channels for hyperscale procurement, while regional integrators rely on distributor networks for fragmented enterprise demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DC powered server infrastructure is exiting a capex contraction cycle as hyperscale operators resume 48V architecture deployment following EPA efficiency mandate acceleration. Rack density thresholds exceeding 30kW per cabinet justify replacement economics against legacy 12V infrastructure.
For Market Incumbents: Secure captive supply of silicon carbide semiconductors through foundry partnerships or in-house wafer capacity commitments. Defend against disintermediation by embedding thermal management expertise into power shelf designs that OEMs cannot replicate through direct sourcing. Channel control through certified integrator networks protects specification influence in fragmented enterprise segments.
For New Entrants and Emerging Players: Anchor in managed DC busbar services where electrical commissioning expertise scarcity concentrates margin capture. Telecom edge deployments across Germany represent the most penetrable white-space, with base station micro data centers requiring integrated power architectures that collapse conversion stages. A hardware-as-a-service go-to-market angle bypasses upfront capital barriers for regional co-location operators.
For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure efficiency play because regulatory mandates for power usage effectiveness create irreversible substitution pressure against legacy AC designs. Acquisition targets should display vertical integration into power electronics manufacturing or upstream silicon carbide supply relationships. The signal to watch is FERC finalization of 400V DC fault protection standards, which would trigger architecture commitment lock-in across US hyperscale facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Captive wafer allocation from Taiwanese foundries secures 48V regulator production capacity. |
| Open Compute Project Certification | Reference design approval enables procurement eligibility with AWS, Azure, and Google Cloud Platform. |
| Liquid Cooling Partnership | Cold plate integration with DC busbars addresses EU F-Gas Regulation mandates for Frankfurt facilities. |
| Managed Services Capability Buildout | Outsourced maintenance contracts capture recurring revenue as operators shed electrical expertise. |
| India Greenfield Facility Investment | CEA renewable purchase obligations create native DC coupling demand in Maharashtra and Karnataka. |
Study Parameters
A standing panel of hyperscale facility directors, power electronics procurement leads, thermal management engineers, and DC busbar integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from FERC interconnection filings, EPA Energy Star certification databases, Open Compute Project technical specifications, and customs records for power semiconductor trade flows. Bottom-up shipment estimates by form factor and voltage tier triangulated against top-down hyperscale capex disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, end-user archetype, voltage architecture, and regional regulatory cluster. CAGRs derived from deployment schedule acceleration observed in Northern Virginia and Singapore facility buildouts. Forecast inputs incorporated silicon carbide adoption curves and evolving electrical code timelines for 400V DC fault protection.
Decision-makers should treat outputs as directional under assumptions of sustained EPA efficiency mandate enforcement and stable copper price regimes; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
United States Data Center Market