
 Singapore Data Center Rack Market | 2026-2036
Singapore Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Rack Market Insights
Buyer concentration among hyperscale cloud providers and colocation operators is pivoting toward a smaller set of anchor tenants commanding customized rack specifications. Schneider Electric leverages its integrated power and cooling architecture to dominate large-scale deployments. Vertiv sustains technology leadership in thermal-optimized rack systems for tropical climates. Eaton anchors its position through advanced power distribution units embedded within rack enclosures.
A data center rack is a standardized metal framework designed to house servers, networking equipment, and power infrastructure, typically measured in rack units with 42U and 48U configurations supporting loads exceeding 1,500 kilograms per cabinet. Its primary purpose is to enable efficient space utilization, cable management, and airflow optimization in high-density computing environments. Enclosed racks with integrated cooling channels capture premium positioning as thermal management grows critical in Singapore's equatorial climate. Open frame racks maintain volume leadership among hyperscale builders prioritizing cost efficiency and rapid deployment cycles. Wall-mounted and specialty rack categories occupy niche positions at the margin pool periphery.
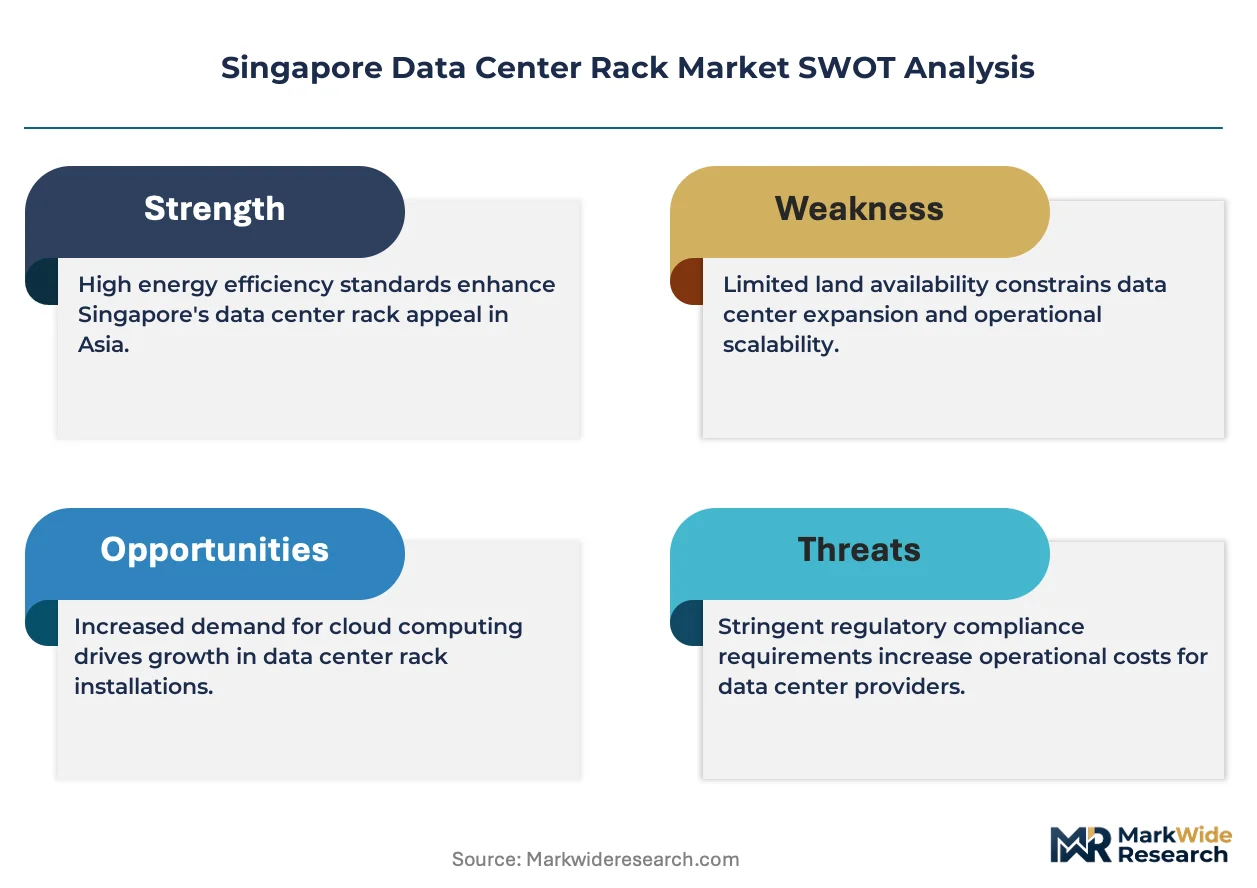
Singapore's Infocomm Media Development Authority imposes sustainability standards on data center developments, directly shaping rack efficiency requirements for power usage effectiveness and carbon intensity. The Building and Construction Authority's Green Mark certification extends to data center infrastructure, mandating materials and designs that reduce embodied carbon in rack manufacturing. BIS-equivalent structural standards govern load-bearing specifications and seismic resilience for equipment enclosures deployed in the region. Stakeholders must monitor how evolving energy efficiency regulations will redefine rack power density thresholds and cooling integration requirements.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and demanding rack configurations optimized for liquid cooling integration, forcing enclosure manufacturers to redesign thermal architectures around Singapore's tropical operating conditions.
Growth Catalysts
- IMDA Sustainability Standards:The Infocomm Media Development Authority's data center efficiency mandates are accelerating replacement cycles for legacy rack infrastructure across Jurong and Loyang facility clusters.
- Liquid Cooling Adoption:Direct-to-chip and immersion cooling technologies are penetrating high-performance computing deployments, requiring specialized rack enclosures with integrated coolant distribution manifolds.
- Hyperscale Buildouts:Anchor tenants in Singapore's digital infrastructure corridor are commissioning customized 48U and 52U configurations with load ratings exceeding 2,000 kilograms per cabinet.
Market Restraints
- Steel and Aluminum Volatility:Rack enclosure manufacturing faces margin pressure from fluctuating commodity metal prices, with cold-rolled steel representing 35-45% of bill-of-materials costs.
- Supply Concentration Risk:Precision sheet metal fabrication for high-load cabinets concentrates among a limited supplier base in Guangdong and Jiangsu provinces.
- Seismic Load Specifications:BIS-equivalent structural standards impose costly reinforcement requirements that open-frame rack designs struggle to meet without significant engineering redesign.
Strategic Opportunities
- Edge Computing Micro-Data Centers:Distributed infrastructure deployments across Singapore's industrial estates and logistics hubs are creating demand for compact 24U and wall-mounted rack configurations.
- Green Mark Certification Premium:The Building and Construction Authority's extended certification pathway rewards rack manufacturers with verified embodied carbon reduction in enclosure materials.
- Modular Integration:Convergence of power distribution, cooling, and monitoring systems into factory-integrated rack units is enabling higher-margin turnkey enclosure sales to colocation operators.
Industry Challenges
- Thermal Engineering Talent Scarcity:Computational fluid dynamics expertise for optimizing airflow in tropical high-density configurations remains concentrated among a small specialist workforce.
- Legacy Facility Retrofit Complexity:Existing data centers built for 8-10 kW per rack face structural and spatial constraints when upgrading to 30+ kW liquid-cooled configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Rack Market |
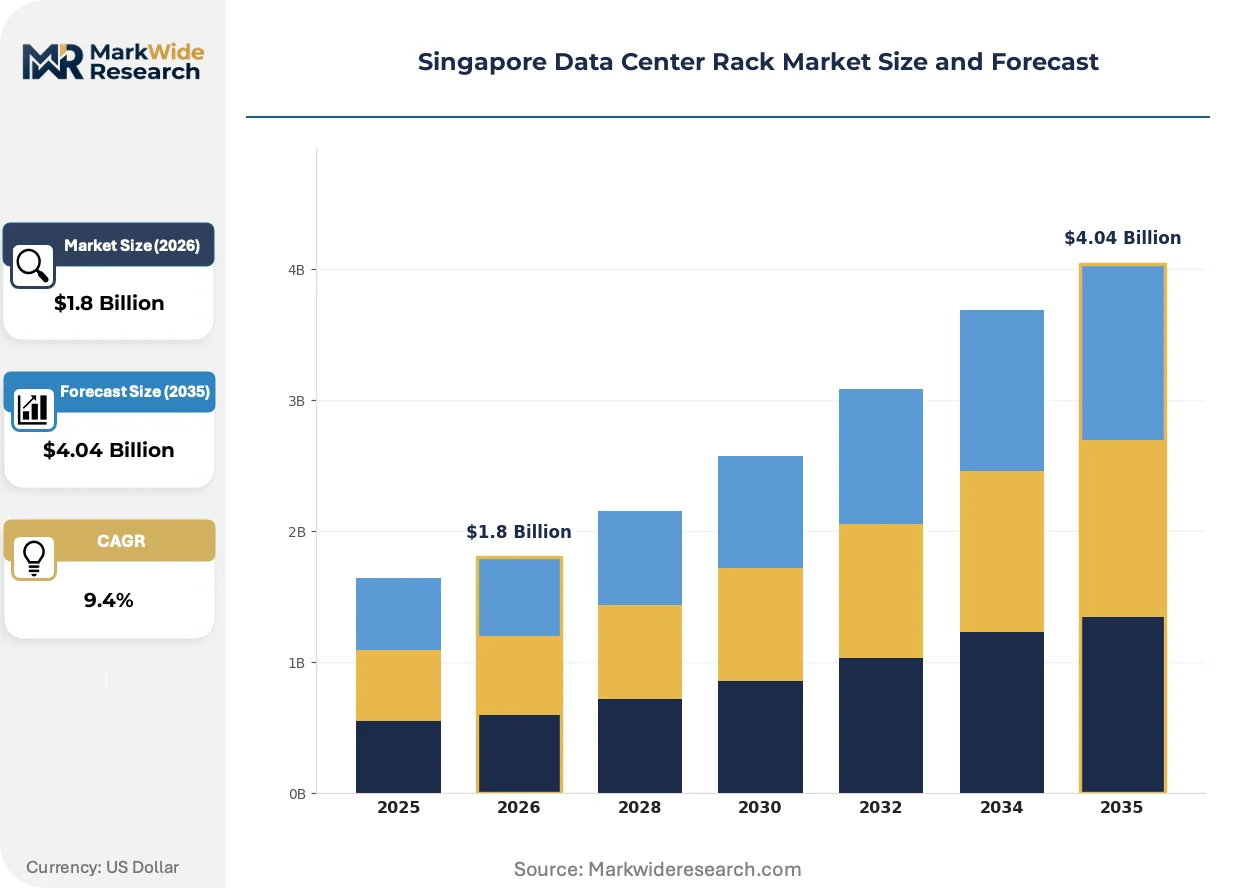
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mounted Racks, Specialty Racks End User: Telecommunications, BFSI, IT & Telecom, Healthcare Deployment: On-Premise, Colocation, Managed Hosting, Hybrid Size: 42U, 45U, 48U, 24U |
| Companies Covered | Schneider Electric, Vertiv, Eaton, Rittal, Panduit, Hewlett Packard Enterprise, Dell Inc, Black Box Corporation, ERS Industries Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Rack Market Trends and Innovations
Rack architecture is converging with power and cooling infrastructure as a single engineered system, eroding the historical separation between enclosure manufacturing and thermal management supply chains.
Immersion cooling tank integration into standard rack footprints is electrifying deployment timelines for artificial intelligence training clusters. Hyperscale operators in Singapore are specifying sealed bath enclosures with dielectric fluid circulation as baseline requirements for new GPU-intensive builds. This technology is electrifying competitive differentiation among enclosure suppliers capable of delivering certified fire-suppression and leak-detection systems as standard features.
The Building and Construction Authority's Green Mark for Data Centres is tightening embodied carbon thresholds for rack manufacturing materials and end-of-life recyclability. Facility developers now require Environmental Product Declarations for structural steel and aluminum components in enclosure bids. Colocation operators with sustainability-linked financing are prioritizing certified low-carbon rack suppliers in procurement evaluations.
Specification consolidation around hyperscale anchor tenants is compressing vendor diversity in Singapore's procurement pipeline. Large cloud providers are issuing master service agreements that lock in rack configurations, power densities, and thermal architectures for multi-year deployment waves. This concentration is most visible in the Jurong industrial zone where three major facility developments are standardizing on identical 48U liquid-cooling-ready specifications.
Singapore Data Center Rack Market Segmentation
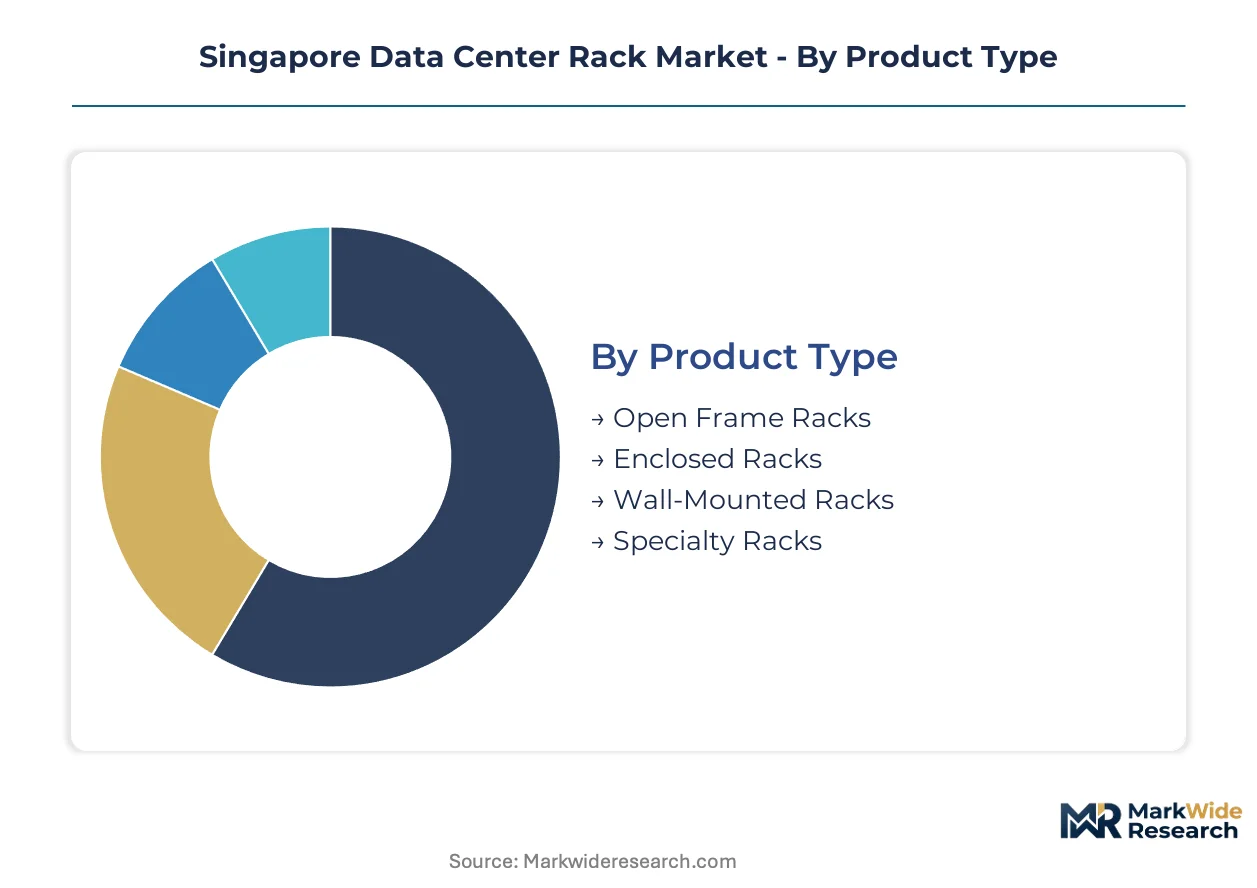
Singapore's data center rack segmentation reflects divergent procurement logics across facility types. Hyperscale operators prioritize thermal-optimized configurations for tropical deployment, while edge and enterprise segments demand compact form factors for constrained footprints.
Product Type:
Integration depth varies sharply: open frame racks function as standalone structural elements, while enclosed and specialty racks embed power distribution and cooling subsystems.
- Open Frame Racks:Four-post skeletal structures with minimal material overhead support rapid hyperscale deployment cycles. Demand concentrates in Jurong and Loyang facility clusters where cloud operators prioritize cost efficiency and airflow flexibility over environmental sealing.
- Enclosed Racks:Sealed metal cabinets with integrated cable management and thermal channels command premium positioning. The IMDA's sustainability standards are accelerating replacement of legacy open-frame infrastructure with enclosed units featuring certified power usage effectiveness ratings.
- Wall-Mounted Racks:Compact 12U-24U enclosures anchor distributed edge deployments across Singapore's industrial estates and logistics hubs.
- Specialty Racks:Custom-configured immersion cooling baths and seismic-reinforced cabinets serve high-performance computing and BIS-equivalent structural compliance requirements.
Open Frame Racks lead volumes today; Enclosed Racks is gaining share fastest.
End User:
Customer archetypes span capital-intensive infrastructure owners to service-dependent tenants, with procurement authority residing at different organizational levels.
- Telecommunications:National carriers and mobile network operators deploy 48U-52U configurations for core network equipment with stringent seismic resilience requirements. Singtel and StarHub facility expansions in Loyang are specifying liquid-cooling-ready enclosures for 5G core infrastructure.
- BFSI:Banks and insurers prioritize physically segregated rack configurations for regulatory compliance, with dedicated enclosed cabinets for payment processing and customer data workloads.
- IT & Telecom:Enterprise technology departments and cloud service providers represent the volume anchor, with procurement consolidating around standardized 42U and 48U specifications.
- Healthcare:Medical data centers and research institutions demand specialized racks for imaging equipment and clinical trial data infrastructure, with emphasis on electromagnetic interference shielding.
IT & Telecom leads volumes today; BFSI is expanding most quickly.
Deployment:
Operational model selection determines rack ownership, customization latitude, and refresh cycle timing.
- On-Premise:Enterprise-owned facilities in Singapore's central business district maintain legacy 42U configurations, facing structural constraints when upgrading to high-density liquid-cooled architectures.
- Colocation:Multi-tenant data center operators commission standardized rack specifications for lease to enterprise customers, with Keppel Data Centres and ST Telemedia Global Data Centres driving specification consolidation.
- Managed Hosting:Service providers bundle rack space with operational management, typically utilizing colocation facility infrastructure with limited rack-level customization.
- Hybrid:Architectures spanning on-premise and colocation footprints require rack consistency across environments, favoring modular 48U configurations with unified power and cooling interfaces.
Colocation leads volumes today; Hybrid is climbing the fastest.
Size:
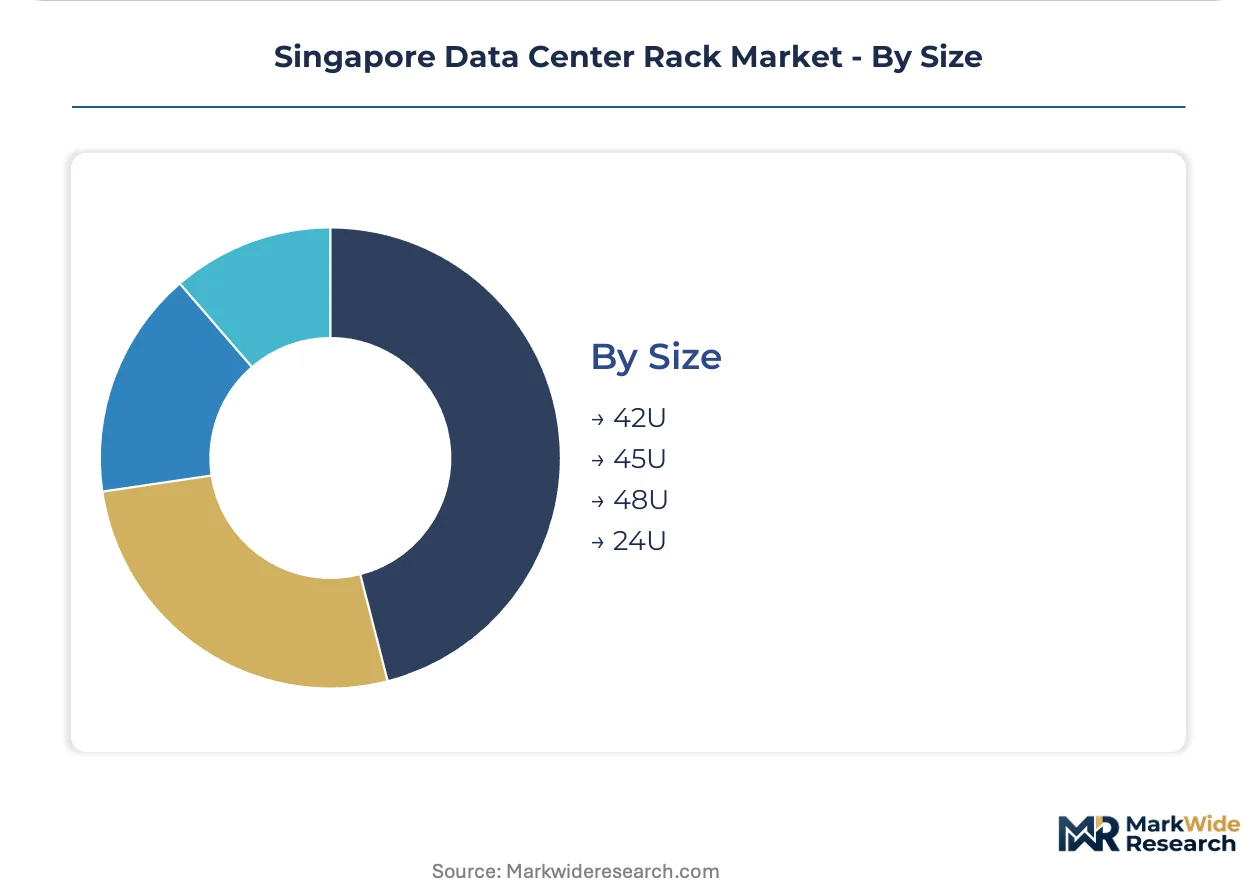
Rack height specifications encode power density ambition and facility ceiling constraints.
- 42U:The legacy standard dominates existing facility retrofits where raised floor depth and overhead cable tray positioning limit vertical expansion. Enterprise data centers in Singapore's central region maintain this specification for compatibility with installed server populations.
- 48U:Emerging hyperscale standard optimized for GPU-intensive workloads and liquid cooling integration. New Jurong facility developments from Microsoft, Google, and Amazon Web Services are standardizing on 48U with 2,000+ kilogram load ratings.
- 45U:Intermediate specification serving colocation operators balancing tenant flexibility against structural cost, with adoption concentrated in Loyang facility clusters.
- 24U:Compact form factor anchors edge computing micro-data centers and telecommunications equipment rooms across Singapore's industrial zones.
42U leads volumes today; 48U is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia attracts rack suppliers seeking lower-cost fabrication outside Singapore's premium zone, while Indonesia builds sovereign cloud capacity with localized enclosure sourcing. Both markets diverge from Singapore's high-density liquid-cooling trajectory.
Malaysia
Johor's Iskandar Puteri corridor hosts hyperscale facility developments from ByteDance and Microsoft, creating demand for 48U liquid-cooling-ready racks. The Malaysian Investment Development Authority's data center tax incentives accelerate foreign direct investment in enclosure manufacturing partnerships. Cyberjaya and Kulai maintain legacy enterprise demand for standard 42U configurations.
Indonesia
Batam's free trade zone proximity to Singapore enables cross-border rack assembly operations serving both markets. The Ministry of Communication and Informatics' data localization regulations mandate domestic cloud infrastructure, stimulating demand for enclosed cabinets with tropical thermal ratings. Jakarta's Cikarang industrial estate clusters new facility builds requiring seismic-reinforced specialty racks.
Thailand
Chonburi's Eastern Economic Corridor attracts Google and Amazon Web Services expansions specifying 52U high-load configurations. The Board of Investment's enhanced incentives for digital infrastructure target 30% local content in rack manufacturing supply chains. Bangkok's Thonburi district concentrates enterprise colocation operators transitioning from open-frame to enclosed thermal-optimized units.
Vietnam
Ho Chi Minh City's Thu Duc district hosts VNG and FPT Telecom facility expansions demanding 24U edge-computing racks for distributed architectures. The Ministry of Information and Communications' cloud-first government directive accelerates public sector procurement of BIS-equivalent certified enclosures. Bac Ninh province's industrial parks attract Chinese sheet metal fabricators serving regional rack demand.
Philippines
Cavite's Laguna Technopark anchors Facebook and Google hyperscale builds with standardized 48U specifications mirroring Singapore procurement patterns. The Department of Information and Communications Technology's National Broadband Plan mandates disaster-resilient data infrastructure, elevating seismic load requirements for rack enclosures. Manila's Makati CBD maintains financial services demand for physically segregated BFSI-compliant cabinet configurations.
Singapore Data Center Rack Market Competitive Landscape
European electrical engineering conglomerates anchor the premium tier; Asian metal fabrication specialists hold volume positions in standardized open-frame supply. Market structure concentrates around three strategic archetypes: integrated power-cooling-enclosure systems providers, precision sheet metal fabricators with thermal engineering capabilities, and regional contract manufacturers serving price-sensitive procurement. Competitive dynamics center on M&A activity consolidating cooling technology into enclosure portfolios, plus capacity expansion into Vietnam and Indonesia to bypass Singapore's cost base.
Within the integrated systems tier, Schneider Electric and Vertiv exemplify full-stack positioning spanning power distribution, thermal management, and rack enclosure engineering. Eaton occupies a distinct position through embedded power distribution specialization. Among Asia-Pacific fabricators, ERS Industries Pte Ltd represents Singapore-based precision metalwork capabilities serving regional hyperscale demand. Rittal anchors German engineering standards in tropical-climate deployments across Southeast Asian facility clusters.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Eaton |
| Rittal |
| Panduit |
| Hewlett Packard Enterprise |
| Dell Inc |
| Black Box Corporation |
| ERS Industries Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Sovereign wealth-backed industrial conglomerates and family-owned precision metalwork specialists anchor Singapore's rack supply base, concentrating fabrication expertise in Jurong and Loyang industrial zones while enforcing pricing discipline through long-term anchor tenant contracts with hyperscale cloud operators.
Pricing Analysis
Capacity additions in Guangdong and Jiangsu provinces are reshaping price floors for cold-rolled steel enclosures across Southeast Asian procurement pipelines. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooling-ready 48U configurations with IMDA sustainability certification from basic open-frame units and legacy 42U retrofits. Cost compression in standard open-frame tiers is intensifying because Chinese sheet metal fabricators are expanding capacity into Vietnam and Indonesia. Enterprise data centers in Singapore's central business district exhibit highest price sensitivity due to structural constraints limiting high-density upgrades, while hyperscale operators in Jurong prioritize thermal performance over unit cost.
Supply Chain Analysis
Precision sheet metal fabrication labor availability in Guangdong and Jiangsu provinces constrains output elasticity for high-load cabinet production serving Singapore's tropical climate specifications. Manufacturing gravity centers on Chinese cold-rolled steel processing, Malaysian aluminum extrusion, and Singapore-based final assembly with BIS-equivalent structural testing. Raw material dependencies encompass cold-rolled steel for structural frames, aluminum for thermal-optimized panels, and copper for embedded power distribution busbars. Single-source vulnerability concentrates in precision coolant distribution manifold machining for liquid-cooling-ready configurations. Distribution runs through direct master service agreements with hyperscale anchor tenants, bypassing traditional channel intermediaries for large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's data center rack market offers margin expansion pathways through premium-tier liquid-cooling integration and embodied carbon certification, as the Building and Construction Authority's Green Mark standards displace commodity open-frame procurement.
For Market Incumbents: Extend thermal engineering capabilities into sealed immersion cooling bath enclosures with integrated fire-suppression systems, defending against emerging Chinese fabricators with Vietnam-based cost positions. Deepen backward integration into precision coolant distribution manifold production to capture value migrating from standalone cooling suppliers. Prioritize IMDA sustainability certification investment to maintain specification lock-in with hyperscale anchor tenants issuing multi-year master service agreements. For New Entrants and Emerging Players: Begin with edge computing micro-data center configurations in Singapore's industrial estates, where 24U compact form factors face limited incumbent specialization and distributed logistics infrastructure creates service differentiation opportunities. Target telecommunications equipment room retrofits in Loyang with seismic-reinforced wall-mounted enclosures, leveraging Batam's free trade zone proximity for cross-border assembly cost advantages. Pursue direct contracting with national carriers specifying 5G core infrastructure liquid-cooling readiness as procurement entry point. For Investors and Strategic Acquirers: Valuations sit cheapest among precision sheet metal fabricators lacking thermal engineering capabilities but holding BIS-equivalent structural certification and established hyperscale supplier relationships. Five-to-ten year viability hinges on successful convergence with power distribution and cooling subsystem integration, displacing standalone enclosure manufacturing. Monitor IMDA data center sustainability standard threshold tightening as inflection indicator for replacement cycle acceleration and premium-tier specification capture.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration | Captures premium positioning as IMDA mandates displace legacy air-cooled infrastructure. |
| Green Mark Certification Investment | Unlocks sustainability-linked financing procurement from colocation operators with ESG commitments. |
| Precision Sheet Metal Fabrication Acquisition | Consolidates Guangdong and Jiangsu supplier base to secure high-load cabinet capacity. |
| Edge Computing Micro-Data Center Development | Addresses distributed infrastructure demand across Singapore's industrial estates and logistics hubs. |
| Immersive Cooling Tank Standardization | Accelerates GPU-intensive AI training cluster deployment timelines for hyperscale anchor tenants. |
Research Methodology
Direct dialogue with data center facility engineering directors, thermal infrastructure procurement managers, colocation operator leasing executives, and precision sheet metal fabrication plant managers grounded qualitative findings in operational reality. Secondary validation drew from IMDA sustainability standard filings, Building and Construction Authority Green Mark certification databases, hyperscaler capital expenditure disclosures, and regional customs trade data for cold-rolled steel and aluminum enclosure components. Bottom-up rack deployment estimates triangulated against top-down facility power capacity projections across the analysis window.
Segmentation outputs reflect modeled dimensions spanning enclosure type integration depth, end-user procurement authority, deployment operational model, and rack height specification encoding power density ambition. CAGRs derived from facility pipeline tracking in Jurong and Loyang clusters, replacement cycle acceleration assumptions tied to regulatory threshold evolution, and edge computing distributed infrastructure buildout trajectories. Tropical climate thermal performance degradation factors and seismic load specification compliance costs informed Singapore-specific forecast adjustments.
Several conditions sit outside the modeled scope, including abrupt commodity metal price shocks, geopolitical disruption to Chinese fabrication capacity, and unanticipated IMDA sustainability standard threshold revisions. Forecasts reflect documented assumptions regarding hyperscale anchor tenant procurement consolidation and liquid cooling technology penetration curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
China Data Center Storage Market