
 Advanced Driver Assistance System (ADAS) Sensor Market | 2026-2036
Advanced Driver Assistance System (ADAS) Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Driver Assistance System (ADAS) Sensor Market Outlook
A capital-intensity divergence between foundry-dependent fabless designers and vertically integrated tier-one suppliers is reorganizing competitive tiers in ADAS sensor supply. Robert Bosch GmbH leverages captive semiconductor fabrication and in-house MEMS production to sustain margin control across radar and camera modules. Continental AG competes through its integrated sensor-fusion software stack, while ZF Friedrichshafen AG anchors its position via chassis-system integration that bundles braking and steering with perception hardware.
Advanced Driver Assistance System sensors comprise electromagnetic and optical detection devices—specifically radar transceivers operating at 77 GHz, solid-state lidar emitters, CMOS image sensors with HDR capability beyond 120 dB, and ultrasonic transducers—that perceive vehicle surroundings and enable automated intervention. These components process real-time environmental data to execute collision avoidance, lane-keeping, and adaptive speed functions. Camera sensors dominate unit volume due to low cost and versatility in traffic-sign recognition and pedestrian detection, while lidar represents the fastest-expanding margin pool as robotaxi and Level 3 highway-autonomy programs demand high-resolution 3D point clouds. Radar maintains structural importance for all-weather reliability, particularly in adaptive cruise control where Doppler-based velocity measurement remains unmatched by optical alternatives.
The U.S. NHTSA mandates automatic emergency braking on new passenger vehicles, while Europe's ECE R152 and ECE R79 regulations enforce pedestrian protection and lane-keeping standards that directly specify sensor performance thresholds. Japan's METI coordinates SAE Level 3 deployment guidelines that influence sensor redundancy requirements for domestic OEMs. Stakeholders must monitor how divergent Chinese GB/T standards for connected-vehicle data fusion and EU AI Act risk-classification rules for autonomous decision-making reshape certification burdens and supplier qualification timelines.
Market Dynamics
Multi-sensor fusion architectures are compressing supplier margins as automakers consolidate procurement around integrated perception stacks rather than discrete component sourcing. This structural pressure favors tier-one suppliers with captive software development and in-house semiconductor fabrication.
Growth Catalysts
- ECE R79 mandate:Europe's lane-keeping regulation compels sensor installation across passenger and commercial vehicle fleets, creating baseline demand for camera and radar modules.
- Robotaxi deployment:Autonomous ride-hail programs in California, Arizona, and Texas are accelerating lidar unit volume through fleet-scale sensor retrofits.
- 77 GHz radar migration:Automakers are replacing legacy 24 GHz systems for improved range resolution, driving semiconductor content expansion in front-facing collision-avoidance modules.
Market Restraints
- Silicon photonics foundry concentration:Solid-state lidar production depends on specialized CMOS and MEMS fabrication capacity concentrated in Taiwan and South Korea, creating supply vulnerability.
- Automotive-grade qualification timelines:AEC-Q100 and ISO 26262 functional-safety certification cycles extend 18-24 months, delaying new entrant market entry.
- Ultrasonic substitution risk:Short-range radar and camera-based parking systems are eroding ultrasonic transducer attach rates in premium vehicle segments.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive electronics manufacturing are attracting sensor packaging and testing investments to Pune and Chennai industrial corridors.
- EU AI Act risk classification:Harmonized conformity assessment frameworks for autonomous decision-making systems may streamline multi-market certification for sensor-fusion software vendors.
- V2X infrastructure convergence:Integration of roadside unit communication with onboard perception is opening embedded sensor opportunities in smart highway deployments across Germany and the Netherlands.
Industry Challenges
- Functional-safety engineering scarcity:ISO 26262-certified systems architects and ASIL-D verification specialists command premium compensation, constraining R&D team scaling.
- Multi-domain integration complexity:Synchronizing radar, lidar, and camera data streams with chassis-control systems requires cross-functional expertise spanning perception algorithms and automotive embedded software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Driver Assistance System (ADAS) Sensor Market |
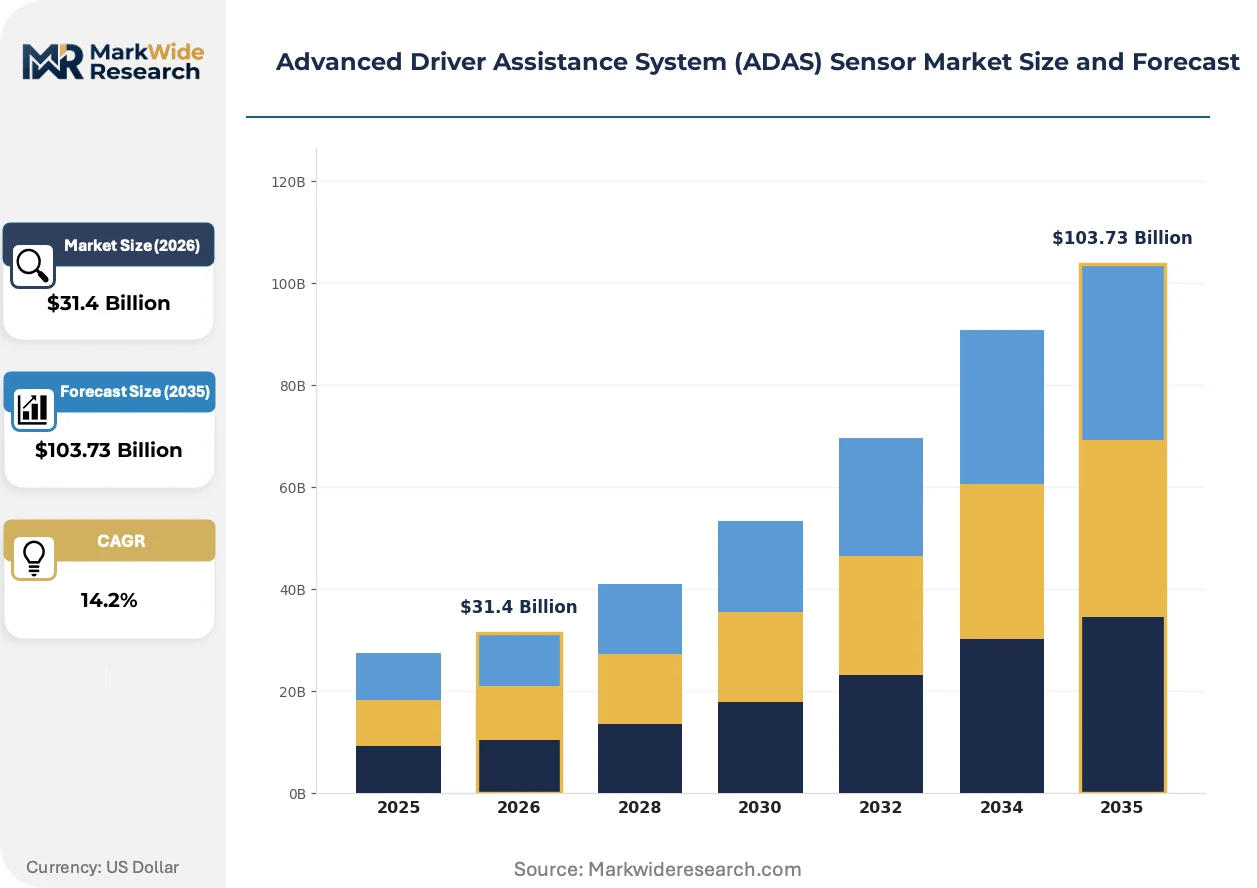
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $103.73 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Lidar, Radar, Camera, Ultrasonic Vehicle Type: Passenger Vehicle, Commercial Vehicle, Electric Vehicle, Autonomous Vehicle Technology: Image Processing, Sensor Fusion, Machine Learning, Computer Vision Functionality: Collision Avoidance, Lane Departure Warning, Adaptive Cruise Control, Parking Assistance |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Valeo SA, Magna International Inc., Texas Instruments Inc., Autoliv Inc., HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Driver Assistance System (ADAS) Sensor Market Strategic Shifts
Sensor hardware commoditization is forcing competitive differentiation toward software-defined perception and over-the-air calibration capabilities. Vendors are repositioning around data fusion IP and predictive maintenance analytics.
Solid-state lidar with MEMS beam-steering is supplanting mechanical spinning units in highway-autonomy programs. BMW and Mercedes-Benz production vehicles are adopting compact flash lidar modules for Level 3 conditional automation. This transition is collapsing unit cost curves and enabling roofline-integrated sensor packaging previously impossible with rotating hardware.
Europe's ECE R152 pedestrian-protection regulation is mandating nighttime detection performance thresholds that exceed legacy camera capabilities. OEMs are responding with thermal-imaging augmentation and higher-dynamic-range CMOS sensors. Premium German manufacturers are accelerating supplier qualification for fused visible-thermal perception stacks.
Fleet operators and mobility service providers are consolidating sensor procurement through long-term supply agreements with direct tier-one relationships. Traditional distributor channels are losing share in the commercial-vehicle segment. This concentration is most pronounced in North American trucking and last-mile delivery vehicle conversions.
Advanced Driver Assistance System (ADAS) Sensor Market Segmentation
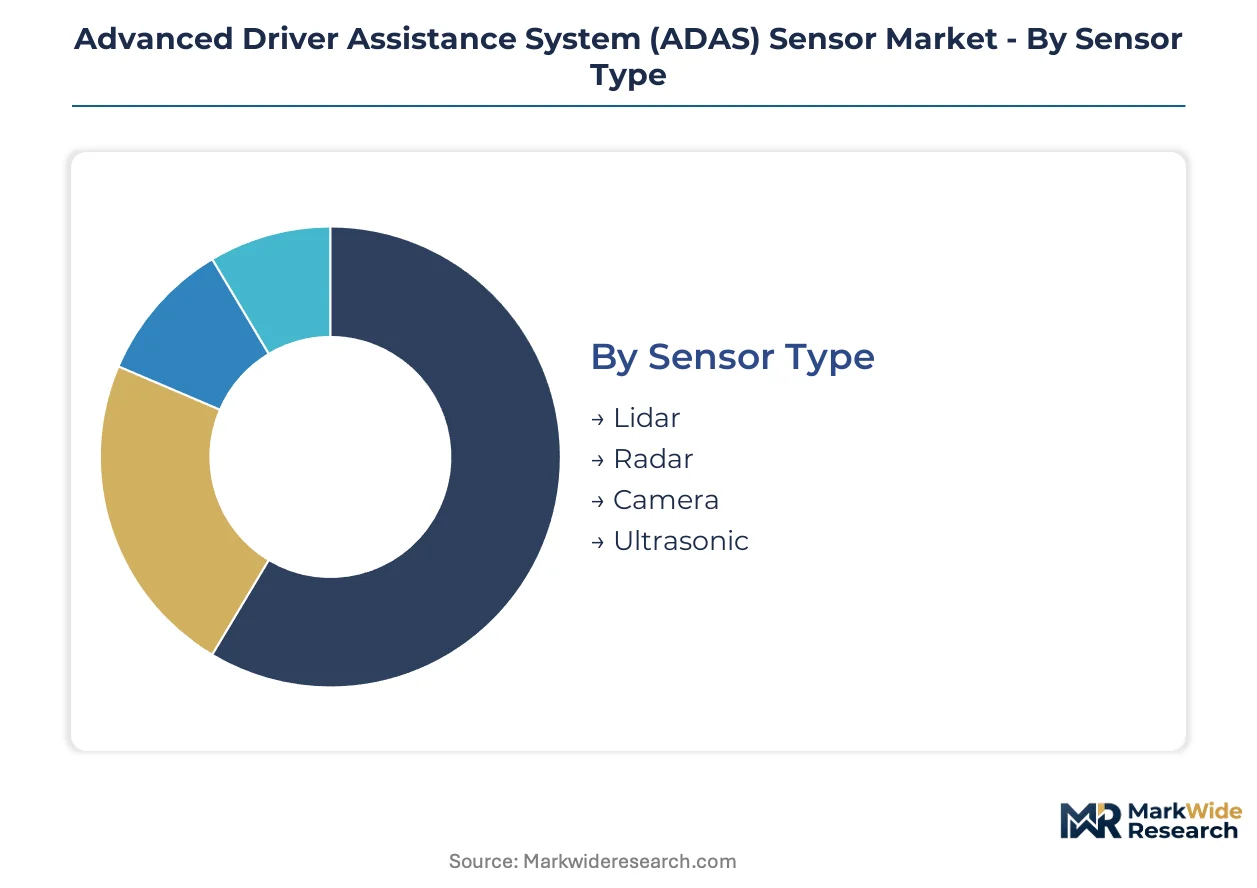
ADAS sensor procurement patterns diverge sharply across vehicle platforms and functional requirements. Automakers configure multi-sensor architectures differently for mass-market driver assistance versus autonomous fleet deployment, creating distinct margin pools and supplier qualification pathways.
Sensor Type:
Camera modules face the most acute substitution pressure as short-range radar and fused perception stacks encroach on traditional visibility-based functions.
- Camera:CMOS image sensors with HDR capability beyond 120 dB process visible-spectrum data for traffic-sign recognition and pedestrian detection. Demand concentrates in Germany where ECE R79 and ECE R152 mandates enforce lane-keeping and nighttime pedestrian protection standards that exceed legacy sensor performance.
- Radar:77 GHz transceivers deliver Doppler-based velocity measurement and all-weather reliability unmatched by optical alternatives. OEM demand from adaptive cruise control programs in Stuttgart and Ingolstadt production corridors sustains structural importance despite lidar encroachment in premium segments.
- Lidar:Solid-state emitters with MEMS beam-steering generate high-resolution 3D point clouds for Level 3 highway autonomy.
- Ultrasonic:Piezoelectric transducers for short-range parking assistance face declining attach rates as camera-based systems and short-range radar displace legacy hardware.
Camera sensors anchor the volume base while lidar gains share at the steepest rate.
Vehicle Type:
Cost tier stratification separates premium autonomous platforms from mass-market assisted driving configurations.
- Passenger Vehicle:High-volume production programs integrate multi-sensor suites across mid-range and premium trim levels. NHTSA automatic emergency braking mandates in the United States and ECE R152 pedestrian-protection rules in Europe standardize radar and camera content across light-vehicle fleets.
- Electric Vehicle:Battery-electric platforms from OEMs in Germany and California serve as technology incubators for consolidated sensor-fusion architectures. Silicon content per vehicle exceeds internal-combustion equivalents due to higher automation feature penetration and over-the-air calibration requirements.
- Commercial Vehicle:Heavy-duty trucking and last-mile delivery applications prioritize durability and long-range detection for highway platooning.
- Autonomous Vehicle:Robotaxi programs in Arizona, California, and Texas deploy redundant lidar-radar-camera stacks with hardware diversity requirements exceeding passenger-vehicle standards.
Passenger vehicles generate the highest absolute unit demand while electric vehicle platforms expand the fastest.
Technology:
Application maturity separates production-proven perception stacks from emerging algorithmic approaches.
- Sensor Fusion:Real-time integration of radar, lidar, and camera data streams enables cross-modal validation for safety-critical functions. Continental AG and tier-one suppliers compete through proprietary fusion software stacks that bundle hardware with embedded perception IP.
- Computer Vision:Edge-based image processing for object classification and lane detection dominates traffic-sign recognition applications. Bosch leverages in-house semiconductor fabrication to optimize CMOS sensor and processing module integration.
- Machine Learning:Neural network inference for predictive collision detection and path planning.
- Image Processing:HDR enhancement and noise reduction algorithms for adverse lighting conditions.
Sensor fusion anchors current production architectures while machine learning climbs the fastest.
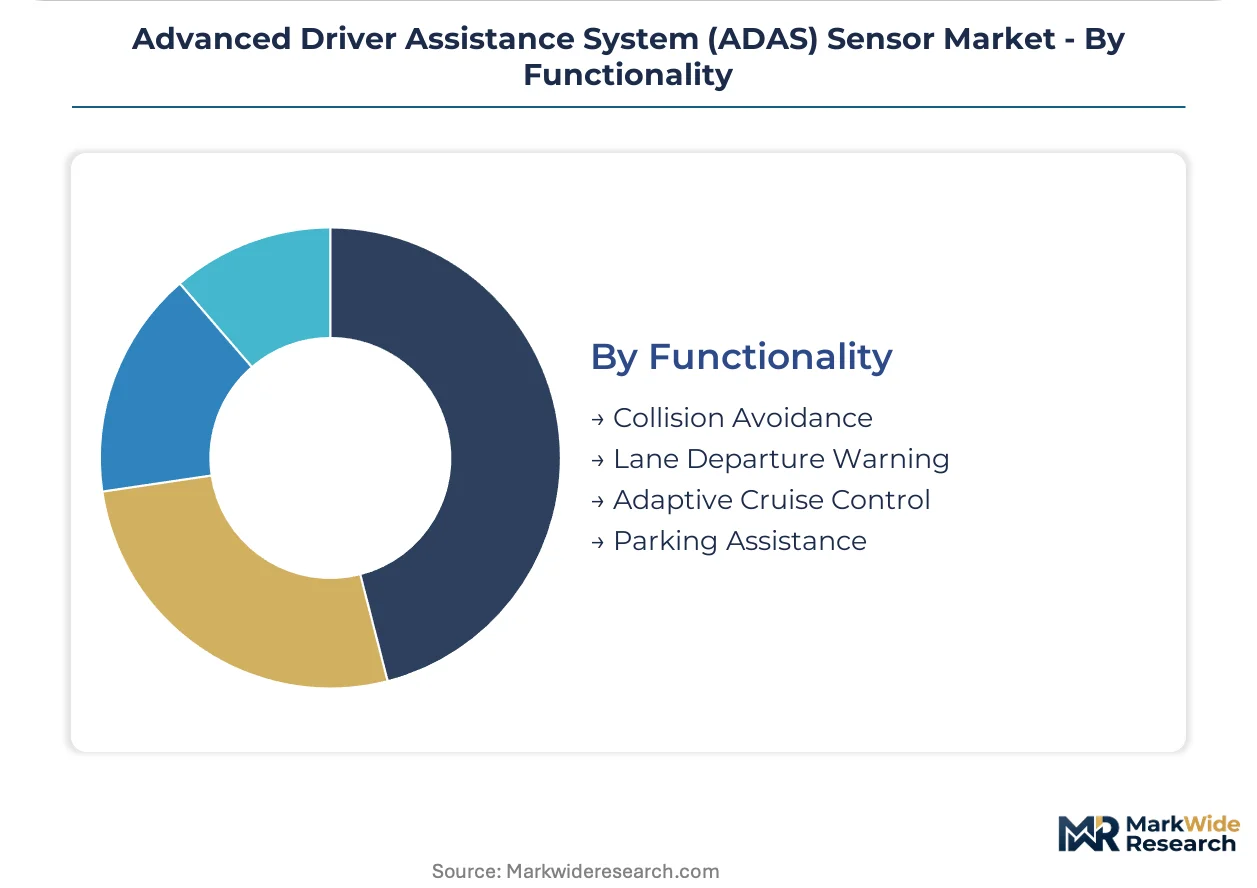
Functionality:
Customer type segmentation separates fleet-operator procurement from retail consumer feature preferences.
- Collision Avoidance:Automatic emergency braking and forward-collision warning systems mandate radar and camera hardware across vehicle classes. NHTSA regulations in the United States and ECE R152 in Europe specify minimum sensor performance thresholds that standardize module specifications.
- Adaptive Cruise Control:Doppler radar maintains velocity and distance control in highway environments where optical sensors degrade in precipitation. 77 GHz migration from legacy 24 GHz systems expands semiconductor content per module.
- Lane Departure Warning:Camera-based edge detection for unintended drift alerts.
- Parking Assistance:Ultrasonic and camera-based proximity detection for automated maneuvering.
Collision avoidance anchors regulatory-mandated installations while parking assistance faces the steepest technology substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Stuttgart production corridor while cost-sensitive procurement in India's Pune industrial belt compresses margins for standard sensor modules. This asymmetry is reshaping supplier qualification pathways across the analysis window.
United States
NHTSA automatic emergency braking mandates and robotaxi fleet deployments in Arizona and California anchor sensor demand. Federal Motor Vehicle Safety Standards enforcement compels radar and camera installation across light-vehicle production. Detroit's automotive engineering base sustains tier-one supplier engineering centers for perception-stack development.
Germany
ECE R79 lane-keeping and ECE R152 pedestrian-protection regulations from KBA enforcement drive premium sensor specifications. Bosch, Continental, and ZF anchor a dense supplier ecosystem around Stuttgart and Ingolstadt. Production corridors in Baden-Württemberg and Bavaria concentrate captive semiconductor fabrication and MEMS production capacity.
China
GB/T connected-vehicle data fusion standards and dual carbon goals accelerate electric vehicle platform sensor integration. MIIT coordination of SAE Level 3 deployment guidelines influences redundancy requirements for domestic OEMs. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province concentrate lidar assembly and testing operations.
Japan
METI guidelines for SAE Level 3 highway automation shape sensor redundancy mandates for domestic manufacturers. JIS standards for automotive electronics qualification create certification barriers for foreign component suppliers. Nagoya's Chubu industrial region hosts Denso engineering centers for radar and camera fusion development.
India
PLI scheme production-linked incentives for automotive electronics attract sensor packaging investments to Pune and Chennai corridors. BIS certification requirements for automotive components extend qualification timelines for module suppliers. Tamil Nadu's Sriperumbudur industrial belt emerges as a testing and calibration hub for export-oriented sensor production.
Advanced Driver Assistance System (ADAS) Sensor Market Competitive Environment
Concentration sits with vertically integrated tier-one suppliers possessing captive semiconductor fabrication and in-house MEMS production. The vendor base stratifies across three archetypes: diversified automotive conglomerates with chassis-system integration capabilities, fabless sensor designers dependent on Taiwan and South Korea foundry capacity, and specialized lidar pure-plays commercializing solid-state architectures. Dominant competitive moves include backward integration into semiconductor fabrication and strategic partnerships for sensor-fusion software licensing.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated-tier archetype through captive production capabilities and embedded software stacks. ZF Friedrichshafen AG occupies a distinct position bundling perception hardware with chassis-control systems. These three entities represent the structural core around which fabless designers and lidar specialists orbit.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Valeo SA |
| Magna International Inc. |
| Texas Instruments Inc. |
| Autoliv Inc. |
| HELLA GmbH & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month AEC-Q100 and ISO 26262 qualification cycles concentrate pricing power with incumbent tier-one suppliers possessing captive semiconductor fabrication in Germany and established foundry partnerships in Taiwan. This lead-time structure rewards strategic inventory positioning and penalizes spot-market procurement for safety-critical sensor modules.
Pricing Analysis
The customization-premium spread widens significantly between standard 77 GHz radar modules and configured-to-order multi-sensor fusion stacks with embedded perception software. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive-grade modules from industrial-tier alternatives and consumer-electronics derivatives. Cost compression in standard camera modules intensifies as short-range radar encroaches on parking-assistance functions. Fleet operators and mobility service providers exhibit the lowest price sensitivity due to total-cost-of-ownership calculations, while mass-market OEM procurement teams in India drive aggressive negotiations for commodity sensor content.
Supply Chain Analysis
Strategic stockpiling of automotive-grade CMOS wafers and MEMS substrates dominates tier-one procurement behavior, contrasting with just-in-time component flows for non-critical ultrasonic transducers. Semiconductor fabrication concentrates in Taiwan, South Korea, and Germany, while sensor module assembly clusters in China's Yangtze River Delta, Mexico's Baja California corridor, and India's Pune industrial belt. Raw material dependencies include silicon carbide substrates, indium gallium arsenide photodetectors, and specialized automotive-grade epoxy molding compounds. Single-source vulnerability in solid-state lidar MEMS foundry capacity creates supply interruption exposure. Distribution runs through direct OEM-tier-one contracts with diminishing distributor channel relevance in commercial-vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 26262-certified systems architects and ASIL-D verification specialists command compensation premiums that constrain R&D team scaling across the competitive landscape. This talent scarcity amplifies returns for organizations possessing functional-safety engineering depth.
For Market Incumbents: Fortify captive semiconductor fabrication capacity and in-house MEMS production to defend margin control against fabless designers dependent on Taiwan and South Korea foundry access. Accelerate sensor-fusion software stack development to capture automaker procurement consolidation around integrated perception platforms rather than discrete component sourcing. Prioritize certification investment for ECE R152 nighttime pedestrian-detection thresholds and EU AI Act autonomous-decision risk classification. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors around Pune and Chennai for sensor packaging and testing investments serving export-oriented production. Target the ultrasonic substitution gap where short-range radar and camera-based parking systems displace legacy piezoelectric transducers in premium vehicle segments. Pursue qualification partnerships with German tier-one suppliers seeking second-source diversification for 77 GHz radar modules. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because multi-sensor fusion architectures compress supplier margins and favor vertically integrated tier-one suppliers with embedded software IP. Target acquisition profiles should emphasize fabless lidar pure-plays commercializing solid-state MEMS beam-steering architectures and sensor-fusion software vendors with automotive-grade certification pipelines. The signal to watch is robotaxi fleet deployment scale in Arizona, California, and Texas as an inflection indicator for lidar unit volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive wafer production at Bosch's Reutlingen facility insulates margin control from foundry pricing volatility. |
| Sensor-Fusion Software Stack Development | Continental's proprietary perception IP bundles hardware with embedded algorithms for automaker consolidation. |
| Solid-State Lidar Platform Standardization | BMW and Mercedes-Benz production adoption validates MEMS beam-steering for Level 3 highway autonomy programs. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme attracts sensor testing investments to Tamil Nadu's Sriperumbudur industrial belt. |
| Functional-Safety Certification Acceleration | ASIL-D verification pipelines streamline ECE R79 and ECE R152 compliance for European OEM qualification. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor foundry account managers; and secondary validation through vehicle production databases, IHS Markit registration data, SEC 10-K automotive segment disclosures, and NHTSA FMVSS enforcement records. Bottom-up sensor unit demand modeling triangulated against top-down ADAS content-per-vehicle estimates across passenger, electric, commercial, and autonomous vehicle platforms.
Across the projection horizon, the analytical framework modeled demand across sensor type, vehicle platform, technology maturity, and functional application dimensions. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate enforcement timelines and OEM platform refresh cycles. Industry-specific forecast inputs included 77 GHz radar migration velocity, solid-state lidar cost-curve collapse trajectories, and ultrasonic transducer attach-rate erosion patterns.
Material uncertainties — silicon photonics foundry capacity constraints, divergent Chinese GB/T and EU AI Act certification burden evolution, and robotaxi fleet deployment scale variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM platform consolidation timelines. Revision becomes warranted when ECE R79 or NHTSA mandate scope expansion crosses thresholds that alter baseline sensor attach-rate assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
EGR Coolers Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Sideloaders Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Motor Monitoring Market