
 Vehicle Air Deflector Market | 2026-2036
Vehicle Air Deflector Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Air Deflector Market Analytics
The EU Green Deal is pivoting commercial vehicle aerodynamics toward mandatory efficiency benchmarks. Magna International Inc leverages its tier-one OEM relationships to embed deflectors into factory truck configurations. Röchling SE & Co. KG anchors its position through deep polymer processing expertise across European commercial vehicle platforms. Lund International competes aggressively in the North American aftermarket with broad distribution coverage.
Vehicle air deflectors are aerodynamic appendages—typically molded from acrylic, polycarbonate, or extruded aluminum—mounted to frontal, roof, side, or rear surfaces to reduce drag coefficient and stabilize airflow around commercial and passenger vehicles. Front air deflectors dominate OEM fitment programs due to their direct impact on highway fuel economy metrics, while roof variants on long-haul trucks command premium pricing tied to fleet operating cost reductions. Polycarbonate segments gain share where impact resistance and weight reduction outweigh acrylic cost advantages in severe-duty applications.
EPA greenhouse gas regulations for medium- and heavy-duty trucks mandate aerodynamic device integration or equivalent fuel consumption offsets, while ECE R29 and related EU type-approval frameworks enforce structural and performance standards for external vehicle attachments. The EU F-Gas Regulation indirectly shapes material selection by pressuring manufacturers toward lower-emission production chemistries in polymer supply chains. Stakeholders must monitor evolving border-adjustment mechanisms and material certification requirements that will determine competitive access across North American and European fleet procurement channels.
Market Dynamics
EPA greenhouse gas standards and EU CO2 emission targets for heavy-duty vehicles are compressing fleet procurement timelines, forcing immediate aerodynamic retrofit commitments rather than gradual adoption curves. This regulatory compression is restructuring supplier-OEM relationships and aftermarket channel priorities.
Growth Catalysts
- EPA Phase 2 Standards:Mandated fuel efficiency improvements for medium- and heavy-duty trucks are accelerating factory-fit deflector installations as OEMs seek compliant baseline configurations.
- Long-haul fleet economics:Diesel price volatility across North American corridors is amplifying payback calculations for roof-mounted deflector systems on Class 8 tractors.
- Polycarbonate material advances:Impact-resistant polymer formulations are displacing acrylic in severe-duty mining and construction vehicle applications where debris strike frequency is elevated.
Market Restraints
- Aluminum sheet volatility:Extruded aluminum deflector producers face margin compression from LME price swings and energy-intensive smelting cost structures.
- East Asian polymer concentration:Polycarbonate resin supply chains cluster around South Korean and Chinese petrochemical complexes, exposing European fabricators to shipping rate spikes and tariff uncertainty.
- Aerodynamic testing bottlenecks:Wind tunnel validation capacity at certified facilities is constraining new product introduction cycles for aftermarket specialists.
Strategic Opportunities
- Electric truck integration:Battery-electric Class 8 platforms from manufacturers like Tesla and Daimler require redesigned airflow management around thermal management systems and reduced drag coefficients for range extension.
- EU Green Deal procurement incentives:Member state fleet renewal programs are attaching aerodynamic performance bonuses to vehicle purchase subsidies, creating direct demand pull for premium deflector packages.
- 3D-printed bracket systems:Additive manufacturing of mounting hardware is collapsing tooling costs for low-volume specialty vehicle applications and custom fleet specifications.
Industry Challenges
- Computational fluid dynamics talent scarcity:Vehicle aerodynamics simulation expertise is concentrating at tier-one suppliers and major OEMs, limiting independent deflector developers' optimization capabilities.
- ECE R29 homologation complexity:EU type-approval for external vehicle attachments requires structural integrity testing that extends product development timelines by 8-14 months for new form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Air Deflector Market |
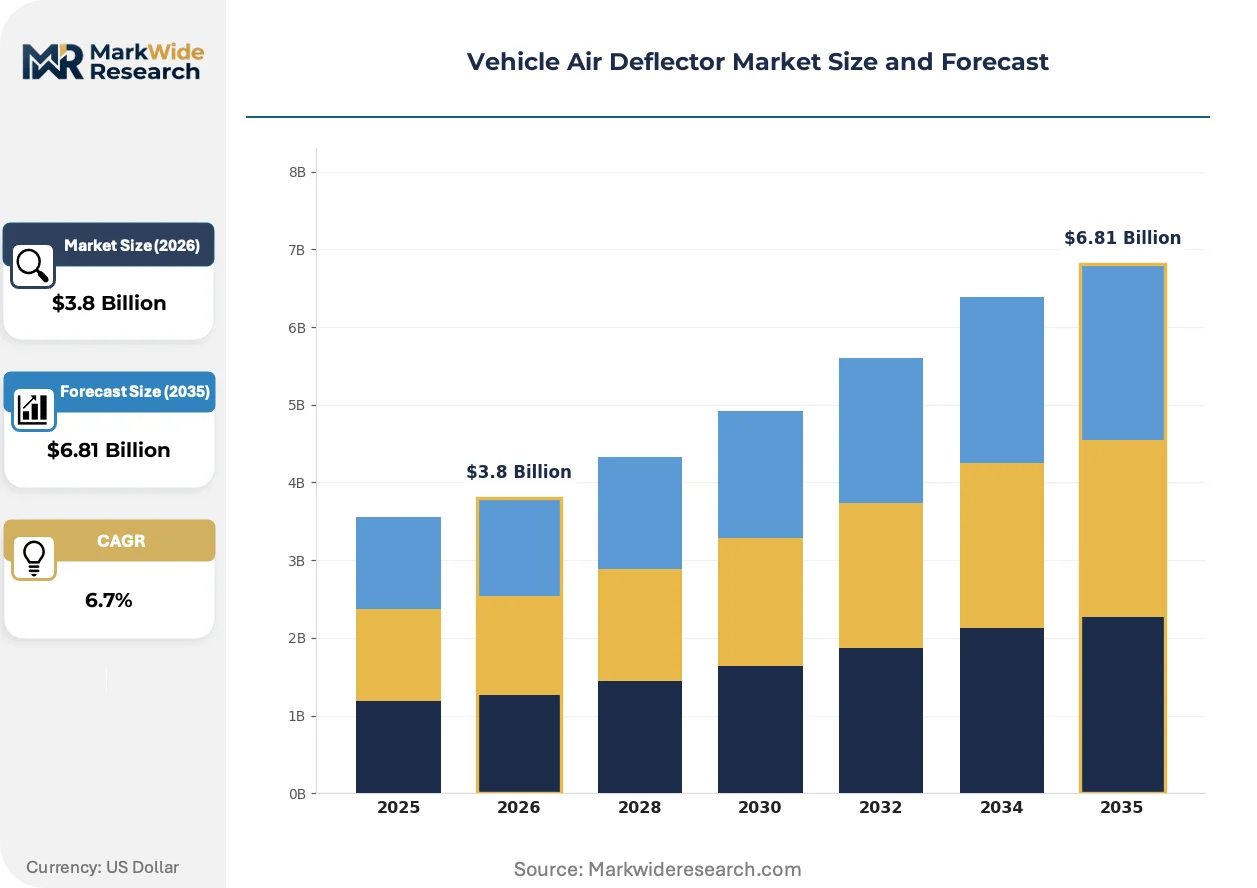
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Air Deflectors, Side Air Deflectors, Roof Air Deflectors, Rear Air Deflectors Material: Acrylic, Polycarbonate, Aluminum, PVC Installation Type: Adhesive Mount, Bolt-On, Clip-On, In-Channel Vehicle Type: SUVs, Trucks, Sedans, Vans |
| Companies Covered | Magna International Inc, Röchling SE & Co. KG, Lund International, Climair UK Ltd, Peterburg Industrial & Design Co. Ltd, HEKO Group, Stampede Automotive Accessories, Piedmont Plastics Inc, Airodyne Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Air Deflector Market Evolving Landscape
Active grille shutter systems and integrated airflow management modules are converging with standalone deflector products, blurring traditional category boundaries. This convergence is reshaping how fleets specify aerodynamic packages and how suppliers position their offerings.
Shape-memory polymer deflectors are expanding into adaptive aerodynamic applications where real-time profile adjustment responds to vehicle speed and load conditions. German commercial vehicle fleets are piloting these systems on refrigerated trailers where drag reduction must balance with refrigeration unit airflow requirements. The technology is expanding into premium long-haul specifications as total cost of ownership models justify higher acquisition prices against fuel savings.
EU F-Gas Regulation amendments are pressuring polymer processors toward lower-GWP blowing agents and production chemistries in polycarbonate and acrylic supply chains. Deflector manufacturers sourcing European-sourced sheet stock must now certify material provenance and production emission profiles to maintain fleet procurement eligibility. German and French transport authorities are incorporating these material credentials into green procurement scoring systems for public fleet tenders.
Fleet maintenance departments are consolidating aerodynamic device specifications under centralized procurement functions, displacing decentralized dealer-channel purchasing that dominated aftermarket retrofits. Large North American trucking operators are negotiating direct supply agreements with deflector manufacturers, bypassing traditional parts distribution networks. This consolidation is most visible among 500-plus unit fleets operating dedicated lanes between Chicago, Dallas, and Southern California distribution corridors.
Vehicle Air Deflector Market Segmentation
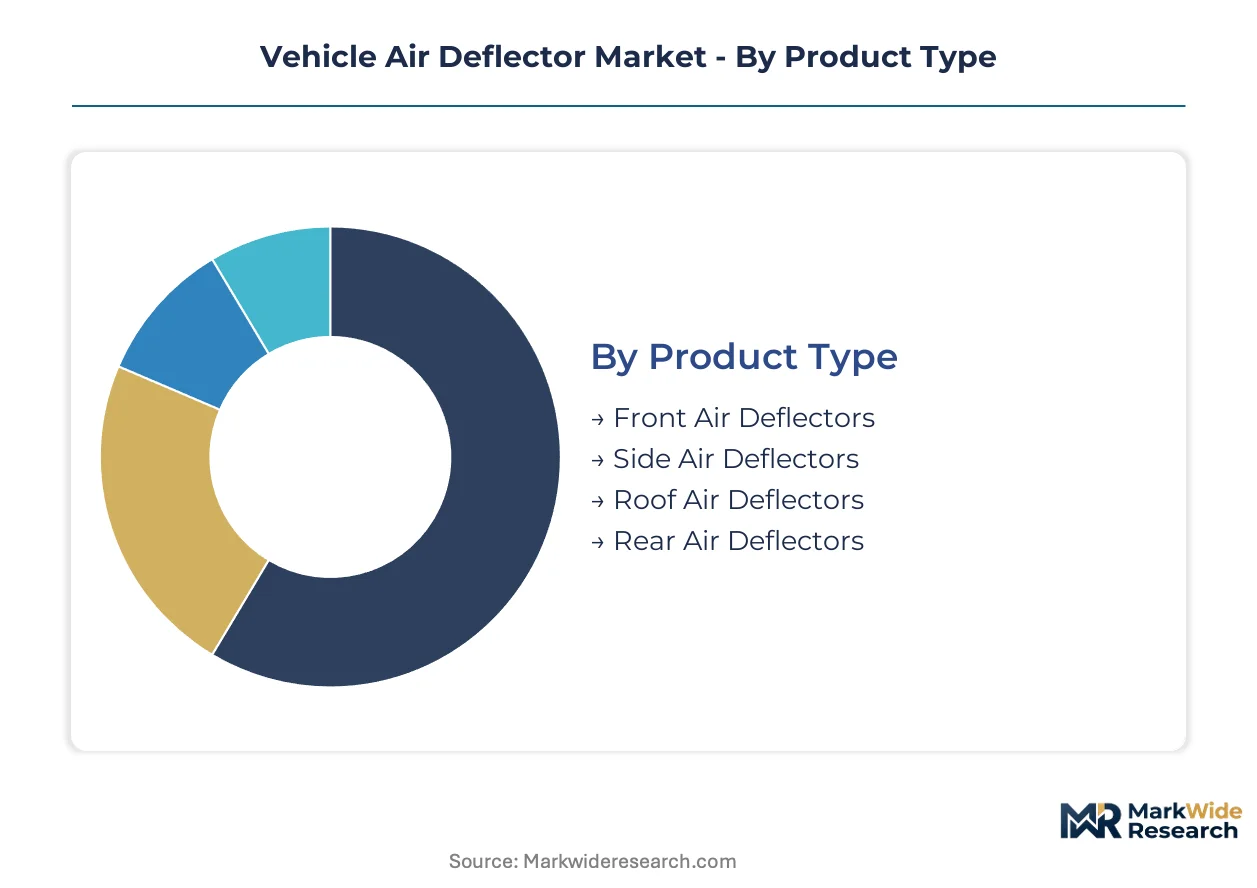
Segmentation in the vehicle air deflector market reflects divergent procurement logics across OEM factory-fit programs and aftermarket retrofit channels. Material selection, mounting methodology, and vehicle platform compatibility each create distinct competitive arenas with separate margin structures and technical qualification requirements.
Product Type:
Upgrade cycles for aerodynamic packages follow EPA compliance timelines and fleet renewal schedules, with replacement decisions tied to tractor-trailer combinations rather than standalone component failure.
- Front Air Deflectors:Molded polymer or aluminum assemblies mounted to hood leading edges to redirect airflow over windshields and reduce bug accumulation. OEM fitment concentrates on Class 8 tractors from Freightliner and Peterbilt assembly plants in the United States, driven by factory-standard aerodynamic packages meeting EPA Phase 2 baseline configurations.
- Roof Air Deflectors:Cab-top fairings engineered to smooth the tractor-trailer gap and reduce pressure drag at highway speeds. Long-haul fleets operating Dallas-to-Chicago corridors specify premium polycarbonate variants where fuel savings amortize higher acquisition costs within eighteen-month payback windows.
- Side Air Deflectors:Cab extenders and fairing panels managing airflow along tractor sides.
- Rear Air Deflectors:Trailer tail and boat-tail assemblies reducing wake turbulence drag.
Front air deflectors sit at the top of the volume ranking, with roof air deflectors climbing the fastest as fleet operators prioritize highway fuel economy metrics.
Material:
Cost tiers separate commodity-grade options from performance-specified materials where impact resistance and weight reduction justify procurement premiums.
- Polycarbonate:Thermoplastic polymer formulations offering superior impact resistance and temperature stability versus acrylic alternatives. Severe-duty mining fleets in Western Australia specify polycarbonate deflectors where flying debris strike frequency demands fracture-resistant performance.
- Acrylic:Cast or extruded polymer sheet providing optical clarity and UV resistance at lower unit cost. Aftermarket retrofit channels in Germany favor acrylic for passenger car applications where aesthetic transparency and price sensitivity dominate purchasing decisions.
- Aluminum:Extruded and formed sheet metal constructions.
- PVC:Thermoplastic polymer for cost-sensitive volume applications.
Acrylic commands the highest shipment volumes through aftermarket distribution, while polycarbonate gains share fastest in commercial vehicle OEM specifications.
Installation Type:
Mounting methodology determines channel access, with factory integration favoring permanent attachment systems and retail aftermarket gravitating toward reversible installation.
- Bolt-On:Mechanical fastening through pre-drilled brackets and threaded hardware. OEM assembly lines in Detroit and Stuttgart specify bolt-on architectures for roof deflector integration, ensuring structural integrity under ECE R29 homologation requirements for external vehicle attachments.
- Adhesive Mount:Pressure-sensitive bonding systems eliminating drilling and preserving vehicle finish. Japanese passenger car aftermarket distributors promote adhesive front deflectors where lease-return penalties discourage permanent modification.
- Clip-On:Friction-fit attachment without tools or permanent alteration.
- In-Channel:Window-channel mounting for side deflector applications.
Bolt-on installation dominates factory-fit volume, with adhesive mount systems expanding most quickly in lease-fleet and rental vehicle aftermarket channels.
Vehicle Type:
Platform-specific aerodynamic requirements create divergent specification standards across light-duty passenger and heavy-duty commercial segments.
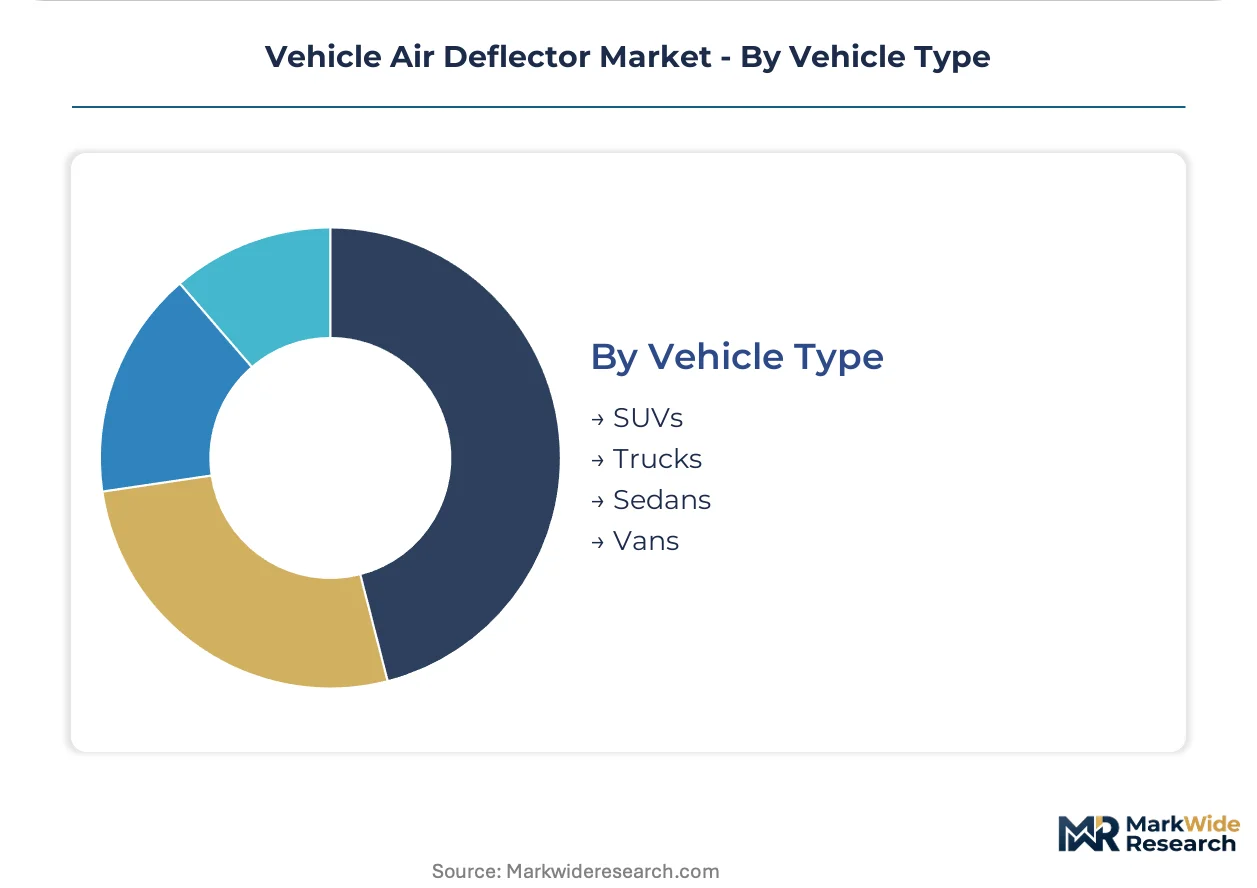
- Trucks:Class 8 tractors and commercial vehicles where roof and side deflector packages deliver measurable fuel consumption reductions. United States long-haul operators running 500-plus unit fleets negotiate direct supply agreements bypassing traditional parts distribution networks.
- SUVs:Light truck platforms with elevated rooflines benefiting from hood deflectors and side window visors. Aftermarket accessory retailers in Canada stock SUV-specific deflector kits where owner customization rates exceed sedan segments.
- Sedans:Passenger car platforms with limited deflector applicability.
- Vans:Commercial and passenger van configurations.
Trucks generate the highest absolute segment volume, with SUVs demonstrating the steepest expansion trajectory as crossover platform proliferation extends addressable market scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vehicle air deflector industry traces its commercial origins to post-war German automotive engineering, where cab-over-engine truck designs first integrated aerodynamic fairings for Autobahn efficiency. American long-haul operators adopted and scaled these concepts during the 1970s fuel crises, establishing the dual-hemisphere pattern of innovation and fleet deployment visible today.
United States
Class 8 tractor production in Michigan and Tennessee drives OEM fitment demand, with Freightliner and Peterbilt assembly plants specifying factory-standard deflector packages. EPA Phase 2 greenhouse gas standards mandate aerodynamic device integration for compliance baselines. Dallas-to-Chicago freight corridors concentrate fleet retrofit activity where 500-plus unit operators negotiate direct supply agreements.
Germany
Commercial vehicle OEMs in Stuttgart and Munich embed roof deflectors into factory configurations meeting EU CO2 emission targets for heavy-duty trucks. The EU Green Deal attaches aerodynamic performance bonuses to fleet renewal subsidies. KBA type-approval requirements for external vehicle attachments shape product development timelines for polycarbonate and aluminum variants.
Japan
Domestic truck manufacturers in Kanto integrate front deflectors into highway tractor specifications governed by METI fuel efficiency benchmarks. Adhesive-mount aftermarket systems dominate lease-fleet channels where permanent modification triggers return penalties. Nagoya-based polymer processors supply impact-resistant formulations for severe-duty construction applications.
China
MIIT fuel consumption standards for heavy-duty commercial vehicles accelerate domestic deflector adoption across state-owned fleet operators. Yangtze River Delta manufacturing clusters produce extruded aluminum and polycarbonate sheet for regional OEM integration. GB standards for external vehicle attachments establish structural testing protocols parallel to ECE R29 frameworks.
Canada
SUV and light truck accessory retailers in Ontario stock vehicle-specific deflector kits where owner customization rates exceed US averages. Health Canada and PMRA environmental guidelines influence polymer selection in aftermarket channels. Pacific Northwest cross-border freight corridors sustain demand for roof deflector retrofits on US-registered tractors operating Canadian lanes.
Vehicle Air Deflector Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models. Integrated polymer processors and extruded aluminum fabricators operate capital-intensive facilities with captive raw material conversion, while specialized assemblers source sheet stock and mounting hardware through distributed supply networks. The vendor base stratifies into three archetypes: tier-one OEM integrators with factory-fit programs, regional aftermarket distributors with broad SKU coverage, and niche specialists serving severe-duty mining and construction segments. Competitive dynamics center on strategic partnerships with commercial vehicle manufacturers and geographic expansion into fleet procurement corridors.
Among North American-based suppliers, Magna International Inc and Lund International occupy positions spanning OEM integration and aftermarket distribution. Magna leverages tier-one relationships with Detroit-area truck manufacturers for factory-fit program participation. Lund competes through broad distribution coverage across independent parts channels. European fabricators concentrate around polymer processing expertise, with Röchling SE & Co. KG representing the integrated processor archetype through deep involvement in commercial vehicle platform engineering. These three companies exemplify the geographic and functional segmentation defining competitive positioning across Atlantic basin markets.
| Leading Market Players |
|---|
| Magna International Inc |
| Röchling SE & Co. KG |
| Lund International |
| Climair UK Ltd |
| Peterburg Industrial & Design Co. Ltd |
| HEKO Group |
| Stampede Automotive Accessories |
| Piedmont Plastics Inc |
| Airodyne Industries Inc |
| Others |
Value Network & Pricing Analysis
Performance-grade certification tiers separate polycarbonate deflectors from commodity acrylic alternatives, and this bifurcation manifests in divergent supply chain configurations across German OEM channels and North American aftermarket distribution. Premium polycarbonate formulations draw from South Korean petrochemical complexes with validated low-GWP production credentials under EU F-Gas Regulation amendments, while acrylic sheet feeds from distributed European extrusion facilities serving price-sensitive retrofit channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with polycarbonate variants commanding substantial premiums justified by ECE R29 homologation testing and impact-resistance certification. Price differentiation rests on material provenance documentation and OEM factory-fit integration versus aftermarket bolt-on accessibility. Cost compression in aluminum extrusion tiers is intensifying because LME price volatility and energy-intensive smelting margins squeeze fabricators serving severe-duty mining applications. Fleet procurement departments demonstrate lowest price sensitivity where eighteen-month fuel payback calculations dominate total cost of ownership models.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese polycarbonate resin producers, where Yangtze River Delta and Ulsan petrochemical clusters anchor global thermoplastic supply for impact-resistant deflector specifications. Raw material dependencies encompass polycarbonate granulate, extruded aluminum billet, and acrylic sheet stock. Tariff exposure on Asian polymer imports threatens European fabricator margins under evolving border-adjustment mechanisms. Distribution runs through tier-one OEM assembly plants in Detroit and Stuttgart for factory-fit volumes, while independent parts channels and direct fleet agreements capture aftermarket retrofit demand across North American long-haul corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory pressure into structural demand, with EPA Phase 2 greenhouse gas standards and EU CO2 emission targets for heavy-duty vehicles mandating aerodynamic device integration as baseline compliance.
For Market Incumbents: Deploy backward integration into polycarbonate sheet extrusion to secure low-GWP material credentials required for EU Green Deal procurement eligibility. Anchor factory-fit programs with Freightliner and Peterbilt assembly plants against emerging active grille shutter systems that blur traditional deflector category boundaries. Channel control through direct supply agreements with 500-plus unit fleets displaces traditional parts distribution networks. For New Entrants and Emerging Players: Mid-tier price-point gaps between premium polycarbonate OEM specifications and commodity acrylic aftermarket retrofits create white-space opportunities in adhesive-mount systems for lease-fleet channels. Target Japanese passenger car aftermarket where permanent modification triggers return penalties and aesthetic transparency drives purchasing decisions. Pursue 3D-printed bracket manufacturing to collapse tooling costs for low-volume specialty vehicle applications. For Investors and Strategic Acquirers: Consolidation pressure builds where computational fluid dynamics talent scarcity limits independent deflector developers' optimization capabilities against tier-one supplier concentration. Long-term viability favors integrated polymer processors with captive raw material conversion and validated ECE R29 homologation pipelines. Monitor wind tunnel validation capacity bottlenecks at certified facilities as an inflection indicator constraining new product introduction cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Secures low-GWP material credentials for EU Green Deal fleet procurement eligibility. |
| ECE R29 Homologation Investment | Accelerates product development timelines for roof deflector integration with Stuttgart OEM platforms. |
| Direct Fleet Supply Agreements | Bypasses independent parts channels for 500-plus unit operators running Dallas-to-Chicago corridors. |
| Active Aerodynamics R&D Partnership | Positions shape-memory polymer deflectors for German refrigerated trailer pilot programs. |
| 3D-Printed Bracket Manufacturing Scale-Up | Collapses tooling costs for custom fleet specifications and low-volume mining applications. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with OEM platform engineers, aftermarket distribution heads, fleet procurement directors, and polymer processing specialists. Secondary validation draws from EPA regulatory filings, EU type-approval databases, vehicle production statistics, and customs trade data for polycarbonate and aluminum sheet imports. Bottom-up volume modeling and top-down value triangulation cross-validate segment-level outputs.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window, with segmentation dimensions encompassing product type, material grade, installation methodology, and vehicle platform class. CAGRs derive from regression analysis against historical fleet renewal cycles and regulatory compliance timelines. Industry-specific forecast inputs incorporate diesel price volatility correlations for long-haul fuel payback calculations and polymer resin price indices tied to Asian petrochemical capacity utilization.
The model assumes a particular technology adoption path; alternative pathways for active grille shutter convergence and battery-electric truck thermal management would alter the outlook. Forecasts reflect assumptions about regulatory enforcement intensity and fleet procurement centralization trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steering Knuckle Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Heavy Vehicles Suspension Anti-Vibration Components Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Towing Ropes Market