
 Global Automotive Rain, Light, Humidity Sensor Market | 2026-2036
Global Automotive Rain, Light, Humidity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Rain, Light, Humidity Sensor Market Intelligence
Expertise in sensor fusion software and embedded AI programming is collapsing the traditional divide between hardware and software engineering teams. Robert Bosch GmbH leverages its vast electronics and software portfolio to offer integrated solutions. Valeo SA specializes in optical sensor technology for both light and rain detection functions. NXP B.V. dominates the microcontroller and processing chip segment that underpins sensor intelligence.
Automotive rain, light, and humidity sensors are mechatronic components that detect environmental conditions to automate vehicle functions. These devices often use optical photodiodes to measure ambient light and infrared light reflection for rain, while capacitive or resistive elements detect air moisture. Combined sensors represent the fastest-growing product type, displacing single-function units in new vehicle platforms. Within applications, automatic windshield wipers and headlight control remain the largest volume segments, driven by OEM integration.
Safety mandates, such as the US NHTSA's guidelines for automatic high beams and the EU's General Safety Regulation, directly link sensor performance to vehicle compliance. In China, GB standards for automotive electronics set minimum reliability and durability requirements for these components. Vendor selection will increasingly depend on the ability to deliver sensor fusion capabilities that support next-generation autonomous driving and cabin comfort features.
Market Dynamics
The central force governing the automotive rain, light, and humidity sensor market is the architectural shift toward sensor fusion. This transition from discrete components to integrated, intelligent modules is driven by the data-processing demands of advanced driver-assistance systems and automated vehicle functions.
Growth Catalysts
- Regulatory Mandates:Safety regulations, including the EU's General Safety Regulation and US NHTSA guidelines for automatic high beams, compel OEM adoption of sensor-dependent features, creating a baseline demand for these components in all new vehicles.
- ADAS Integration:The proliferation of advanced driver-assistance systems (ADAS) requires precise environmental data, making combined rain, light, and humidity sensors essential inputs for functions ranging from autonomous emergency braking to adaptive cruise control.
- Automotive Production Centers:Demand is concentrating in established automotive manufacturing hubs, particularly in Germany and China, where high-volume production lines and sophisticated vehicle platforms accelerate the integration of advanced sensor technologies.
Market Restraints
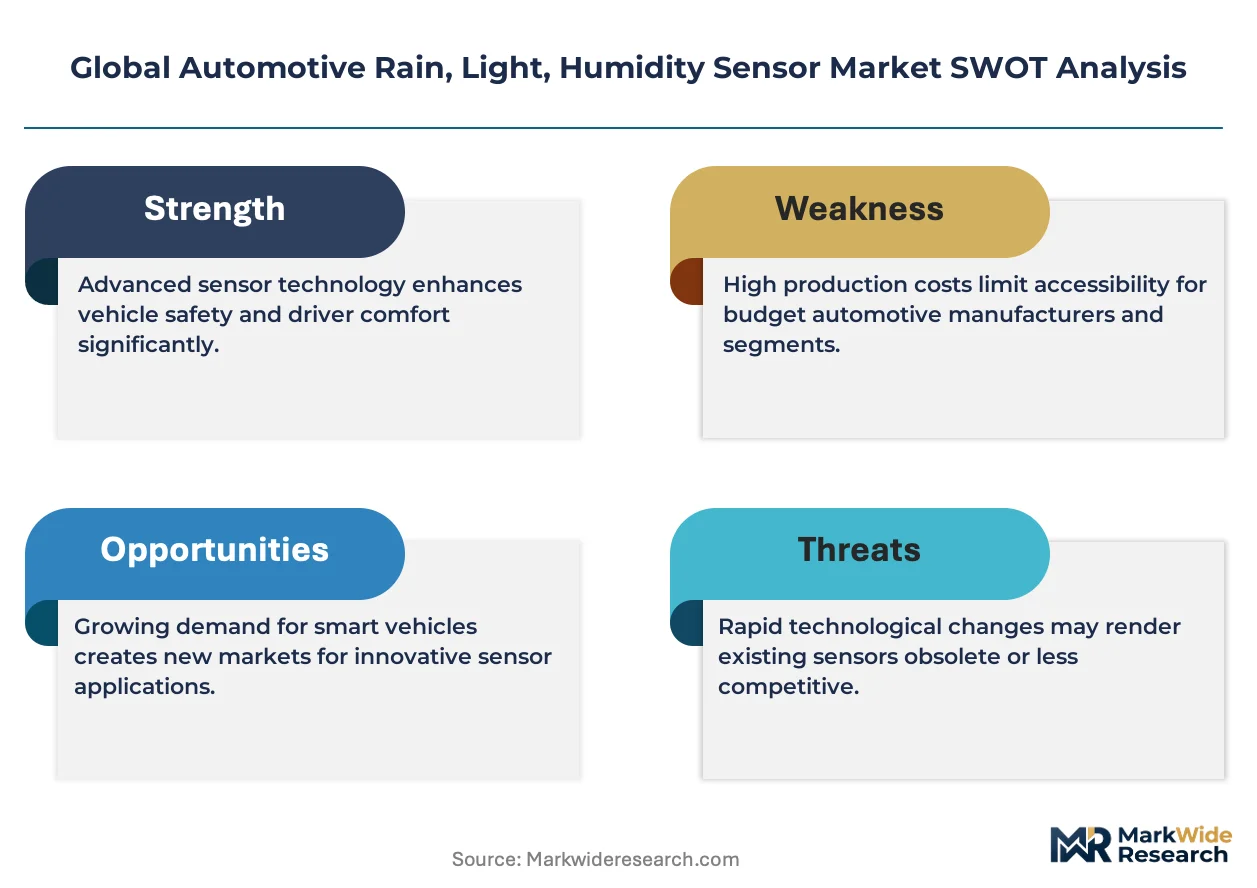
- High Development Costs:The significant investment required for research and development of sophisticated sensor fusion software and embedded AI algorithms creates a high barrier to entry for smaller component manufacturers.
- Performance Limitations:Optical-based rain sensors can experience reduced accuracy or failure in extreme weather conditions such as heavy snow, dense fog, or when the windshield is covered in dirt, posing a reliability challenge.
- Semiconductor Supply Dependency:The market's reliance on a concentrated group of suppliers for essential microcontrollers and processing chips creates vulnerability to supply chain disruptions and price volatility in the semiconductor industry.
Strategic Opportunities
- Cabin Comfort Systems:Integrating humidity and light sensors with vehicle climate control (HVAC) systems presents an opportunity to create automated defogging functions and adaptive interior lighting, enhancing passenger comfort and safety.
- Commercial Vehicle Adoption:The commercial truck segment remains an underpenetrated market for advanced sensors, offering significant growth potential as fleet operators adopt ADAS technologies to improve safety and operational efficiency.
- Solid-State Technology:Development of next-generation solid-state sensors without moving parts or optical lenses offers a path to improved durability, reduced size, and greater resistance to environmental interference compared to current mechatronic devices.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers possessing hybrid expertise in both mechatronic hardware design and embedded AI software programming constrains innovation and product development timelines for sensor manufacturers.
- System Interoperability:Ensuring seamless data communication and functional compatibility between sensors from different vendors within a single vehicle's electronic architecture presents a significant and complex integration challenge for automakers.
- Automotive-Grade Validation:The lengthy and rigorous testing cycles required to certify that sensors meet automotive-grade reliability and durability standards, such as China's GB standards, adds considerable time and cost to product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Rain, Light, Humidity Sensor Market |
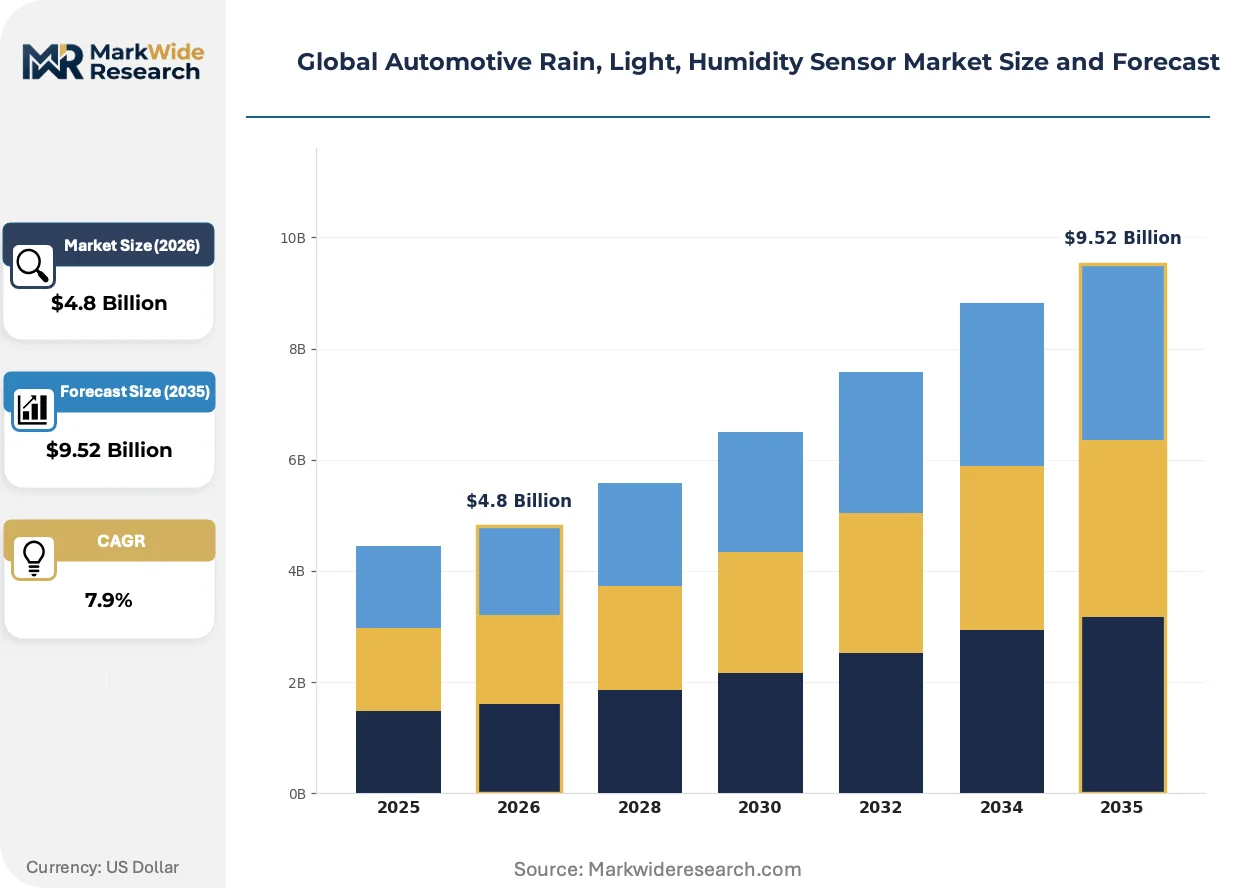
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rain Sensors, Light Sensors, Humidity Sensors, Combined Sensors Technology: Optical, Capacitive, Resistive, Photodiode, Ultrasonic Application: Automatic Windshield Wipers, Headlight Control, Climate Control Systems, Air Quality Monitoring End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | DENSO Corporation, Mitsubishi Electric Corporation, HELLA GmbH & Co. KGaA, PHINIA Inc., NXP B.V., Robert Bosch GmbH, ZF Friedrichshafen AG, Melexis NV, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Rain, Light, Humidity Sensor Market Strategic Shifts & Innovations
The market is transitioning from selling discrete hardware to providing intelligent environmental perception nodes. This evolution is driven by the software-defined vehicle architecture, where sensor data becomes a critical asset for a wide array of onboard systems beyond just wipers and headlights.
Sensor fusion software combines inputs from multiple sources—optical, capacitive, and infrared—to create a unified and more accurate model of the vehicle's immediate environment. Automakers are rapidly adopting this approach to power their latest ADAS and autonomous driving platforms. This software-centric model is decomposing the traditional hardware-focused value chain, elevating the importance of embedded programming and algorithmic expertise.
Regulatory frameworks like the EU's General Safety Regulation are establishing non-negotiable performance floors for safety-critical systems. This directly links sensor accuracy and reliability to a vehicle's legal ability to be sold in the European market. The automatic headlight and wiper control segments are most affected, forcing suppliers to invest in more robust validation to prove compliance.
A distinct change in OEM sourcing behavior involves bundling procurement away from individual components and toward pre-integrated sensor modules. This practice disrupts the classic Tier-2 component supplier model, creating an advantage for larger Tier-1 suppliers capable of delivering a validated hardware and software package. This procurement trend is most visible in Germany and China, where automakers prioritize reducing integration complexity and development overhead.
Global Automotive Rain, Light, Humidity Sensor Market Segmentation
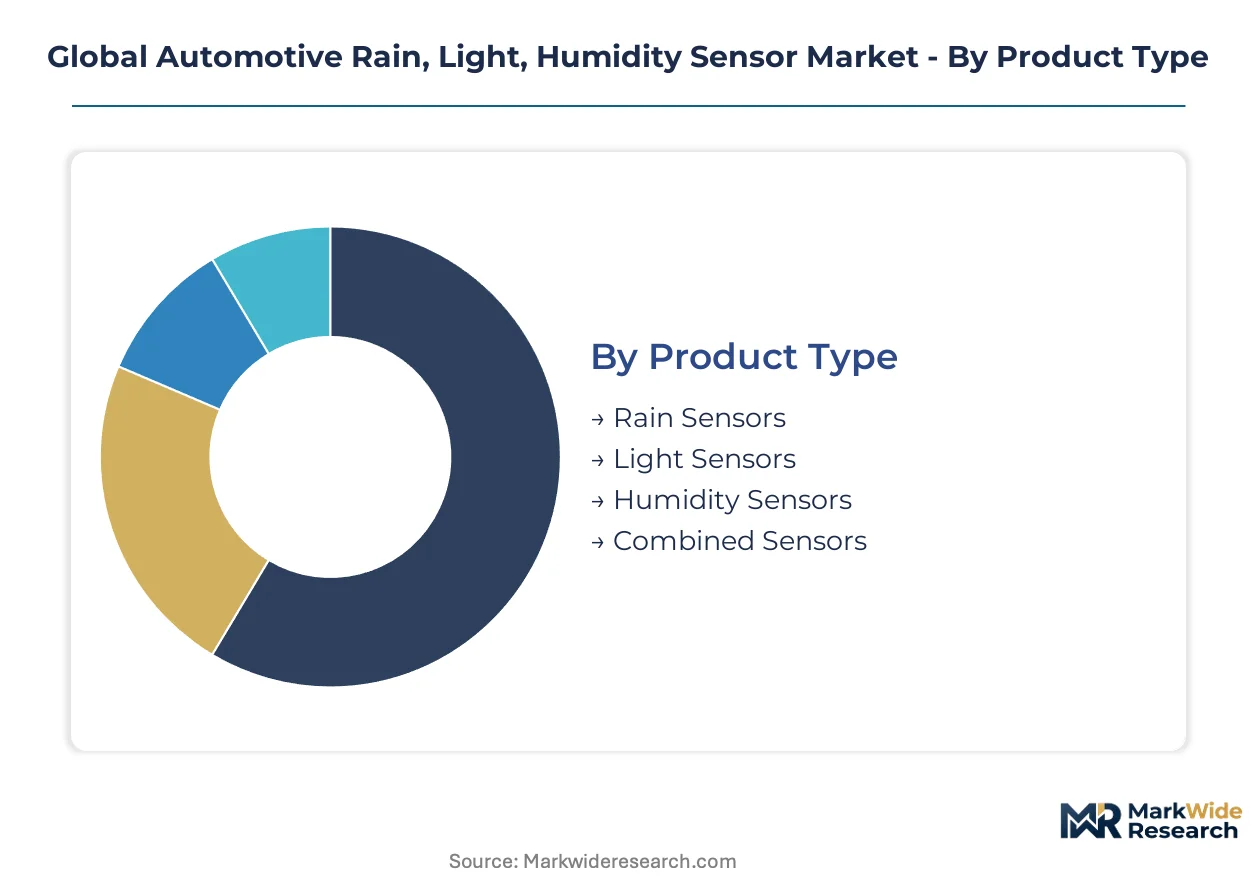
Segmentation within the automotive rain, light, and humidity sensor market illuminates critical shifts in product development and end-user procurement strategies. It reveals how technological advancements and regulatory pressures are reconfiguring product offerings and application focus within the automotive sensor market. This analysis highlights shifts from discrete components to integrated solutions.
Product Type:
Combined sensors exert significant substitution pressure on single-function units within the automotive sensor market, driving a transition towards integrated solutions. This reflects OEM demand for consolidated components and simplified vehicle architectures.
- Combined Sensors:These mechatronic components integrate multiple detection capabilities, such as optical for light and infrared for rain, into a single unit. Demand concentrates in new vehicle platforms, driven by OEM efforts to reduce complexity and component count in advanced driver-assistance systems.
- Rain Sensors:Utilize optical photodiodes and infrared light reflection to detect water on the windshield, automating wiper operation. Regulatory mandates for automatic windshield wipers, particularly from the EU's General Safety Regulation, drive their widespread integration into new vehicles.
- Light Sensors:Optical photodiodes measure ambient illumination for automatic headlight control and adaptive interior lighting systems.
- Humidity Sensors:Employ capacitive or resistive elements to detect air moisture levels, primarily for automated defogging and climate control functions.
Rain Sensors retain volume leadership; Combined Sensors hold the steepest expansion curve.
Technology:
The choice of sensor technology is dictated by specific application requirements and performance trade-offs in different environmental conditions. Each technology offers distinct advantages for various detection tasks.
- Optical:Leverages light-based principles, often infrared or visible spectrum, for detecting rain, light levels, and sometimes even humidity through advanced spectroscopy. Its prevalence in ADAS applications, particularly for light and rain detection, drives high demand across global automotive production centers like Germany and China.
- Photodiode:A semiconductor device converting light into electrical current, forming the core component for ambient light detection in vehicles. These are essential for automatic headlight systems and interior lighting adjustments, ensuring compliance with safety regulations like those from US NHTSA.
- Capacitive:Measures changes in electrical capacitance caused by moisture, primarily used for humidity sensing and touch-sensitive surfaces.
- Resistive:Detects humidity by measuring changes in electrical resistance across a moisture-sensitive material.
- Ultrasonic:Employs sound waves to detect objects or measure distances, with niche applications in some advanced environmental sensing.
Optical technologies remain foundational, while advanced integration drives innovation.
Application:
Regulatory mandates directly influence the volume and functional integration of sensors across various vehicle applications. These regulations establish baseline safety features that rely on accurate sensor data.
- Automatic Windshield Wipers:Utilizes rain sensors to detect precipitation on the windshield, automatically activating and adjusting wiper speed. This application represents the largest volume segment, driven by OEM integration and consumer convenience expectations in all major automotive markets.
- Headlight Control:Employs light sensors to detect ambient illumination, automatically switching headlights on/off or adjusting high beams. US NHTSA guidelines for automatic high beams and similar regulations in other regions mandate its inclusion, ensuring safety compliance.
- Climate Control Systems:Integrates humidity and temperature sensors to optimize cabin air quality and defogging functions, enhancing passenger comfort.
- Air Quality Monitoring:Uses specialized sensors to detect pollutants and allergens, contributing to advanced cabin filtration and environmental control systems.
Automatic Windshield Wipers and Headlight Control dominate current installations, with Climate Control Systems showing significant growth.
End User:
Procurement patterns among end users are shifting towards integrated solutions, influencing supplier relationships and the value chain. This impacts how components are sourced and validated.
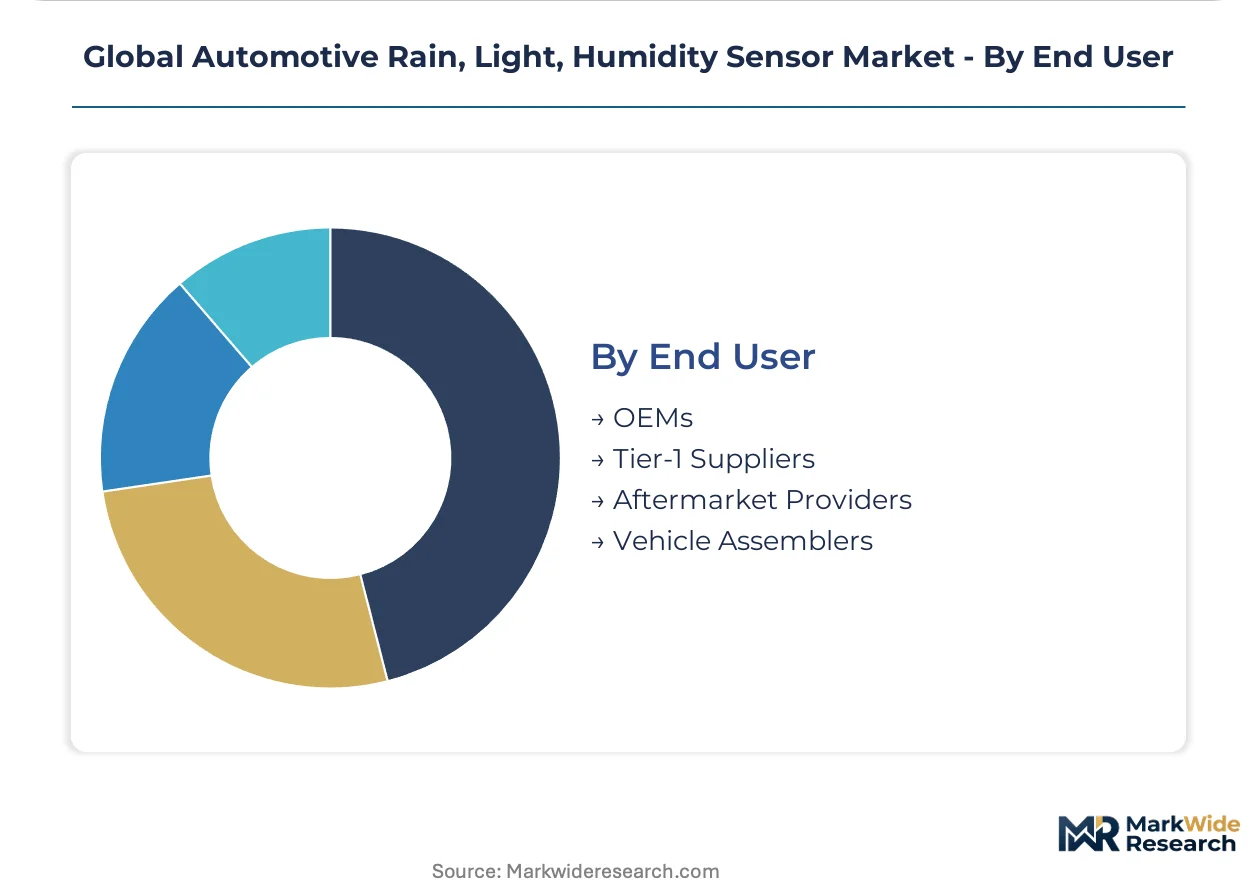
- OEMs:Original Equipment Manufacturers integrate rain, light, and humidity sensors directly into new vehicle designs during the production phase. Their demand is driven by regulatory compliance, ADAS requirements, and the desire for differentiated cabin comfort features, particularly in Germany and China.
- Tier-1 Suppliers:These companies develop and supply complete sensor modules and subsystems directly to OEMs, often incorporating components from Tier-2 manufacturers. Their role is critical in delivering validated hardware and software packages, especially for complex sensor fusion architectures.
- Aftermarket Providers:Offer replacement sensors or upgrade kits for existing vehicles, catering to repairs or feature enhancements post-sale.
- Vehicle Assemblers:Integrate pre-assembled sensor modules into the final vehicle structure, focusing on efficient installation and quality control.
OEMs are the primary purchasers, with Tier-1 suppliers acting as crucial integration partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A pronounced regional pricing-power asymmetry characterizes the global automotive rain, light, and humidity sensor market. German manufacturers often command premium pricing for advanced integrated solutions, while Chinese suppliers compete intensely on volume and cost efficiency. This dynamic influences procurement strategies across major automotive production centers.
Germany
German automakers prioritize advanced ADAS integration, driving demand for high-performance rain, light, and humidity sensors. The EU's General Safety Regulation mandates features relying on these components, ensuring a baseline market. Automotive clusters around Stuttgart and Munich are centers for sensor development and OEM integration.
China
Chinese vehicle production volumes necessitate substantial sensor procurement, with a focus on cost-effective yet reliable solutions. GB standards for automotive electronics establish minimum reliability thresholds for these components. Major manufacturing hubs like the Yangtze River Delta concentrate demand for integrated sensor modules.
United States
US consumer preferences for convenience features and advanced safety systems stimulate demand for sophisticated environmental sensors. The US NHTSA guidelines for automatic high beams directly influence sensor performance requirements. Detroit remains a critical hub for automotive R&D and sensor application development.
Japan
Japanese automakers integrate rain, light, and humidity sensors into their advanced vehicle platforms for enhanced safety and comfort. Domestic regulations, including JIS standards for automotive components, ensure high quality and durability. Innovation centers in Toyota City and Nagoya drive sensor technology advancements.
India
India's automotive sector is gradually adopting ADAS technologies, increasing the uptake of basic and combined rain, light, and humidity sensors. Government initiatives promoting road safety are expected to accelerate sensor integration in new vehicles. Manufacturing zones in Chennai and Pune are expanding their sensor assembly capabilities.
Global Automotive Rain, Light, Humidity Sensor Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the automotive sensor market. The industry exhibits a tiered structure, with large, vertically integrated Tier-1 suppliers dominating the premium segment through advanced R&D. Mid-sized specialists focus on specific sensor technologies or embedded software solutions. Dominant players often pursue strategic partnerships for software capabilities and engage in M&A to acquire specialized sensor technologies.
Integrated solution providers, such as Robert Bosch GmbH, leverage extensive electronics and software portfolios to offer comprehensive, high-value sensor packages to global automakers. French-based automotive supplier Valeo SA exemplifies optical sensor specialization, focusing on advanced light and rain detection functions for both ADAS and cabin comfort systems. Dutch semiconductor company NXP B.V. anchors the microcontroller and processing chip segment, providing the essential intelligence underpinning sensor fusion and embedded AI algorithms for various market participants across the value chain.
| Leading Market Players |
|---|
| DENSO Corporation |
| Mitsubishi Electric Corporation |
| HELLA GmbH & Co. KGaA |
| PHINIA Inc. |
| NXP B.V. |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Melexis NV |
| Valeo SA |
| Others |
Cost & Logistics Intelligence
The concentrated manufacturing capacity for microcontrollers in specific regions dictates both supply availability and component cost floors for the automotive sensor market. This concentration influences the pricing power of key suppliers and the overall cost structure for OEMs.
Pricing Analysis
Configured-to-order sensor modules command premium pricing compared to standard, high-volume units. The dominant pricing structure remains per-unit transactional, often under long-term contract-based agreements with automotive OEMs. Performance differentiation, particularly sensor fusion capabilities and automotive-grade validation, drives price differentiation. Pricing softness stems from intense competition among Tier-1 suppliers and the cost-efficiency focus of Chinese manufacturers. OEMs are generally less price-sensitive for safety-critical ADAS components, while aftermarket providers exhibit higher price sensitivity.
Supply Chain Analysis
China and Germany anchor the production of automotive rain, light, and humidity sensor modules, reflecting their roles as major automotive manufacturing hubs. The supply chain draws from critical raw materials including silicon for photodiodes and various rare earth elements for specialized optical components. Single-source vulnerability for essential microcontrollers and processing chips creates a structural supply chain risk. Distribution runs through a tiered model, with Tier-1 suppliers integrating components from Tier-2 manufacturers before delivering complete modules to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive rain, light, humidity sensor market experiences a buyer-power shift as OEMs consolidate procurement towards integrated sensor solutions.
For Market Incumbents: Consolidate core competencies in sensor fusion and embedded AI software development. This strategic move counters the threat from specialized software firms and strengthens integrated offerings. Invest in advanced material science for solid-state sensor development to mitigate performance limitations in extreme weather. Leverage existing OEM relationships to co-develop next-generation cabin comfort systems, expanding beyond traditional safety applications.
For New Entrants and Emerging Players: Anchor in niche applications such as commercial vehicle ADAS or specialized cabin comfort systems. The underpenetrated commercial truck segment offers a viable entry point. Focus on developing cost-effective, high-reliability solutions for emerging markets like India, where basic ADAS adoption is accelerating. A go-to-market angle emphasizing modularity and ease of integration can appeal to OEMs seeking to reduce development overhead.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in solid-state sensor development and advanced AI algorithms. Long-term viability hinges on companies capable of delivering validated hardware-software packages for autonomous driving platforms. Acquisition targets should possess strong intellectual property in optical sensor technology or embedded processing. The signal to watch is the market's response to new automotive-grade validation standards for sensor fusion systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Solid-State Sensor R&D | This reduces performance limitations in harsh weather and enhances long-term durability for vehicle owners. |
| Develop Advanced Sensor Fusion Software | This enables more precise environmental perception for next-generation ADAS and autonomous driving systems. |
| Expand into Commercial Vehicle ADAS | This captures growth from an underpenetrated segment seeking improved safety and operational efficiency for fleet operators. |
| Strengthen Microcontroller Supply Partnerships | This mitigates supply chain vulnerability and ensures stable production for critical sensor components. |
| Pursue Automotive-Grade Validation for AI | This ensures compliance with global safety regulations like the EU's General Safety Regulation for advanced sensor functions. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. This study engaged OEM platform engineers, Tier-1 supplier procurement managers, and specialized software developers. Secondary data sources included vehicle production databases, regulatory filings from US NHTSA and EU bodies, and technical publications. Bottom-up and top-down triangulation ensured data consistency and comprehensive market sizing.
Sensitivity analysis informed the quantitative modeling, accounting for various scenarios impacting market growth drivers. The analytical framework projected market development across the analysis window, segmented by product type, technology, application, end user, and regional production cluster. Compound annual growth rates were derived from historical trends and future projections, incorporating inputs like ADAS penetration rates and semiconductor material costs.
Decision-makers should treat outputs as directional under current regulatory and technological adoption assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding automotive production volumes and the pace of autonomous driving feature integration. Recalibration cycles align with material shifts in regulatory mandates, ADAS integration rates, or semiconductor supply dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Rail Components Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
HCV Axles Market