
 Global Software Asset Management Market | 2026-2036
Global Software Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Software Asset Management Market Outlook
Enterprise-grade license compliance is reorganizing competitive dynamics in software asset management. Flexera Software LLC leverages deep publisher partnerships to sustain its position across complex enterprise environments. ServiceNow Inc. anchors its offering through platform integration with IT service management workflows. Snow Software Oy differentiates through discovery capabilities that span on-premise and cloud estates.
Software asset management encompasses the systematic governance of software licenses, entitlements, and usage rights through automated discovery, normalization, and reconciliation processes against vendor-specific metrics such as processor value units or named user counts. Its primary commercial purpose is to eliminate audit liability, optimize renewal negotiations, and prevent shelfware across distributed IT environments. Cloud-based deployment leads segment expansion as organizations abandon perpetual license tracking for dynamic SaaS subscription governance, while license management solutions command the deepest margin pools due to publisher audit defense requirements. The IT services end-user category generates the most complex entitlement scenarios, driving specialized tool development.
The US Federal Acquisition Regulation, EU GDPR, and ISO 19770 standards collectively shape product requirements by mandating demonstrable software inventory accuracy and data residency controls. The US Office of Management and Budget reinforces federal-level SAM discipline through category management directives. Stakeholders must monitor how AI-driven usage analytics reshape vendor audit methodologies and buyer negotiation leverage.
Market Dynamics
SaaS subscription sprawl is fragmenting enterprise software visibility, forcing IT departments to abandon static license inventories for dynamic entitlement tracking across multi-cloud estates.
Growth Catalysts
- ISO 19770-1 certification mandates:Enterprise procurement policies in Germany and Japan now require standardized software identification tags, accelerating tool deployment for inventory normalization.
- Financial services audit exposure:Banking regulators in the United States intensified vendor compliance examinations, driving demand for automated reconciliation against processor value unit metrics.
- Container orchestration adoption:Kubernetes-based microservices architectures complicate license consumption measurement, creating urgency for usage analytics that span ephemeral compute instances.
Market Restraints
- Publisher contract complexity:Oracle and Microsoft embed virtualization clauses that trigger unintended licensing exposure, increasing professional services costs for compliance interpretation.
- Cloud vendor lock-in:AWS, Azure, and Google Cloud maintain proprietary metering APIs that resist third-party SAM tool integration, constraining multi-cloud visibility.
- Data residency requirements:GDPR Article 44 restricts cross-border software usage telemetry, forcing redundant regional tool deployments and inflating total cost of ownership.
Strategic Opportunities
- India's digital infrastructure expansion:RBI-mandated IT governance standards for scheduled commercial banks create first-mover advantage for SAM vendors establishing localized data centers.
- AI-driven usage forecasting:Machine learning models that predict license consumption patterns enable proactive true-up negotiations before audit triggers.
- Embedded finance integration:Non-banking financial companies adopting banking-as-a-service platforms require granular entitlement tracking across white-labeled software stacks.
Industry Challenges
- SaaS discovery blind spots:Shadow IT procurement through corporate credit cards bypasses central SAM workflows, leaving 30-40% of cloud subscriptions untracked in typical enterprises.
- Skill scarcity in entitlement engineering:Professionals capable of interpreting IBM sub-capacity licensing rules or Adobe enterprise term agreements command premium compensation, constraining implementation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Software Asset Management Market |
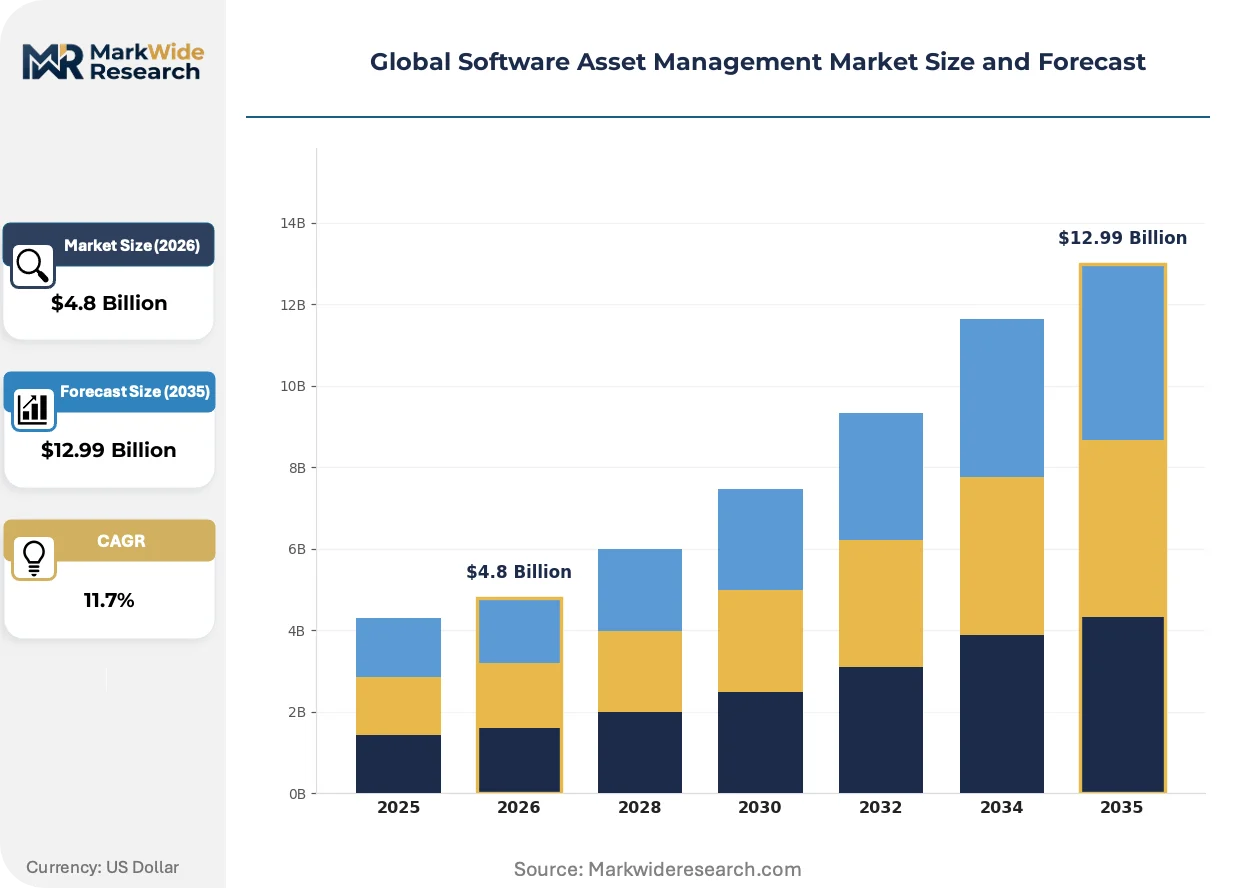
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based End User: IT Services, BFSI, Healthcare, Education Solution: License Management, Compliance Management, Optimization Tools, Reporting Solutions Application: Inventory Management, Usage Tracking, Cost Management, Vendor Management |
| Companies Covered | International Business Machines Corporation, Ivanti Inc., Flexera Software LLC, Aspera GmbH, Certero Limited, Snow Software Oy, Micro Focus International plc, Zoho Corporation Private Limited, ServiceNow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Software Asset Management Market Strategic Shifts
Automated discovery engines are supplanting manual inventory methods as the primary competitive differentiator, compressing implementation timelines from quarters to weeks.
Agentless network scanning is fragmenting traditional endpoint-based discovery architectures. Financial services institutions in the United States deploy passive traffic analysis to map SaaS consumption without client installation. This approach compresses deployment friction but introduces accuracy trade-offs for browser-based applications.
The EU AI Act establishes algorithmic transparency requirements for automated decision systems, including software usage analytics platforms. SAM vendors serving European enterprises must document training data provenance and inference logic. German automotive manufacturers now demand audit trails for license optimization recommendations affecting procurement decisions.
Corporate buying committees are consolidating vendor relationships to reduce SAM tool proliferation. Enterprise IT departments in Japan increasingly mandate platform consolidation, replacing point solutions with integrated IT service management suites. This pattern concentrates purchasing authority with CIO offices and extends procurement cycles.
Global Software Asset Management Market Segmentation
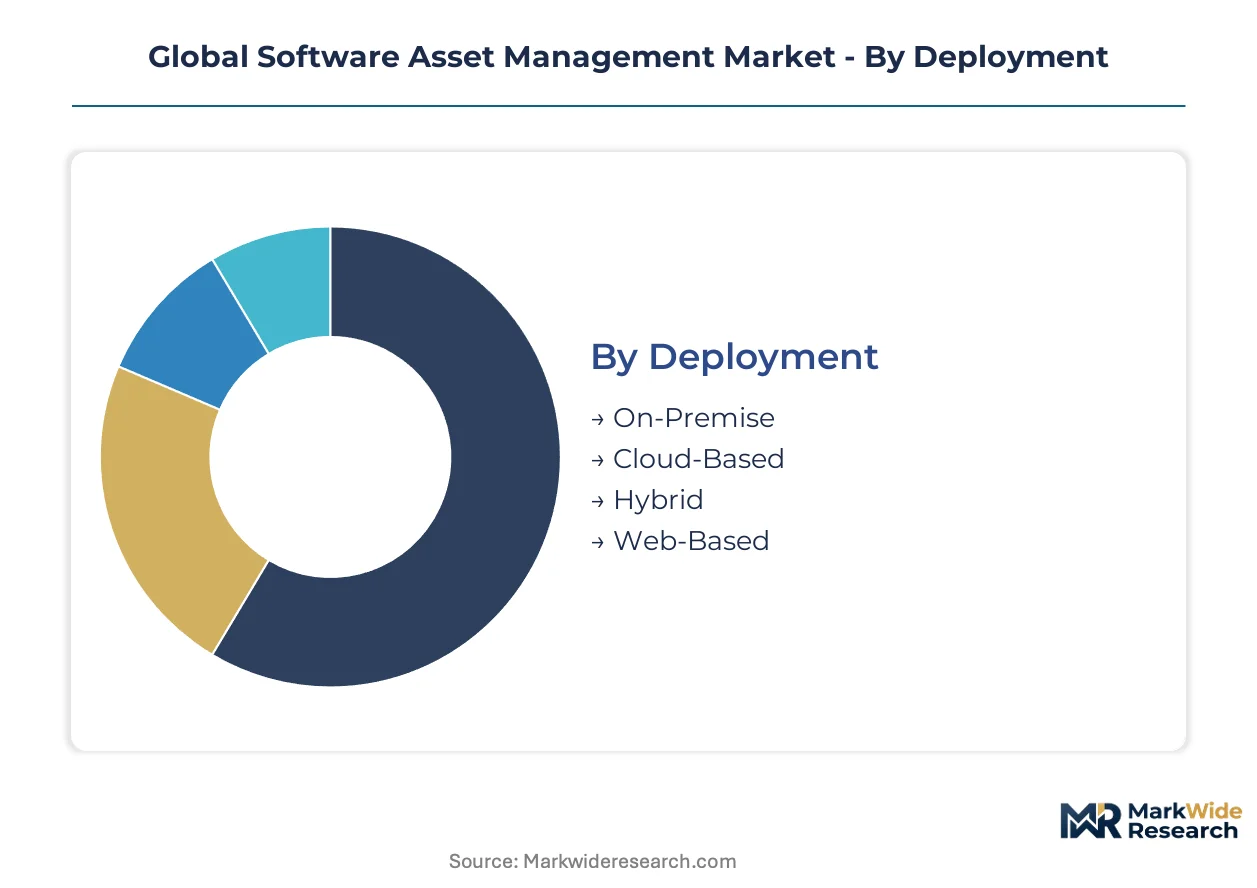
Software asset management vendors structure their offerings around deployment flexibility, end-user complexity, and solution depth. Segmentation reflects how organizations balance audit defense requirements against cloud migration timelines and IT governance maturity.
Deployment:
Channel mix varies sharply by deployment model, with direct enterprise sales dominating on-premise implementations while cloud-based solutions flow through MSPs and SaaS marketplaces.
- On-Premise:Organizations with stringent data residency mandates deploy these solutions within controlled data centers. Financial services institutions in Germany and Japan favor this model to satisfy GDPR Article 44 and local banking regulator requirements for software inventory sovereignty.
- Cloud-Based:Dynamic subscription governance across multi-cloud estates drives demand here. United States enterprises expanding SaaS portfolios favor this deployment for its reduced infrastructure overhead and faster time-to-value during vendor audit preparation.
- Hybrid:Combines on-premise discovery agents with cloud-native analytics platforms. This architecture addresses transitional states where legacy perpetual licenses coexist with emerging SaaS subscriptions.
- Web-Based:Browser-delivered interfaces eliminate client installation requirements. Mid-market organizations with limited IT operations staff select this option for simplified access management.
On-Premise deployments dominate installed base. Cloud-Based solutions are where expansion concentrates.
End User:
Cost tier stratification separates enterprise-grade implementations from mid-market deployments, with compliance complexity determining pricing bands.
- IT Services:Managed service providers and systems integrators face the most intricate entitlement scenarios across client environments. These organizations require granular tracking of processor value units and named user counts to defend against publisher audits affecting multiple customer contracts simultaneously.
- BFSI:Banking, financial services, and insurance entities confront intensified regulatory scrutiny. United States federal banking examinations and RBI-mandated IT governance standards in India compel automated reconciliation capabilities.
- Healthcare:HIPAA compliance intersects with software inventory accuracy requirements. Patient data protection mandates drive demand for solutions documenting every application touching protected health information.
- Education:Volume licensing agreements with Microsoft and Adobe create unique optimization opportunities. Campus-wide deployments across distributed departments challenge centralized procurement visibility.
BFSI commands premium pricing tiers. Healthcare represents the steepest expansion trajectory as digital health initiatives proliferate.
Solution:
Application depth separates point solutions from integrated platforms, with audit defense functionality commanding the deepest investment.
- License Management:Core entitlement tracking against vendor-specific metrics forms the foundation of SAM programs. These solutions normalize discovery data into publisher-recognized consumption units for true-up negotiations.
- Compliance Management:Automated policy enforcement against ISO 19770-1 standards and internal procurement rules. German automotive manufacturers now mandate these capabilities to satisfy EU AI Act documentation requirements for algorithmic procurement decisions.
- Optimization Tools:Usage analytics identify shelfware and reharvesting opportunities. Machine learning models predicting consumption patterns enable proactive renewal negotiations before audit triggers.
- Reporting Solutions:Executive dashboards and audit-ready documentation packages streamline stakeholder communication. These modules accelerate procurement cycle approvals and reduce professional services dependency.
License Management anchors revenue. Optimization Tools are gaining share fastest as organizations shift from reactive audit defense to proactive spend reduction.
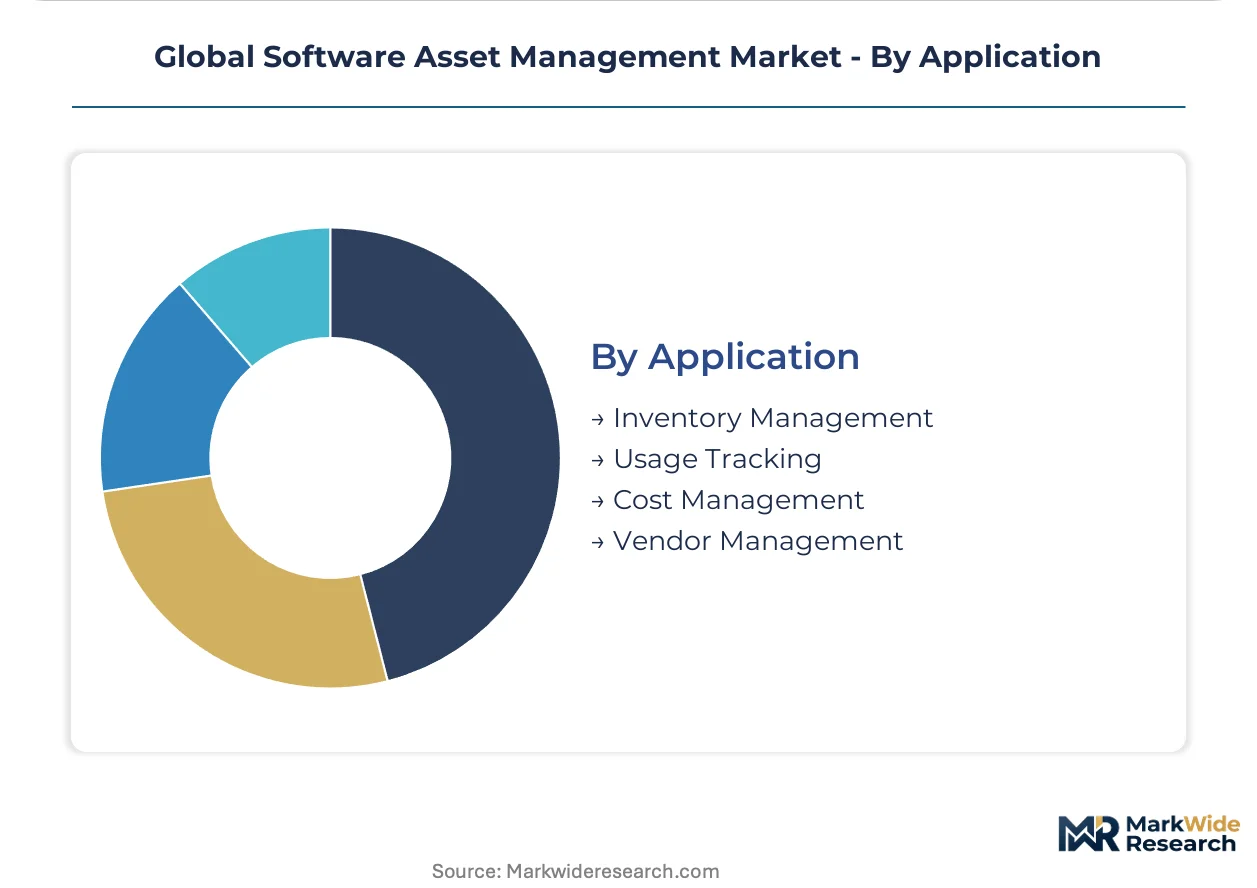
Application:
Customer maturity determines which functional modules deploy first, with inventory discovery preceding advanced analytics in typical implementation sequences.
- Inventory Management:Foundation layer discovering installed software across on-premise, cloud, and containerized environments. Agentless network scanning now supplements traditional endpoint agents for faster deployment.
- Usage Tracking:Consumption analytics spanning ephemeral compute instances and browser-based SaaS applications. Kubernetes-based microservices architectures create particular measurement complexity here.
- Cost Management:Financial allocation and chargeback functionality for distributed IT budgets. Shadow IT procurement through corporate credit cards leaves substantial untracked spend requiring reconciliation.
- Vendor Management:Contract repository and renewal workflow automation. Oracle and Microsoft virtualization clauses trigger unintended licensing exposure that specialized interpretation addresses.
Inventory Management saturates mature accounts. Usage Tracking is where new investment flows as SaaS sprawl fragments enterprise visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border software licensing flows generate substantial trade documentation requirements, with net-importing jurisdictions accelerating SAM deployment to track entitlement transfers. The United States, Germany, and Japan dominate procurement volumes, while India and the United Kingdom emerge as high-velocity expansion markets.
United States
Federal banking examinations and OMB category management directives compel automated reconciliation capabilities across financial services. The SEC intensifies vendor compliance scrutiny for listed entities. Enterprise procurement clusters in New York and Chicago drive premium-tier solution adoption for audit defense.
Germany
Automotive manufacturers and industrial conglomerates mandate ISO 19770-1 certification for supplier qualification. KBA oversight intersects with EU AI Act algorithmic transparency requirements for procurement analytics. Bavarian technology corridors concentrate deployment of hybrid discovery architectures.
Japan
METI industrial digitization programs accelerate cloud migration timelines, fragmenting legacy license visibility. Financial institutions confront intensified FSA examinations of software inventory accuracy. Tokyo-Osaka enterprise corridors anchor demand for containerized workload entitlement tracking.
India
RBI-mandated IT governance standards for scheduled commercial banks create localized data center requirements. Digital infrastructure expansion across fintech and banking-as-a-service platforms generates granular tracking needs. Mumbai and Bengaluru technology clusters drive first-mover vendor establishment.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border entitlement documentation for multinational enterprises. Financial conduct authority examinations emphasize demonstrable software inventory controls. London's financial services concentration sustains demand for audit-ready reconciliation platforms.
Global Software Asset Management Market Competitive Environment
Listed leaders compete with private specialists across platform integration depth, creating a tiered structure where scale advantages concentrate with IT workflow incumbents while discovery specialists defend niche positions. The vendor base separates into three archetypes: platform-integrated suites, standalone discovery engines, and publisher-aligned compliance tools. Consolidation pressure intensifies as enterprise buying committees mandate vendor reduction. M&A activity targets cloud-native discovery capabilities, while strategic partnerships with hyperscalers constrain independent tool interoperability.
Within the platform-integrated tier, ServiceNow Inc. and International Business Machines Corporation occupy positions anchoring enterprise workflow consolidation. Flexera Software LLC exemplifies the publisher-aligned archetype through deep entitlement interpretation capabilities. Snow Software Oy and Ivanti Inc. represent specialists spanning hybrid discovery architectures. These groupings illustrate how competitive positioning stratifies across integration depth rather than functional breadth alone.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Ivanti Inc. |
| Flexera Software LLC |
| Aspera GmbH |
| Certero Limited |
| Snow Software Oy |
| Micro Focus International plc |
| Zoho Corporation Private Limited |
| ServiceNow Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day implementation cycles for enterprise SAM deployments concentrate pricing power with vendors possessing pre-built connector libraries, while cloud-native delivery compresses infrastructure costs and reshapes margin pools across deployment tiers. This lead-time compression rewards suppliers with established publisher partnerships and penalizes point-solution vendors facing integration delays.
Pricing Analysis
Enterprise IT procurement teams anchor SAM pricing around subscription tiers indexed to discovery node counts and reconciliation complexity. Three-tier pricing structure across premium, standard, and economy levels separates audit-defense suites with ISO 19770-1 certification from mid-market inventory tools and basic reporting modules. Pricing pressure stems from MSP consolidation and platform bundling with ITSM workflows, compressing standalone tool margins. Mid-market organizations exhibit highest price sensitivity due to limited professional services budgets, while financial services institutions prioritize audit readiness over cost minimization.
Supply Chain Analysis
Ninety-day implementation cycles reflect dependency on specialized entitlement engineering talent concentrated in the United States, Germany, and India. Software discovery engines draw from cloud infrastructure provisioned through AWS, Azure, and Google Cloud, alongside on-premise agent deployment kits manufactured through regional IT distributors. Single-source vulnerability emerges from hyperscaler API lock-in constraining multi-cloud visibility. Distribution runs through direct enterprise sales for complex implementations and MSP channels for standardized cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SAM market exhibits cyclical recovery characteristics driven by enterprise cloud migration waves triggering successive entitlement governance investments. Audit intensity from major publishers creates recurring demand spikes aligned with fiscal year-end compliance cycles.
For Market Incumbents: Compound platform integration depth through native ITSM workflow embedding, defending against point-solution disintermediation. Extend discovery agent architectures into Kubernetes-native microservices monitoring to capture container orchestration spend. Prioritize ISO 19770-1 certification maintenance as procurement gatekeeping tightens in German and Japanese enterprise accounts. For New Entrants and Emerging Players: Anchor in India's RBI-mandated banking IT governance compliance surge, where localized data center requirements disadvantage foreign incumbents. Target mid-market healthcare providers facing HIPAA audit exposure with browser-delivered, agentless discovery tools requiring minimal implementation support. Pursue channel partnerships with regional MSPs rather than direct enterprise sales to accelerate customer acquisition. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core software compliance units, particularly automotive manufacturers streamlining supplier management portfolios. Long-term viability hinges on AI-driven usage analytics capabilities displacing reactive audit defense. Monitor Oracle and Microsoft virtualization clause enforcement intensity as inflection indicator for professional services demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ITSM workflow embedding consolidates purchasing authority with CIO offices and extends contract durations. |
| Acquisition of Specialist Firm | Kubernetes-native discovery capabilities address container orchestration licensing complexity in financial services microservices architectures. |
| Geographic Expansion | Localized data center establishment in India satisfies RBI data residency mandates for scheduled commercial banks. |
| Strategic Partnership | Hyperscaler alliances expand connector libraries despite API access constraints from AWS, Azure, and Google Cloud. |
| Product Launch | Agentless network scanning tools reduce deployment friction for United States financial institutions avoiding endpoint installation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, ISO certification registries, and trade data from software publisher audit defense engagements. Primary interviews encompassed CTOs at financial services institutions, IT procurement officers managing SaaS portfolios, platform engineers architecting multi-cloud governance, and channel partners distributing compliance tools. Bottom-up sizing of deployment volumes triangulates against top-down publisher licensing revenue estimates across the analysis window.
Segmentation dimensions modeled span deployment architecture, end-user vertical complexity, solution functional depth, and application maturity sequence throughout the forecast period. CAGRs derive from regression analysis against enterprise SaaS spend trajectories and audit frequency patterns. Forecast inputs incorporate ISO 19770-1 adoption curves in Germany and Japan, alongside RBI IT governance enforcement timelines in India.
Decision-makers should treat outputs as directional under assumptions of sustained publisher audit intensity and stable hyperscaler API access policies; material deviation in regulatory enforcement or cloud vendor integration terms would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Development Market
Software & Services
Account-Based Data Software Market
Software & Services
Smartphone Music Production Software Market
Software & Services
Gym Management Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Workstation Software Market
Software & Services
User Retention Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Content Distribution Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
PCB Design Software Market
Software & Services
Online Whiteboard Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Exploration and Production (E&P) Software Market