
 Device As a Service (Daas) Market | 2026-2036
Device As a Service (Daas) Market Size, Share, and Industry Trends Forecast 2026-2036
Device As a Service (Daas) Market Outlook
Multi-source procurement for endpoint fleets is shifting toward consolidated Daas contracts with integrated lifecycle management. Dell Technologies leverages its direct supply chain control to bundle hardware provisioning with predictive replacement logistics. HP Development Company anchors its competitive stance through in-house device refurbishment capabilities that extend contract profitability. Lenovo specializes in Chromebook-heavy educational deployments, occupying a distinct niche against enterprise-focused rivals.
Device As a Service delivers enterprise computing hardware through subscription contracts combining procurement, deployment, maintenance, and end-of-life recovery under per-seat pricing. Typical agreements span thirty-six to sixty months and incorporate remote monitoring agents for proactive failure detection. The laptop segment leads hardware attachment volumes, though hybrid deployment models are growing fastest as regulated industries demand local data residency alongside cloud management planes. Large enterprises represent the deepest margin pool, while educational institutions drive volume expansion through standardized refresh cycles.
The Federal Trade Commission scrutinizes auto-renewal clauses and early termination fees in US technology service contracts, reshaping vendor pricing transparency. The EU Corporate Sustainability Reporting Directive mandates disclosure of circular economy metrics, pressuring providers to document device recovery rates and carbon footprint per deployed unit. Germany's Federal Office for Information Security certifies endpoint security standards that Daas contracts must reference for public sector eligibility. Stakeholders must weigh residual value forecasting accuracy against regulatory compliance automation when selecting long-term service partners.
Market Dynamics
Healthcare systems across North America and Europe are consolidating endpoint procurement into bundled managed service contracts to satisfy tightening NIST cybersecurity frameworks and EU NIS2 directives while eliminating capital expenditure volatility.
Growth Catalysts
- EU NIS2 Directive:Mandatory endpoint security standards for critical infrastructure operators are accelerating migration from self-managed device fleets to vendor-bundled Daas contracts with integrated compliance automation.
- Germany's Mittelstand:Mid-sized industrial manufacturers favor operational expenditure models for shop-floor device fleets, converting hardware ownership into predictable monthly subscriptions.
- Predictive replacement logistics:Remote monitoring agents embedded in Daas contracts enable proactive failure detection, reducing downtime costs for regulated industries.
Market Restraints
- Residual value forecasting:Semiconductor price volatility and accelerated obsolescence cycles compress hardware remarketing margins, forcing providers to absorb depreciation risk.
- Supply concentration:Taiwan-based ODMs control notebook motherboard production, creating vulnerability for providers dependent on just-in-time hardware provisioning.
- Data residency mandates:China's MIIT cybersecurity reviews and Russia's data localization laws fragment cloud management architectures, increasing contract complexity.
Strategic Opportunities
- India's PLI scheme:Localized device assembly incentives enable Daas providers to establish captive refurbishment hubs serving South Asian enterprise demand.
- Edge-AI convergence:On-device machine learning accelerators are creating new subscription tiers combining hardware refresh with model inference capacity.
- EU CSRD disclosure:Mandatory circular economy metrics are positioning device recovery and carbon-per-unit tracking as differentiated service modules.
Industry Challenges
- Firmware security certification:Germany's BSI endpoint standards and US FedRAMP authorization timelines extend contract onboarding by six to twelve months.
- Legacy ERP integration:SAP and Oracle environments at industrial incumbents require custom API development for asset lifecycle synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Device As a Service (Daas) Market |
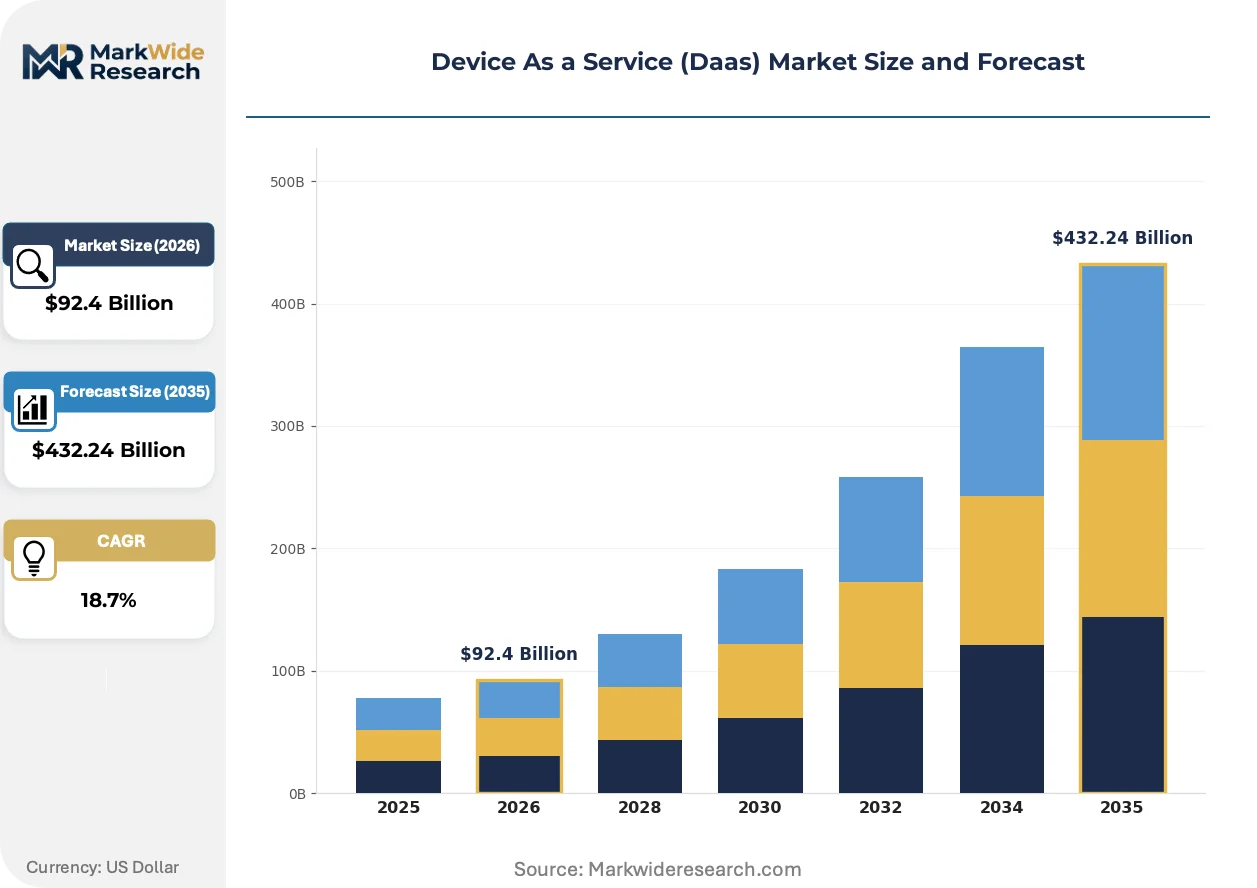
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $432.24 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, Tablets, Smartphones Deployment Model: Cloud-based, On-premises, Hybrid, Managed Service Service Type: Hardware Provisioning, Software Licensing, Technical Support, Maintenance Services End User: SMEs, Large Enterprises, Educational Institutions, Government Agencies |
| Companies Covered | Accenture, Dell Technologies, HP Development Company, Lenovo, Microsoft Corporation, Cisco, Computacenter, Intel Corporation, CompuCom Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Device As a Service (Daas) Market Strategic Shifts
Embedded telemetry and automated lifecycle orchestration are compressing the traditional three-year hardware refresh cycle while embedding compliance documentation directly into service delivery.
Zero-touch provisioning technology is electrifying enterprise endpoint deployment. IT departments at financial services firms are eliminating pre-configuration labor through cloud-initiated device enrollment. This capability is compressing deployment timelines from weeks to hours while reducing on-site technician dependency.
The EU Corporate Sustainability Reporting Directive mandates granular disclosure of device recovery rates and carbon footprint per deployed unit. Hardware providers must now embed blockchain-tracked chain-of-custody documentation into contract deliverables. Public sector procurement in Germany and France now weights circular economy metrics at thirty percent of technical evaluation scores.
Subscription-based consumption is displacing capital purchase authority within procurement functions. Facility management departments are absorbing IT hardware decisions previously owned by CIO organizations. This shift is most visible in US healthcare systems where capital budget freezes are redirecting clinical workstation acquisition through operational expenditure channels.
Device As a Service (Daas) Market Segmentation
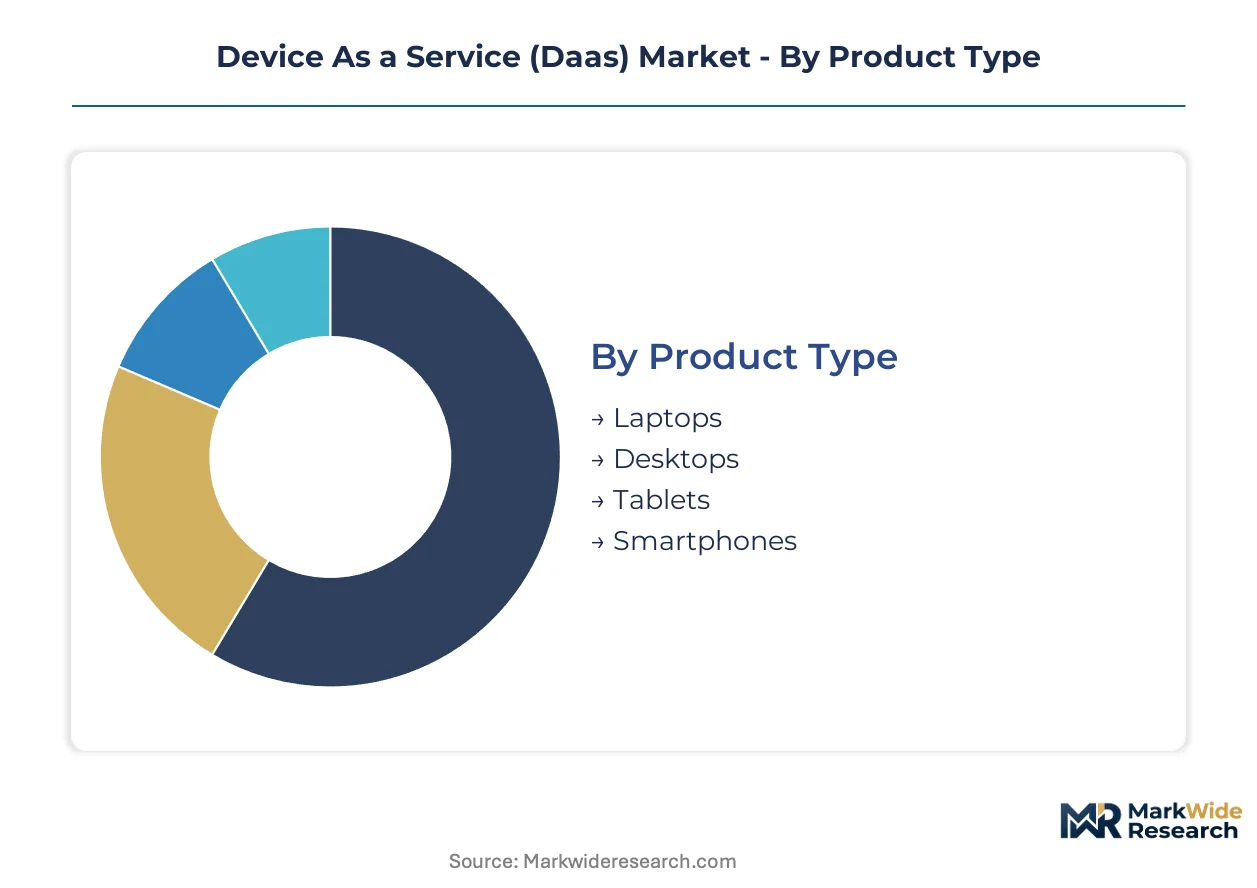
Device As a Service contracts bundle hardware lifecycle management with financial structuring that varies sharply by asset type and operational model. Procurement officers weigh residual value risk against compliance automation when selecting contract tiers across these dimensions.
Product Type:
Form factor specifications determine refresh cadence, remote monitoring feasibility, and remarketing liquidity in secondary channels.
- Laptops:Mobile compute platforms with embedded telemetry agents enable proactive failure detection and automated warranty claims processing. Healthcare systems in Germany and the United States consolidate clinical workstation procurement around laptop-heavy fleets to satisfy NIST cybersecurity frameworks while eliminating capital expenditure volatility.
- Desktops:Fixed-location workstations deliver superior thermal headroom for sustained computational loads and simpler internal component access for field repair. Industrial Mittelstand manufacturers in Germany favor desktop Daas for shop-floor engineering stations where operational expenditure models convert hardware ownership into predictable monthly subscriptions.
- Tablets:Touch-enabled mobile endpoints serve field service technicians and patient-facing clinical workflows requiring portability without full keyboard input.
- Smartphones:Cellular-connected handheld devices extend enterprise mobility management into frontline worker populations previously excluded from corporate device programs.
Laptops lead on scale; smartphones lead on momentum.
Deployment Model:
Data residency requirements and cloud management plane architectures fragment contract structures across regulated industries.
- Hybrid:Split architectures combining local data processing with cloud-based policy orchestration address conflicting mandates from China's MIIT cybersecurity reviews and EU GDPR data localization principles. Financial services firms in Frankfurt and Singapore deploy hybrid Daas to maintain on-premise transaction data while leveraging centralized endpoint management.
- Managed Service:Fully outsourced device lifecycle contracts bundle hardware provisioning with security operations center monitoring and compliance documentation. US healthcare systems migrating from self-managed fleets cite FTC scrutiny of auto-renewal clauses as a catalyst for transparent managed service relationships.
- Cloud-based:Pure cloud management planes eliminate on-premise infrastructure but face exclusion from public sector procurement in jurisdictions with strict data sovereignty laws.
- On-premises:Air-gapped or privately hosted management servers satisfy defense and intelligence community requirements at the cost of operational complexity.
Hybrid deployments lead on scale; managed service contracts lead on momentum.
Service Type:
Contract component unbundling allows procurement functions to match service levels against internal IT capabilities and regulatory exposure.
- Hardware Provisioning:Physical device procurement, imaging, and logistics coordination with predictive replacement algorithms based on telemetry-derived failure probability models. German public sector eligibility requires BSI-certified endpoint security standards embedded in provisioning workflows.
- Software Licensing:Operating system and productivity suite subscription management with automated license reclamation upon device retirement.
- Technical Support:Tiered helpdesk services ranging from password reset automation to on-site hardware replacement with defined mean-time-to-resolution commitments.
- Maintenance Services:Preventive and corrective maintenance with spare parts inventory management and field technician dispatch coordination.
Hardware provisioning leads on scale; software licensing leads on momentum.
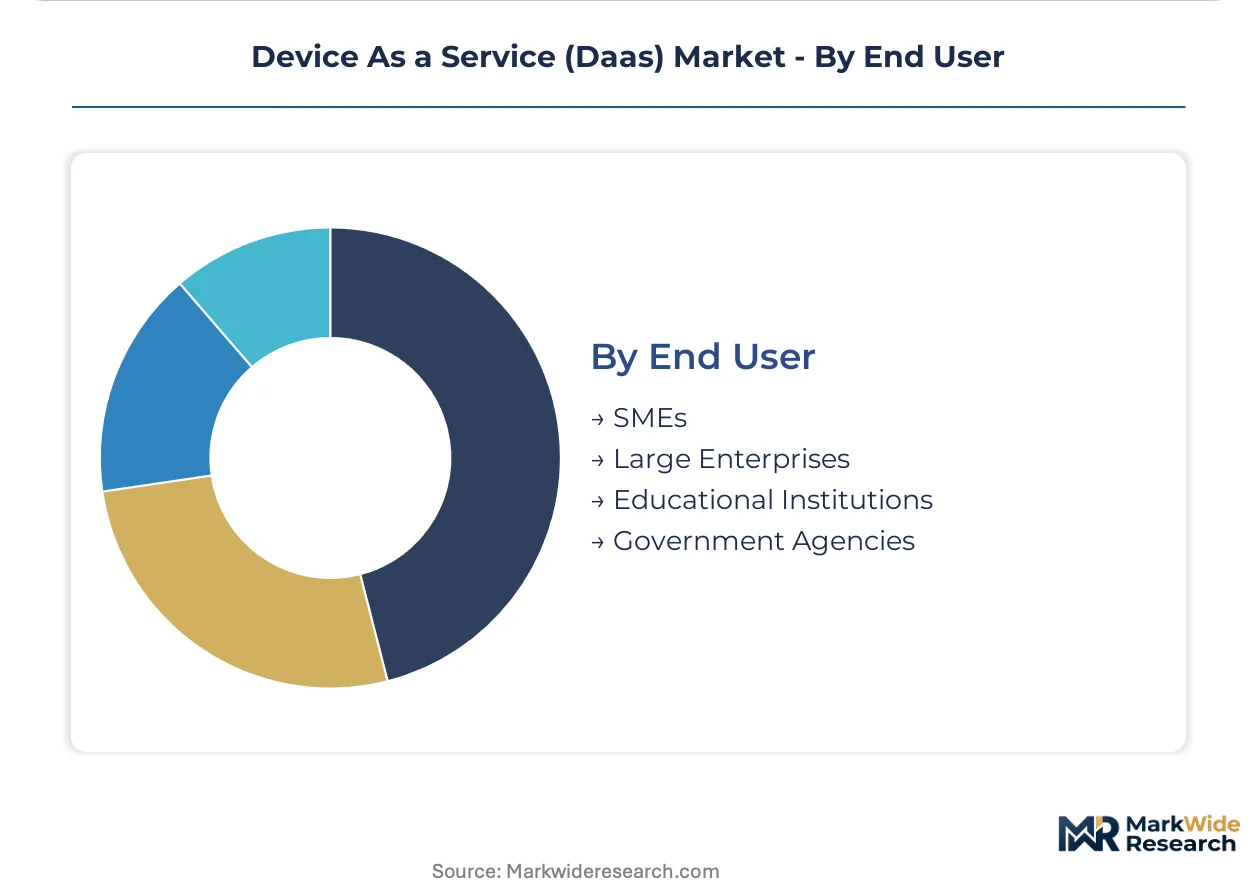
End User:
Organizational scale and procurement authority structures determine contract negotiation leverage and standardization potential.
- Large Enterprises:Multi-thousand seat contracts with customized service level agreements and dedicated account management resources. Industrial conglomerates leverage volume concentration to demand API integration with legacy SAP environments for asset lifecycle synchronization.
- Educational Institutions:Standardized refresh cycles and simplified device portfolios enable volume discounts but compress margins through competitive bidding requirements. US K-12 districts and universities drive Chromebook-heavy deployments with predictable three-year replacement cadences.
- SMEs:Small and medium enterprises with limited IT staff rely on Daas for turnkey endpoint management without internal hardware expertise.
- Government Agencies:Public sector procurement with mandatory disclosure of circular economy metrics under EU CSRD and weighted scoring for carbon-per-unit tracking.
Large enterprises lead on scale; educational institutions lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting Daas contract origination toward jurisdictions with streamlined compliance automation. Providers establish service delivery hubs where endpoint security certification timelines compress procurement cycles.
United States
Healthcare systems in Texas and California consolidate clinical workstation procurement into operational expenditure models. FTC scrutiny of auto-renewal clauses in technology service contracts is reshaping vendor pricing transparency requirements. Financial services firms in New York deploy hybrid Daas architectures to satisfy data residency mandates while leveraging centralized endpoint management.
Germany
Mid-sized manufacturers in Bavaria and Baden-Württemberg favor subscription-based shop-floor device fleets. BSI endpoint security standards extend public sector contract onboarding timelines by six to twelve months. Industrial engineering clusters around Stuttgart convert hardware ownership into predictable monthly subscriptions through managed service relationships.
United Kingdom
Enterprise buyers in London and the Southeast prioritize bundled lifecycle contracts with integrated compliance documentation. CSRD disclosure requirements pressure providers to document device recovery rates and carbon footprint per deployed unit. Educational institutions across England drive standardized Chromebook refresh cycles through competitive procurement frameworks.
India
Enterprise demand in Maharashtra and Karnataka accelerates localized device assembly under PLI scheme incentives. IT services exporters in Hyderabad and Bengaluru establish captive refurbishment hubs serving South Asian contract volumes. Mid-market companies in Delhi-NCR adopt turnkey endpoint management without internal hardware expertise.
Japan
Manufacturing conglomerates in the Chubu region around Nagoya operationalize predictive replacement logistics for engineering workstations. METI guidelines on data sovereignty influence hybrid deployment architectures combining local processing with cloud orchestration. Electronics assemblers in the Kanto region demand API integration with legacy ERP environments for asset lifecycle synchronization.
Device As a Service (Daas) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue edge-AI convergence and circular economy service modules. The vendor base stratifies across three maturity tiers: direct supply chain controllers, in-house refurbishment specialists, and educational niche operators. Consolidation pressure intensifies as semiconductor price volatility compresses hardware remarketing margins. Dominant competitive moves include predictive replacement logistics integration and API development for legacy ERP synchronization.
Within the direct supply chain tier, Dell Technologies and HP Development Company exemplify contrasting operational models. Dell leverages captive manufacturing control to bundle provisioning with automated failure detection workflows. HP anchors its position through internal device refurbishment capabilities that extend contract profitability across extended lease terms. Lenovo occupies the educational specialization vector, concentrating on Chromebook-heavy deployments with standardized refresh cadences against enterprise-focused rivals.
| Leading Market Players |
|---|
| Accenture |
| Dell Technologies |
| HP Development Company |
| Lenovo |
| Microsoft Corporation |
| Cisco |
| Computacenter |
| Intel Corporation |
| CompuCom Systems |
| Others |
Value Chain & Pricing Dynamics
Healthcare procurement officers in Germany and the United States anchor contract negotiations around bundled lifecycle pricing that converts capital expenditure into predictable operational outflows. This buyer concentration forces providers to absorb residual value risk while competing on compliance automation tiers.
Pricing Analysis
Distributor margins compress as direct vendor relationships displace channel intermediaries in large enterprise deals. Three-tier pricing structure across premium, standard, and economy levels segments by security certification grade and API integration depth. Pricing pressure stems from semiconductor price volatility eroding hardware remarketing margins. Educational institutions exhibit highest price sensitivity due to competitive bidding mandates, while regulated healthcare systems prioritize compliance guarantees over unit cost.
Supply Chain Analysis
Notebook motherboard production rests on Taiwan-based ODMs, creating single-source vulnerability for just-in-time provisioning workflows. Semiconductor fabrication draws from South Korean memory foundries and Chinese component assemblers. Tariff exposure on cross-border electronics shipments fragments regional fulfillment architectures. Distribution runs through certified refurbishment hubs in India and Germany serving localized contract volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as buyers migrate toward premium specifications embedding predictive replacement logistics and circular economy documentation. The shift from capital purchase to subscription consumption elevates service reliability over hardware acquisition cost.
For Market Incumbents:Cement defensive positioning through captive refurbishment capabilities that extend contract profitability across elongated lease terms. Invest in BSI and FedRAMP certification pipelines to compress public sector onboarding timelines against emerging competitors lacking authorization depth. Prioritize API development for SAP and Oracle integration at industrial Mittelstand accounts where legacy ERP synchronization creates switching costs.
For New Entrants and Emerging Players:Capture white-space in India's PLI-subsidized device assembly corridor by establishing localized refurbishment hubs serving South Asian enterprise demand. Target mid-market SMEs in Delhi-NCR and Bengaluru lacking internal hardware expertise for turnkey endpoint management offerings. Lead with circular economy metrics disclosure to differentiate against established providers in EU CSRD-mandated procurement evaluations.
For Investors and Strategic Acquirers:Cloud service providers and systems integrators are the most active acquirer in this space, seeking endpoint management capabilities to complement infrastructure portfolios. Evaluate targets with proven predictive logistics algorithms and established BSI certification pathways over pure hardware provisioning scale. Watch semiconductor price volatility and Taiwan supply concentration as inflection indicators for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Logistics Integration | Embedded telemetry agents at Dell and HP enable proactive failure detection reducing healthcare system downtime costs. |
| Refurbishment Hub Localization | India PLI incentives allow captive facility establishment serving South Asian contract volumes with reduced tariff exposure. |
| API Development for ERP Synchronization | SAP and Oracle integration capabilities lock in industrial Mittelstand accounts through asset lifecycle data continuity. |
| Circular Economy Certification | Blockchain-tracked chain-of-custody documentation satisfies EU CSRD disclosure mandates in German public sector procurement. |
| Edge-AI Subscription Tiering | On-device machine learning accelerator bundling creates differentiated pricing for inference-capable workstation deployments. |
Study Parameters
Direct dialogue with Daas procurement officers, IT asset managers, channel distribution heads, and regulatory compliance leads grounded quantitative modeling in operational reality. Secondary validation drew from SEC 10-K filings of hardware OEMs, EU CSRD disclosure databases, German BSI certification registries, and hyperscaler capex allocation reports. Bottom-up contract volume analysis triangulated against top-down endpoint shipment estimates across the projection horizon.
Bottom-up modeling aggregated individual contract values by deployment model, organization size, and hardware form factor throughout the forecast period. Segmentation dimensions included product type, service tier unbundling, and regional regulatory cluster. CAGRs derived from weighted average of historical subscription renewal rates and projected new contract origination by buyer archetype. Forecast inputs incorporated Taiwan ODM capacity utilization and EU NIS2 implementation timelines.
Semiconductor price volatility, Taiwan supply concentration, and EU regulatory enforcement intensity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on endpoint refresh cadence and residual value recovery rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
India ICT Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Virtual Office Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
IT Asset Management Market