
 North America Servicenow Store Apps Market | 2026-2036
North America Servicenow Store Apps Market Size, Share, and Industry Trends Forecast 2026-2036
North America Servicenow Store Apps Market Analytics
FedRAMP authorization is unwinding the competitive landscape for public sector Servicenow Store Apps deployment. ServiceNow leverages its native platform certification to sustain first-mover advantage in federal workflow automation. Deloitte anchors its position through deep systems integration capabilities across civilian and defense agencies. Accenture competes by combining cloud migration services with custom app development on the Now Platform.
Servicenow Store Apps are pre-certified software extensions built on the Now Platform, designed to extend IT service management, security operations, and HR workflows through standardized APIs and modular architecture. These apps integrate via ServiceNow's proprietary IntegrationHub and Flow Designer, enabling low-code automation across enterprise systems without core platform modification. IT Service Management applications dominate current revenue pools, while Security Operations extensions represent the fastest-growing segment as cyber governance mandates tighten. Public Cloud deployment models capture the majority of new implementations, though Hybrid Cloud configurations retain margin premiums in regulated industries requiring data residency controls.
HIPAA compliance obligations shape healthcare sector app requirements, while FedRAMP and StateRAMP frameworks gate federal and state-level procurement eligibility. The FCC's evolving cybersecurity labeling standards for communications infrastructure indirectly pressure telecom buyers toward certified automation tools. Procurement officers must evaluate whether vendor certification roadmaps align with their own compliance timelines.
Market Dynamics
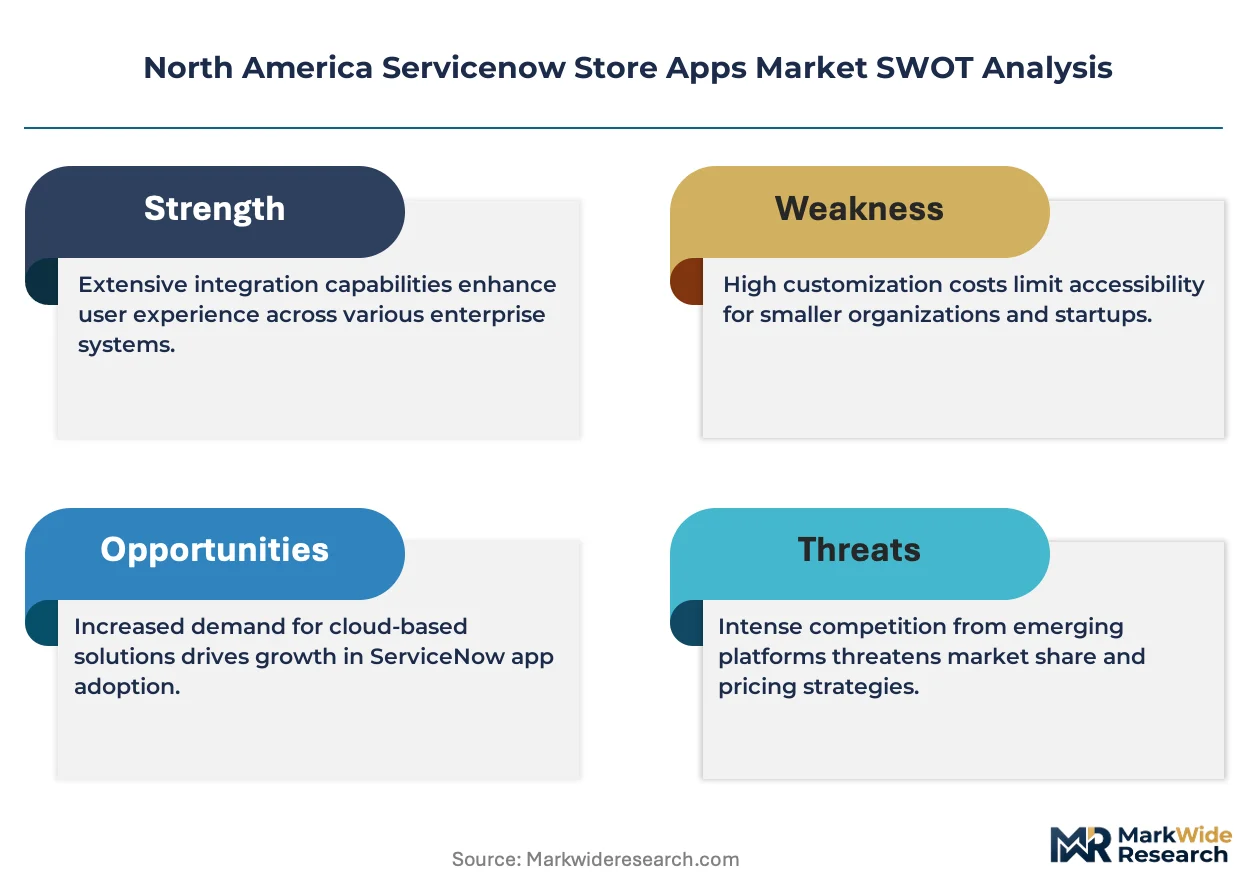
FedRAMP authorization requirements are restructuring competitive access to federal and state procurement channels, forcing vendors to align certification roadmaps with elongated government sales cycles.
Growth Catalysts
- StateRAMP framework expansion:State-level procurement bodies across Texas, California, and Illinois are adopting cloud security baselines that favor pre-certified Store Apps vendors. Municipal IT modernization grants accelerate workflow automation deployment.
- Healthcare cyber governance mandates:HIPAA Security Rule enforcement intensifies breach notification obligations. Large hospital systems in Boston and Minneapolis prioritize Security Operations extensions for automated incident response.
- Financial services automation:New York and Toronto banking regulators press for operational resilience frameworks. Tier-1 institutions deploy IT Service Management apps to satisfy operational continuity mandates.
Market Restraints
- FedRAMP certification timelines:Authorization processes extend 12-18 months for moderate-impact cloud services. Vendor backlog limits addressable public sector opportunity in the near term.
- Specialized integration talent scarcity:Flow Designer and IntegrationHub expertise concentrates in Dallas, Atlanta, and Seattle metro areas. Regional wage premiums compress implementation margins.
- Hybrid cloud infrastructure complexity:Regulated industries in Chicago and Montreal require data residency controls. Dual-environment deployment doubles architectural validation requirements.
Strategic Opportunities
- Canadian federal digital transformation:Shared Services Canada consolidates IT procurement across departments. Ottawa-based systems integrators lack Now Platform specialization, creating vendor entry paths.
- Telecom infrastructure automation:FCC cybersecurity labeling standards for communications equipment indirectly pressure carriers toward certified orchestration tools. 5G network operations centers in Denver and Phoenix represent greenfield deployment sites.
- AI-powered workflow convergence:Predictive analytics modules embedding within ITSM apps enable proactive incident management. Early adopters in San Francisco and Vancouver reduce mean-time-to-resolution metrics substantially.
Industry Challenges
- Multi-cloud API fragmentation:Enterprise buyers operate across AWS GovCloud, Azure Government, and on-premises environments. Store Apps must maintain certification parity across divergent infrastructure stacks.
- Legacy CMDB migration complexity:Federal agencies and provincial health authorities retain decades-old configuration databases. Data normalization consumes 40-60% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Servicenow Store Apps Market |
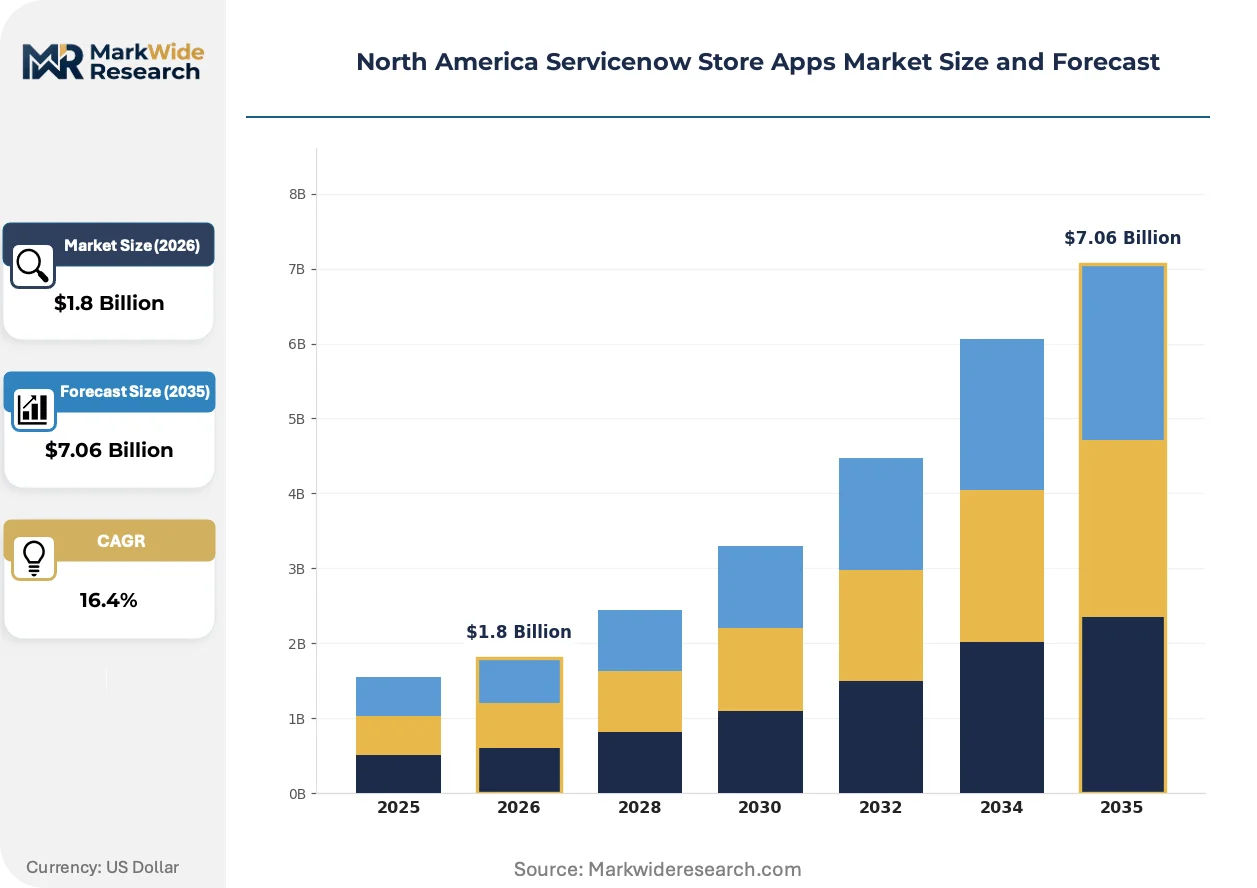
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: IT Service Management, Customer Service Management, HR Service Delivery, Security Operations Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises User Type: Enterprise Users, Small Business Users, Public Sector Users, Educational Institutions Functionality: Workflow Automation, Incident Management, Problem Management, Change Management |
| Companies Covered | ServiceNow, Accenture, Deloitte, Cognizant, IBM, SailPoint Technologies, Dynatrace, PagerDuty, TeamViewer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Servicenow Store Apps Market Evolving Landscape
Low-code automation interfaces are compressing the traditional systems integration value chain, enabling business units to deploy workflows without centralized IT intervention.
Agentic AI orchestration is supplanting rule-based automation in Security Operations workflows. Large financial institutions in Manhattan and Charlotte deploy autonomous response modules that execute containment actions without human approval. This capability compresses breach response windows from hours to minutes while reducing tier-1 security analyst headcount requirements.
StateRAMP reciprocity agreements with FedRAMP are harmonizing cloud security authorization across federal and state procurement channels. Texas and California procurement officers now accept moderate-impact federal authorizations for state agency deployments. Healthcare and education verticals in Austin and Sacramento accelerate vendor onboarding through streamlined attestation processes.
Business-unit-led procurement is fragmenting traditional enterprise software buying patterns. Department heads in Philadelphia and Vancouver bypass centralized IT evaluation to acquire specialized HR and Facilities apps directly. This shift pressures vendor pricing transparency and accelerates consumption-based licensing adoption among mid-market buyers.
North America Servicenow Store Apps Market Segmentation
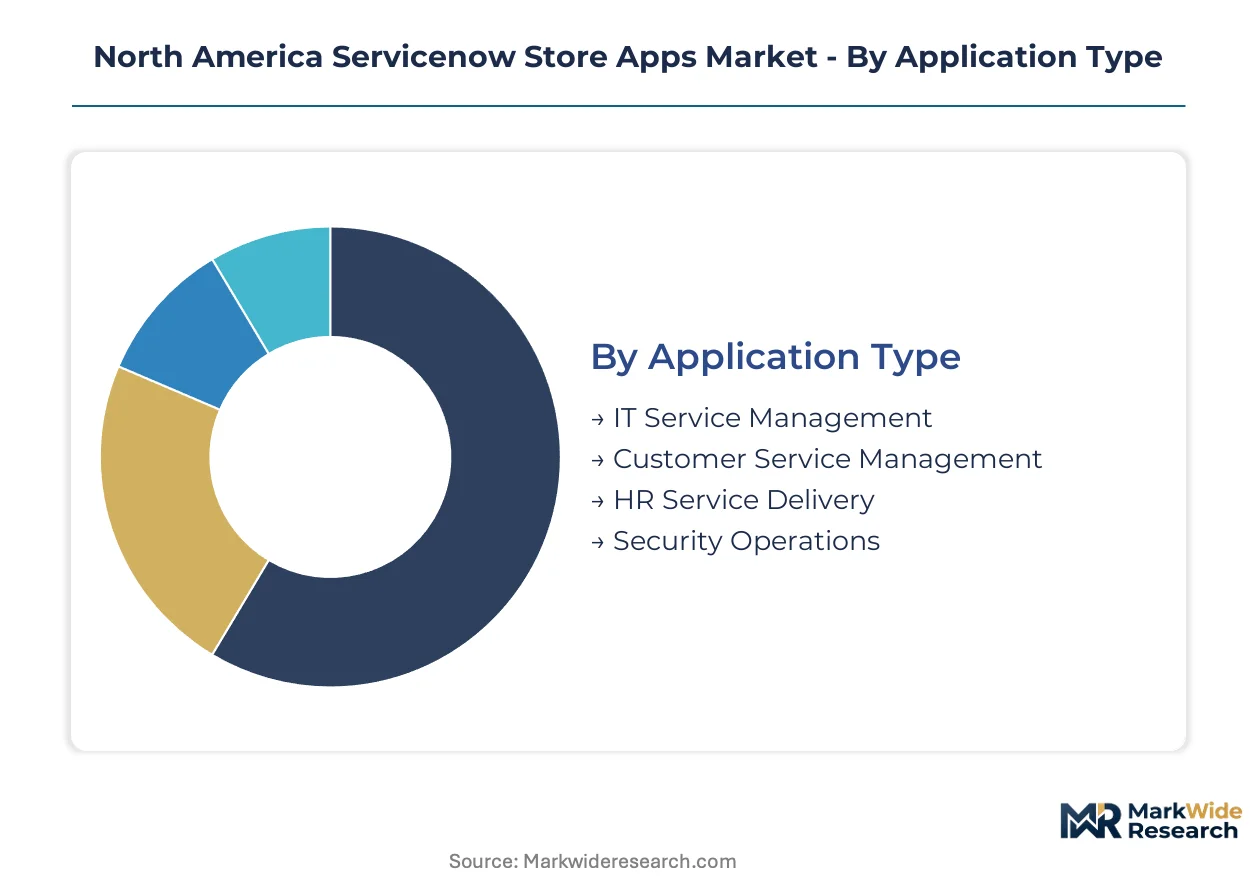
ServiceNow Store Apps segmentation reveals how compliance requirements and infrastructure constraints reshape purchasing patterns across federal, financial, and healthcare verticals. Procurement officers align deployment choices with data residency mandates and pre-certification availability.
Application Type:
FedRAMP authorization tiers create procurement friction that favors pre-certified application categories in federal and state channels.
- IT Service Management:Core workflow engines for incident, problem, and change management through ServiceNow's native ITSM framework. Large banks in New York and insurance carriers in Toronto deploy these modules to satisfy operational resilience mandates from NYDFS and OSFI regulators.
- Security Operations:Automated threat detection and response extensions integrating with SIEM platforms. Hospital systems in Boston and Minneapolis prioritize SOAR capabilities to compress HIPAA breach notification timelines under intensified OCR enforcement.
- Customer Service Management:Omnichannel case routing and field service optimization for external-facing operations.
- HR Service Delivery:Employee onboarding, case management, and workplace service automation.
IT Service Management handles the majority of throughput; Security Operations is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates volume plays from margin-rich specialized configurations.
- Public Cloud:Multi-tenant SaaS delivery through ServiceNow's government and commercial cloud instances. State agencies in Texas and California accelerate adoption via StateRAMP reciprocity agreements that streamline vendor onboarding.
- Hybrid Cloud:Split architectures maintaining sensitive data on-premises while leveraging cloud orchestration. Tier-1 Canadian banks in Montreal and Toronto deploy hybrid configurations to satisfy PIPEDA data residency requirements alongside OSFI operational continuity rules.
- Private Cloud:Dedicated single-tenant environments for isolated workload processing.
- On-premises:Fully air-gapped installations for classified or critical infrastructure environments.
Public Cloud captures the volume base; Hybrid Cloud commands the steepest margin premiums.
User Type:
Customer maturity and procurement sophistication determine solution complexity and sales cycle length.
- Enterprise Users:Fortune 500 corporations with dedicated platform teams and multi-year roadmaps. Federal civilian agencies and defense departments in Washington D.C. and Colorado Springs mandate FedRAMP Moderate or High baselines for all cloud acquisitions.
- Public Sector Users:Federal, state, and municipal agencies subject to specialized procurement frameworks. Municipal IT modernization grants in Illinois and Ohio accelerate workflow automation deployment among mid-size cities lacking internal development capacity.
- Small Business Users:Mid-market firms purchasing through channel partners or direct self-service.
- Educational Institutions:Universities and K-12 districts with constrained IT budgets and shared service models.
Enterprise Users anchor current revenue; Public Sector Users are expanding most quickly as StateRAMP adoption broadens.
Functionality:
Implementation depth and integration complexity separate commodity automation from strategic platform investments.
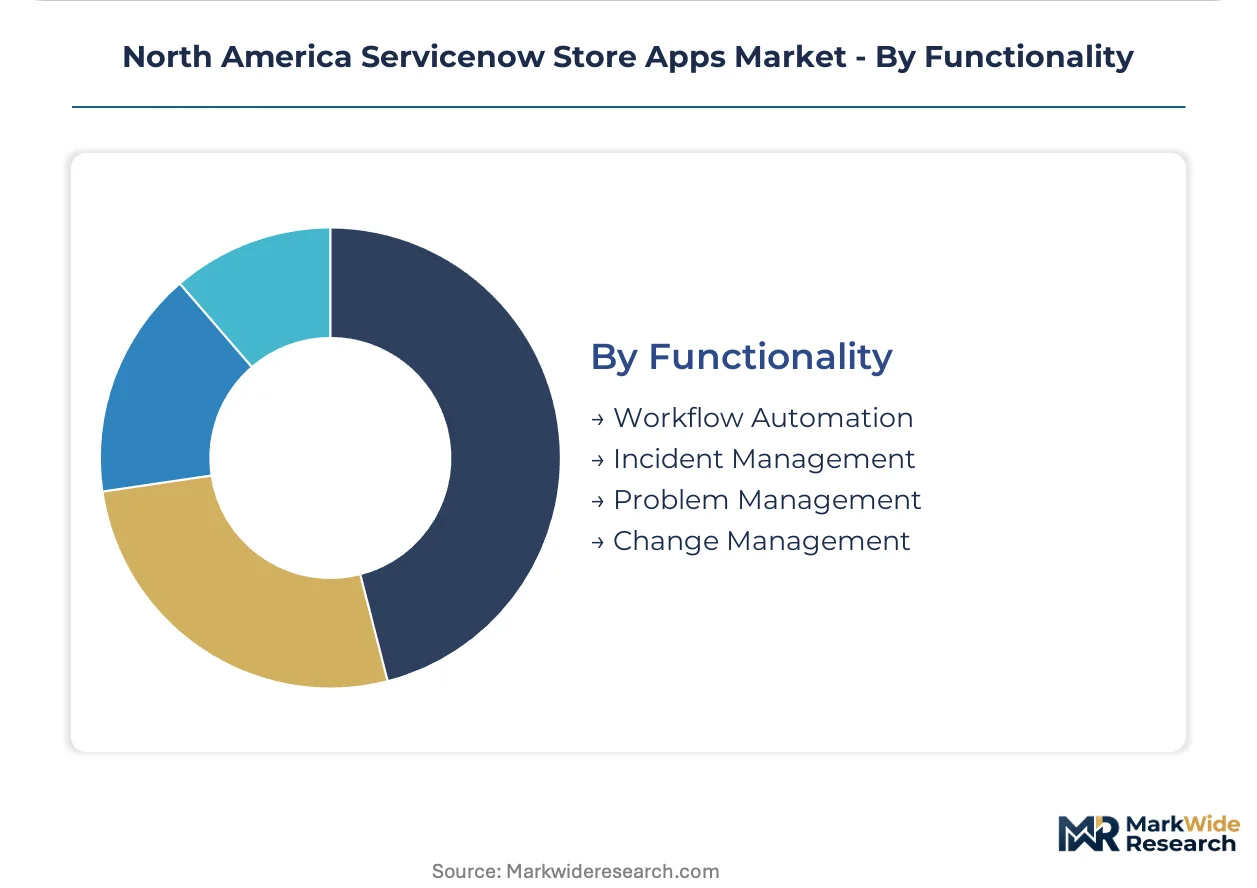
- Workflow Automation:Low-code process design through Flow Designer and IntegrationHub connectors. Business units in Philadelphia and Vancouver bypass centralized IT to deploy departmental HR and facilities workflows directly.
- Incident Management:Structured response protocols for service disruptions and security events. 5G network operations centers in Denver and Phoenix embed automated incident orchestration to meet FCC cybersecurity labeling standards for communications infrastructure.
- Problem Management:Root cause analysis and permanent corrective action tracking.
- Change Management:Controlled release coordination with risk assessment and approval gates.
Workflow Automation dominates deployment velocity; Incident Management is climbing the fastest as cyber governance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States and Canada dominate procurement volumes, with federal agencies and tier-1 financial institutions driving certification-heavy deployment patterns across both nations.
United States
Federal civilian agencies and defense departments in Washington D.C. and Colorado Springs mandate FedRAMP Moderate or High baselines for all cloud acquisitions. The FCC's cybersecurity labeling standards for communications infrastructure indirectly pressure telecom carriers toward certified orchestration tools. Large banks in New York deploy IT Service Management apps to satisfy NYDFS operational resilience mandates.
Canada
Shared Services Canada consolidates IT procurement across federal departments, creating concentrated demand for pre-certified workflow solutions. PIPEDA data residency requirements and OSFI operational continuity rules push tier-1 banks in Toronto and Montreal toward hybrid cloud configurations. Ottawa-based systems integrators lack Now Platform specialization, opening vendor entry paths.
Texas
State-level procurement bodies in Austin have adopted StateRAMP cloud security baselines that favor pre-certified Store Apps vendors. Municipal IT modernization grants accelerate workflow automation deployment among mid-size cities lacking internal development capacity. Dallas metro area concentrates scarce Flow Designer and IntegrationHub expertise, driving regional wage premiums.
California
Procurement officers in Sacramento now accept moderate-impact federal authorizations for state agency deployments through StateRAMP reciprocity agreements. Healthcare and education verticals in San Francisco accelerate vendor onboarding through streamlined attestation processes. Silicon Valley early adopters embed predictive analytics modules within ITSM apps to compress mean-time-to-resolution metrics.
Illinois
Municipal IT modernization grants in Chicago accelerate workflow automation deployment among mid-size cities with constrained internal capacity. Hybrid cloud infrastructure complexity in regulated industries requires data residency controls that double architectural validation requirements. Regional hospital systems prioritize Security Operations extensions for automated incident response under intensified breach notification obligations.
North America Servicenow Store Apps Market Competitive Landscape
Player mix skews toward systems integrators and native platform vendors with established certification credentials. The competitive landscape consolidates around entities possessing FedRAMP authorization and deep IntegrationHub expertise. Three archetypes dominate: native platform vendors leveraging first-mover certification advantage, global consultancies combining cloud migration with custom development, and specialized workflow boutiques. Dominant competitive moves include strategic partnerships to accelerate certification roadmaps and portfolio diversification into adjacent automation segments.
Within the native platform tier, ServiceNow occupies the anchor position through proprietary platform certification. Among global consultancies, Accenture and Deloitte exemplify the systems integration archetype, with the former combining cloud migration services and the latter anchoring civilian and defense agency relationships. These three entities represent the certification-heavy procurement channel that federal and state buyers increasingly favor.
| Leading Market Players |
|---|
| ServiceNow |
| Accenture |
| Deloitte |
| Cognizant |
| IBM |
| SailPoint Technologies |
| Dynatrace |
| PagerDuty |
| TeamViewer |
| Others |
Value Network & Pricing Analysis
Eighteen-month FedRAMP authorization timelines concentrate vendor pricing power among pre-certified incumbents while compressing margins for aspirants awaiting clearance. Procurement officers in Washington D.C. and Ottawa accept substantial premiums for authorized deployments, creating tiered value capture across the certification divide.
Pricing Analysis
Cost-plus contracts indexed to labor-rate escalators dominate systems integration engagements, with Accenture and Deloitte embedding annual CPI adjustments into multi-year federal awards. Three-tier pricing stratifies across FedRAMP High, Moderate, and commercial cloud baselines, with certification grade commanding steeper differentiation than feature depth. Cost compression in mid-market SaaS tiers intensifies as self-service procurement fragments traditional enterprise sales cycles. Small business users exhibit acute price sensitivity, while defense agencies prioritize authorization speed over unit economics.
Supply Chain Analysis
Ninety-day implementation backlogs for IntegrationHub specialists in Dallas and Seattle signal talent scarcity propagating through delivery timelines. Platform engineering expertise concentrates in the United States, Canada, and India, with Hyderabad development centers feeding U.S. federal channel demand. Proprietary API dependencies on ServiceNow's IntegrationHub and Flow Designer tether implementation quality to vendor certification status. Single-source vulnerability in specialized workflow boutiques elevates acquisition premiums. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ServiceNow Store Apps represent a service-attach opportunity where managed workflow optimization and continuous compliance monitoring expand recurring revenue faster than initial platform licensing.
For Market Incumbents: Secure FedRAMP High authorization ahead of defense agency consolidation waves, then anchor civilian expansion through StateRAMP reciprocity. Acquire boutique Flow Designer specialists in Atlanta and Denver before wage premiums render captive talent uneconomical. Threat: Agentic AI orchestration modules from autonomous response vendors displace rule-based automation margins. For New Entrants and Emerging Players: Anchor in Canadian federal procurement where Shared Services Canada consolidation outpaces Ottawa systems integrator capacity. Target municipal IT modernization grants in Illinois and Ohio where pre-certified vendors remain underrepresented. Go-to-market angle: Fixed-price rapid deployment packages compressing legacy CMDB migration timelines for provincial health authorities. For Investors and Strategic Acquirers: Carve-out targets emerge from global consultancies spinning non-core workflow automation practices lacking platform-specific certification depth. Long-term viability hinges on sustaining authorization moats as StateRAMP adoption broadens competitive access. Acquisition archetype: Regional systems integrators with dormant FedRAMP Moderate credentials and established federal relationships. Signal to watch: Reciprocity agreement expansion beyond Texas and California into northeastern state procurement bodies.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP High Authorization Investment | Defense agency eligibility unlocks Colorado Springs and Pentagon-adjacent procurement channels. |
| StateRAMP Reciprocity Expansion | Streamlined attestation accelerates vendor onboarding in Sacramento and Austin procurement offices. |
| Agentic AI Module Integration | Autonomous response capabilities compress breach windows for Manhattan financial institutions. |
| Hybrid Cloud Architecture Certification | PIPEDA compliance enables Toronto and Montreal tier-1 banking deployments. |
| IntegrationHub Specialist Acquisition | Dallas and Seattle talent scarcity elevates captive expertise value in federal delivery. |
Research Methodology
A spread of perspectives from federal procurement officers, platform engineers at ServiceNow, systems integration leads at Deloitte and Accenture, and municipal IT directors in Chicago and Houston converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FedRAMP authorization databases, StateRAMP reciprocity agreements, and SEC filings from publicly traded workflow vendors. Bottom-up deployment estimates triangulated against top-down addressable market calculations.
Segmentation dimensions modeled span deployment model, application type, user maturity tier, and FedRAMP authorization status across the projection horizon. CAGRs derived from deployment velocity curves weighted by certification pipeline visibility. Industry-specific forecast inputs include municipal IT modernization grant disbursement rates and defense agency cloud migration mandate timelines.
Material uncertainties — authorization timeline delays, StateRAMP adoption heterogeneity, AI orchestration capability disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory reciprocity expansion and talent concentration persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
PCB CAD Software Market
Software & Services
School Timetable Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Global Automation Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Push Notifications Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Enterprise Application Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Home Design Software Market
Software & Services
Mobile Application Stores Market