
 GCC and Africa ICT Market | 2026-2036
GCC and Africa ICT Market Size, Share, and Industry Trends Forecast 2026-2036
GCC and Africa ICT Market Insights
Copper-based legacy cabling is consolidating toward fiber-optic infrastructure across Gulf data center builds, slashing latency-per-dollar for enterprise clients. Huawei Technologies Co., Ltd. anchors submarine cable projects linking Mombasa to Fujairah. Microsoft Corporation leverages hyperscale cloud campuses in Johannesburg and Dubai. Emirates Telecommunications Group Company PJSC (e&) dominates last-mile fiber rollout across Abu Dhabi and Riyadh.
Information and communications technology in the GCC and Africa encompasses the hardware, software, and services enabling data transmission, storage, and processing across enterprise and consumer networks, with fiber-optic backbones achieving sub-10 millisecond latency and 5G base stations operating in sub-6 GHz and millimeter-wave spectrum bands. Cloud Services within the Service Type dimension captures the fastest margin expansion as sovereign cloud requirements multiply across Gulf states. Artificial Intelligence under Technology sits at early commercialization in African markets but attracts disproportionate venture inflow relative to installed base. Hybrid Cloud across Deployment Model leads enterprise spending as banks and telecom operators straddle compliance mandates with scalability needs.
Saudi Arabia's National Cybersecurity Authority and South Africa's Information Regulator enforce data localization standards that redirect procurement toward domestic or regional providers. The UAE's Telecommunications and Digital Government Regulatory Authority certifies 5G equipment vendors under national security protocols, filtering market access. Nigeria's National Information Technology Development Agency pushes indigenous content quotas into federal IT contracts. Stakeholders must weigh sovereign data requirements against the capital efficiency of centralized global cloud architectures.
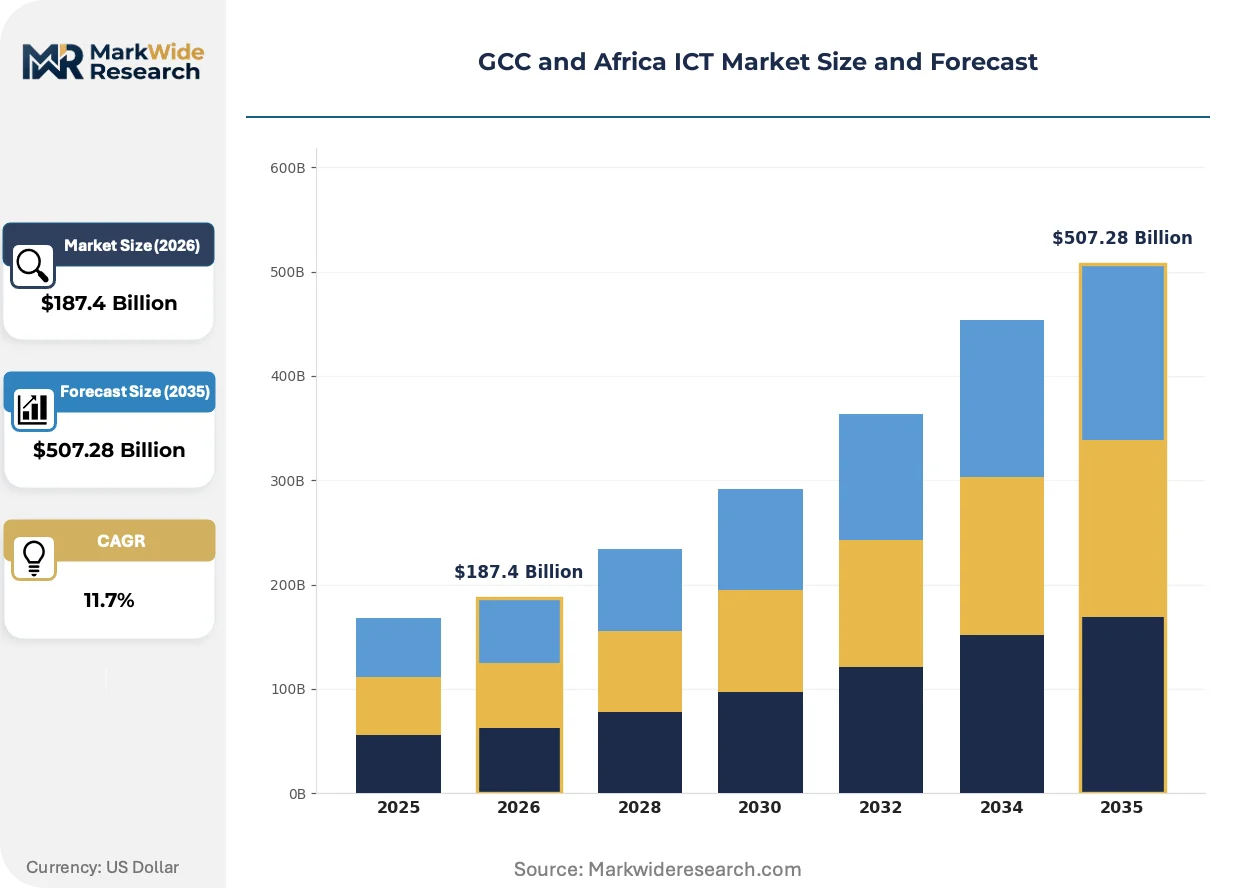
Market Dynamics
Data sovereignty mandates across Gulf Cooperation Council states and African economies are fragmenting cloud procurement patterns, forcing enterprise buyers to choose between compliance-aligned regional deployments and cost-optimized global architectures.
Growth Catalysts
- Sovereign Cloud Mandates:Saudi Arabia's Personal Data Protection Law and South Africa's POPIA compel financial institutions to retain customer data within national borders, redirecting infrastructure spending toward domestic and regional providers.
- 5G Spectrum Allocation:The UAE's Telecommunications and Digital Government Regulatory Authority has certified sub-6 GHz and millimeter-wave equipment vendors, accelerating base station deployment across Abu Dhabi and Dubai.
- Submarine Cable Expansion:Fiber-optic backbones linking Mombasa to Fujairah are slashing latency-per-dollar for enterprise clients, consolidating demand toward low-latency corridors.
Market Restraints
- Capital Intensity of Hyperscale Builds:Cloud campus construction in Johannesburg and Dubai requires sustained multi-year capex commitments that strain balance sheets of regional operators.
- Equipment Vendor Concentration:5G base station supply concentrates among a narrow vendor base, exposing procurement timelines to single-source risks.
- Legacy Copper Infrastructure:Last-mile fiber rollout must navigate existing copper-based networks, creating stranded asset concerns for incumbent telecom operators.
Strategic Opportunities
- Hybrid Cloud Adoption:Banks and telecom operators across Nigeria and Kenya are straddling compliance mandates with scalability needs, creating demand for workload orchestration between private and public environments.
- Artificial Intelligence Commercialization:Early-stage AI deployment in African markets attracts disproportionate venture inflow relative to installed base, signaling white space for application-layer providers.
- Indigenous Content Quotas:Nigeria's National Information Technology Development Agency mandates local participation in federal IT contracts, opening procurement pathways for domestic systems integrators.
Industry Challenges
- Cross-Border Data Governance:Enterprises must architect flows that satisfy Saudi Arabia's National Cybersecurity Authority localization standards while maintaining interoperability with global SaaS platforms.
- Skill Scarcity in Fiber Deployment:Splicing and termination expertise for hyperscale data center builds remains concentrated among specialized contractor networks, constraining rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC and Africa ICT Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Managed Services, Network Services, Data Centers Technology: 5G, IoT, Blockchain, Artificial Intelligence End User: Government, Healthcare Providers, Financial Institutions, Telecommunications Deployment Model: Hybrid Cloud, Private Cloud, Public Cloud, On-Premises |
| Companies Covered | Microsoft Corporation, HP Inc., SAP SE, Alphabet Inc., International Business Machines Corporation, Emirates Telecommunications Group Company PJSC (e&), Saudi Telecom Company, Ooredoo Q.P.S.C., Huawei Technologies Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC and Africa ICT Market Trends and Innovations
Competitive positioning in GCC and Africa ICT markets is electrifying around latency arbitrage, with fiber depth and edge proximity becoming primary differentiators for enterprise cloud contracts.
Multi-core fiber cables are electrifying data center interconnects across Gulf builds. Wholesale colocation providers in Dubai and Riyadh are adopting ribbon fiber architectures to maximize duct utilization. This compression of fiber count-per-conduit is electrifying price-per-bit economics for cross-border traffic exchange.
Saudi Arabia's National Cybersecurity Authority has issued mandatory certification requirements for cloud service providers handling government data. Operators must demonstrate in-country data residency and encryption key localization. Financial services entities in Riyadh are responding by segmenting workloads across certified sovereign zones and non-certified global regions.
Enterprise buyers are unbundling managed service contracts that previously bundled connectivity, compute, and professional services. Large Nigerian banks now procure fiber transport, cloud capacity, and systems integration through separate RFP processes. This disintermediation is most visible in Lagos, where procurement teams have established dedicated vendor management functions for infrastructure layers.
GCC and Africa ICT Market Segmentation
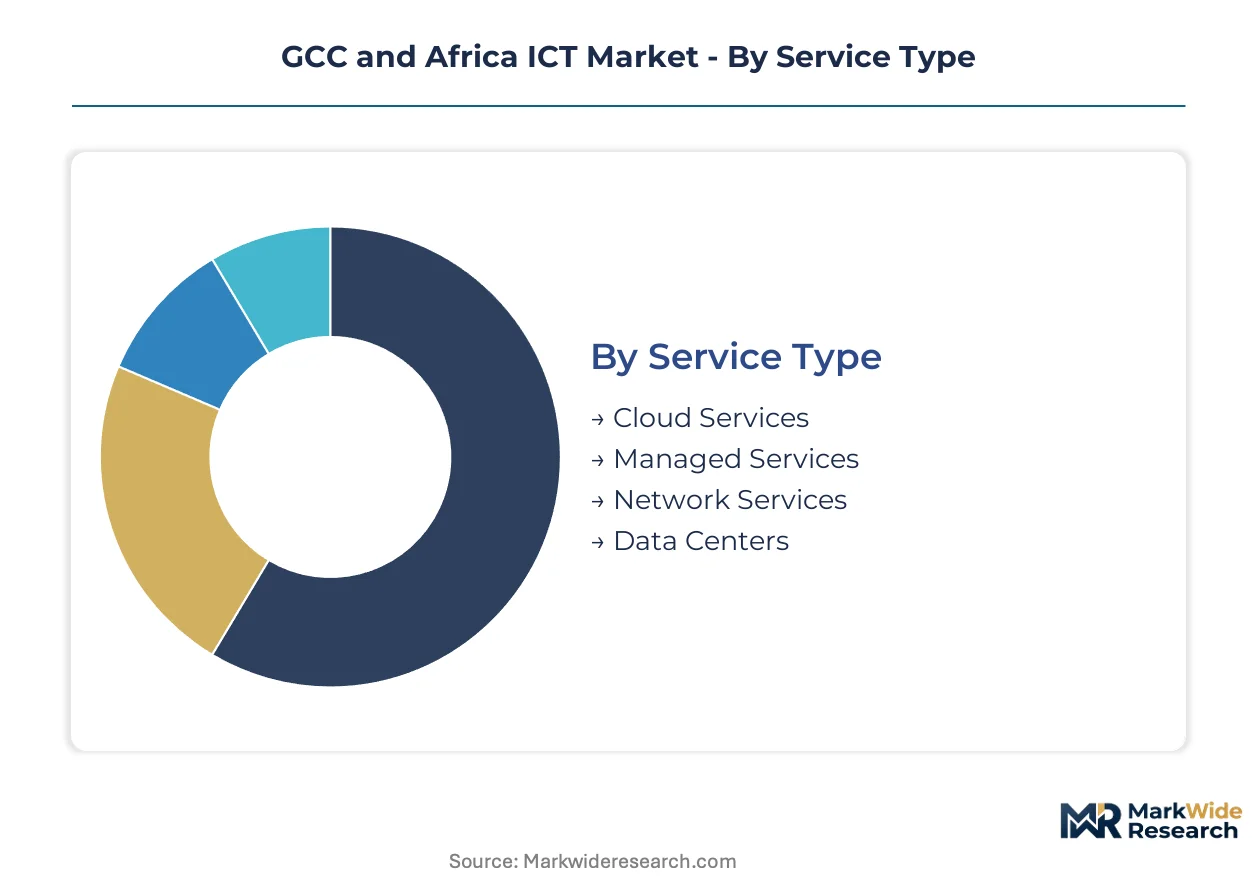
ICT procurement across the GCC and Africa fragments along four distinct axes. Each dimension carries divergent capital requirements, regulatory exposure, and vendor qualification thresholds that reshape competitive positioning.
Service Type:
Cloud Services and Data Centers demand the heaviest upfront infrastructure commitment, with hyperscale builds in Dubai and Johannesburg requiring multi-year capex cycles.
- Cloud Services:Sovereign cloud deployments dominate procurement conversations across Saudi Arabia and the UAE. Saudi Arabia's National Cybersecurity Authority mandates in-country data residency for government workloads, redirecting financial institutions toward certified domestic providers.
- Data Centers:Wholesale colocation facilities in Riyadh and Lagos absorb enterprise demand for latency-sensitive workloads. Ribbon fiber architectures maximize duct utilization, compressing price-per-bit economics for cross-border traffic exchange.
- Managed Services:Nigerian banks now unbundle connectivity, compute, and integration into separate RFP processes.
- Network Services:Submarine cable landing stations linking Mombasa to Fujairah anchor regional bandwidth pricing.
Data Centers absorb the bulk of installed capacity; Cloud Services is expanding most quickly.
Technology:
5G base station deployment concentrates capital expenditure among spectrum license holders in the UAE and Saudi Arabia, while Artificial Intelligence attracts venture inflow disproportionate to current commercial scale.
- 5G:Sub-6 GHz and millimeter-wave equipment certification by the UAE's Telecommunications and Digital Government Regulatory Authority filters vendor access. Abu Dhabi and Dubai lead base station density across the Gulf.
- Artificial Intelligence:Early commercialization in African markets lags installed base but draws disproportionate venture capital relative to current deployment scale.
- IoT:Industrial sensor networks in Kenyan agriculture and Nigerian logistics drive edge compute demand.
- Blockchain:Central bank digital currency pilots in Nigeria and South Africa test distributed ledger infrastructure at scale.
5G carries the deepest installed base; Artificial Intelligence climbs the fastest.
End User:
Financial Institutions face the most stringent compliance overlay, with Saudi Arabia's Personal Data Protection Law and South Africa's POPIA imposing data localization mandates that inflate infrastructure costs.
- Financial Institutions:Banks across Nigeria and Kenya segment workloads across sovereign-certified zones and non-certified global regions. Procurement teams in Lagos have established dedicated vendor management functions for infrastructure layers.
- Government:Federal IT contracts in Nigeria carry indigenous content quotas from the National Information Technology Development Agency.
- Telecommunications:Incumbent operators in Abu Dhabi and Riyadh navigate stranded copper assets during last-mile fiber overbuilds.
- Healthcare Providers:Hospital networks in Johannesburg and Dubai consolidate electronic medical record systems onto hybrid architectures.
Telecommunications retains the largest legacy installed base; Financial Institutions gain share fastest.
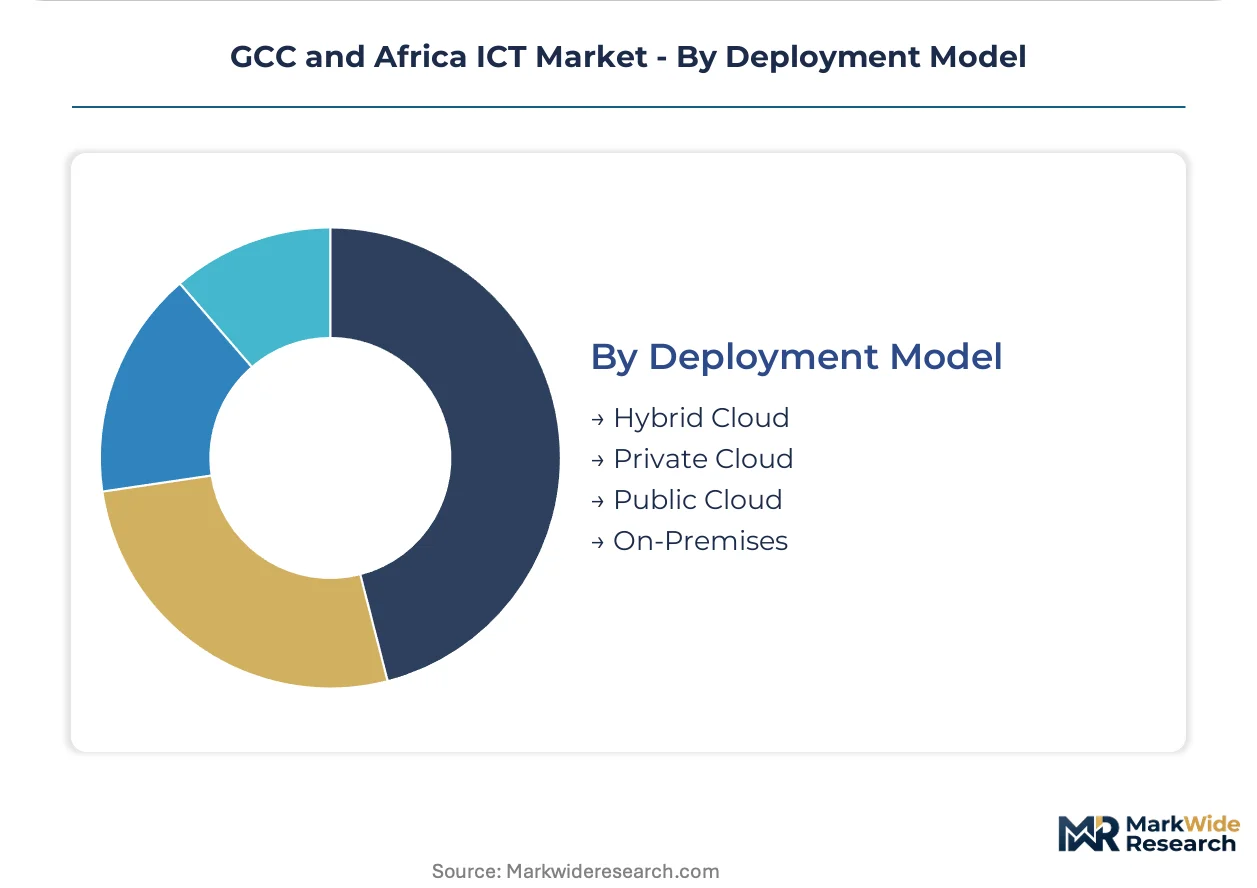
Deployment Model:
Hybrid Cloud configurations impose the most complex architectural demands, forcing banks and telecom operators to orchestrate workloads across private infrastructure and public platforms while satisfying divergent compliance regimes.
- Hybrid Cloud:Workload orchestration between private and public environments dominates enterprise architecture discussions. Kenyan banks straddle scalability needs with South Africa's POPIA localization requirements.
- Private Cloud:Single-tenant infrastructure satisfies Saudi Arabia's National Cybersecurity Authority encryption key localization mandates.
- Public Cloud:Global hyperscale campuses in Johannesburg and Dubai compete on price-per-compute-cycle.
- On-Premises:Legacy mainframe retention persists in South African financial services compliance environments.
On-Premises retains residual installed capacity; Hybrid Cloud shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise cloud procurement concentrates in financial services clusters across Lagos, Johannesburg, and Riyadh, where data residency mandates redirect infrastructure spending toward certified domestic facilities.
United Arab Emirates
Dubai and Abu Dhabi host hyperscale cloud campuses serving Gulf financial institutions. The Telecommunications and Digital Government Regulatory Authority certifies 5G equipment vendors under national security protocols, filtering market access. Ribbon fiber architectures in Dubai Internet City maximize duct utilization for cross-border traffic exchange.
Saudi Arabia
Riyadh anchors sovereign cloud demand as banks segment workloads across certified zones. The National Cybersecurity Authority mandates in-country data residency and encryption key localization for government workloads. Wholesale colocation facilities in Riyadh absorb latency-sensitive enterprise demand.
South Africa
Johannesburg concentrates hybrid cloud adoption among financial institutions navigating POPIA localization requirements. The Information Regulator enforces data governance standards that inflate infrastructure costs for cross-border data flows. Cape Town hosts submarine cable landing stations linking to Mombasa and Fujairah corridors.
Nigeria
Lagos drives unbundled procurement patterns as banks separate connectivity, compute, and integration into distinct vendor relationships. The National Information Technology Development Agency mandates indigenous content quotas in federal IT contracts. Enterprise buyers in Lagos have established dedicated infrastructure vendor management functions.
Kenya
Nairobi anchors East African cloud demand as agricultural and logistics IoT networks drive edge compute requirements. Mombasa serves as the submarine cable landing point for fiber backbones linking to Fujairah, slashing latency-per-dollar for regional enterprise clients. Kenyan banks straddle scalability needs with South African POPIA compliance for cross-border operations.
GCC and Africa ICT Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud operators consolidating compute capacity while telecom incumbents defend last-mile connectivity positions. The vendor base organizes around three archetypes: global hyperscale platforms, regional sovereign cloud specialists, and infrastructure equipment vendors. Competitive dynamics center on M&A activity targeting fiber depth and strategic partnerships bridging compliance mandates with global architecture efficiency.
Among global technology platforms, Microsoft Corporation and Alphabet Inc. occupy positions anchoring hyperscale cloud demand across Johannesburg and Dubai campuses. Within the regional telecom tier, Emirates Telecommunications Group Company PJSC (e&) exemplifies the incumbent fiber rollout specialist, while Huawei Technologies Co., Ltd. represents the infrastructure equipment archetype linking submarine cable projects across the Mombasa-Fujairah corridor.
| Leading Market Players |
|---|
| Microsoft Corporation |
| HP Inc. |
| SAP SE |
| Alphabet Inc. |
| International Business Machines Corporation |
| Emirates Telecommunications Group Company PJSC (e&) |
| Saudi Telecom Company |
| Ooredoo Q.P.S.C. |
| Huawei Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fiber-splicing technician pools concentrated in the UAE and South Africa generate labor-cost differentials that widen pricing-tier spreads between premium latency-optimized deployments and standard connectivity offerings across Gulf data center markets.
Pricing Analysis
Volume concentrates in wholesale colocation contracts while margins accrue to sovereign-certified cloud services. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost. Cost compression in the standard tier is intensifying because global hyperscalers are competing on price-per-compute-cycle in Johannesburg and Dubai. Financial institutions show least price sensitivity due to compliance mandates, while mid-market enterprises in Kenya and Nigeria exhibit highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Dubai and Johannesburg anchor hub-and-spoke patterns for equipment deployment across East and West Africa. Manufacturing concentrates in China, South Korea, and Taiwan for 5G base stations, fiber-optic cables, and server hardware. The supply chain draws from optical fiber preform, semiconductor components, and precision cooling systems. Single-source vulnerability in 5G equipment creates procurement timeline exposure. Distribution runs through certified systems integrators and direct vendor relationships with hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC and Africa ICT market sits in a technology-transition phase as fiber-optic infrastructure displaces copper-based legacy networks across enterprise and consumer deployments.
For Market Incumbents: Cement fiber depth advantages through accelerated last-mile overbuilds in Abu Dhabi and Riyadh before stranded copper assets erode returns. Invest in sovereign cloud certification to defend against global hyperscaler encroachment under Saudi Arabia's National Cybersecurity Authority mandates. Prioritize workforce development in fiber-splicing specialties to constrain rollout velocity for competitors.
For New Entrants and Emerging Players: Cloud marketplace platforms offer lower customer acquisition costs than direct enterprise sales for AI application-layer providers targeting early commercialization in African markets. Prioritize edge compute deployments for agricultural IoT networks in Kenya and logistics sensor integration in Nigeria. Pursue indigenous content quota compliance to access federal IT contracts under Nigeria's National Information Technology Development Agency mandates.
For Investors and Strategic Acquirers: Re-rating potential sits with regional sovereign cloud specialists given Saudi Arabia's Personal Data Protection Law and South Africa's POPIA redirecting financial institution procurement toward compliant domestic providers. Long-term viability hinges on fiber asset depth and certification portfolio breadth. Watch submarine cable landing rights in Mombasa and Fujairah as inflection indicators for bandwidth pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Saudi Arabia's National Cybersecurity Authority mandates redirect government procurement toward compliant domestic providers. |
| Submarine Cable Expansion | Fiber backbones linking Mombasa to Fujairah slash latency-per-dollar for regional enterprise cloud contracts. |
| Hybrid Cloud Platform Integration | Kenyan banks orchestrate workloads across private infrastructure and public platforms to satisfy POPIA requirements. |
| Indigenous Content Compliance | Nigeria's National Information Technology Development Agency opens federal IT procurement to qualified domestic integrators. |
| 5G Equipment Vendor Diversification | The UAE's Telecommunications and Digital Government Regulatory Authority certification filters reduce single-source procurement risk. |
Research Methodology
Independent corroboration across hyperscaler capex disclosures, telecom regulatory filings, and submarine cable consortium announcements underwrites the qualitative findings in this study. Primary interviews with data center operations directors, cloud procurement officers at Nigerian banks, fiber deployment contractors, and regulatory affairs specialists at Gulf telecom operators combined with secondary validation from SEC filings, TRAI spectrum auction records, and customs trade data. Bottom-up project pipeline analysis and top-down market sizing triangulate volume estimates.
Comparable historical deployment cycles across the 2015-2020 fiber buildout wave anchored the forecast window to observed adoption S-curves. The analytical framework models service type, technology, end user, and deployment mode segmentation dimensions throughout the forecast period. CAGRs derive from installed base growth rates adjusted for replacement demand and greenfield penetration. Forecast inputs include spectrum allocation timelines, data center power capacity additions, and sovereign certification rollout schedules.
The model holds under stable regulatory enforcement of data localization mandates; deviation in cross-border data governance harmonization or submarine cable route security would shift cloud procurement patterns. Forecasts reflect documented assumptions about 5G base station deployment velocity and hyperscale campus completion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Beacons Management Software Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Data Converter Market
Digital Solutions
Crowdsourcing Market