
 Conference Room Solutions Market | 2026-2036
Conference Room Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Conference Room Solutions Market Analysis
China is tilting toward domestic manufacturing of unified communications hardware. Logitech leverages its supply chain scale to dominate peripheral categories across enterprise channels. Crestron Electronics anchors high-end integrated systems through dealer-exclusive distribution. Cisco Systems competes in cloud-native room platforms with Webex infrastructure tie-ins.
Conference room solutions encompass integrated audiovisual, computing, and networking equipment designed for synchronous group communication, typically supporting 1080p or 4K video resolution, full-duplex audio with acoustic echo cancellation, and sub-150ms latency for real-time interaction. These systems serve commercial environments requiring scheduled or ad-hoc collaboration sessions among distributed participants. Video conferencing systems capture the largest revenue pool among product types, reflecting enterprise refresh cycles and IT standardization mandates. Cloud-based solutions within the technology dimension represent the fastest-expanding segment as organizations retire on-premise infrastructure. Corporates as an end-user category sustain premium pricing, while co-working spaces drive volume through multi-tenant scalable deployments.
FCC Part 15 emissions standards govern wireless connectivity modules in US-sold equipment, while CE marking under the EU Radio Equipment Directive enables market access across member states. ISO/IEC 27001 certification pressures vendors to embed information security management into cloud-based and hybrid system architectures. Stakeholders must weigh interoperability commitments against proprietary ecosystem lock-in as platform consolidation reshapes procurement criteria.
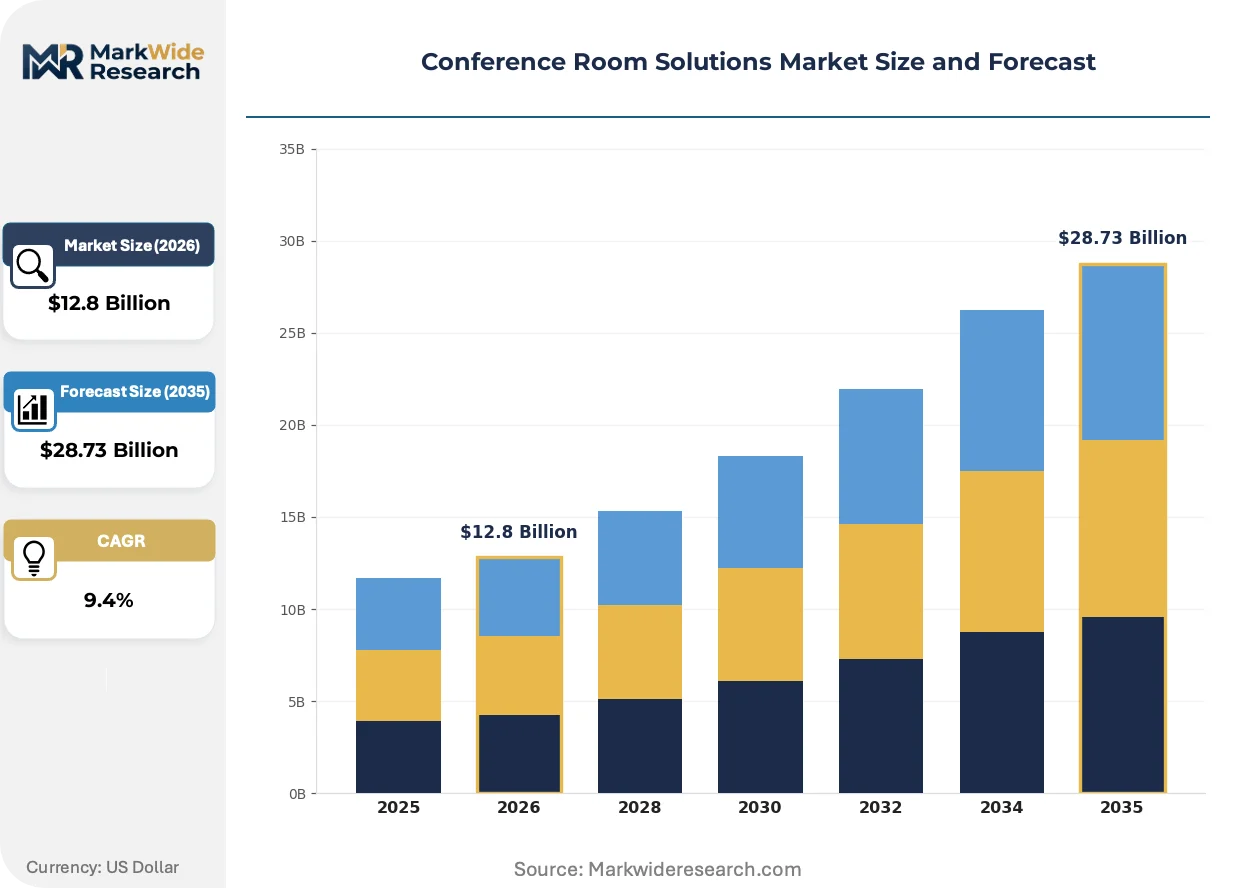
Market Dynamics
Enterprise IT standardization around cloud-native architectures is compressing refresh cycles and forcing hardware vendors to recalibrate around recurring software revenue models rather than capital equipment sales.
Growth Catalysts
- Hybrid workplace mandates:Fortune 500 facility managers in the United States are retrofitting 40% of meeting spaces with integrated AV systems to support distributed teams. Corporate real estate budgets now prioritize collaboration technology over square footage expansion.
- FCC Part 15 certification streamlining:Faster equipment authorization timelines for wireless conferencing peripherals accelerate product launches and reduce time-to-revenue for hardware vendors serving North American enterprises.
- Acoustic AI processing:Machine learning-driven noise cancellation algorithms embedded in ceiling microphone arrays eliminate the need for distributed table microphones, reducing installation complexity and cabling costs.
Market Restraints
- Semiconductor supply concentration:Video codec chip fabrication concentrates among TSMC and Samsung foundries in Taiwan and South Korea, creating vulnerability to geopolitical disruption and allocation constraints during demand surges.
- Copper and rare earth input volatility:Magnet materials for speaker drivers and HDMI cable assemblies face price swings tied to Chinese export quotas, compressing hardware margins at the mid-tier product level.
- Latency floor in satellite-dependent deployments:Sub-150ms real-time interaction requirements exclude Starlink and similar low-earth-orbit connectivity from viable enterprise conference room backhaul in remote locations.
Strategic Opportunities
- India co-working penetration:WeWork India and Awfis are scaling multi-tenant facilities in Bangalore and Mumbai faster than dedicated IT staffing permits, creating demand for turnkey room systems with zero-configuration deployment.
- EU CSRD reporting integration:Sustainability disclosure mandates push corporate procurement teams to favor vendors with ISO 14001-certified manufacturing and carbon-neutral shipping for hardware refresh programs.
- AI-whiteboard convergence:Computer vision-enabled capture systems merging with generative AI summarization tools create premium pricing power in executive briefing rooms and board installations.
Industry Challenges
- Certification timeline compression:CE marking under the EU Radio Equipment Directive now requires expanded cybersecurity documentation, extending product launch schedules by 8-12 weeks for hybrid cloud-room systems.
- Legacy analog integration friction:Government and education sector buyers in Germany and Japan retain substantial installed bases of VGA and 3.5mm audio infrastructure, forcing vendors to maintain obsolete port configurations and support burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conference Room Solutions Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Conferencing Systems, Collaboration Boards, Audio Systems, Projectors Technology: Wireless Connectivity, IP Networking, Cloud-Based Solutions, Hybrid Systems End User: Corporates, Educational Institutions, Government Agencies, Co-Working Spaces Installation Type: On-Premise, Managed Services, DIY Installations, Subscription-Based Services |
| Companies Covered | Logitech, Crestron Electronics, Cisco Systems, Yealink, Google, Microsoft, Poly, Barco, Zoom Video Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conference Room Solutions Market Emerging Trajectories
Intelligence migration from room hardware to cloud inference is redistributing value capture across the supply chain and reshaping buyer evaluation criteria toward software ecosystem depth.
Single-codec 4K video processing silicon with embedded neural network accelerators is rendering obsolete the discrete DSP-and-camera module architectures that dominated enterprise room kits through the previous decade. Mid-market IT departments in financial services and professional services verticals are standardizing on these consolidated system-on-chip platforms to reduce field failure rates and spare parts inventory. The consolidation compresses bill-of-materials costs while locking procurement into vendor-specific firmware update streams.
CE marking obligations under the EU Cybersecurity Act's expanded Radio Equipment Directive scope now mandate vulnerability disclosure timelines and secure boot requirements for all network-connected conference room devices sold in member states. Hardware vendors must embed hardware security modules and attestation capabilities that previously served only defense and classified government segments. German automotive and industrial conglomerates with pan-European facility footprints are driving compliance urgency through centralized procurement mandates that exclude non-certified suppliers from approved vendor lists.
Subscription-based room-as-a-service contracts are displacing capital purchase models for deployments below fifty seats, with facilities management providers bundling hardware, software licensing, and proactive monitoring into per-room monthly fees. Channel partners in the United Kingdom and Netherlands are building recurring revenue practices around this shift, hiring customer success functions unfamiliar to traditional AV integration firms. The model concentrates buyer relationships with distributor-owned service entities and erodes direct vendor access to end-user usage data and upgrade timing signals.
Conference Room Solutions Market Segmentation
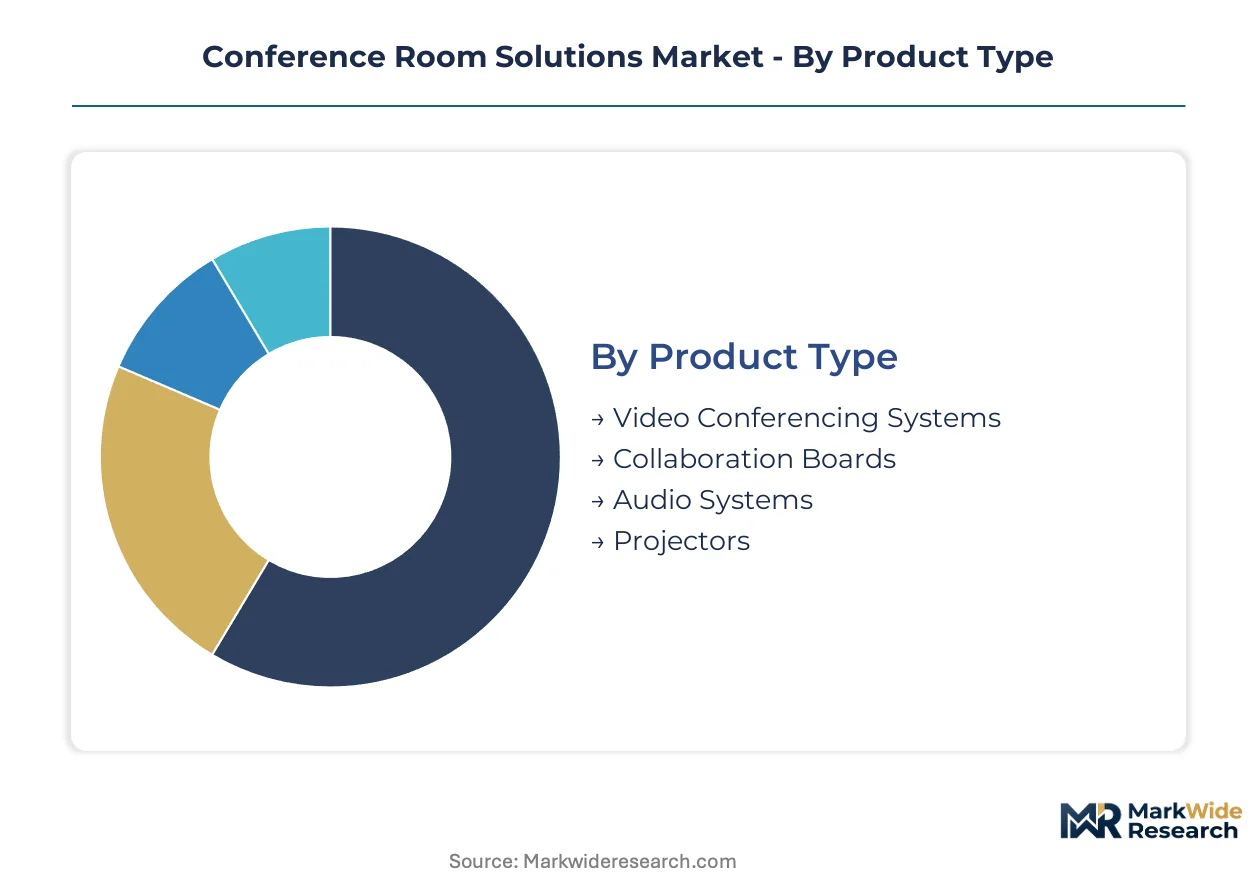
Conference room solutions fragment across four intersecting dimensions that shape procurement workflows and vendor positioning. Product type determines hardware capital allocation, while technology architecture dictates recurring cost structures and IT integration burden.
Product Type:
The use-case spectrum spans executive boardrooms requiring broadcast-grade fidelity to huddle rooms prioritizing rapid deployment.
- Video Conferencing Systems:Integrated camera-codec-display bundles supporting 4K resolution and sub-150ms latency dominate enterprise standardization programs. Fortune 500 IT departments in the United States prioritize these systems for hybrid workforce mandates, though semiconductor allocation constraints from TSMC and Samsung foundries extend lead times during refresh cycles.
- Audio Systems:Ceiling-mounted microphone arrays with embedded AI noise cancellation eliminate distributed table microphones, reducing cabling complexity by 60% in retrofit scenarios. German automotive conglomerates drive demand for acoustic processing that handles multi-language simultaneous interpretation in pan-European facilities.
- Collaboration Boards:Touch-enabled displays with embedded whiteboarding software serve creative and agile teams.
- Projectors:Laser-illuminated models persist in education and legacy government installations requiring large-format projection.
Established volume favors Video Conferencing Systems; emerging adoption favors Audio Systems as AI processing migrates to ceiling infrastructure.
Technology:
Cost tier stratification separates capital-intensive on-premise deployments from operational-expense cloud models.
- Cloud-Based Solutions:Browser-native meeting platforms with automatic firmware management reduce IT field support tickets by eliminating on-site server maintenance. Co-working operators in India favor these for zero-configuration room provisioning across multi-tenant facilities.
- Hybrid Systems:Split architectures retaining local media processing while leveraging cloud control planes address data residency requirements in European financial services. CE marking under expanded EU Cybersecurity Act mandates now requires secure boot attestation for these deployments.
- Wireless Connectivity:Wi-Fi 6E and proprietary millimeter-wave protocols enable cable-free laptop pairing.
- IP Networking:Standards-based SIP and H.323 interoperability ensures legacy system compatibility.
Hybrid Systems capture premium pricing in regulated verticals; Cloud-Based Solutions are expanding most quickly through subscription conversions.
End User:
Customer type determines feature depth, with corporates sustaining margin pools that subsidize volume segments.
- Corporates:Multi-national headquarters and regional offices drive integrated AV standardization across thousands of rooms, with procurement centralized through facilities management teams. FCC Part 15 certification requirements for US deployments and CSRD sustainability disclosure mandates in Europe filter vendor eligibility.
- Co-Working Spaces:WeWork India, Awfis, and comparable operators require turnkey systems deployable without dedicated AV technicians, favoring subscription-based room-as-a-service models over capital purchase.
- Educational Institutions:K-12 and university buyers prioritize durability and theft resistance over feature sophistication.
- Government Agencies:Classified and unclassified installations maintain divergent certification paths, with defense segments requiring hardware security modules.
Corporates dominate absolute revenue; Co-Working Spaces generate the steepest expansion trajectory through facility scaling.
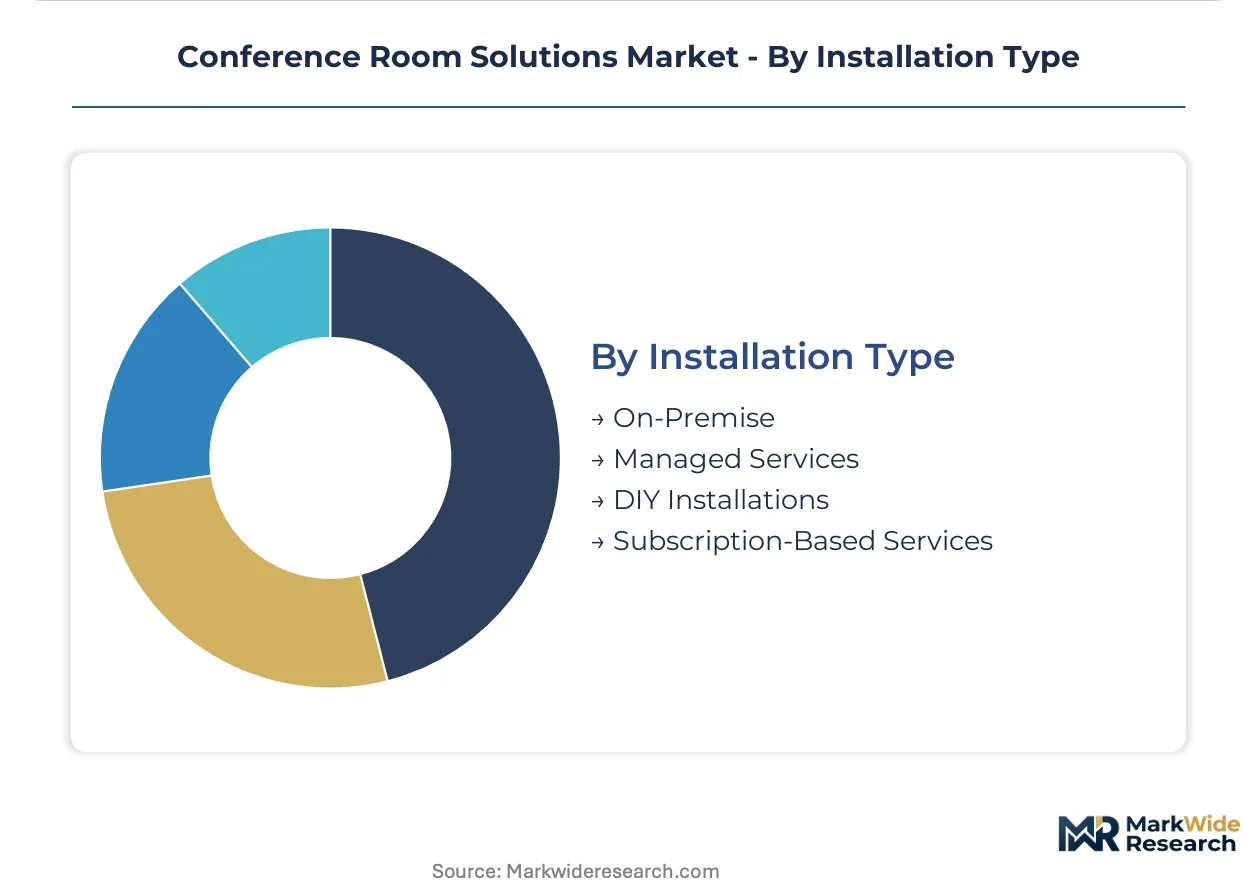
Installation Type:
Margin structure inverts across deployment models, with services capturing value that hardware commoditization erodes.
- Managed Services:Channel partners in the United Kingdom and Netherlands bundle proactive monitoring, firmware management, and break-fix response into per-room monthly fees, building recurring revenue practices that displace traditional integration margins. German automotive conglomerates with pan-European footprints favor this model to standardize support quality.
- Subscription-Based Services:Hardware, software licensing, and cloud infrastructure collapse into single operational expenditure line items, accelerating procurement approval cycles for mid-market buyers.
- On-Premise:Capital purchase with internal IT ownership persists in security-sensitive and remote locations with unreliable connectivity.
- DIY Installations:Self-configured USB peripherals address cost-constrained small business and home office segments.
Managed Services consolidate buyer relationships with distributor-owned entities; Subscription-Based Services gain share fastest through procurement simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Video codec silicon fabrication concentrates among Taiwan and South Korean foundries, creating geographic chokepoints that ripple through enterprise procurement timelines. Corporate facility managers in specific national markets navigate distinct regulatory and infrastructure constraints as they scale hybrid workplace investments.
United States
Fortune 500 headquarters in New York and Chicago drive integrated AV standardization across thousands of meeting spaces. FCC Part 15 equipment authorization requirements govern wireless peripheral certification timelines. Austin and Seattle tech corridors anchor cloud-native room platform development, with enterprise IT departments prioritizing browser-native deployments.
Germany
Automotive and industrial conglomerates in Stuttgart and Munich mandate pan-European facility standardization with data residency controls. CE marking under the EU Radio Equipment Directive now requires expanded cybersecurity documentation. Frankfurt financial services clusters favor hybrid architectures splitting local media processing from cloud control planes.
Japan
Government and education buyers in Tokyo and Osaka retain substantial legacy analog infrastructure, forcing continued VGA and 3.5mm audio port support. METI industrial standards shape procurement specifications for multinational headquarters. Nagoya manufacturing hubs generate demand for acoustic processing handling multi-language simultaneous interpretation.
India
WeWork India and Awfis scale multi-tenant facilities in Bangalore and Mumbai faster than dedicated AV staffing permits. TRAI telecommunications regulations influence connectivity requirements for cloud-based room deployments. Hyderabad tech campuses drive demand for turnkey systems with zero-configuration provisioning.
United Kingdom
Channel partners in London and Manchester build recurring revenue practices around room-as-a-service contracts displacing capital purchase models. CSRD sustainability disclosure mandates push procurement teams toward ISO 14001-certified hardware vendors. Cambridge technology clusters experiment with AI-whiteboard convergence for executive briefing installations.
Conference Room Solutions Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in peripheral and silicon layers. The vendor base stratifies into three tiers: cloud-native platform operators with recurring revenue models, integrated hardware-software vendors with dealer-exclusive distribution, and commodity peripheral manufacturers competing on supply chain scale. Two dominant competitive moves define current positioning: subscription-based service bundling that collapses hardware and software into operational expenditure line items, and acoustic AI processing migration from table devices to ceiling infrastructure that reshapes installation economics.
Within the integrated systems tier, Crestron Electronics and Cisco Systems exemplify divergent go-to-market architectures—one anchored in dealer-exclusive high-end installations, the other in cloud infrastructure tie-ins. Logitech occupies a position representing supply chain scale dominance in peripheral categories across enterprise channels. These three entities collectively illustrate how vendor positioning fragments across platform depth, distribution control, and component cost structures.
| Leading Market Players |
|---|
| Logitech |
| Crestron Electronics |
| Cisco Systems |
| Yealink |
| Microsoft |
| Poly |
| Barco |
| Zoom Video Communications |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors connecting Taiwan and South Korean foundries to North American distribution hubs transmit cost volatility directly into hardware pricing tiers, with semiconductor allocation constraints amplifying premium tier premiums while compressing mid-market margins through forced component substitution.
Pricing Analysis
FCC Part 15 equipment authorization requirements dictate the pricing tier structure across the United States market, with certified wireless peripherals commanding premium positioning over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates integrated system bundles from peripheral-only kits and DIY USB devices. Cost compression in the mid-tier is intensifying because magnet material price swings tied to Chinese export quotas squeeze speaker driver margins. Co-working operators in India exhibit the highest price sensitivity, while German automotive conglomerates with pan-European standardization mandates show the least.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit foundry capacity expansion in Taiwan and South Korea, constraining video codec silicon availability for enterprise room systems. Fabrication concentrates among TSMC and Samsung facilities, drawing from copper and rare earth inputs for HDMI assemblies and speaker magnets. Single-source vulnerability in Taiwan Strait logistics creates disruption exposure for North American enterprise refresh cycles. Distribution runs through dealer-exclusive networks for integrated systems and direct enterprise channels for cloud-native platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conference room solutions represent a substantial service-attach opportunity, with subscription-based room-as-a-service contracts expanding faster than capital hardware sales as facilities management providers consolidate buyer relationships.
For Market Incumbents: Build certification moats around CE marking under expanded EU Cybersecurity Act mandates and ISO 27001 information security frameworks to exclude non-compliant challengers from approved vendor lists at German automotive conglomerates. Deepen backward integration into acoustic AI processing silicon to capture value migrating from table devices to ceiling infrastructure. Channel control through distributor-owned service entities locks out direct vendor access to upgrade timing signals. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with facility managers lacking dedicated AV staffing and accepting zero-configuration cloud-native deployments. Turnkey room-as-a-service models bypass capital approval cycles that favor established vendors in corporate headquarters. Partner with co-working operators scaling faster than technical hiring permits. For Investors and Strategic Acquirers: Cloud-native platform specialists with recurring revenue concentration above sixty percent of total sales offer the strongest long-term viability framing across the analysis window. Acoustic AI processing capabilities embedded in ceiling microphone arrays signal defensible differentiation as machine learning noise cancellation becomes table stakes. Watch for inflection when hybrid system vendors achieve secure boot attestation compliance ahead of CE marking deadline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Browser-native Webex and Teams tie-ins consolidate procurement at Fortune 500 IT departments. |
| Acquisition of Specialist Firm | Ceiling microphone array specialists add acoustic AI capabilities without internal R&D timelines. |
| Geographic Expansion | India co-working penetration accelerates through WeWork India and Awfis facility scaling. |
| Product Launch | Single-codec 4K system-on-chip platforms reduce field failure rates for financial services buyers. |
| Strategic Partnership | Channel partners in the United Kingdom build recurring revenue practices around room-as-a-service contracts. |
Methodological Framework
Initial hypotheses were tested against primary input from enterprise IT directors, AV integration specialists, facilities management procurement leads, and semiconductor supply planners and refined through secondary validation against FCC equipment authorization databases, CE marking notification files, hyperscaler capex disclosures, and customs trade records. Bottom-up room deployment estimates triangulated against top-down enterprise technology spending benchmarks.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling product type splits across video conferencing systems, audio systems, collaboration boards, and projectors alongside technology architecture dimensions spanning cloud-based, hybrid, wireless connectivity, and IP networking deployments. CAGRs were derived from installed base refresh cycle analysis and IT standardization mandate tracking, with semiconductor allocation constraints and co-working facility expansion rates serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in corporate real estate budgets and enterprise capital expenditure cycles would shift the trajectory of hardware refresh timing and subscription conversion rates. Cross-checking against hyperscaler collaboration platform user growth metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Construction Design App Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Email Marketing Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Graph Technology Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Singapore System Integration Market