
 Lit Fiber Market | 2026-2036
Lit Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Lit Fiber Market Intelligence
Hyperscale data center operators is collapsing as the dominant buyer archetype in lit fiber procurement, displacing traditional telecom-led demand patterns. Verizon sustains one of the largest intercity fiber footprints through aggressive metropolitan route densification. Crown Castle Fiber specializes in last-mile lit connectivity for wireless backhaul and enterprise edge applications. AT&T dominates long-haul routes with deep spectrum coordination across its fiber-wireless convergence strategy.
Lit fiber denotes optically active telecommunications infrastructure where the service provider owns, lights, and manages the transmission equipment across deployed fiber strands, typically operating at wavelengths between 1260 nm and 1625 nm with active DWDM or CWDM multiplexing systems. Its primary commercial purpose is delivering managed bandwidth services without transferring physical fiber ownership to the customer. Single-mode fiber commands the largest revenue pool given its dominance in long-haul and metro applications requiring minimal signal attenuation. Multi-mode fiber occupies a narrowing niche within enterprise campus and data center interconnects below 500 meters. Enterprise Networks represents the fastest-growing application segment as distributed work architectures force organizations to outsource private wavelength management.
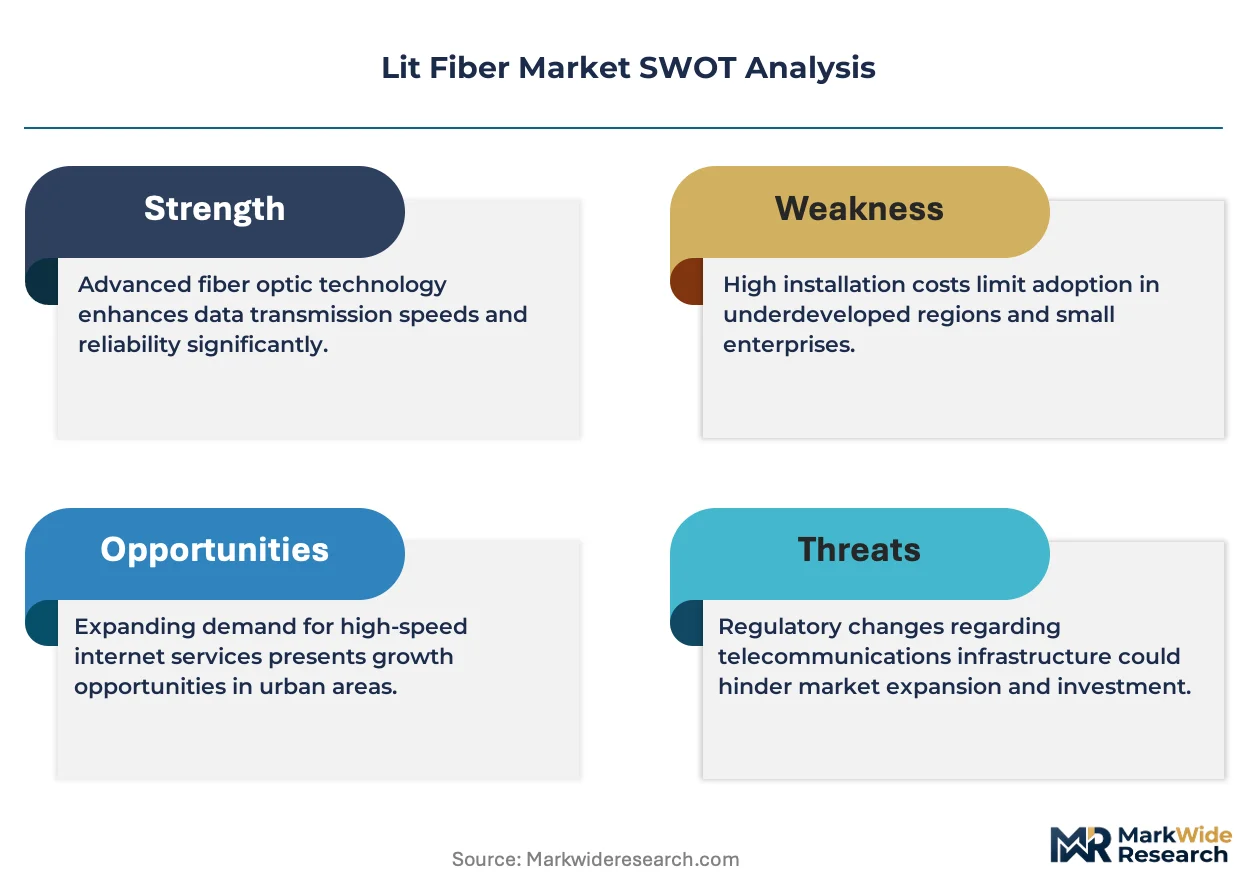
The FCC enforces network reliability standards through its outage reporting frameworks, while OSHA governs aerial and underground installation safety protocols that directly shape contractor deployment costs and timeline compliance. State-level public utility commissions layer additional open-access requirements that condition market entry for non-incumbent providers. Stakeholders must weigh the trade-off between capital-intensive dark fiber ownership and operational flexibility as carrier pricing models evolve toward consumption-based wavelength contracts.
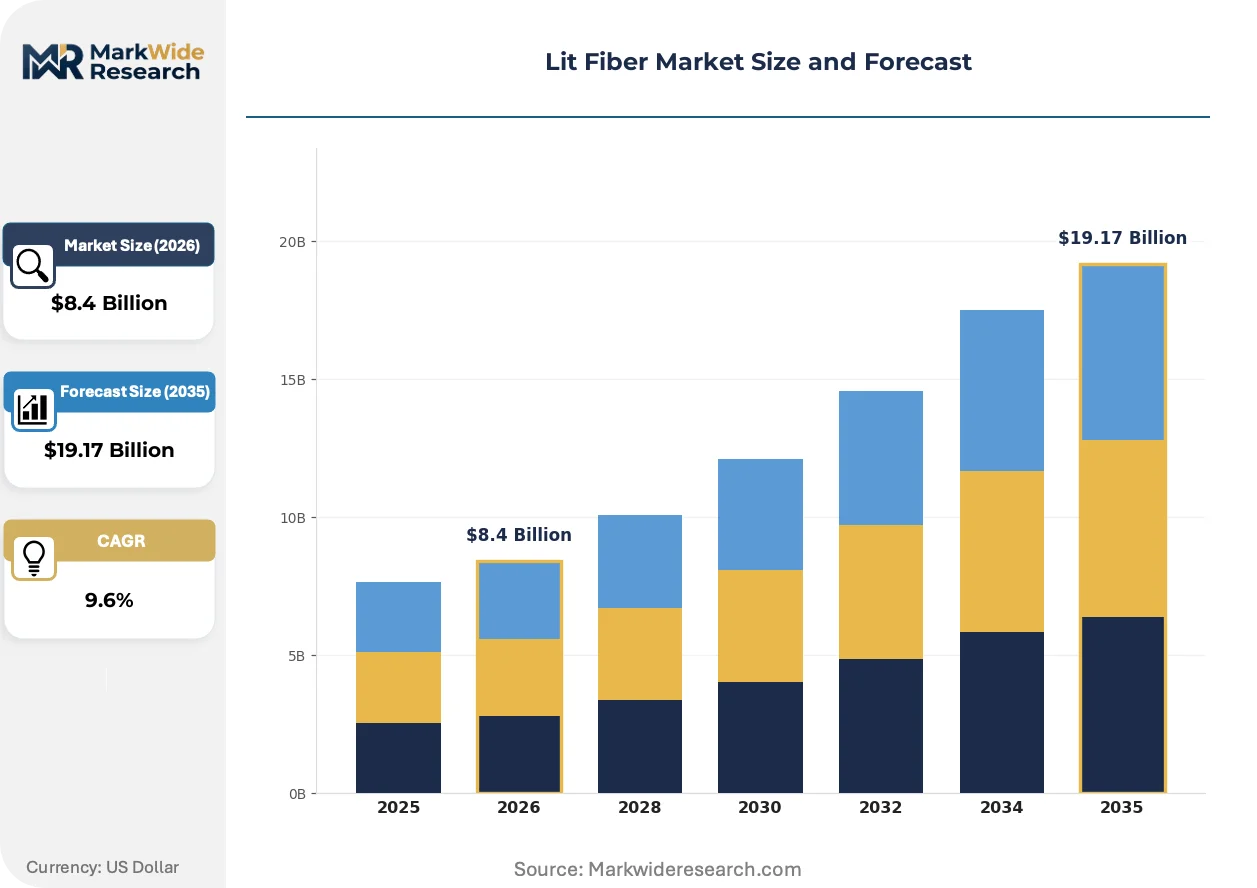
Market Dynamics
Hyperscale data center clustering along the Texas-California-Virginia corridor is compressing provisioning timelines and forcing carrier procurement toward managed wavelength services over dark fiber builds.
Growth Catalysts
- BEAD Program Allocations:The FCC's infrastructure subsidy frameworks are accelerating carrier deployment priorities across underserved metropolitan rings, redirecting capital toward lit fiber overbuilds.
- Cloud Service Provider Demand:Enterprise procurement from hyperscale operators is collapsing toward lit solutions as internal wavelength management capabilities mature.
- DWDM System Advances:Dense wavelength division multiplexing equipment cost curves are flattening, enabling 400G and 800G service tiers at price points competitive with dark fiber leases.
Market Restraints
- Right-of-Way Access Costs:Municipal permitting timelines and pole attachment fees in dense urban cores inflate deployment economics beyond rural fiber builds.
- Optical Equipment Supply Concentration:DWDM transponder and ROADM manufacturing concentrates among a limited supplier base, creating procurement bottlenecks during capacity expansion cycles.
- Skilled Technician Scarcity:Fusion splicing and optical testing expertise pools inadequately against deployment velocity requirements, extending commissioning windows.
Strategic Opportunities
- Edge Computing Interconnects:Distributed AI inference clusters are creating demand for low-latency lit fiber rings connecting secondary metros to primary data center hubs.
- Wireless Backhaul Modernization:5G mid-band densification is forcing mobile network operators to upgrade from copper T1 circuits to fiber-based Ethernet backhaul.
- Submarine Cable Landing Extensions:New transatlantic and transpacific cable landings on the US East and West Coasts require terrestrial lit fiber extensions to inland data center markets.
Industry Challenges
- Legacy SONET/TDM Migration:Incumbent carriers face stranded asset complexity as enterprise customers demand packet-optical service handoffs incompatible with existing circuit-switched infrastructure.
- Intercarrier Provisioning Coordination:Multi-carrier end-to-end wavelength services require seamless OSS/BSS integration across competitive networks, creating service activation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lit Fiber Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fiber, Multi-Mode Fiber, Armored Fiber, Loose Tube Fiber Application: Telecommunications, Data Centers, Enterprise Networks, Residential Installation Type: Indoor, Outdoor, Aerial, Direct Burial End User: Telecom Operators, Enterprise Businesses, Government Agencies, Educational Institutions |
| Companies Covered | AT&T, Verizon, Comcast, Lumen Technologies, Crown Castle Fiber, Frontier Communications, Zayo Group, Altice USA, Spectrum Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lit Fiber Market Strategic Shifts & Innovations
Open optical networking principles are dismantling proprietary vendor lock-in across transport layers, enabling disaggregated procurement of transponders, amplifiers, and line systems from separate suppliers.
Coherent pluggable optics operating at 400G ZR and 800G ZR standards is decomposing traditional chassis-based DWDM terminal architectures. Cloud operators and large enterprises are adopting these pluggable interfaces for data center interconnects below 120 kilometers. This shift is compressing equipment vendor margins and accelerating refresh cycles from seven-year to three-year intervals.
The FCC's outage reporting frameworks are tightening reliability disclosure requirements for facilities-based carriers. Facilities must now report service disruptions affecting 900,000 or more user-minutes within specified timeframes. Long-haul route operators face the steepest compliance burden as single fiber cuts can trigger multi-state reporting obligations.
Consumption-based wavelength contracts are displacing fixed-term IRU and lease structures in enterprise procurement. Buyers now prefer monthly recurring charges tied to actual bandwidth utilization rather than stranded capacity payments. This pattern concentrates among financial services and media verticals with volatile traffic patterns.
Lit Fiber Market Segmentation
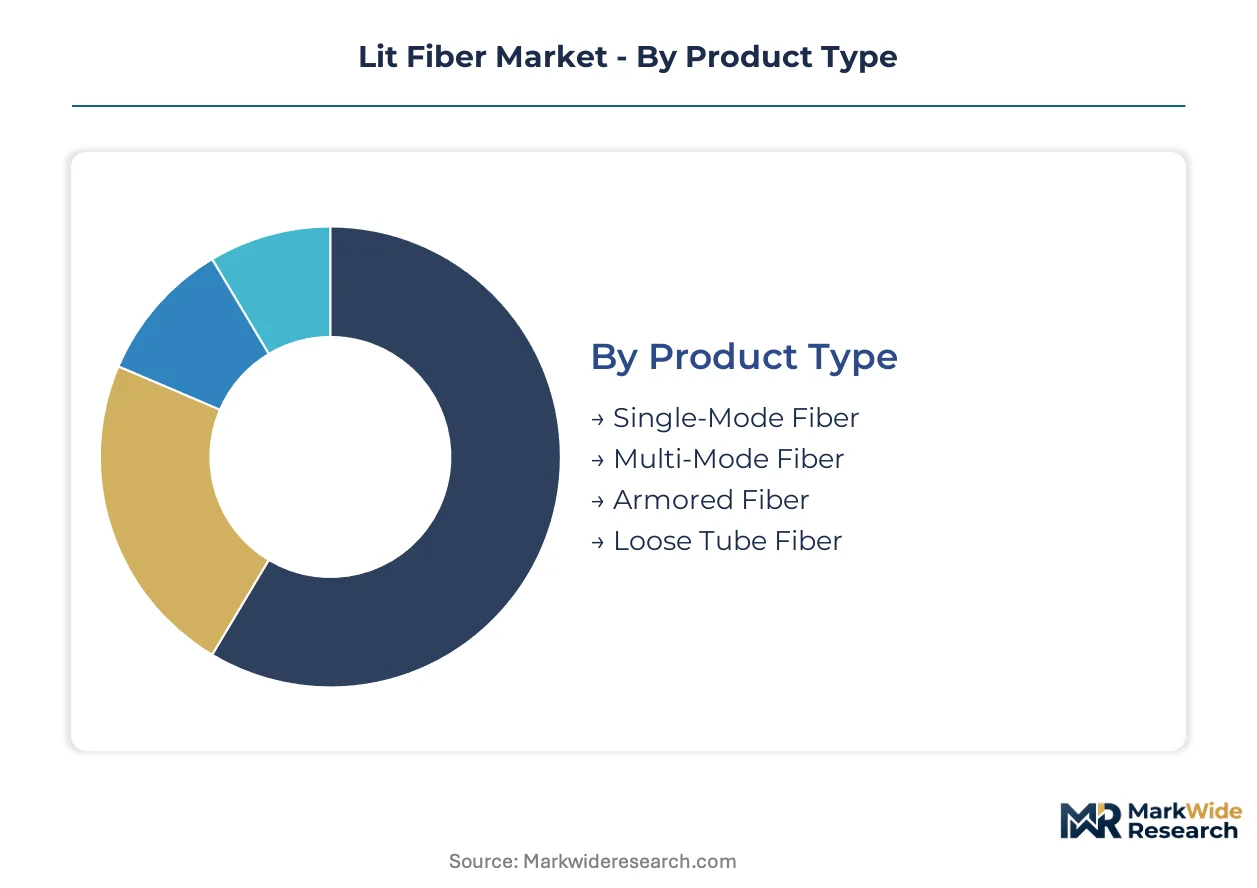
Lit fiber procurement patterns diverge sharply across technical specifications, deployment contexts, and buyer archetypes. Understanding these segment boundaries clarifies where carrier pricing power concentrates versus where competitive intensity erodes margins.
Product Type:
Domestic deployment economics favor single-mode and armored variants, while loose tube fiber concentrates in export-driven submarine cable and international long-haul projects.
- Single-Mode Fiber:Engineered for minimal signal attenuation across 1260-1625 nm wavelengths, enabling 100G+ coherent transmission over hundreds of kilometers. Demand clusters in Texas, California, and Virginia data center corridors where hyperscale operators lease managed wavelengths rather than provision dark fiber. Fiber scarcity in these markets compresses provisioning timelines and elevates pricing leverage for carriers with installed single-mode plant.
- Multi-Mode Fiber:Optimized for shorter-reach applications below 500 meters using 850 nm and 1300 nm transmission windows. Enterprise campus interconnects and intra-data center links drive procurement, though coherent pluggable optics are encroaching on traditional multi-mode strongholds. Cost-sensitive buyers in secondary metros favor this grade for edge computing deployments.
- Armored Fiber:Steel or aluminum protective layers defend against rodent damage, crushing, and moisture ingress in direct burial and industrial environments. Utility and railroad right-of-way deployments specify this grade exclusively.
- Loose Tube Fiber:Gel-filled buffer tubes isolate strands from thermal expansion and mechanical stress in outdoor aerial and duct installations. Submarine cable landing extensions and rural overbuilds represent primary demand nodes.
Single-mode fiber commands the established base. The steepest expansion runs through armored fiber as infrastructure hardening requirements intensify.
Application:
Cost tier segmentation separates capital-intensive data center interconnects from operational expenditure-driven enterprise network outsourcing.
- Telecommunications:Incumbent carriers deploy lit fiber to replace aging SONET/TDM infrastructure with packet-optical handoffs. Intercarrier wavelength coordination challenges and OSS/BSS integration friction constrain service activation velocity.
- Data Centers:Hyperscale operators in Northern Virginia, Dallas-Fort Worth, and Silicon Valley procure 400G and 800G wavelength services as internal optical engineering capabilities mature. DWDM equipment cost flattening enables competitive pricing against dark fiber alternatives.
- Enterprise Networks:Financial services and media verticals with volatile traffic patterns are adopting consumption-based wavelength contracts. Distributed work architectures force organizations to outsource private wavelength management rather than maintain in-house optical expertise.
- Residential:BEAD program subsidies redirect carrier capital toward lit fiber overbuilds in underserved metropolitan rings. Municipal permitting timelines and pole attachment fees inflate deployment economics relative to rural builds.
Telecommunications retains the revenue base. Enterprise networks are climbing the fastest as procurement patterns shift from fixed-term IRU structures to utilization-based recurring charges.
Installation Type:
Volume concentration tracks right-of-way access economics, with aerial and direct burial commanding scale advantages over indoor premium deployments.
- Indoor:Plenum-rated and riser-rated cables serve enterprise buildings, data center meet-me rooms, and central office interconnection points. Fire safety codes and OSHA installation protocols shape contractor deployment costs.
- Outdoor:Underground duct and conduit installations dominate metro fiber rings. State-level public utility commissions layer open-access requirements that condition market entry for non-incumbent providers.
- Aerial:Pole-mounted deployments accelerate provisioning in suburban and exurban corridors where underground construction costs prove prohibitive. Electric utility joint-use agreements create negotiation friction.
- Direct Burial:Armored cables placed without conduit dominate rural and long-haul routes. Fusion splicing and optical testing expertise scarcity extends commissioning windows for this labor-intensive installation mode.
Outdoor installations anchor carrier infrastructure. Aerial methods are gaining share fastest where permitting velocity determines competitive positioning.
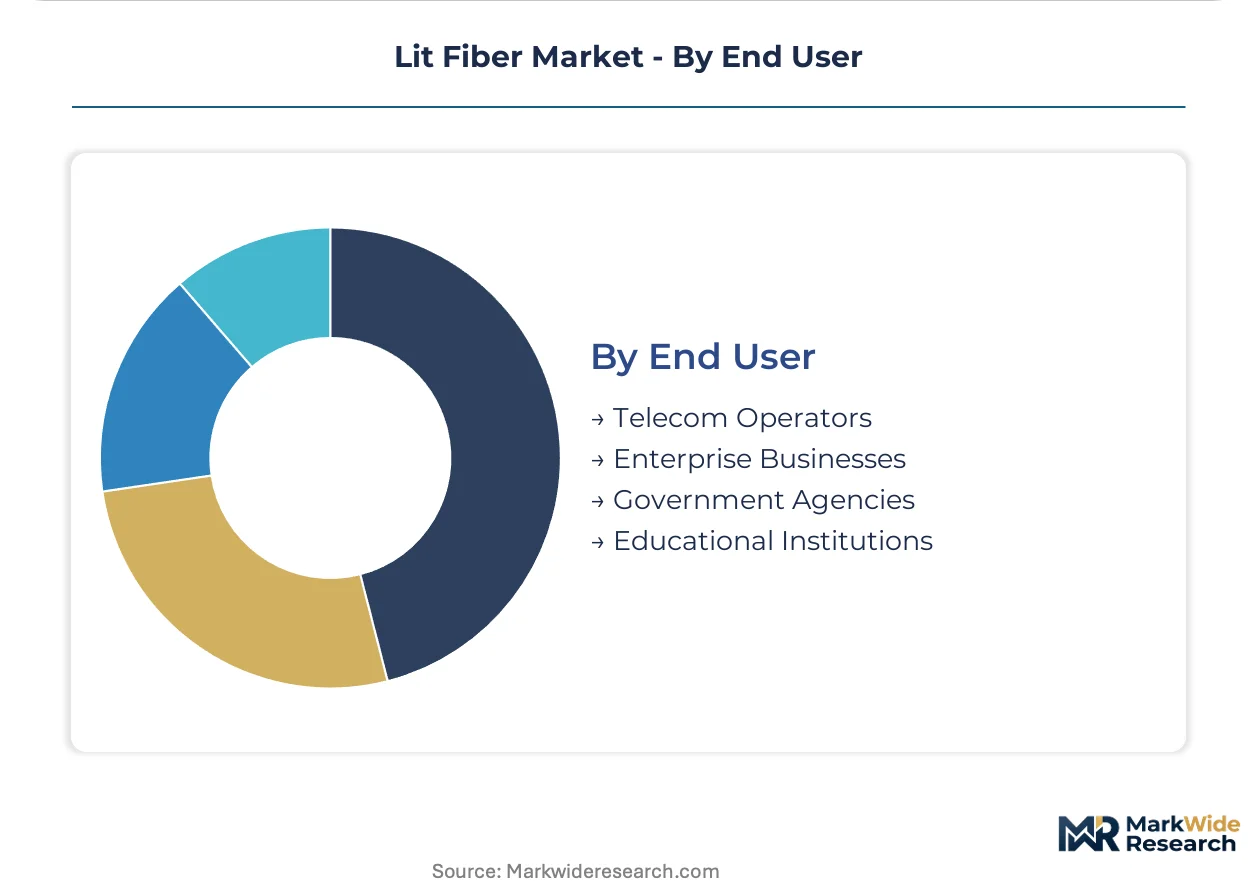
End User:
Customer type segmentation reveals procurement sophistication gradients, with government and educational buyers prioritizing reliability disclosure over bandwidth economics.
- Telecom Operators:Facilities-based carriers face FCC outage reporting obligations for disruptions affecting 900,000+ user-minutes. Long-haul route operators bear the steepest compliance burden as single fiber cuts trigger multi-state reporting.
- Enterprise Businesses:Cloud service providers and Fortune 500 firms negotiate consumption-based wavelength contracts with monthly recurring charges tied to actual utilization. Procurement teams favor operational flexibility over stranded capacity risk.
- Government Agencies:Federal and state entities mandate diverse routing and physical path redundancy. Reliability disclosure requirements outweigh price sensitivity in RFP evaluation criteria.
- Educational Institutions:Research universities and K-12 districts access lit fiber through E-Rate program subsidies. Bandwidth demand from distributed learning platforms and research data transfers strains legacy copper infrastructure.
Telecom operators dominate transaction volume. Enterprise businesses are expanding most quickly as hyperscale procurement patterns reshape competitive dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier-grade fiber deployment concentrates disproportionately in markets where data center clustering intersects with permissive infrastructure policy. Regulatory subsidy programs and municipal permitting velocity determine competitive positioning across metropolitan rings.
United States
Hyperscale operators in Northern Virginia, Dallas-Fort Worth, and Silicon Valley drive wavelength procurement at 400G and 800G tiers. The FCC's BEAD program redirects carrier capital toward lit fiber overbuilds in underserved metropolitan rings. Texas, California, and Virginia corridor markets suffer persistent fiber scarcity as data center clustering compresses provisioning timelines.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg demand low-latency lit fiber for smart manufacturing backhaul. The Bundesnetzagentur enforces open-access requirements on federally subsidized fiber deployments. Frankfurt's position as a financial services hub concentrates enterprise wavelength demand for trading infrastructure.
United Kingdom
London's status as a submarine cable landing point drives terrestrial lit fiber extensions to Slough and Docklands data center campuses. Ofcom's wholesale fiber access remedies condition market entry for alternative network providers. The M4 corridor and Manchester media hub represent secondary demand nodes for broadcast and content delivery networks.
Japan
Tokyo-Osaka metropolitan corridors sustain dense wavelength division multiplexing deployments for financial services and cloud interconnects. METI's digital infrastructure targets accelerate fiber-to-the-premises overbuilds in secondary cities. The Kanto region's concentration of hyperscale facilities creates persistent demand for managed optical services.
Singapore
Submarine cable landings at Changi and Tuas anchor terrestrial lit fiber extensions to data center campuses in the western industrial zone. The Infocomm Media Development Authority mandates network resilience standards for critical infrastructure operators. Marina Bay and Jurong Lake Districts concentrate financial services and enterprise cloud demand respectively.
Lit Fiber Market Key Industry Players
Concentration sits with facilities-based carriers possessing deep metropolitan route densification and intercity fiber footprints. The market structure divides between incumbent telecom operators with legacy SONET infrastructure and fiber-first specialists emphasizing packet-optical service delivery. Two archetypes dominate: scale-driven national carriers leveraging spectrum coordination across fiber-wireless convergence strategies, and metro-focused specialists targeting last-mile connectivity for wireless backhaul and enterprise edge applications. Competitive moves center on metropolitan route densification through organic buildouts and strategic fiber swaps with electric utilities.
Within the incumbent carrier tier, AT&T and Verizon exemplify scale-driven national positioning through extensive long-haul route ownership. Crown Castle Fiber occupies a distinct position as a metro-focused specialist emphasizing last-mile lit connectivity. These three anchors represent divergent strategic postures: wavelength-heavy infrastructure ownership versus agile metropolitan service delivery.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| Comcast |
| Lumen Technologies |
| Crown Castle Fiber |
| Frontier Communications |
| Zayo Group |
| Altice USA |
| Spectrum Enterprise |
| Others |
Cost & Logistics Intelligence
Ninety-to-one-hundred-day DWDM transponder lead times compress carrier procurement flexibility and concentrate pricing leverage among vertically integrated equipment vendors. This inventory tightness intersects with fiber scarcity in Texas-California-Virginia corridors to amplify wavelength service premiums.
Pricing Analysis
FCC outage reporting frameworks dictate the pricing tier structure across lit fiber services. Three-tier pricing structure across premium, standard, and economy levels separates managed wavelength SLAs with sub-50ms protection switching from best-effort transport and wholesale dark fiber alternatives. Price differentiation rests on route diversity certification and DWDM equipment generation. Cost compression in standard-tier metro rings is intensifying because coherent pluggable optics are collapsing chassis-based system premiums. Hyperscale cloud operators exhibit lowest price sensitivity due to internal optical engineering capabilities, while educational institutions accessing E-Rate subsidies face strict budget caps.
Supply Chain Analysis
Extended ROADM component lead times expose carrier deployment schedules to procurement volatility. Manufacturing concentrates in Japan, South Korea, and the United States for coherent DSPs, optical amplifiers, and wavelength-selective switches. Raw material dependencies span rare-earth doped fibers, indium phosphide substrates, and precision optical coatings. Single-source vulnerability concentrates in 400G ZR transponder supply. Distribution runs through direct OEM contracts with tier-one carriers and value-added resellers serving regional enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale data center operators as their procurement volume consolidates across fewer cloud platforms. This concentration forces carriers toward consumption-based contracts and away from fixed-term IRU structures.
For Market Incumbents: Consolidate metropolitan route density through strategic fiber swaps with electric utilities to defend against fiber-first specialists encroaching on last-mile connectivity. Deepen vertical integration into coherent pluggable optics manufacturing to capture equipment margin compression. Priority lever: OSS/BSS integration investments that accelerate intercarrier wavelength provisioning velocity.
For New Entrants and Emerging Players: Anchor in secondary metro edge computing interconnects where latency requirements for distributed AI inference clusters outpace incumbent carrier response times. Target wireless backhaul modernization in 5G mid-band densification corridors. Go-to-market angle: consumption-based wavelength contracts with monthly utilization reconciliation for financial services verticals.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because fiber scarcity in data center corridors creates durable pricing power for route-dense assets. Acquisition target archetype: metro-focused specialists with electric utility joint-use agreements and packet-optical service capabilities. Signal to watch: BEAD program subsidy disbursement velocity as indicator of competitive overbuild intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Metropolitan Route Densification | Fiber swaps with utilities in Northern Virginia and Dallas-Fort Worth lock in data center corridor access. |
| Packet-Optical Infrastructure Migration | SONET/TDM replacement programs align carrier assets with hyperscale wavelength service demands. |
| Coherent Pluggable Optics Integration | 400G ZR and 800G ZR adoption collapses traditional chassis-based DWDM terminal economics. |
| Consumption-Based Contract Structuring | Monthly recurring charges tied to actual bandwidth utilization attract financial services procurement teams. |
| BEAD Program Capital Deployment | FCC subsidy frameworks redirect carrier investment toward underserved metropolitan ring overbuilds. |
Research Approach
A standing panel of network engineering executives, carrier procurement directors, data center interconnection managers, and optical equipment vendor sales engineers provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FCC infrastructure subsidy filings, SEC carrier 10-K disclosures, submarine cable landing permits, and hyperscaler capex announcements. Bottom-up wavelength service demand modeling and top-down carrier revenue triangulation anchored the analytical framework.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The forecast framework modeled segmentation dimensions including fiber type, installation mode, application vertical, and buyer archetype. CAGRs derived from carrier revenue trajectory analysis and equipment shipment correlations. Industry-specific inputs incorporated DWDM system cost curves, right-of-way permitting velocity, and hyperscale data center clustering patterns.
Material uncertainties — municipal permitting delays, optical component supply disruptions, and subsidy program allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions about carrier deployment priorities and enterprise procurement pattern stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
MENA Wireless Routers Market
Network Technology
Hyperconnectivity Market
Network Technology
Network Equipment Market
Network Technology
Sand Lane Systems Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Europe SD-WAN Market
Network Technology
Global Routing Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Mobile Accelerator Market
Network Technology
5G CPE Device Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Open RAN Market
Network Technology
Global Optical Transport Network (OTN) Market